
 Trash Rakes Market | 2026-2036
Trash Rakes Market Size, Share, and Industry Trends Forecast 2026-2036
Trash Rakes Market Analytics
REACH compliance is rebalancing material specifications for trash rake manufacturers serving European water utilities. WesTech Engineering leverages its North American manufacturing footprint to compete on delivery timelines for large municipal contracts. Andritz AG anchors its position through in-house production of stainless steel screening components. Huber Technology differentiates via specialized rake geometries optimized for high-debris river intakes.
Trash rakes are mechanical screening devices installed at water intake structures, composed of steel or polymer bars spaced to intercept floating debris while permitting water flow; they protect pumps, turbines, and treatment equipment from damage. Automated rakes dominate capital expenditure allocations due to labor cost pressures and continuous operation requirements at remote facilities. Mechanical rakes retain substantial installed base replacement demand across legacy European treatment plants. Municipal end users concentrate procurement volume through framework agreements spanning multi-year maintenance obligations.
The EPA enforces Clean Water Act debris removal standards at US municipal intakes, while the EU Urban Wastewater Treatment Directive mandates pretreatment screening upgrades across member states. Germany's KBA and France's ANSM do not regulate this equipment directly, but national water agency procurement rules embed CE marking and ISO 9001 certification as baseline qualifications. Stakeholders must monitor how stricter debris classification standards in the EU Green Deal implementation reshape product testing protocols and supplier qualification timelines.
Market Dynamics
Automated screening technology is compressing replacement cycles at European water utilities, forcing manufacturers to reconfigure service architectures around predictive maintenance rather than equipment sales.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Pretreatment screening mandates across member states are accelerating infrastructure retrofit timelines at municipal facilities.
- Stainless steel component standardization:REACH-compliant material specifications are expanding addressable market for certified European suppliers.
- Rhine-Ruhr corridor:Overlapping aging infrastructure replacement cycles and effluent mandates are concentrating procurement volume in Germany's densest utility network.
Market Restraints
- Specialized alloy supply concentration:Duplex stainless steel sourcing remains concentrated among Nordic and German metallurgical suppliers.
- CE marking certification friction:Extended conformity assessment timelines for automated rakes are delaying project commissioning.
- Mechanical rake installed base:Legacy equipment longevity is compressing near-term replacement demand at budget-constrained utilities.
Strategic Opportunities
- High-debris river intake specialization:Customized rake geometries for alpine and flood-prone waterways represent underserved specification tiers.
- Remote facility automation:Unattended operation requirements at isolated pumping stations are expanding addressable market for fully automated systems.
- EU Green Deal implementation:Stricter debris classification standards are creating qualification barriers that favor early-certifying suppliers.
Industry Challenges
- Mechatronics integration complexity:Utilities struggle to retrofit automated rakes onto concrete intake structures designed for manual operation.
- ISO 9001 audit preparation:National water agency procurement rules embed quality management certification as baseline, extending vendor onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trash Rakes Market |
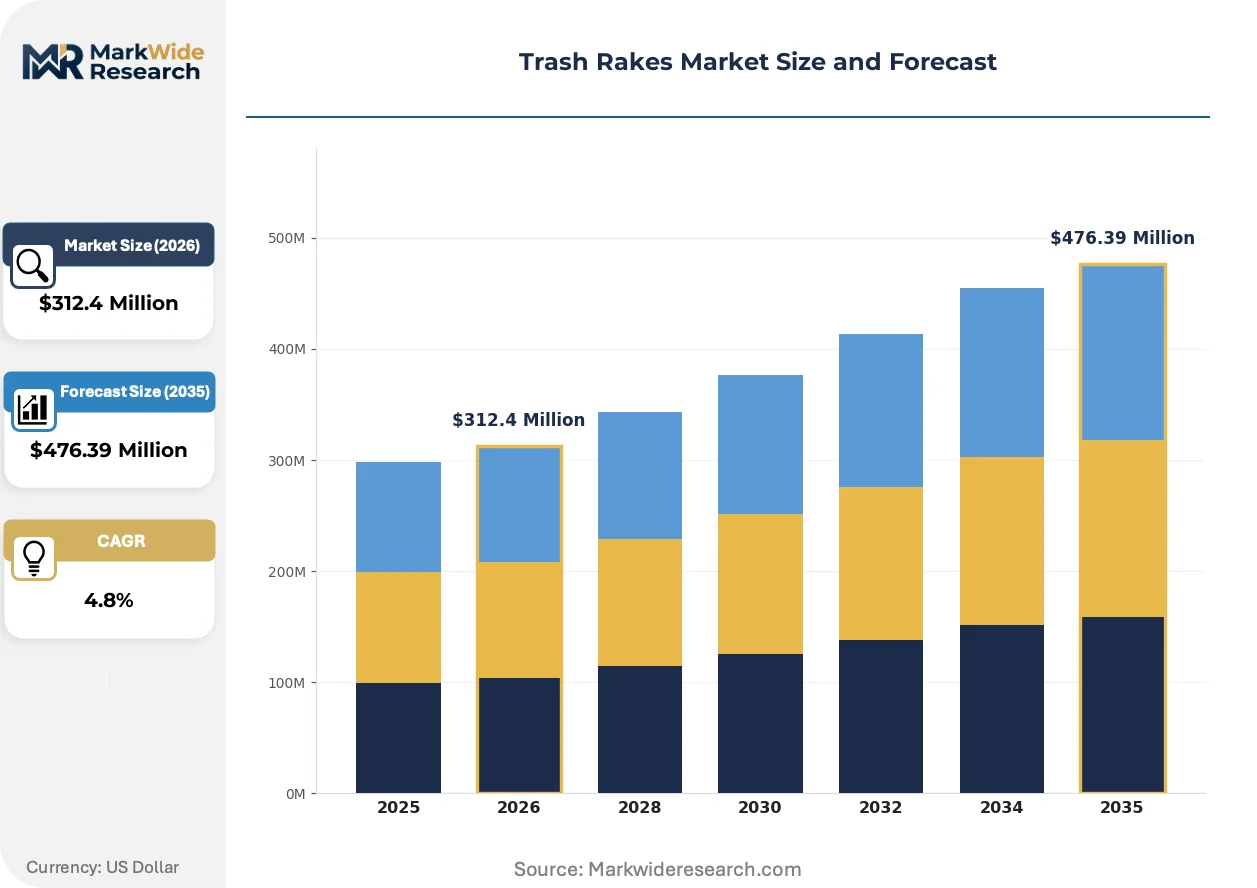
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Rakes, Mechanical Rakes, Hydraulic Rakes, Automated Rakes End User: Municipalities, Waste Management Companies, Environmental Agencies, Construction Sites Application: Park Maintenance, Beach Cleaning, River Cleaning, Waste Removal Deployment: Onshore, Offshore, Urban Areas, Rural Areas |
| Companies Covered | WesTech Engineering, Pentair, Ovivo, Aqseptence Group, BDP Industries, Parkson Corporation, Veolia Water Technologies, Andritz AG, Huber Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trash Rakes Market Evolving Landscape
Screening equipment architecture is fragmenting into configurable subsystems, enabling utilities to match capital deployment to debris load profiles rather than overspecifying for peak conditions.
Polymer-composite bar screen systems are modularizing field installation and reducing foundation requirements at retrofit sites. German municipal operators are piloting these configurations at Rhine tributary intakes. The technology is modularizing supplier relationships, allowing utilities to source bars, drives, and control systems from different vendors.
REACH substance restriction schedules are forcing reformulation of anti-corrosion coatings on steel screening components. Coating suppliers are accelerating qualification of chromium-free alternatives for water-contact applications. Municipal procurement departments in France and Germany are embedding material compliance verification into technical specification templates.
Framework agreements with multi-year maintenance obligations are displacing transactional equipment purchasing at large water utilities. German municipal associations are consolidating procurement through regional purchasing cooperatives. This concentration is visible across the Rhine-Ruhr metropolitan corridor, where aggregated demand is shifting bargaining power toward buyer consortiums.
Trash Rakes Market Segmentation
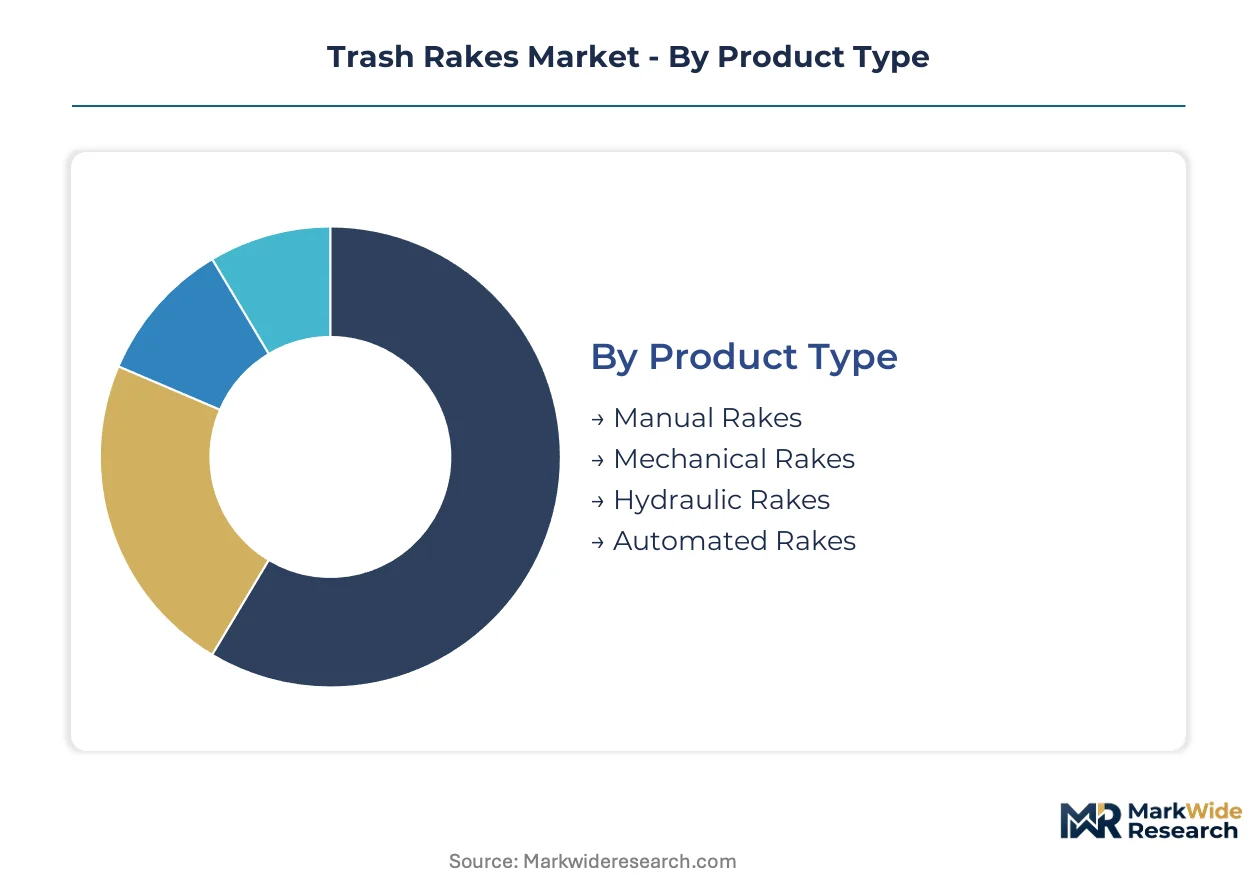
Segmentation in trash rakes determines procurement specifications, maintenance architectures, and supplier qualification pathways. Municipal utilities deploy divergent screening technologies based on debris load profiles, labor availability, and regulatory compliance timelines. Understanding these category boundaries clarifies where capital expenditure concentrates and which specifications are gaining technical traction.
Product Type:
Supply concentration in stainless steel screening components favors manufacturers with captive metallurgical capabilities or long-term Nordic supply contracts.
- Automated Rakes:These systems integrate programmable logic controllers with variable-frequency drives to enable unattended debris removal cycles. German municipal utilities along the Rhine-Ruhr corridor are prioritizing automated installations to satisfy EU Urban Wastewater Treatment Directive pretreatment mandates while reducing labor costs at remote intake structures.
- Mechanical Rakes:Chain-and-sprocket drive systems with manual or semi-automated operation dominate legacy European treatment plant retrofits. Budget-constrained utilities in France and Belgium are extending replacement cycles for mechanical units despite rising maintenance labor costs, compressing near-term demand for full automation upgrades.
- Manual Rakes:Portable aluminum or polymer screening tools serve emergency debris removal at small tributary intakes.
- Hydraulic Rakes:Piston-driven raking mechanisms handle high-torque requirements at flood-prone river installations.
Automated rakes absorb the bulk of installed capacity; hydraulic rakes are expanding most quickly in alpine flood-prone specifications.
End User:
Cost tier stratification separates framework-agreement municipalities from transactional construction-site procurement.
- Municipalities:Regional purchasing cooperatives in Germany's Rhine-Ruhr metropolitan corridor aggregate demand through multi-year maintenance-embedded framework agreements. These contracts prioritize REACH-compliant stainless steel components and ISO 9001-certified suppliers, creating qualification barriers for smaller equipment vendors.
- Environmental Agencies:Conservation-focused river restoration programs specify polymer-composite bar screens for reduced foundation requirements at sensitive ecological sites. French agency procurement templates are embedding material compliance verification for chromium-free anti-corrosion coatings.
- Waste Management Companies:Private operators prioritize total cost of ownership metrics over capital expenditure minimization.
- Construction Sites:Temporary intake protection drives demand for rental and lease-based screening solutions.
Municipalities command the largest procurement volume; environmental agencies are climbing the fastest specification tier for sustainable materials.
Application:
Volume concentration centers on continuous-operation river intakes versus intermittent park maintenance deployments.
- River Cleaning:Permanent intake structures at hydroelectric facilities and municipal water treatment plants require heavy-duty screening with automated debris compaction and conveyor discharge. High-debris alpine waterways in Switzerland and Austria are driving demand for specialized rake geometries with reinforced bar spacing.
- Waste Removal:Industrial effluent pretreatment at chemical and food processing facilities demands corrosion-resistant duplex stainless steel construction. REACH substance restriction schedules are accelerating qualification of chromium-free coating alternatives for these water-contact applications.
- Park Maintenance:Seasonal leaf and litter collection at urban green spaces utilizes portable manual and small mechanical rakes.
- Beach Cleaning:Saltwater corrosion environments specify marine-grade aluminum or polymer-composite bar systems.
River cleaning holds the steepest expansion trajectory; park maintenance retains the largest installed base of legacy mechanical equipment.
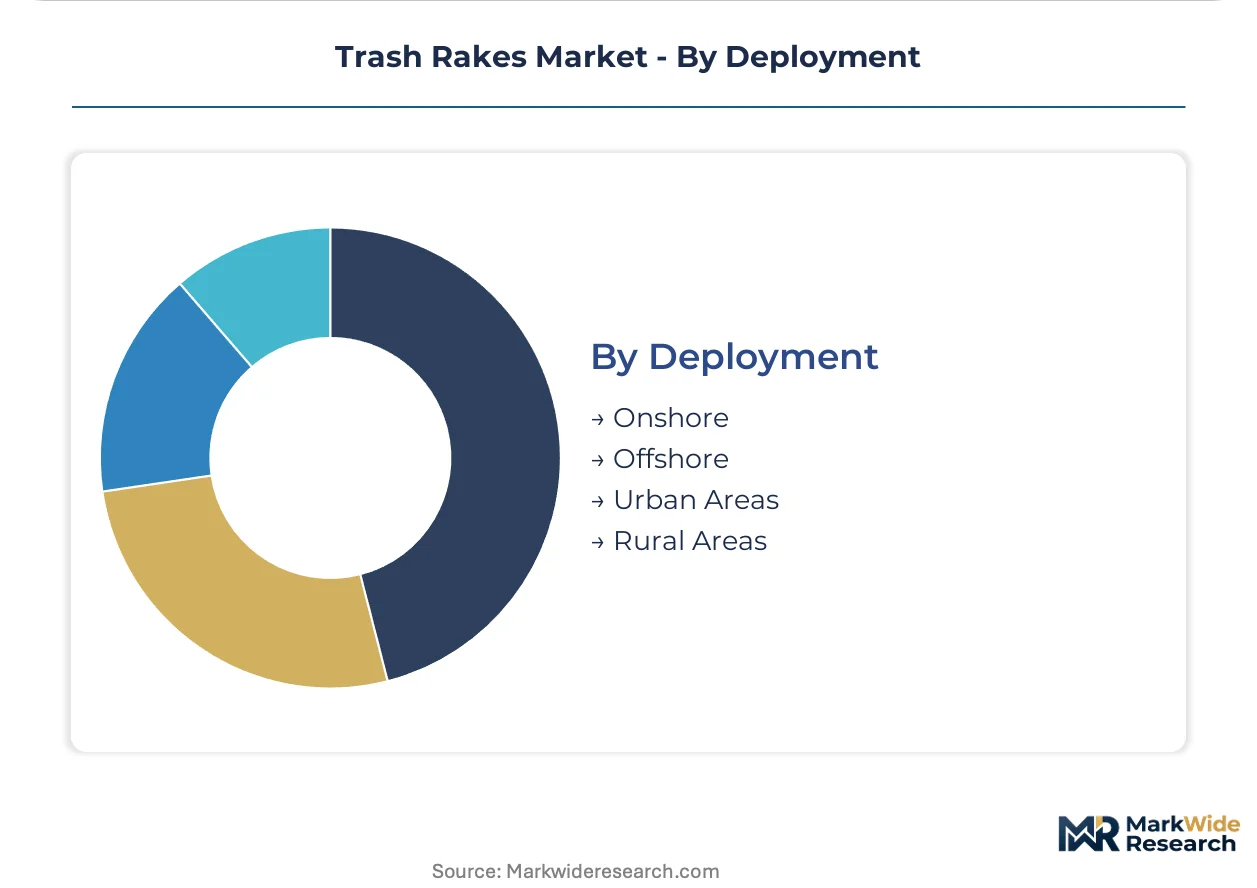
Deployment:
Customer type differentiation separates unattended remote rural installations from urban infrastructure with maintenance crew proximity.
- Urban Areas:Dense utility networks in German and French metropolitan regions enable shared maintenance resources and rapid response times. Procurement departments in these markets are consolidating through regional purchasing cooperatives, shifting bargaining power toward buyer consortiums.
- Onshore:Fixed concrete intake structures at treatment plants and industrial facilities require retrofit-compatible automated rake designs. Utilities struggle with mechatronics integration complexity when upgrading manual-era infrastructure.
- Offshore:Floating intake platforms and coastal desalination facilities specify marine-grade materials and weatherproof drive enclosures.
- Rural Areas:Isolated pumping stations with limited crew access drive demand for fully automated systems with remote monitoring capabilities.
Urban areas concentrate procurement volume; rural areas are gaining share fastest through unattended automation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan corridor functions as Europe's densest concentration of water utility procurement activity, where aging infrastructure replacement cycles intersect with stricter EU effluent mandates. Municipal water treatment facilities across Germany's industrial heartland are accelerating automated screening installations to satisfy revised regulatory timelines.
Germany
The Rhine-Ruhr corridor aggregates demand through regional purchasing cooperatives embedding multi-year maintenance obligations into framework agreements. KBA procurement rules enforce CE marking and ISO 9001 certification as baseline supplier qualifications. Municipal operators in North Rhine-Westphalia are piloting polymer-composite bar screen systems at Rhine tributary intakes to reduce foundation retrofit costs.
France
ANSM-aligned water agency procurement templates are embedding REACH substance compliance verification into technical specifications for chromium-free anti-corrosion coatings. Budget-constrained utilities in the Hauts-de-France region are extending mechanical rake replacement cycles despite rising maintenance labor costs. The Île-de-France water authority is consolidating screening equipment procurement through centralized purchasing cooperatives.
Switzerland
Swissmedic does not regulate trash rakes directly, but cantonal water utilities enforce stringent material compliance for alpine river intake applications. High-debris alpine waterways in the Bernese Oberland are driving demand for specialized rake geometries with reinforced bar spacing. Zurich's municipal water department is prioritizing unattended automation at remote mountain pumping stations.
United States
EPA Clean Water Act enforcement at municipal intakes is accelerating debris removal standard upgrades across Great Lakes and Mississippi River watershed facilities. The Rust Belt corridor from Michigan to Ohio exhibits concentrated replacement demand as legacy mechanical systems reach end-of-design-life. Chicago's metropolitan water reclamation district is embedding predictive maintenance clauses into large-scale screening equipment contracts.
Austria
Federal water management authorities are implementing EU Urban Wastewater Treatment Directive pretreatment mandates through provincial infrastructure grant programs. Alpine flood-prone river intakes in Tyrol and Vorarlberg are specifying hydraulic rake mechanisms for high-torque debris handling. Vienna's municipal utility is retrofitting automated screening onto concrete intake structures originally designed for manual operation.
Trash Rakes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered qualification barriers. The vendor base stratifies between scale-driven diversified water technology groups and mid-cap screening equipment specialists with captive metallurgical capabilities. Three archetypes dominate: integrated water technology conglomerates with broad environmental portfolios, European pure-play specialists with in-house stainless steel component production, and regional fabricators serving transactional construction-site demand. Capacity expansion in REACH-compliant coating alternatives and backward integration into duplex stainless steel sourcing represent the dominant competitive moves.
Among diversified water technology groups, Veolia Water Technologies and Pentair occupy positions spanning multiple environmental infrastructure verticals. WesTech Engineering exemplifies the North American manufacturing footprint archetype competing on delivery timelines for large municipal contracts. Andritz AG anchors the European specialist tier through in-house production capabilities for stainless steel screening components. Huber Technology represents the German pure-play model differentiated via specialized rake geometries optimized for high-debris river intakes.
| Leading Market Players |
|---|
| WesTech Engineering |
| Pentair |
| Ovivo |
| Aqseptence Group |
| BDP Industries |
| Parkson Corporation |
| Veolia Water Technologies |
| Andritz AG |
| Huber Technology |
| Others |
Value Network & Pricing Analysis
Regional purchasing cooperatives in Germany's Rhine-Ruhr corridor aggregate municipal water utility demand through multi-year framework agreements, embedding maintenance obligations that compress upfront equipment margins while extending revenue visibility across contract lifecycles. This buyer concentration shifts pricing power toward consortiums capable of extracting REACH-compliant material certifications and ISO 9001 quality guarantees as baseline qualifications.
Pricing Analysis
Lead-time premiums command substantial price separation between Nordic duplex stainless steel suppliers with captive metallurgical capacity and spot-market fabricators facing extended CE marking conformity assessments. Three-tier pricing structure across premium REACH-certified, standard CE-marked, and economy mechanical-rake tiers reflects certification grade and volume scale differentiation. Cost compression in standard-tier automated rakes is intensifying because regional purchasing cooperatives consolidate procurement volume. Budget-constrained French and Belgian utilities exhibit highest price sensitivity, while German municipal associations prioritize total cost of ownership metrics.
Supply Chain Analysis
Freight cost escalation from Nordic metallurgical centers to Central European fabrication sites is compressing margins for non-vertically integrated assemblers lacking captive stainless steel production. Supply concentrates in Germany, Sweden, and Finland for duplex stainless steel screening components; polymer-composite bar systems draw from specialized compounders in Switzerland and Austria. REACH substance restriction schedules on chromium-based anti-corrosion coatings introduce regulatory chokepoint risk. Distribution runs through regional equipment distributors serving municipal procurement departments and direct OEM relationships with large water technology conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated screening technology is displacing mechanical rake installed base across European water utilities, with programmable logic controller integration and predictive maintenance architectures replacing chain-and-sprocket legacy systems. This transition phase compresses replacement cycles while creating qualification barriers for suppliers lacking mechatronics capabilities.
For Market Incumbents: Acquire predictive maintenance software capabilities and remote monitoring platform assets to defend service revenue streams against pure-play automation specialists. Backward integration into REACH-compliant coating formulation insulates margin position from raw material compliance volatility. Capacity addition in polymer-composite bar production addresses foundation-light retrofit demand at aging concrete intake structures. For New Entrants and Emerging Players: The premium-economy price gap in hydraulic rake systems for alpine flood-prone installations creates entry opportunity for specialized geometry designers. Target Austrian and Swiss cantonal water utilities with unattended automation requirements at remote mountain pumping stations. Go-to-market angle should emphasize chromium-free coating compliance ahead of EU Green Deal implementation timelines. For Investors and Strategic Acquirers: The window for entry favors mid-cap European screening specialists with in-house stainless steel component production and established CE marking pathways. Long-term viability rests on regulatory compliance infrastructure rather than pure manufacturing scale. Watch for EU Urban Wastewater Treatment Directive enforcement acceleration as inflection indicator for retrofit demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Duplex Stainless Steel | Captive metallurgical supply secures REACH-compliant material flow for Rhine-Ruhr municipal contracts. |
| Predictive Maintenance Platform Development | Remote monitoring capabilities unlock recurring revenue from framework-agreement utilities in Germany. |
| Polymer-Composite Bar System Qualification | Modular foundation requirements address retrofit cost barriers at aging French and Belgian treatment plants. |
| CE Marking Acceleration for Automated Rakes | Compressed conformity assessment timelines improve win rates against North American delivery competitors. |
| Alpine Intake Specialization Partnership | Customized rake geometries for high-debris Swiss and Austrian waterways capture underserved specification tier. |
Research Methodology
Independent corroboration across municipal water utility procurement officers, screening equipment maintenance directors, and polymer-composite materials engineers underwrites the qualitative findings in this analysis. Primary interviews with OEM procurement teams at diversified water technology conglomerates and regional fabricators were cross-validated against EU Urban Wastewater Treatment Directive implementation timelines, REACH substance restriction schedules, and customs data on stainless steel screening component trade flows. Bottom-up demand modeling from individual municipal retrofit projects was triangulated with top-down capital expenditure projections from national water agency budget disclosures.
Rate-of-change decomposition across product type segmentation—automated rakes, mechanical rakes, hydraulic rakes, and manual systems—drives volume and value outputs over the projection horizon. End-user stratification between framework-agreement municipalities, environmental agencies, waste management companies, and construction-site operators was modeled alongside deployment differentiation across urban, rural, onshore, and offshore installations. CAGRs were derived from infrastructure replacement cycle analysis and regulatory compliance deadline clustering. Forecast inputs incorporated duplex stainless steel price indices and CE marking assessment timeline distributions.
Inputs from German municipal association procurement databases and French water agency technical specification templates were available through the study window; gaps in real-time project commissioning data from budget-constrained Belgian and Austrian utilities introduce uncertainty bands around near-term replacement velocity. Forecasts reflect documented assumptions regarding EU directive enforcement pacing and REACH compliance cost pass-through rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
Municipal Solid Waste Incineration Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Qatar Waste Management Market