
 Recyclate PET Market | 2026-2036
Recyclate PET Market Size, Share, and Industry Trends Forecast 2026-2036
Recyclate PET Market Outlook
Food-grade pellet certification is rotating toward the center of competitive strategy in recyclate PET. Indorama Ventures Public Company Limited leverages its integrated PET resin and recycling footprint across multiple continents. Alpek S.A.B. de C.V. anchors its position through backward integration into flake collection and wash operations in the Americas. Loop Industries differentiates via proprietary depolymerization technology that converts low-value waste into virgin-quality monomers.
Recyclate PET consists of reprocessed polyethylene terephthalate derived from post-consumer or post-industrial waste streams, typically requiring intrinsic viscosity levels between 0.72 and 0.82 dL/g for bottle applications and melt filtration below 50 microns to achieve optical clarity. Its primary purpose is to displace virgin fossil-based PET in packaging and fiber applications while maintaining equivalent mechanical and barrier performance. Bottle-grade recyclate PET commands the largest volume share but faces margin compression from bale cost volatility, whereas fiber-grade material benefits from more stable textile off-take agreements with apparel brands. Sheet-grade and film-grade segments occupy narrower niches where optical consistency requirements limit supplier pools.
The US FDA issues letters of no objection for recyclate PET processes intended for food contact, while the EU's REACH framework and EFSA safety assessments govern migration limits and contamination thresholds for recycled content in consumer packaging. China's SAMR enforces GB standards for recycled plastics used in food packaging, creating divergent compliance pathways that fragment market access. Stakeholders must monitor regulatory harmonization progress between jurisdictions and assess whether regional certification investments will yield transferable qualifications or strand capital in single-market compliance infrastructure.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing virgin PET margins by mandating minimum recycled content thresholds, forcing packaging converters to secure certified food-grade recyclate supply ahead of infrastructure readiness.
Growth Catalysts
- Bottle-to-bottle recycling mandates:The EU Green Deal accelerates closed-loop commitments from beverage brands, creating guaranteed offtake for food-grade pellet producers.
- Chemical recycling scale-up:Depolymerization technologies unlock feedstock from colored and contaminated bales previously routed to fiber or landfill.
- Germany:Advanced collection infrastructure and sorting investments concentrate demand, establishing price benchmarks for neighboring markets.
Market Restraints
- Bale cost volatility:Post-consumer PET collection rates fluctuate with oil-price-driven virgin resin arbitrage, squeezing recycler margins unpredictably.
- Technical limitation:Intrinsic viscosity degradation through mechanical reprocessing caps bottle-grade recyclate at 30-50% blend ratios without IV restoration.
- Regulatory friction:Divergent FDA, EFSA, and SAMR certification pathways fragment market access and strand compliance capital in single jurisdictions.
Strategic Opportunities
- Underpenetrated geography:India's BIS standards evolution and EPR implementation create first-mover advantage for integrated flake-to-pellet operators.
- Technology convergence:Digital watermarks combined with AI-powered sorting raise bale purity and reduce manual preprocessing costs.
- Regulatory tailwind:The EU's CSRD disclosure requirements push apparel brands toward verified recycled content sourcing for Scope 3 reporting.
Industry Challenges
- Capex intensity:Food-grade pellet lines require melt filtration below 50 microns and solid-state polymerization, demanding 8-12 year payback horizons.
- Certification timeline:FDA letters of no objection for novel recycling processes extend 18-36 months, delaying commercialization.
- Skill gap:Chemical recycling operations require polymer chemists and process engineers scarce in traditional mechanical recycling labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recyclate PET Market |
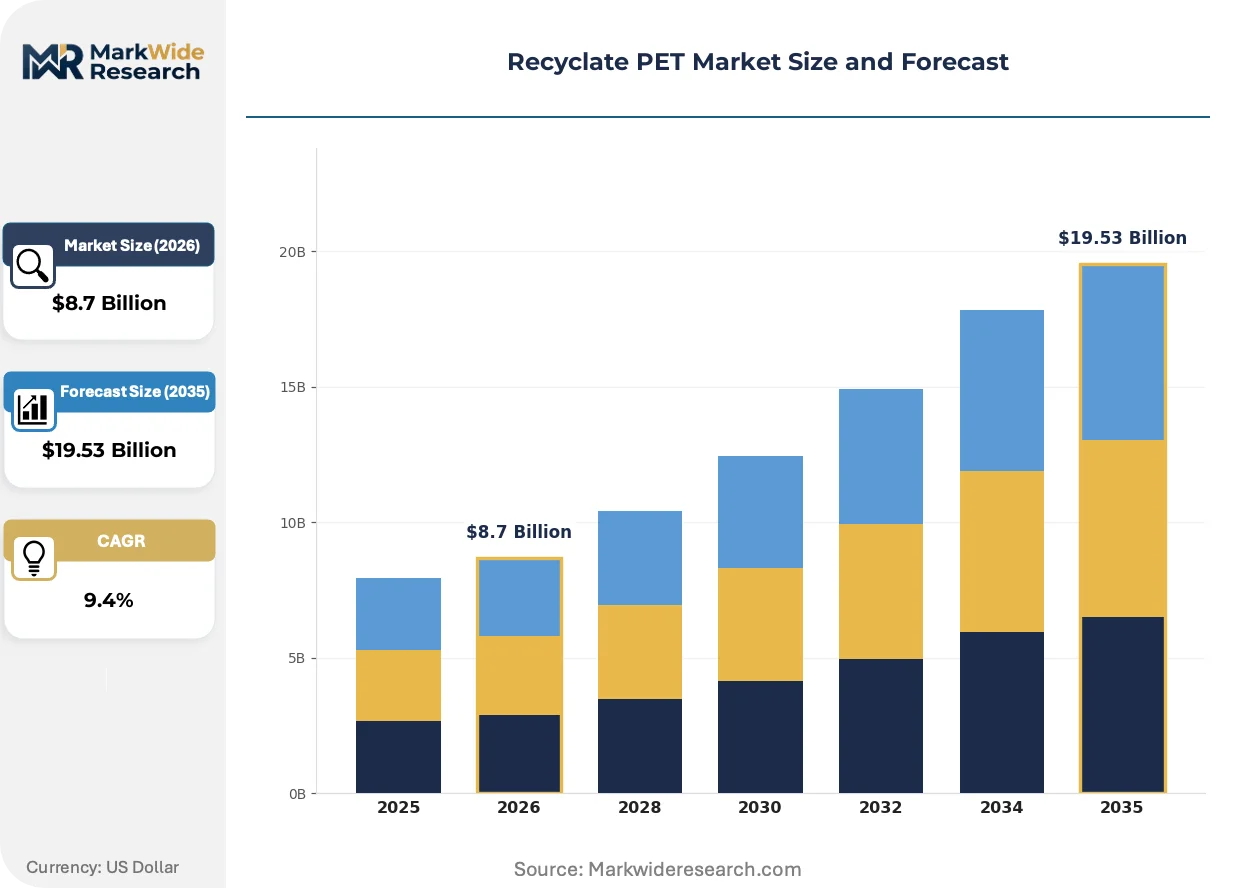
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottle Grade, Fiber Grade, Sheet Grade, Film Grade Application: Packaging, Textiles, Automotive, Construction End User: Cosmetics, Food & Beverage, Apparel, Consumer Goods Distribution Channel: Online Retail, Wholesale, Direct Sales, Supermarkets |
| Companies Covered | Indorama Ventures Public Company Limited, Alpek S.A.B. de C.V., Plastipak Holdings, Inc., Far Eastern New Century Corporation, PolyQuest, Inc., Evergreen Plastics, Inc., Loop Industries, ALPLA, CarbonLITE Industries LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recyclate PET Market Strategic Shifts
Food-grade certification standards are becoming the primary battleground for competitive differentiation, separating integrated producers from merchant recyclers unable to bear validation costs.
Depolymerization-to-repolymerization technology is fragmenting the traditional mechanical recycling value chain by enabling direct conversion of low-quality waste into virgin-equivalent monomers. Beverage brands with aggressive recycled content targets are contracting dedicated offtake from these facilities. The technology is fragmenting established flake and chip merchant markets by collapsing intermediate processing steps.
REACH framework updates are tightening migration limit thresholds for recycled content in food contact, compelling recyclers to invest in enhanced decontamination and testing protocols. The industrial consequence is accelerated consolidation among pellet producers lacking in-house analytical capabilities. Bottle-grade recyclate destined for EU markets bears the heaviest compliance burden, with converters demanding chain-of-custody documentation.
Brand-led procurement specifications are displacing commodity spot purchasing as the dominant sourcing model for food-grade recyclate. Packaging converters are locking multi-year supply agreements with certified producers, replacing auction-based bale buying. This shift is most visible in Germany, where beverage industry concentration enables collective bargaining for recycled content security.
Recyclate PET Market Segmentation
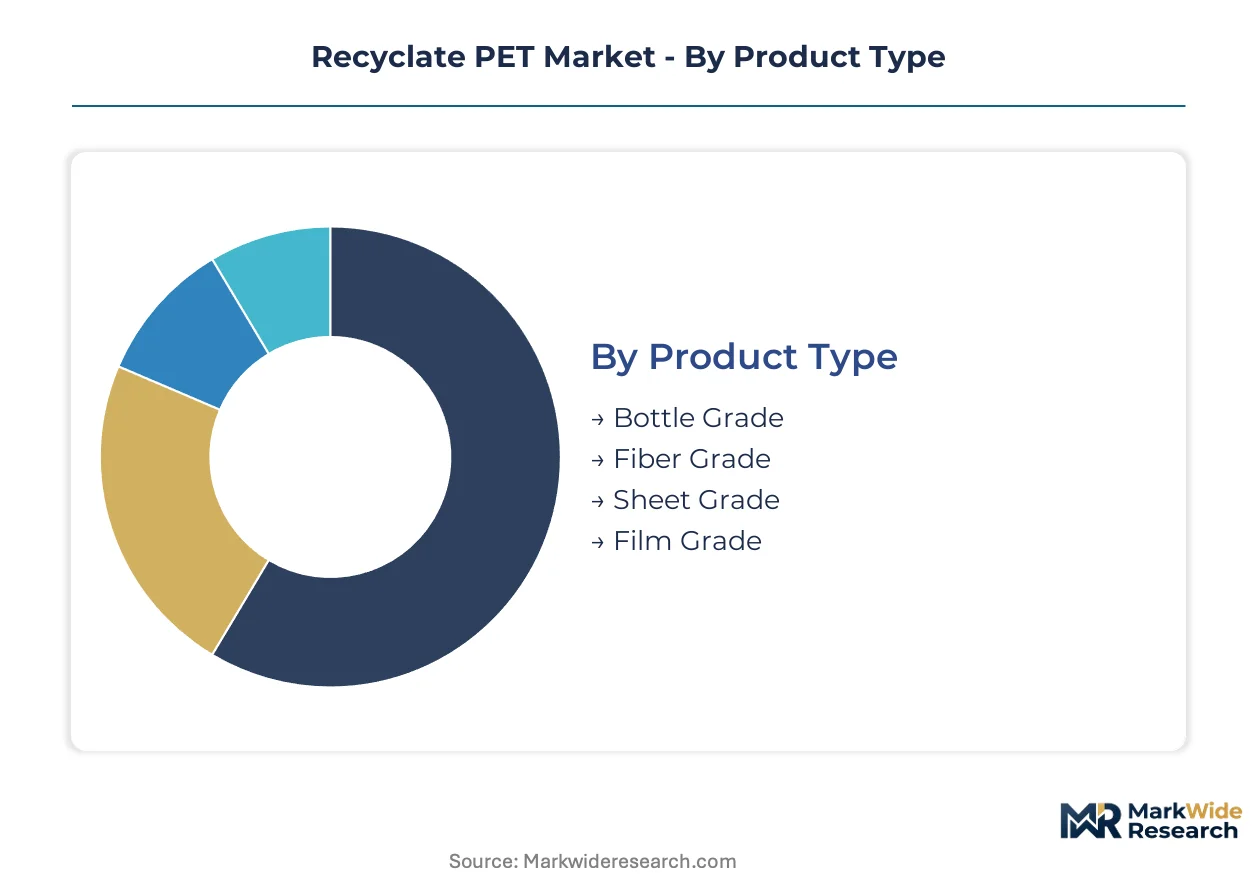
Segmentation in recyclate PET reveals how technical specifications, regulatory pathways, and end-use requirements fragment supply chains. Different grades carry distinct certification burdens and margin profiles that reshape competitive positioning across value chain tiers.
Product Type:
German converters dominate bottle-grade offtake, while fiber-grade demand clusters in Southeast Asian textile hubs. Export-led segments concentrate where EFSA-equivalent certification is attainable.
- Bottle Grade:Requires intrinsic viscosity between 0.72 and 0.82 dL/g and melt filtration below 50 microns for optical clarity. Demand concentrates in Germany and France where beverage brands face EU Green Deal recycled content mandates; FDA letters of no objection extend commercialization timelines.
- Fiber Grade:Tolerates lower IV thresholds and broader contamination windows than bottle applications. Textile manufacturers in Vietnam and Bangladesh lock multi-year offtake agreements with apparel brands pursuing CSRD-compliant Scope 3 reporting.
- Sheet Grade:Narrow niche where thermoforming optical consistency limits supplier pools to integrated flake-to-pellet operators.
- Film Grade:Specialized barrier performance requirements constrain viable feedstock to post-industrial waste streams with controlled contamination profiles.
Bottle grade holds the largest share; momentum sits with fiber grade as apparel brands accelerate verified recycled content commitments.
Application:
Cost tier differentiation separates premium food-contact packaging from commodity textile and construction applications with minimal certification overhead.
- Packaging:Demands EFSA safety assessments and REACH migration limit compliance for food contact. German and Italian converters secure dedicated supply from depolymerization facilities producing virgin-equivalent monomers.
- Textiles:Benefits from stable off-take agreements with limited regulatory friction compared to food-grade pathways. Bangladeshi and Vietnamese spinners source flake directly from European collection systems.
- Automotive:Emerging specification tier where OEMs specify recycled content for interior trim under EU end-of-life vehicle directives.
- Construction:Lowest certification barrier segment where non-food contact geotextiles and insulation absorb mixed-color flake rejected from bottle-grade lines.
Packaging commands premium pricing; construction absorbs volume fastest as infrastructure projects specify recycled content.
End User:
Customer-type concentration shows food and beverage brands driving certified supply while cosmetics and apparel follow with less stringent chain-of-custody demands.
- Food & Beverage:Mandates bottle-to-bottle recycling with full FDA or EFSA validation. Coca-Cola and PepsiCo contracting structures in Germany establish regional price benchmarks for neighboring markets.
- Apparel:Leverages CSRD disclosure requirements to push verified recycled fiber sourcing. H&M and Zara parent companies specify mass-balance certification from Southeast Asian textile mills.
- Cosmetics:Premium positioning supports higher pellet costs for optical-grade sheet and bottle applications with decorative clarity requirements.
- Consumer Goods:Diverse specification range from durable goods housings to disposable cutlery with mixed regulatory exposure across EU and US jurisdictions.
Food and beverage anchors volume commitments; cosmetics delivers margin expansion through premium optical specifications.
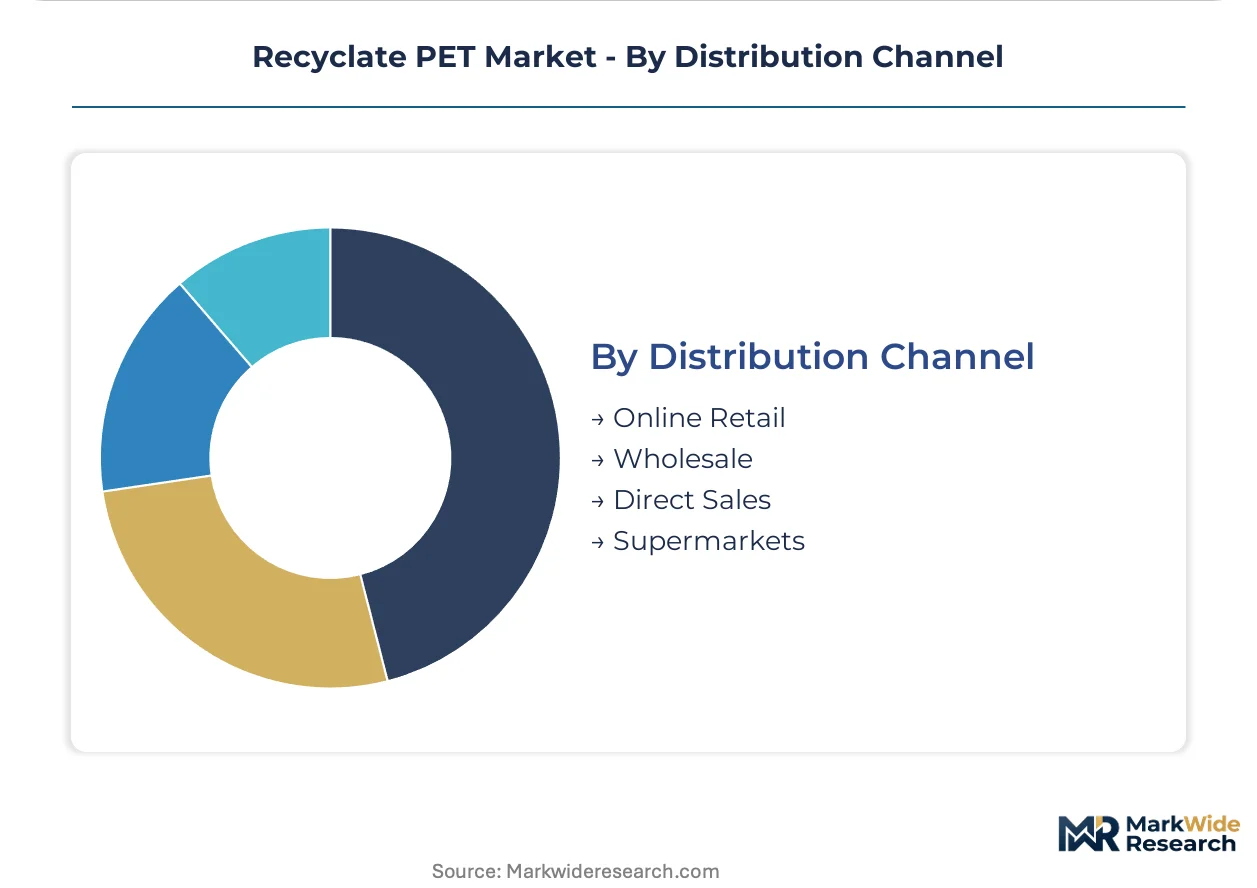
Distribution Channel:
Supply concentration favors direct sales for certified grades while wholesale and online channels handle commodity fiber-grade flake with minimal preprocessing.
- Direct Sales:Dominates food-grade pellet movement where converters demand chain-of-custody documentation and lot-specific contamination testing. Indorama and Alpek maintain dedicated account teams for major beverage bottlers.
- Wholesale:Handles fiber-grade flake aggregation from multiple collection systems into standardized bales for Asian textile processors.
- Online Retail:Emerging channel for small-batch specialty grades and experimental formulations targeting niche packaging designers.
- Supermarkets:Limited penetration; primarily reverse-logistics collection points for post-consumer bale aggregation rather than forward distribution.
Direct sales captures certified-grade value; wholesale scales fiber-grade volume across fragmented textile demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate in Germany as the net surplus hub, while Asian textile processors import European flake and the United States maintains deficit positions in food-grade pellet supply. Trade patterns follow certification gradients, with EFSA-validated material commanding destination premiums.
Germany
Beverage bottlers under the EU Green Deal mandate secure dedicated offtake from depolymerization facilities. The country's national packaging regulator enforces strict post-consumer collection quotas through extended producer responsibility frameworks. The Rhineland industrial cluster hosts integrated flake-to-pellet operations serving Coca-Cola and PepsiCo contracting structures that establish regional price benchmarks.
United States
Packaging converters face FDA letter-of-no-objection timelines stretching commercialization horizons for novel recycling entrants. The EPA oversees state-level bottle bill variations that fragment collection infrastructure efficiency. The Southeast manufacturing corridor attracts chemical recycling investments targeting apparel brand Scope 3 compliance requirements.
China
Textile manufacturers in Zhejiang and Jiangsu provinces lock multi-year flake offtake agreements with European collection systems. SAMR enforces GB standards for recycled plastics in food packaging that diverge from Western certification pathways. The Yangtze River Delta concentration of fiber-grade processing absorbs mixed-color flake rejected from bottle-grade lines elsewhere.
India
Integrated flake-to-pellet operators anticipate BIS standards evolution and EPR implementation creating first-mover structural advantages. The central government's PLI scheme incentives attract mechanical recycling capacity expansion. The Gujarat petrochemical corridor anchors backward integration into wash operations serving domestic textile demand.
Vietnam
Spinners in Ho Chi Minh City and Binh Duong province source flake directly from European collection systems for CSRD-compliant apparel supply chains. The country's national standards body aligns technical specifications with EU REACH migration limits to maintain export market access. The Mekong Delta concentration of polyester fiber production benefits from stable off-take agreements with limited regulatory friction compared to food-grade pathways.
Recyclate PET Market Competitive Environment
Concentration sits with integrated resin producers that control backward integration into flake collection and wash operations. The market structure tiers between multinational chemical conglomerates with global PET footprints, regional mechanical recyclers serving textile demand, and technology licensors offering depolymerization solutions. Strategic moves center on capacity expansion in food-grade pellet lines and geographic diversification to capture emerging EPR implementation windows.
Within the integrated producer tier, Indorama Ventures Public Company Limited and Alpek S.A.B. de C.V. represent archetypes of global scale with captive supply chain control. Loop Industries occupies a position exemplifying technology-driven differentiation through proprietary chemical recycling approaches. These three anchors illustrate the competitive spectrum from commodity resin integration to novel process validation.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Alpek S.A.B. de C.V. |
| Plastipak Holdings, Inc. |
| Far Eastern New Century Corporation |
| PolyQuest, Inc. |
| Evergreen Plastics, Inc. |
| Loop Industries |
| ALPLA |
| CarbonLITE Industries LLC |
| Others |
Value Chain & Pricing Dynamics
EFSA safety assessments gate both supply qualification and price differentiation in recyclate PET, separating certified food-grade pellet producers from merchant recyclers locked out of premium tiers. The certification burden concentrates pricing power among integrated operators while fragmenting downstream access for converters lacking validated supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with beverage brands locking multi-year supply agreements at fixed premiums over spot flake indices. Price differentiation separates FDA-lettered food-grade pellet from fiber-grade flake and construction-grade mixed-color material, with certification tier and volume scale as primary drivers. Cost compression in mechanical recycling lines is intensifying because bale cost volatility erodes margins unpredictably. Textile spinners in Southeast Asia exhibit highest price sensitivity, while German bottlers under EU Green Deal mandates accept premium pricing for supply security.
Supply Chain Analysis
Strait of Hormuz transit underwrites naphtha feedstock flows that tether virgin PET pricing to regional resin arbitrage, indirectly disciplining recyclate pellet premiums. Supply concentrates in Germany, the United States, and Thailand, with raw material dependencies spanning post-consumer bale collection, PTA/MEG monomer supply, and specialized melt filtration equipment. Single-source vulnerability runs through European flake aggregation systems serving Asian textile demand. Distribution runs through direct sales channels for certified grades and wholesale bale aggregation for commodity fiber applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage brand consolidation under EU Green Deal collective bargaining structures has shifted procurement power toward buyers, forcing pellet producers into dedicated offtake negotiations with compressed margin structures.
For Market Incumbents: Fortify backward integration into wash operations and flake collection infrastructure to defend against merchant recycler margin erosion from bale cost volatility. Prioritize depolymerization capacity additions in Germany and the US Southeast to capture chemical recycling premiums ahead of FDA letter-of-no-objection bottlenecks for novel entrants. Lock exclusive supply relationships with Coca-Cola and PepsiCo contracting structures that establish regional price benchmarks. For New Entrants and Emerging Players: FDA fast-track pathways for novel recycling processes create white-space entry points for depolymerization specialists targeting 18-36 month commercialization windows. India's evolving BIS standards and EPR implementation offer the most penetrable geography for integrated flake-to-pellet operators. Lead with digital watermarking and AI-powered sorting technology as a go-to-market angle to differentiate bale purity and reduce preprocessing costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mechanical recycling platforms lacking food-grade certification infrastructure and stranded in fiber-grade commodity exposure. Five-to-ten year viability hinges on successful certification navigation and technology transition to chemical recycling pathways. Watch for FDA letter-of-no-objection issuance velocity as the inflection indicator separating viable food-grade pellet producers from stranded merchant recyclers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flake Collection | Captures bale cost margin and secures feedstock for Indorama and Alpek integrated operations. |
| Depolymerization Technology Licensing | Loop Industries' proprietary approach converts contaminated waste into virgin-equivalent monomers for beverage brands. |
| Food-Grade Pellet Line Expansion | EFSA-validated capacity commands destination premiums in German and French converter markets. |
| Digital Watermark Implementation | AI-powered sorting raises bale purity and reduces manual preprocessing costs for merchant recyclers. |
| Multi-Year Offtake Agreement Structuring | Coca-Cola and PepsiCo contracting in Germany establishes regional price benchmarks for neighboring markets. |
Study Parameters
A spread of perspectives from PET resin procurement managers, recycling plant engineers, beverage brand sustainability directors, and EFSA regulatory consultants converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from customs trade data, SEC 10-K filings of integrated resin producers, EU REACH framework updates, and FDA letter-of-no-objection databases. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Segmentation dimensions modeled include product grade tier, end-use application, certification pathway, and regional regulatory cluster across the projection horizon. CAGRs derive from installed capacity expansion schedules, EPR implementation timelines, and brand recycled content commitment trajectories. Specific forecast inputs incorporate bale collection rate elasticity to oil-price-driven virgin resin arbitrage and chemical recycling scale-up velocity.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and stable apparel brand Scope 3 reporting requirements; material deviation in regulatory stringency or macroeconomic conditions would warrant model refresh. Practitioners should keep alternative scenarios live as FDA certification timelines and SAMR GB standards evolution create divergent market access pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market