
 Qatar Waste Management Market | 2026-2036
Qatar Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Waste Management Market Insights
Qatar's National Development Strategy is consolidating the waste management landscape by raising compliance thresholds and mandating integrated treatment infrastructure. Averda leverages its regional logistics network to sustain collection density across Doha's commercial corridors. Veolia Qatar anchors its position through technology leadership in hazardous waste treatment. Seashore Group differentiates via vertical integration into transport and disposal operations.
Waste management encompasses the systematic collection, transport, treatment, and disposal of solid and liquid refuse, with engineered landfills requiring composite liner systems and leachate collection networks to prevent groundwater contamination. The primary purpose is environmental protection and public health preservation while recovering material and energy value from discarded resources. Collection services dominate revenue flow due to recurring municipal contracts and fixed-route density. Recycling is expanding fastest as Qatar's National Vision targets divert recoverable materials from landfill streams. Industrial waste processing commands premium margins given specialized handling protocols and limited licensed capacity.
The Ministry of Municipality and Environment sets landfill licensing criteria and enforces waste segregation mandates under Qatar's broader environmental framework. The General Authority of Customs coordinates with waste regulators to control cross-border movement of hazardous materials. Stakeholders must monitor how enforcement intensity around circular economy targets reshapes investment timelines and technology selection criteria.
Market Dynamics
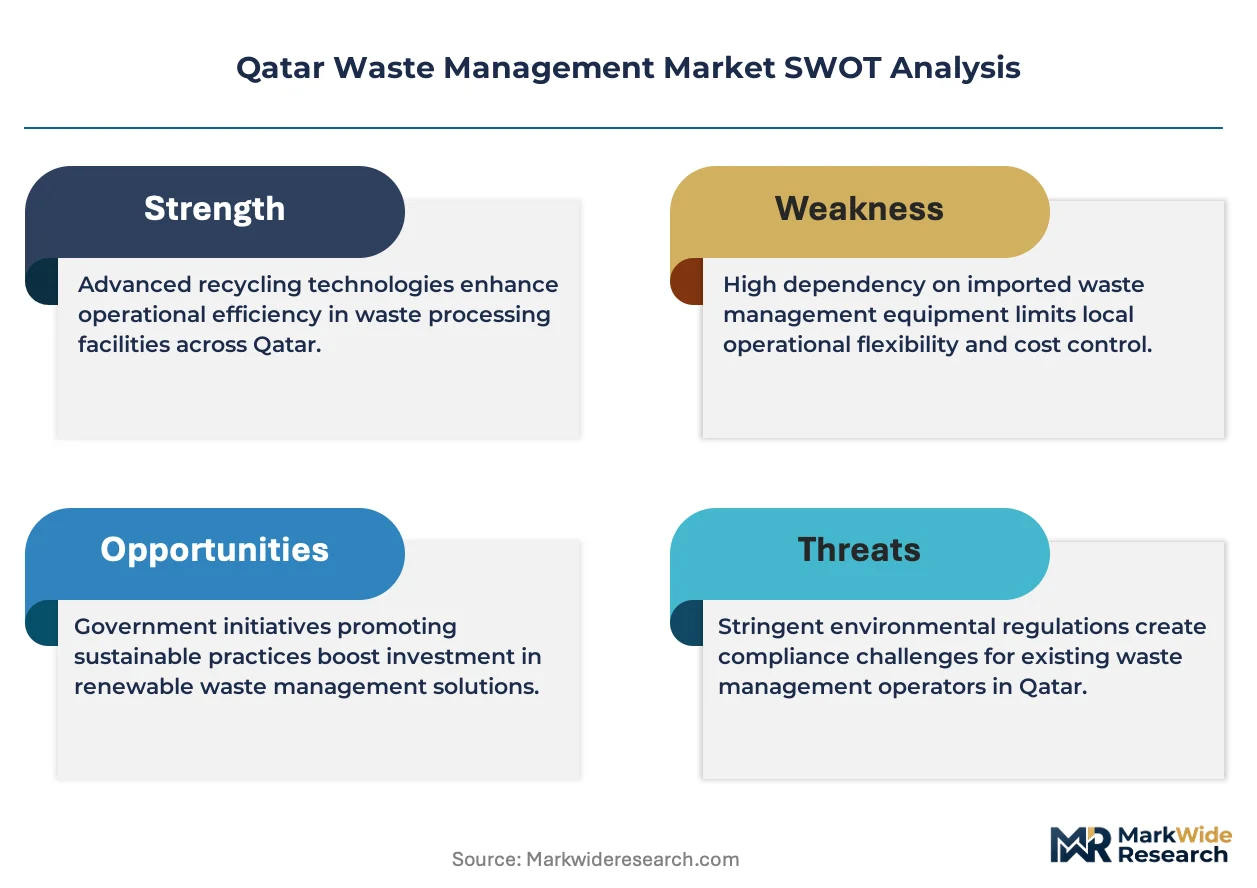
Qatar's National Development Strategy is compressing landfill diversion timelines and mandating integrated treatment infrastructure, forcing operators to retool collection networks and invest in material recovery facilities ahead of regulatory deadlines.
Growth Catalysts
- Construction waste streams:Mega-infrastructure projects in Doha and Lusail generate bulk demolition and excavation debris requiring licensed processing capacity. The Ministry of Municipality and Environment channels this volume through permitted facilities.
- Circular economy mandates:Qatar National Vision 2030 sets hard diversion targets for recoverable materials. Treatment operators must install sorting and recycling lines to maintain landfill access permits.
- Industrial zone clustering:Mesaieed and Ras Laffan concentrate petrochemical and manufacturing waste requiring hazardous handling protocols. Licensed incineration and stabilization capacity commands premium positioning.
Market Restraints
- Limited landfill airspace:Qatar's engineered cell construction costs and liner system requirements constrain greenfield site development. Existing facilities face capacity exhaustion within operational planning horizons.
- Specialized equipment import dependency:Leachate treatment systems and material recovery machinery rely on European and East Asian suppliers. Currency exposure and shipping timelines compress project margins.
- Segregation infrastructure gaps:Residential source separation remains underdeveloped despite Ministry mandates. Contaminated dry recyclables raise processing costs at material recovery facilities.
Strategic Opportunities
- Energy-from-waste development:Qatar's grid expansion and industrial steam demand create offtake visibility for thermal treatment investments. The General Electricity and Water Corporation provides interconnection pathways.
- Reverse logistics for e-waste:Consumer electronics turnover and data center refreshes generate precious metal recovery potential. Producer responsibility frameworks are tightening collection obligations.
- Digital fleet optimization:Route algorithms and bin-fill sensors reduce collection cost per ton. Municipal contract renewals increasingly specify technology-enabled service level agreements.
Industry Challenges
- Waste characterization expertise shortage:Hazardous classification and leachate testing require certified chemists and environmental engineers. Training pipelines lag facility licensing timelines.
- Legacy contract renegotiation friction:Existing municipal service agreements lack circular economy performance clauses. Amendment negotiations delay investment recovery periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Waste Management Market |
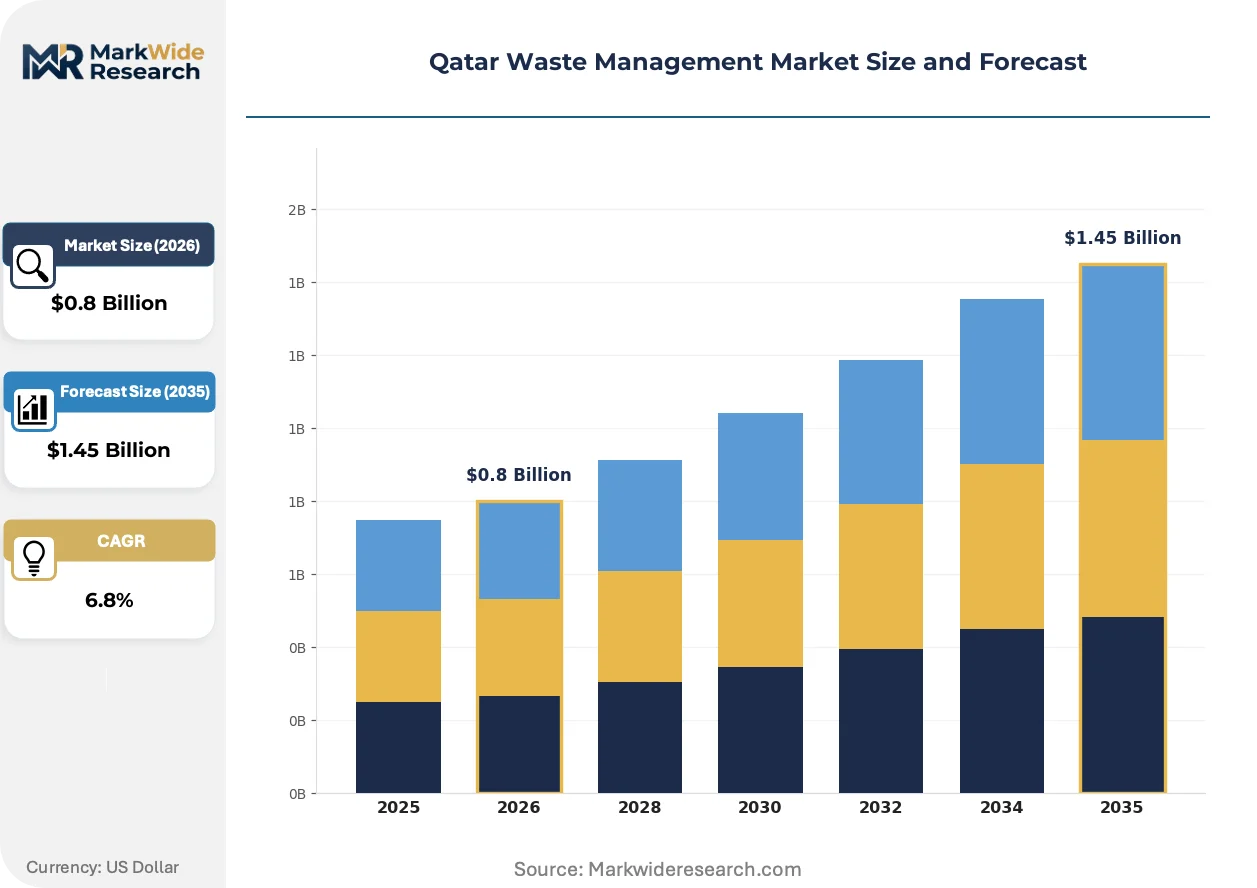
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.45 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Disposal, Recycling Waste Type: Municipal Solid Waste, Industrial Waste, Hazardous Waste, Organic Waste End User: Government, Construction, Healthcare, Manufacturing Technology: Landfill, Incineration, Anaerobic Digestion, Composting |
| Companies Covered | Seashore Group, Averda, Veolia Qatar, Al Haya Environmental Group, Bee'ah Qatar, Power Waste Management & Transport Co. WLL, Elite Waste Management, Dulsco Qatar, Milaha Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Waste Management Market Trends and Innovations
Digitalization and advanced sorting technologies are compressing processing costs while Qatar's regulatory tightening around diversion targets is accelerating capital deployment into material recovery infrastructure.
Optical sorting systems using near-infrared spectroscopy and artificial intelligence are converging with robotic pickers to automate polyethylene and polypropylene separation at material recovery facilities. Industrial waste processors in Mesaieed are piloting these configurations to reduce manual sorting headcount and contamination rates. The technology convergence is enabling higher-purity output streams that qualify for domestic manufacturing reintegration rather than export bales.
The Ministry of Municipality and Environment's updated technical guidelines for landfill liner systems and leachate monitoring are mandating double composite barriers and real-time groundwater quality telemetry. Engineering procurement contracts now specify 30-year post-closure care bonds. Hazardous waste incineration operators are responding by consolidating smaller facilities into centralized high-temperature units with continuous emissions monitoring.
Performance-based service contracts are displacing fixed-fee municipal collection agreements in Doha and Al Wakrah municipalities. Contractors now bear volume risk and earn margins through tonnage-diverted incentives tied to recycling recovery rates. This model is most visible in commercial corridor zones where waste audit data supports transparent baseline-setting and contract renewal bidding.
Qatar Waste Management Market Segmentation
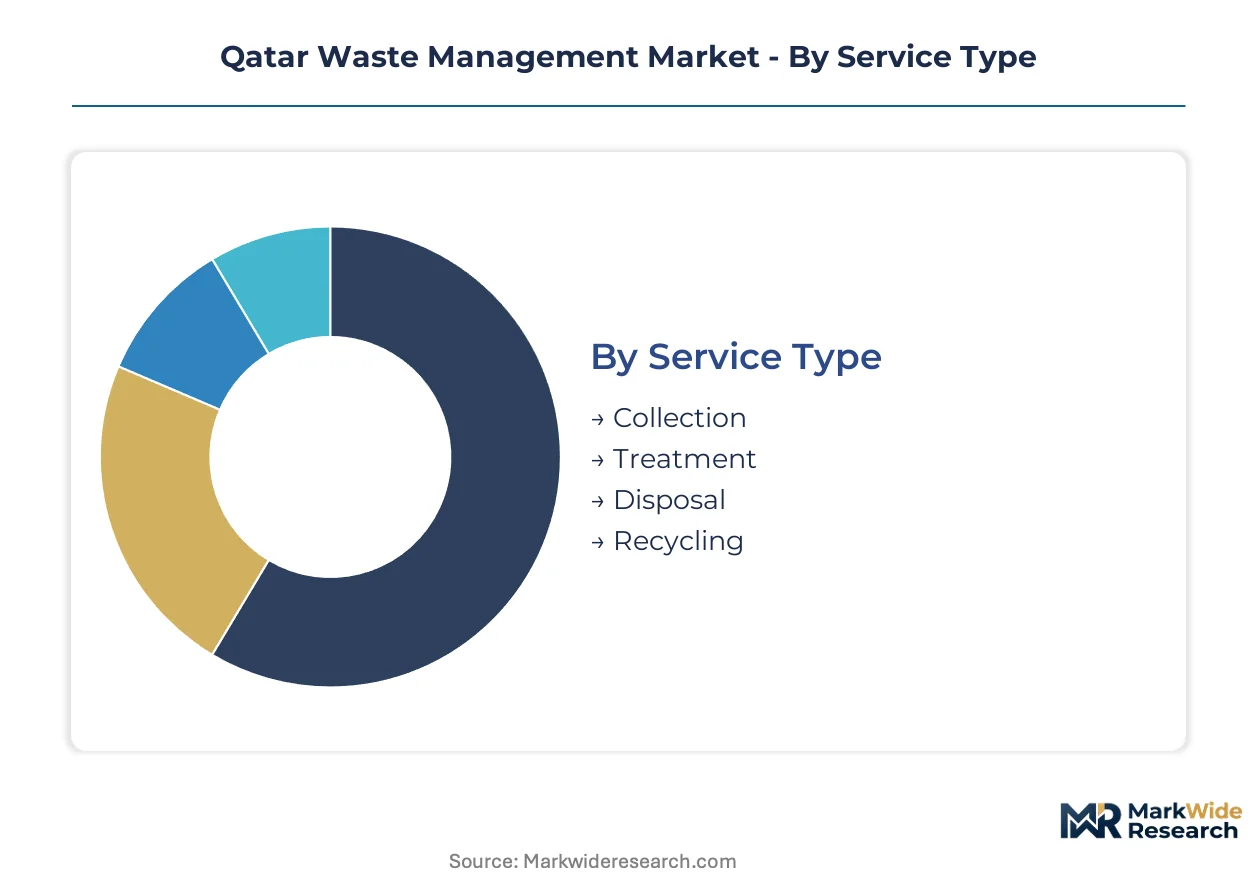
Segmentation in Qatar's waste management market reveals how regulatory pressure and infrastructure constraints concentrate revenue across specific service lines and waste streams. Understanding these divisions exposes where capital deployment and technology selection create sustainable competitive positioning.
Service Type:
Collection density in Doha's commercial corridors and industrial zones determines margin sustainability across service tiers.
- Collection:Fixed-route municipal contracts generate recurring revenue through dense urban zones. Doha's commercial corridors concentrate truck utilization rates, while Ministry of Municipality and Environment mandates enforce service frequency standards that lock in operational scale.
- Recycling:Material recovery facilities process polyethylene and polypropylene streams from construction and packaging waste. Qatar National Vision diversion targets are compressing landfill access permits, forcing operators to install optical sorting lines ahead of regulatory deadlines.
- Treatment:Stabilization and neutralization protocols handle hazardous industrial streams under licensed facility requirements.
- Disposal:Engineered landfill cells with composite liner systems and leachate collection networks serve residual waste streams.
Today's leader: Collection. Tomorrow's challenger: Recycling.
Waste Type:
Margin structure varies sharply by handling complexity and regulatory oversight intensity across waste categories.
- Industrial Waste:Petrochemical and manufacturing residues from Mesaieed and Ras Laffan require specialized stabilization and incineration capacity. Licensed treatment protocols and limited permitted facility availability sustain premium pricing for qualified operators.
- Hazardous Waste:Medical, chemical, and electronic waste streams demand certified chemists for classification and high-temperature destruction units. Ministry of Municipality and Environment licensing constraints restrict market entry to capital-intensive players with continuous emissions monitoring infrastructure.
- Municipal Solid Waste:Residential and commercial mixed streams dominate tonnage volume through Doha and Al Wakrah collection networks.
- Organic Waste:Food and agricultural residues feed composting and anaerobic digestion facilities serving landscaping and energy recovery applications.
Industrial Waste commands current margin peaks. Hazardous Waste is climbing the fastest as enforcement tightens.
End User:
Contract structures and procurement sophistication diverge sharply across customer categories.
- Construction:Mega-infrastructure projects in Lusail and Doha generate bulk demolition and excavation debris requiring permitted processing capacity. Ministry channeling of waste streams through licensed facilities creates volume visibility for specialized operators.
- Government:Municipal service agreements in Doha and Al Wakrah are shifting from fixed-fee to performance-based models with tonnage-diverted incentives tied to recycling recovery rates.
- Healthcare:Medical waste incineration contracts require specialized handling protocols and temperature verification documentation.
- Manufacturing:Industrial zone clustering in Mesaieed concentrates hazardous waste generation from petrochemical operations.
Construction anchors near-term volume. Government contracts are gaining share fastest through procurement reform.
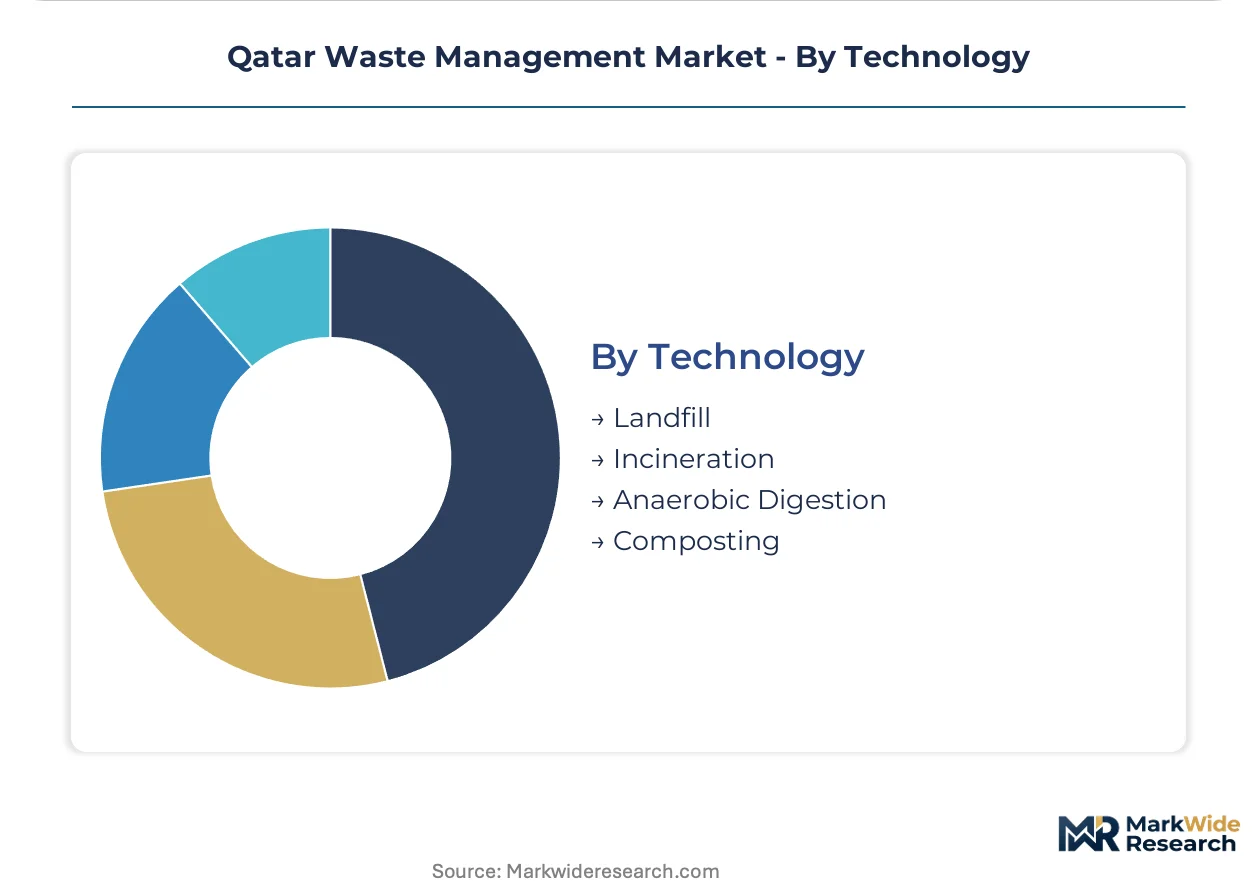
Technology:
Capital intensity and regulatory compliance burden segment competitive positioning across treatment methods.
- Landfill:Engineered cell construction with double composite barriers and real-time groundwater telemetry addresses Qatar's limited airspace constraints. Thirty-year post-closure care bonds and liner system specifications under Ministry technical guidelines elevate capital requirements for new site development.
- Incineration:High-temperature hazardous waste destruction units with continuous emissions monitoring consolidate smaller facilities into centralized operations. Mesaieed industrial processors pilot these configurations to reduce manual handling and contamination risk.
- Anaerobic Digestion:Organic waste decomposition generates biogas for industrial steam demand and grid interconnection through General Electricity and Water Corporation pathways.
- Composting:Aerobic processing of agricultural and food residues produces soil amendments for landscaping and revegetation projects.
Landfill retains volume dominance. Incineration shows the steepest expansion trajectory as hazardous waste enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waste management infrastructure in Qatar traces its modern lineage to the 2006 Asian Games construction cycle, when Doha's first engineered landfills and centralized collection networks were commissioned to handle surging construction debris and municipal loads.
Doha Metropolitan Area
Doha's commercial corridors and dense residential zones generate the highest collection route density in Qatar. The Ministry of Municipality and Environment enforces service frequency mandates that lock in operational scale for contracted operators. West Bay and the Pearl-Qatar concentrate premium commercial waste streams requiring specialized handling protocols.
Al Wakrah Municipality
Al Wakrah's industrial periphery and expanding residential districts drive dual waste stream growth. Qatar National Vision 2030 diversion targets are compressing landfill access permits for operators serving this zone. The Mesaieed industrial corridor bordering Al Wakrah concentrates petrochemical waste requiring licensed treatment capacity.
Lusail Development Zone
Lusail's mega-infrastructure projects generate bulk demolition and excavation debris requiring permitted processing facilities. The Ministry channels construction waste through licensed operators to maintain environmental compliance. Smart city infrastructure investments are creating demand for technology-enabled collection and monitoring systems.
Al Khor and Northern Industrial Zone
Al Khor's manufacturing clusters and Ras Laffan's industrial concentration generate hazardous waste streams requiring specialized stabilization and incineration capacity. Limited permitted facility availability sustains premium positioning for qualified operators. The General Authority of Customs coordinates cross-border hazardous material controls for this zone.
Qatar Waste Management Market Competitive Landscape
The competitive structure tilts toward regional specialists with established Ministry relationships and integrated infrastructure assets. Three to five operators control the majority of licensed landfill capacity and municipal collection contracts. Strategic archetypes include: vertically integrated waste-to-energy developers, hazardous waste specialists with incineration assets, and logistics-heavy collection contractors. Dominant competitive moves center on capacity expansion ahead of regulatory deadlines and strategic partnerships with industrial zone developers.
Among Qatar-based environmental service groups, Seashore Group and Al Haya Environmental Group occupy positions within the integrated infrastructure tier. Regional specialists Averda and Veolia Qatar anchor the multinational operator segment, leveraging technology transfer and regional logistics networks. Bee'ah Qatar represents the Gulf-based expansion archetype, extending UAE operational models into Qatari municipal and industrial contracts.
| Leading Market Players |
|---|
| Seashore Group |
| Averda |
| Veolia Qatar |
| Al Haya Environmental Group |
| Bee'ah Qatar |
| Power Waste Management & Transport Co. WLL |
| Elite Waste Management |
| Dulsco Qatar |
| Milaha Logistics |
| Others |
Pricing and Supply Chain Analysis
Optical sorting systems using near-infrared spectroscopy are compressing processing costs while simultaneously concentrating supply relationships among European and East Asian equipment vendors. This technology transition reshapes both capital expenditure planning and vendor qualification timelines for Qatari operators seeking to meet Ministry of Municipality and Environment diversion mandates.
Pricing Analysis
Collection and treatment services split between bundled municipal contracts and unbundled commercial waste streams. Pricing stratifies across premium hazardous handling, standard industrial processing, and economy municipal collection tiers based on certification complexity and liability exposure. Cost compression in standard-tier recycling is intensifying because optical sorting automation reduces manual labor headcount. Municipal clients show highest price sensitivity due to fixed budget appropriations, while petrochemical operators in Mesaieed accept premium rates for licensed hazardous capacity.
Supply Chain Analysis
Dual-sourcing requirements for leachate treatment systems and material recovery machinery mandate multi-vendor qualification among German, Italian, and South Korean equipment manufacturers. Raw material dependencies center on high-density polyethylene liners, specialized filtration membranes, and emissions monitoring sensors. Single-source vulnerability concentrates in European suppliers of continuous emissions monitoring infrastructure. Distribution runs through Doha-based engineering procurement contractors who coordinate installation with Ministry licensing timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's waste management sector functions as a stable compounder anchored by construction waste volume visibility from National Vision infrastructure commitments. Regulatory tightening around landfill diversion creates predictable demand expansion for qualified operators.
For Market Incumbents: Acquire licensed landfill airspace and permitted hazardous treatment capacity ahead of Ministry capacity moratoriums. Consolidate smaller collection operators in Al Wakrah and Lusail to defend route density against emerging logistics competitors. Backward integration into transport fleets reduces exposure to fuel cost volatility and driver availability constraints.
For New Entrants and Emerging Players: Begin with digital fleet optimization services for municipal contract renewals specifying technology-enabled service level agreements. White-space targets include reverse logistics for e-waste collection and anaerobic digestion facilities serving Qatar's food service sector. Go-to-market leverage rests on partnerships with General Electricity and Water Corporation for biogas offtake agreements.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale hazardous waste specialists because Ministry licensing constraints restrict new facility approvals and sustain premium pricing for incumbents. Five-to-ten-year viability hinges on circular economy enforcement intensity rather than commodity recycling margins. Monitor Ministry of Municipality and Environment landfill permit issuance velocity as the primary inflection signal for capacity scarcity pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New material recovery facilities in Doha and Al Wakrah secure landfill access permits under National Vision diversion mandates. |
| Backward Integration | In-house transport fleet ownership reduces fuel cost exposure and improves collection route density economics. |
| Technology Licensing | Optical sorting and robotic picker deployments from European vendors lower contamination rates at polyethylene recovery lines. |
| Long-term Supply Agreement | Municipal service contracts with tonnage-diverted incentives align operator margins with Ministry recycling targets. |
| Joint Venture | Partnerships with Mesaieed industrial zone developers anchor hazardous waste volume visibility for incineration investments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged waste management executives, Ministry of Municipality and Environment licensing officers, municipal procurement directors, and petrochemical facility environmental managers. Secondary validation drew from customs import records for specialized equipment, Qatar National Vision policy documents, General Authority of Customs hazardous material filings, and engineering procurement contract databases. Bottom-up facility capacity tallies and top-down waste generation estimates were cross-referenced for triangulation.
Segment-weighting approaches distributed value and volume across service type, waste category, end-user industry, and treatment technology dimensions. Modeled projections applied driver elasticity analysis to construction waste generation forecasts, regulatory enforcement timelines, and circular economy target compliance rates. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Industry-specific inputs included Ministry landfill permit issuance schedules and General Electricity and Water Corporation grid interconnection pathways for energy-from-waste projects.
Several conditions sit outside the modeled scope, including geopolitical disruptions to equipment import timelines, currency fluctuations affecting European machinery costs, and abrupt regulatory relaxation of diversion targets. Forecasts reflect documented assumptions about enforcement continuity and infrastructure investment pacing. Deviation in Ministry licensing velocity or construction project completion rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Construction Waste Management Market
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
India Recycling Market