
 Europe Waste Recycling Services Market | 2026-2036
Europe Waste Recycling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Waste Recycling Services Market Foresight
A shift from fragmented municipal in-house operations toward consolidated outsourced contracts is repositioning procurement patterns across European waste management. Veolia leverages its pan-European treatment infrastructure to secure long-term service agreements with industrial clusters. SUEZ anchors its competitive stance through specialized hazardous waste streams and advanced sorting capabilities. Remondis SE & Co. KG dominates in Central European logistics networks, where its dense collection route density creates cost advantages.
Europe waste recycling services encompass the systematic recovery, processing, and reintroduction of discarded materials into productive supply chains, typically operating through collection networks, mechanical separation lines, and thermal or chemical conversion units that achieve specified purity thresholds for reprocessed outputs. The primary commercial purpose is to reduce virgin material extraction while meeting producer compliance obligations under extended producer responsibility frameworks. Mechanical recycling of plastics and paper currently occupies the largest volume share, though chemical recycling is gaining traction as contamination-tolerant alternatives for complex multi-layer packaging. Collection services sustain the highest revenue visibility due to their contractual annuity structure with municipalities, while treatment margins fluctuate with energy costs and secondary commodity prices.
The EU Green Deal and Circular Economy Action Plan, enforced through ECHA registration requirements and national transpositions of the Waste Framework Directive, bind member states to escalating recycling targets that directly mandate service procurement volumes. Germany's Packaging Act and France's extended producer responsibility schemes impose financial penalties for non-compliance, transferring regulatory risk to contracted service providers. Stakeholders must monitor how the EU's evolving end-of-waste criteria and carbon border adjustment mechanisms reshape the economic viability of domestic recycling versus export-oriented waste flows.
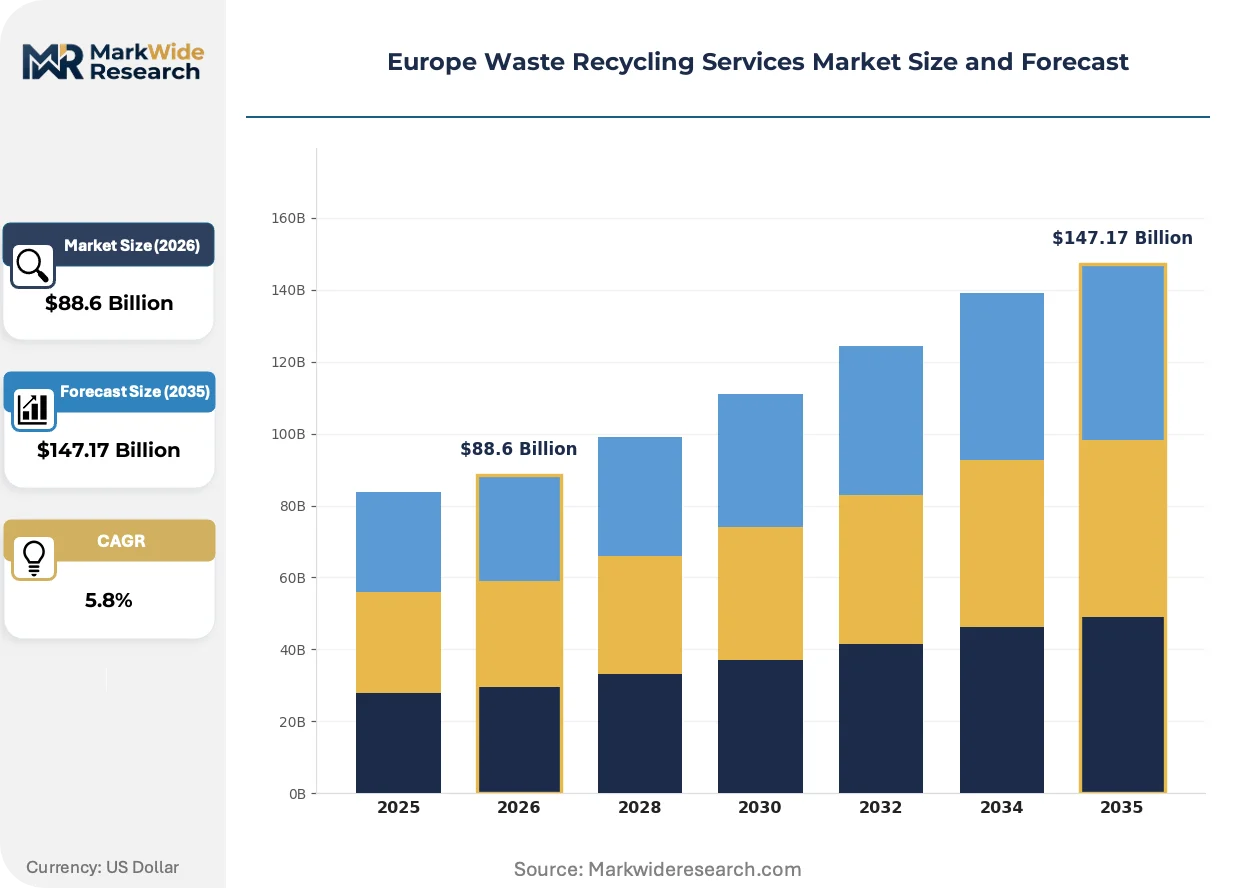
Market Dynamics
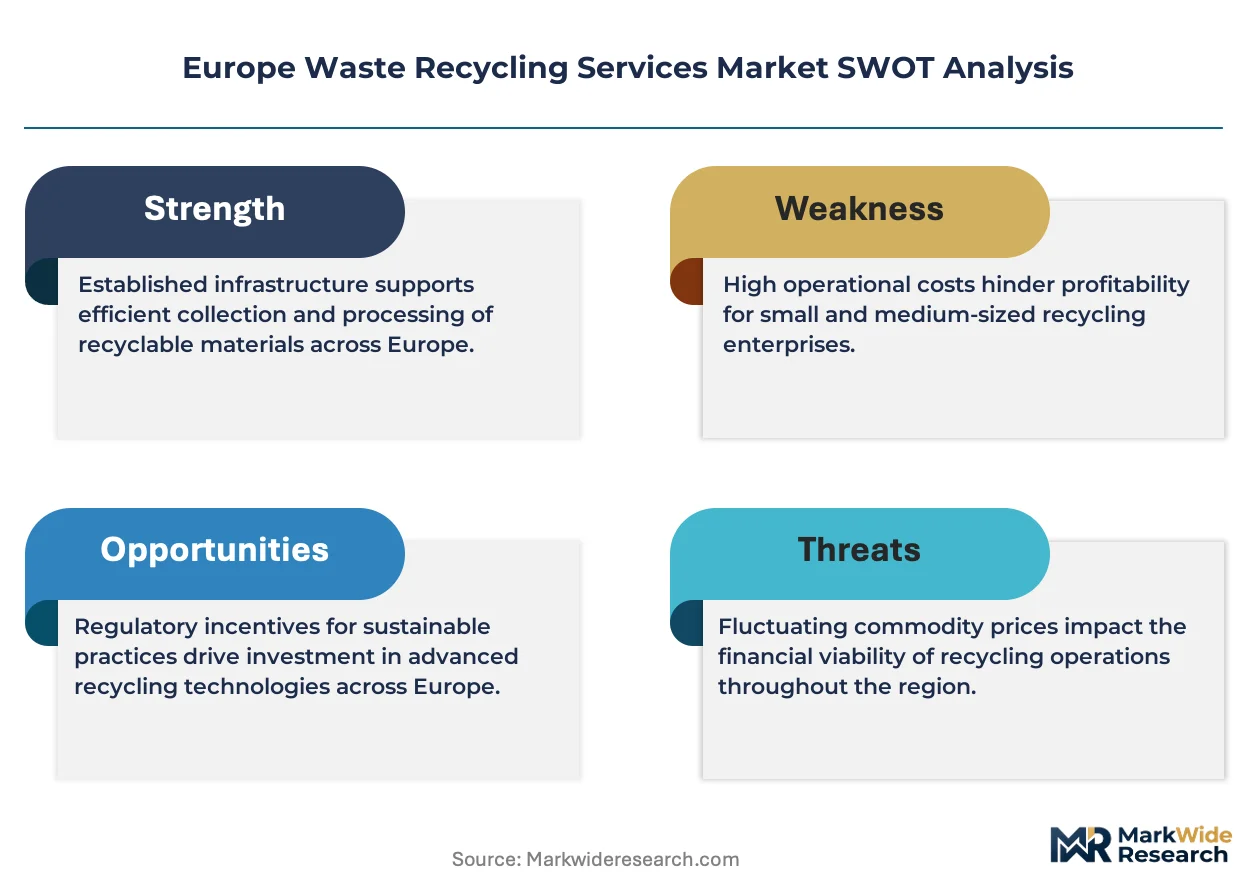
The binding recycled content mandates under the EU Green Deal are compressing virgin material demand while forcing service providers to scale chemical recycling capacity ahead of mechanical processing economics.
Growth Catalysts
- Extended Producer Responsibility Schemes:France's Citeo and Germany's Duales System Deutschland impose compliance fees that fund collection infrastructure expansion. Packaging manufacturers now contract directly with recyclers to meet minimum recycled content thresholds.
- Industrial Cluster Density:The Rhine-Ruhr corridor generates concentrated high-volume waste streams that justify integrated sorting and chemical treatment facilities. Proximity to BASF and Covestro operations enables closed-loop polymer recovery.
- Chemical Recycling Scale-Up:Pyrolysis and gasification technologies tolerate contaminated multi-layer packaging that mechanical lines reject. Investment flows toward Rotterdam-Antwerp port zones with existing petrochemical feedstock integration.
Market Restraints
- Natural Gas Price Volatility:Thermal treatment processes consume substantial energy inputs. German and Dutch facilities face margin compression when TTF benchmark prices spike above seasonal norms.
- Secondary Commodity Price Cycles:Recycled PET and HDPE pellet values track virgin polymer spreads. Chinese import restrictions on contaminated bales have destabilized European mixed plastic offtake agreements.
- Feedstock Quality Heterogeneity:Source-separated collection systems vary by municipality. Sorting lines require constant recalibration for film versus rigid packaging ratios, degrading throughput yields.
Strategic Opportunities
- Central European Logistics Gaps:Poland and Czech Republic collection networks remain fragmented relative to Western European density. Route optimization platforms can consolidate rural municipal contracts.
- Carbon Border Adjustment Mechanism:The EU CBAM imposes embodied carbon costs on imported virgin materials. Domestic recycling gains cost parity against Turkish and Southeast Asian resin imports.
- Digital Waste Tracking Integration:Blockchain-verified chain-of-custody systems converge with smart bin sensor networks. Real-time fill-level data enables dynamic collection scheduling for commercial waste generators.
Industry Challenges
- Chemical Process Engineering Talent Scarcity:Pyrolysis reactor operation and catalyst management require specialized petrochemical expertise. European technical universities produce insufficient graduates for scaled plant deployment.
- End-of-Waste Certification Timelines:ECHA evaluates reprocessed material applications case-by-case. Regulatory uncertainty delays offtake contracts for novel chemical recycling outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Waste Recycling Services Market |
| Market Size in 2026 | $88.6 Billion |
| Market Size in 2035 | $147.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Sorting, Treatment, Landfilling Material Type: Plastic, Glass, Metal, Paper End User: Municipalities, Industries, Construction, Retail Technology: Mechanical, Thermal, Biological, Chemical |
| Companies Covered | Veolia, SUEZ, Remondis SE & Co. KG, Biffa plc, FCC Environment, Paprec Group, Ragn-Sells Group, Renewi, Fortum Oyj, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Waste Recycling Services Market Shifts & Advancements
Technology maturation and compliance architecture are compressing the gap between collection economics and treatment value capture across European waste networks.
Near-infrared spectroscopy paired with robotics is overtaking manual sorting stations in mixed waste facilities. French and Italian MRF operators deploy AI-guided picking arms to extract film and flexibles at 120 picks per minute. The displacement of labor-intensive pre-sorting is compressing facility breakeven thresholds below 50,000 tonnes annual throughput.
REACH registration requirements for recycled content additives are tightening purity specifications for food-contact applications. EFSA safety assessments now cover legacy chemical migration from post-consumer feedstocks. German beverage packaging producers are reformulating bottle designs to eliminate problematic pigments that complicate reprocessing certification.
Consolidated service contracts are displacing fragmented municipal in-house operations. Dutch and Belgian intermunicipal authorities bundle collection, sorting, and residue treatment into single-source agreements. Industrial clusters in Belgium's Port of Antwerp-Bruges now procure integrated waste-to-feedstock services rather than transactional disposal arrangements.
Europe Waste Recycling Services Market Segmentation
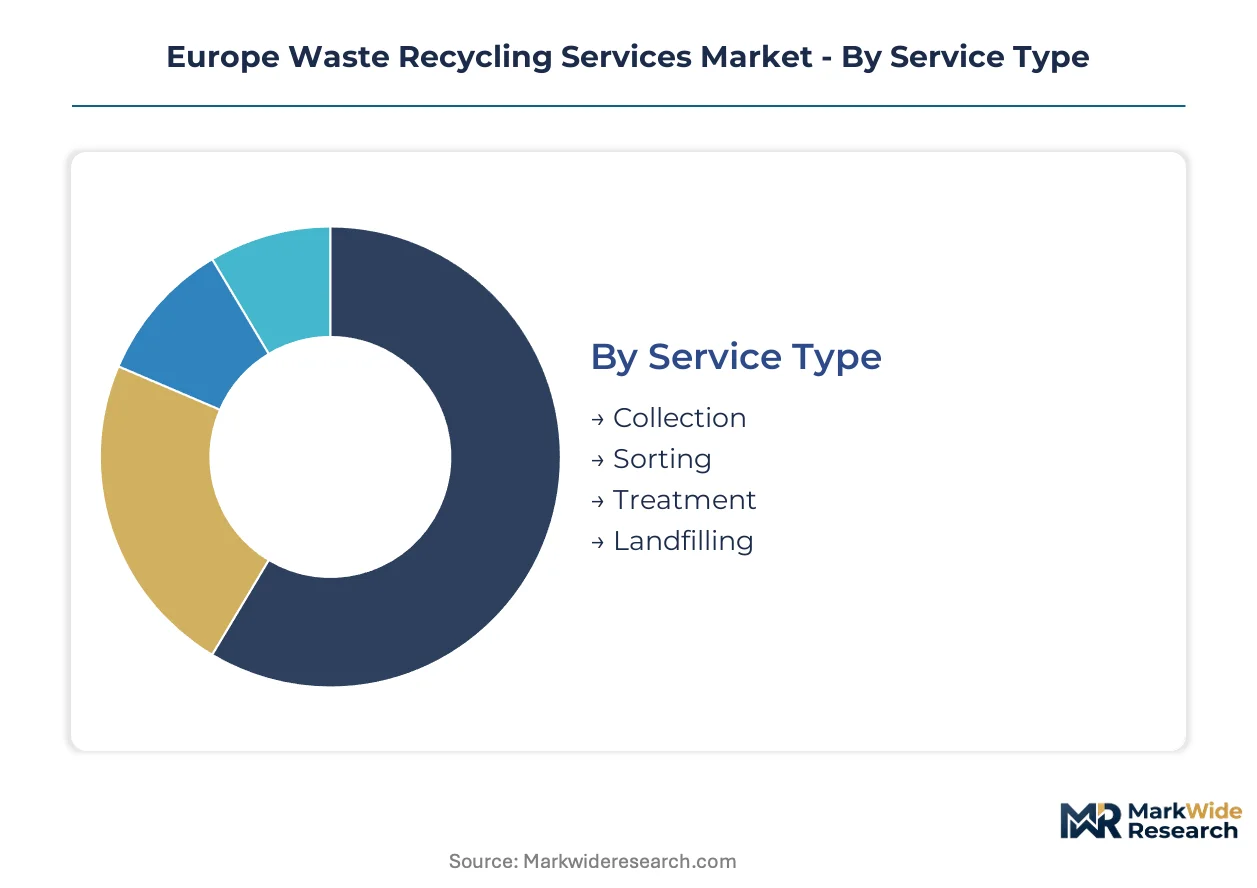
Service procurement patterns across European waste management diverge sharply by contract structure, material contamination levels, and regulatory compliance intensity. Understanding how these dimensions fragment demand reveals where margin pools concentrate and which technology investments align with buyer willingness to pay.
Service Type:
Municipal and industrial buyers differentiate primarily by contract duration risk allocation and capital exposure preferences.
- Collection:Dense route networks in Germany's Rhine-Ruhr corridor and the Netherlands Randstad generate annuity revenue streams with 5-15 year concession terms. French intermunicipal syndicates now bundle collection with digital tracking mandates, compressing operator margins through performance penalties for missed pickups.
- Sorting:Material recovery facilities in Belgium's Port of Antwerp-Bruges cluster process 300,000+ tonnes annually, achieving economies that justify AI-guided robotics. Proximity to petrochemical feedstock infrastructure enables direct polymer purification for food-contact applications under EFSA safety assessments.
- Treatment:Thermal and chemical conversion units command premium pricing for hazardous industrial residues.
- Landfilling:Residual disposal capacity concentrates in Eastern European member states with lower landfill diversion targets.
Volume sits with Collection; growth tilts toward Sorting.
Material Type:
Contamination tolerance and end-of-waste certification complexity separate high-margin from commodity-grade material streams.
- Plastic:Multi-layer packaging and flexibles drive chemical recycling investments in Rotterdam-Antwerp port zones. Pyrolysis operators tolerate feedstock heterogeneity that mechanical lines reject, though ECHA end-of-waste timelines delay offtake contract finalization.
- Paper:Containerboard mills in Germany's industrial corridor source post-consumer OCC bales with strict prohibitions on wax coatings and adhesives. China's import restrictions on contaminated fibre have redirected Southeast Asian trade flows toward European domestic pulping capacity.
- Metal:Ferrous scrap trades on transparent LME-linked benchmarks with established automotive offtake channels.
- Glass:Colour-sorted cullet commands packaging manufacturer premiums for amber and flint specifications.
Revenue concentrates in Plastic; expansion accelerates fastest in Paper as packaging EPR schemes mature.
End User:
Compliance obligation intensity and procurement sophistication stratify buyer segments from transactional to strategic partnerships.
- Industries:BASF and Covestro operations in Ludwigshafen procure closed-loop polymer recovery with carbon footprint verification under EU Green Deal reporting frameworks. Chemical sector clusters negotiate 10-year feedstock supply agreements that transfer recycling technology risk to service providers.
- Municipalities:Dutch and Belgian intermunicipal authorities consolidate fragmented in-house operations into single-source contracts bundling collection through residue treatment. Performance metrics now incorporate kg CO2e per tonne diverted rather than simple tonnage thresholds.
- Construction:Demolition waste streams require specialized inert material processing for aggregate reuse certification.
- Retail:French Citeo compliance fees fund collection infrastructure for packaging waste from large-format grocery distribution.
Contract value pools deepest with Industries; municipal procurement volumes are expanding most quickly under EPR mandate expansion.
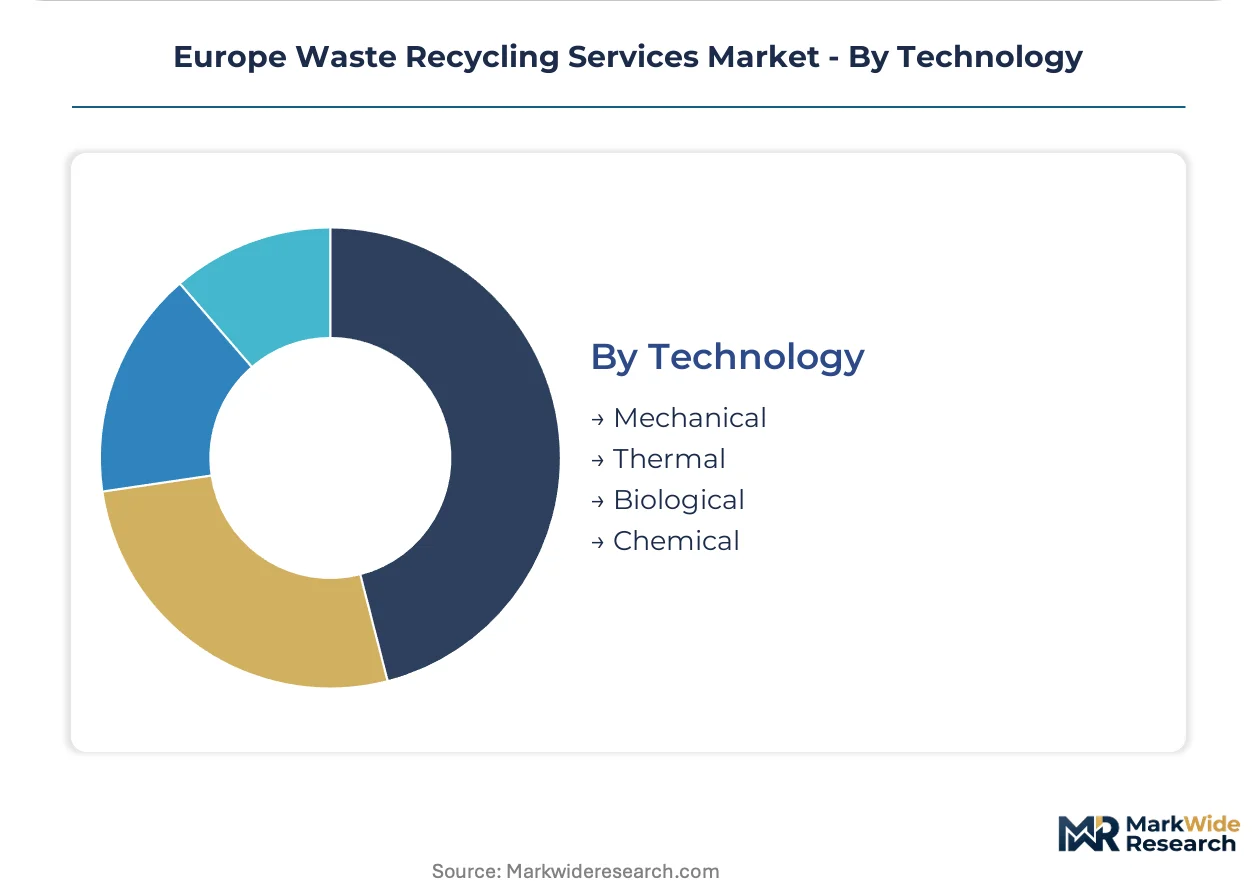
Technology:
Capital intensity and feedstock flexibility requirements determine which technology pathways attract scaled investment versus niche application.
- Mechanical:Near-infrared spectroscopy and robotic picking arms displace manual pre-sorting in French and Italian MRFs, compressing breakeven thresholds below 50,000 tonnes annual throughput. REACH registration requirements for recycled content additives constrain food-contact applications to high-purity mono-material streams.
- Chemical:Pyrolysis and gasification units in Rotterdam-Antwerp corridors integrate with existing petrochemical infrastructure for polymer feedstock replacement. Natural gas price volatility at TTF benchmarks directly compresses thermal process margins during winter demand spikes.
- Thermal:Waste-to-energy plants face carbon accounting scrutiny under EU CBAM implementation for electricity export.
- Biological:Anaerobic digestion capacity concentrates in agricultural regions with captive organic waste supply.
Installed base dominates Mechanical; capital deployment is concentrating fastest in Chemical as contamination-tolerant alternatives mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's industrial Rhine-Ruhr corridor, where dense manufacturing clusters generate high-volume waste streams requiring integrated treatment solutions. France and Italy follow with expanding outsourced municipal contracts. Eastern European markets present logistics consolidation opportunities.
Germany
Industrial waste volumes from BASF and Covestro operations in Ludwigshafen drive demand for closed-loop polymer recovery services. The Packaging Act imposes strict extended producer responsibility compliance fees that fund collection infrastructure expansion. The Rhine-Ruhr corridor hosts integrated sorting and chemical treatment facilities serving petrochemical feedstock replacement markets.
France
Citeo compliance schemes channel packaging manufacturer fees into collection network expansion across intermunicipal syndicates. EFSA safety assessments for food-contact recycled content applications constrain mechanical reprocessing specifications. The Port of Antwerp-Bruges adjacent zone attracts pyrolysis investment for multi-layer packaging conversion.
Netherlands
Randstad urban density supports annuity revenue structures for collection concessionaires with 5-15 year contract terms. The EU Green Deal's carbon border adjustment mechanism enhances domestic recycling cost parity against virgin resin imports. Rotterdam-Antwerp port zones integrate chemical recycling with existing petrochemical infrastructure.
Italy
Municipal outsourcing accelerates as fragmented in-house operations consolidate under single-source service agreements. REACH registration requirements for recycled content additives tighten purity specifications for mechanical reprocessing lines. Northern Italian MRF operators deploy AI-guided robotics for film and flexibles extraction at commercial scale.
Poland
Collection network fragmentation relative to Western European density creates route optimization opportunities for logistics platforms. Lower landfill diversion targets concentrate residual disposal capacity in Eastern European member states. Industrial clusters near the German border generate cross-border waste service procurement demand.
Europe Waste Recycling Services Market Competitive Landscape
Capacity expansion dominates the current landscape as service providers scale chemical recycling infrastructure ahead of mechanical processing economics. The market exhibits tiered consolidation with pan-European treatment networks, specialized hazardous waste operators, and regional logistics specialists coexisting. Three archetypes define positioning: integrated infrastructure owners leveraging concession portfolios, technology specialists commanding premium pricing for complex feedstocks, and route-density optimizers capturing municipal contract economics. M&A activity and strategic partnerships between recyclers and petrochemical offtakers represent the dominant competitive vectors.
Among pan-European infrastructure owners, Veolia and SUEZ occupy positions defined by treatment network scale and long-term service agreement structures. Remondis SE & Co. KG exemplifies the logistics-optimization archetype through dense Central European collection route density. These three entities represent distinct strategic postures within a market where regulatory compliance intensity and feedstock access determine competitive viability.
| Leading Market Players |
|---|
| Veolia |
| SUEZ |
| Remondis SE & Co. KG |
| Biffa plc |
| FCC Environment |
| Paprec Group |
| Ragn-Sells Group |
| Renewi |
| Fortum Oyj |
| Others |
Supply & Pricing Matrix
Chemical recycling scale-up at Rotterdam-Antwerp port zones simultaneously compresses mechanical processing margins and concentrates supply power among integrated petrochemical off-takers. EU Green Deal recycled content mandates force service providers to absorb technology transition costs while long-term concession contracts lock in municipal collection pricing.
Pricing Analysis
Performance-guarantee bundling separates premium chemical recycling contracts from unbundled mechanical sorting arrangements. Contract structures stratify across long-term offtake agreements, annuity-based municipal concessions, and spot-market residue disposal. Price differentiation hinges on EFSA food-contact certification tier and guaranteed carbon footprint verification. Cost compression in mechanical sorting intensifies because AI-guided robotics deployment spreads fixed costs across fewer operators. Municipal procurement teams exhibit highest price sensitivity, while BASF and Covestro operations accept premium positioning for closed-loop polymer recovery with embedded compliance risk transfer.
Supply Chain Analysis
Single-source vulnerability sits with natural gas feedstock dependence for pyrolysis operations at Rotterdam-Antwerp port zones. Primary supply concentration centers on Germany, the Netherlands, and Belgium for integrated treatment infrastructure. Raw material dependencies rest on post-consumer plastic bales, pyrolysis catalysts, and polymer purification solvents. Tariff exposure on imported virgin resin feeds from Turkish and Southeast Asian sources threatens margin stability under EU CBAM implementation. Distribution runs through dense Rhine-Ruhr corridor logistics networks, port-centric chemical clusters, and intermunicipal syndicate bundling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe waste recycling services occupy a technology-transition phase where chemical recycling displaces mechanical processing for contaminated multi-layer packaging streams.
For Market Incumbents: Deploy concession portfolio extension to anchor long-term revenue visibility against municipal outsourcing acceleration. Secure pyrolysis capacity ahead of ECHA end-of-waste certification timelines to capture premium positioning. Integrate backward into polymer purification to defend margin position when natural gas price volatility spikes at TTF benchmarks. For New Entrants and Emerging Players: Digital route-optimization platforms offer the most penetrable entry vector for fragmented Polish and Czech Republic collection networks. Target intermunicipal syndicates in Italy and France with unbundled sorting services rather than integrated collection-treatment bundles. Pursue white-label chemical recycling partnerships with Rotterdam-Antwerp petrochemical infrastructure owners to bypass capital-intensive reactor construction. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by petrochemical majors seeking circular feedstock security. Five-to-ten-year viability hinges on chemical recycling output achieving cost parity against virgin resin under EU CBAM carbon pricing. Monitor ECHA end-of-waste certification velocity as the critical inflection signal for offtake contract finalization and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Pyrolysis Capacity Buildout | Rotterdam-Antwerp port zones integrate chemical recycling with BASF and Covestro polymer feedstock replacement demand. |
| AI-Guided Robotics Deployment | French and Italian MRF operators achieve sub-50,000-tonne breakeven thresholds through labor displacement. |
| Long-Term Concession Extension | Dutch and Belgian intermunicipal syndicates bundle collection through residue treatment into single-source agreements. |
| Backward Integration into Sorting | Veolia and SUEZ capture margin from municipal collection through direct polymer purification for food-contact applications. |
| Digital Tracking Integration | Blockchain-verified chain-of-custody converges with smart bin networks for dynamic commercial waste scheduling. |
Research Methodology
Multi-period observation of EPR scheme fee structures, chemical recycling capacity announcements, and municipal concession award patterns anchored the trend analysis, supplemented by interviews with waste treatment plant managers, municipal procurement officers, petrochemical feedstock buyers, and ECHA regulatory affairs specialists. Secondary validation drew from EU Waste Framework Directive transposition documents, national packaging act filings, EFSA safety assessment registers, and Cefic chemical industry reports. Bottom-up service contract value aggregation triangulated against top-down regulatory mandate volume projections.
Input-output matrices mapped collection route density, sorting throughput yields, and treatment conversion rates across service type, material contamination level, and end-user compliance intensity dimensions. CAGRs were derived from regulatory mandate trajectories under EU Green Deal binding targets, cross-referenced with industrial cluster waste generation coefficients and technology deployment timelines. Forecast inputs incorporated natural gas price volatility assumptions at TTF benchmarks and ECHA end-of-waste certification probability distributions.
The model holds under stable EU Green Deal enforcement and gradual EPR scheme expansion; deviation in regulatory rollback or feedstock quality collapse would shift trajectory bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Europe Plastic Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Middle-East and Africa Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
India Recycling Market