
 UAE Industrial Waste Management Market | 2026-2036
UAE Industrial Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Industrial Waste Management Market Analytics
Aftermarket service revenue from industrial byproduct recovery is reconfiguring margin pools across the UAE waste management value chain. Bee'ah leverages its integrated landfill-gas capture infrastructure to dominate Sharjah's industrial corridor. Veolia Middle East anchors its position through long-term service contracts with downstream oil operators in Jebel Ali. Averda differentiates via specialized hazardous waste logistics serving Abu Dhabi's Ruwais refining complex.
Industrial waste management encompasses the systematic collection, transport, treatment, and final disposition of non-domestic refuse streams, with hazardous fractions requiring stabilization at temperatures exceeding 1,100°C prior to secure landfill placement. The primary purpose is environmental compliance coupled with resource recovery from metallurgical slag, spent solvents, and hydrocarbon-contaminated soils. Treatment services command the largest value share as pre-disposal processing intensifies under tighter effluent standards. Recycling is gaining traction fastest among manufacturing verticals seeking to offset virgin raw material costs. Oil and gas waste streams represent the most entrenched segment, though margin compression from commoditized disposal is pushing operators toward higher-value recovery technologies.
MOHAP and the Emirates Authority for Standardization and Metrology enforce hazardous waste manifesting and landfill liner specifications that directly shape contractor qualification requirements and capital deployment timelines. The UAE's federal circular economy policy framework and Dubai's Industrial Strategy 2030 are accelerating permitting for integrated treatment facilities that combine incineration with energy recovery. Stakeholders must weigh long-term service contracting against in-house treatment investments as regulatory thresholds tighten and feedstock quality becomes more variable.
Market Dynamics
Federal landfill diversion mandates under MOHAP's updated waste management regulations are forcing industrial generators to restructure disposal contracts toward integrated treatment services, compressing margins for pure-play collection operators while elevating capital requirements for thermal processing infrastructure.
Growth Catalysts
- Emirates Authority for Standardization and Metrology specifications:Stringent liner and leachate standards are disqualifying legacy landfill operators, consolidating contract awards toward integrated service providers with captive treatment capacity.
- Abu Dhabi petrochemical cluster expansion:Ruwais refining complex output growth is generating concentrated hazardous waste volumes that justify dedicated incineration with energy recovery investments.
- Plasma gasification:This high-temperature waste-to-syngas process is penetrating oil and gas sludge treatment as operators seek to offset virgin fuel costs and meet circular economy targets.
Market Restraints
- Specialized refractory material costs:Thermal treatment vessel lining replacement cycles are compressing unit economics for rotary kiln operators facing alumina-chrome price volatility.
- Sharjah corridor supply concentration:Bee'ah's integrated landfill-gas infrastructure dominance limits third-party access to feedstock aggregation and grid injection revenue streams.
- MEE hazardous waste classification alignment:Pending harmonization with UAE federal categories is creating manifesting friction for cross-emirate waste movements.
Strategic Opportunities
- Dubai Industrial Strategy 2030 permitting acceleration:Fast-track approvals for combined heat-and-power waste facilities are opening greenfield development slots in Jebel Ali free zone corridors.
- Spent catalyst metal recovery:Hydrotreating residue from Ruwais refineries contains recoverable vanadium and nickel fractions currently undervalued in disposal contracts.
- Blockchain-secured waste tracking:Integration of distributed ledger manifesting with MOHAP reporting systems is creating first-mover advantage for logistics platforms serving multi-site generators.
Industry Challenges
- High-temperature process engineering talent:Incinerator operations and maintenance expertise is concentrated among expatriate specialists with limited local training pipeline capacity.
- Integrated facility capex timelines:Combined mechanical-biological treatment with energy recovery requires 36-48 month deployment cycles against tightening regulatory compliance deadlines.
- Legacy ERP integration:Real-time waste stream characterization sensors are generating data volumes that overwhelm existing generator inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Industrial Waste Management Market |
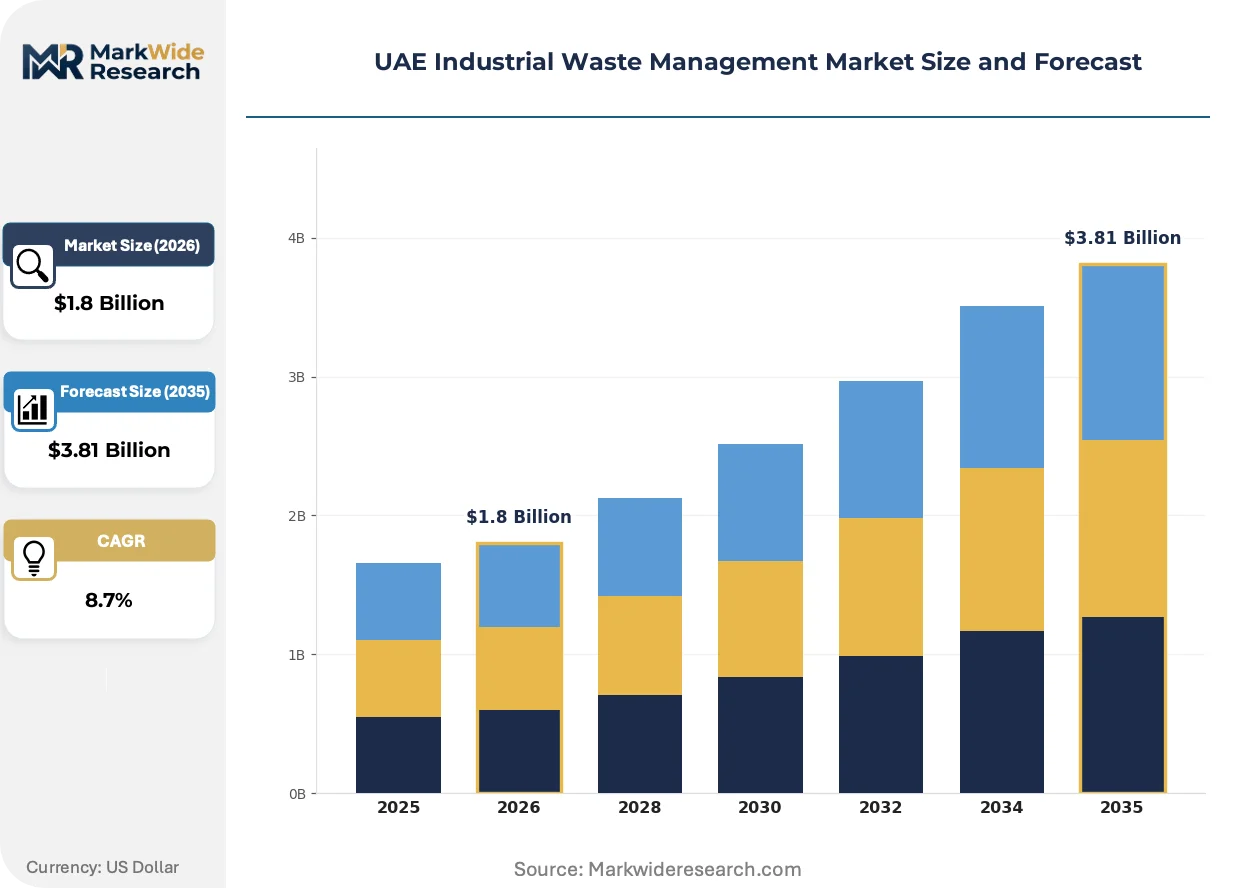
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Recycling, Disposal Industry Vertical: Manufacturing, Construction, Oil & Gas, Chemicals Waste Type: Hazardous, Non-Hazardous, Electronic, Organic Technology: Incineration, Anaerobic Digestion, Landfilling, Composting |
| Companies Covered | Averda, Sembcorp Industries, Bee'ah, Adgeco Group, Enviroserve, Tadweer, Dulsco Environment, Greenmountains, Veolia Middle East, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Industrial Waste Management Market Evolving Landscape
Thermal treatment technology maturation and digital traceability mandates are compressing the traditional separation between waste logistics and resource recovery value pools, creating new service integration models across the UAE's industrial corridors.
Advanced plasma arc gasification is collapsing the distinction between hazardous waste destruction and syngas fuel production. Abu Dhabi National Oil Company downstream operators are piloting mobile units for drilling mud processing at remote wellpad locations. This distributed treatment model is collapsing centralized incineration hub economics by eliminating double-handling transport costs for low-density sludge streams.
MOHAP's 2024 hazardous waste manifest digitization mandate is restructuring contractor qualification protocols. Real-time GPS-tracked transport containers with automated weight verification are becoming mandatory for cross-emirate movements. Petrochemical clusters in Ruwais and Jebel Ali are responding by consolidating vendor panels to operators with certified telematics infrastructure, compressing the approved contractor base by approximately half.
Long-term service contracting with guaranteed residue recovery volumes is displacing spot-market disposal arrangements among free zone manufacturers. Dubai's industrial parks are witnessing contract tenures extending from annual to five-year frameworks with indexed pricing. This shift is most pronounced among automotive coating facilities in Dubai Industrial City seeking to lock in solvent waste processing capacity against tightening environmental enforcement timelines.
UAE Industrial Waste Management Market Segmentation
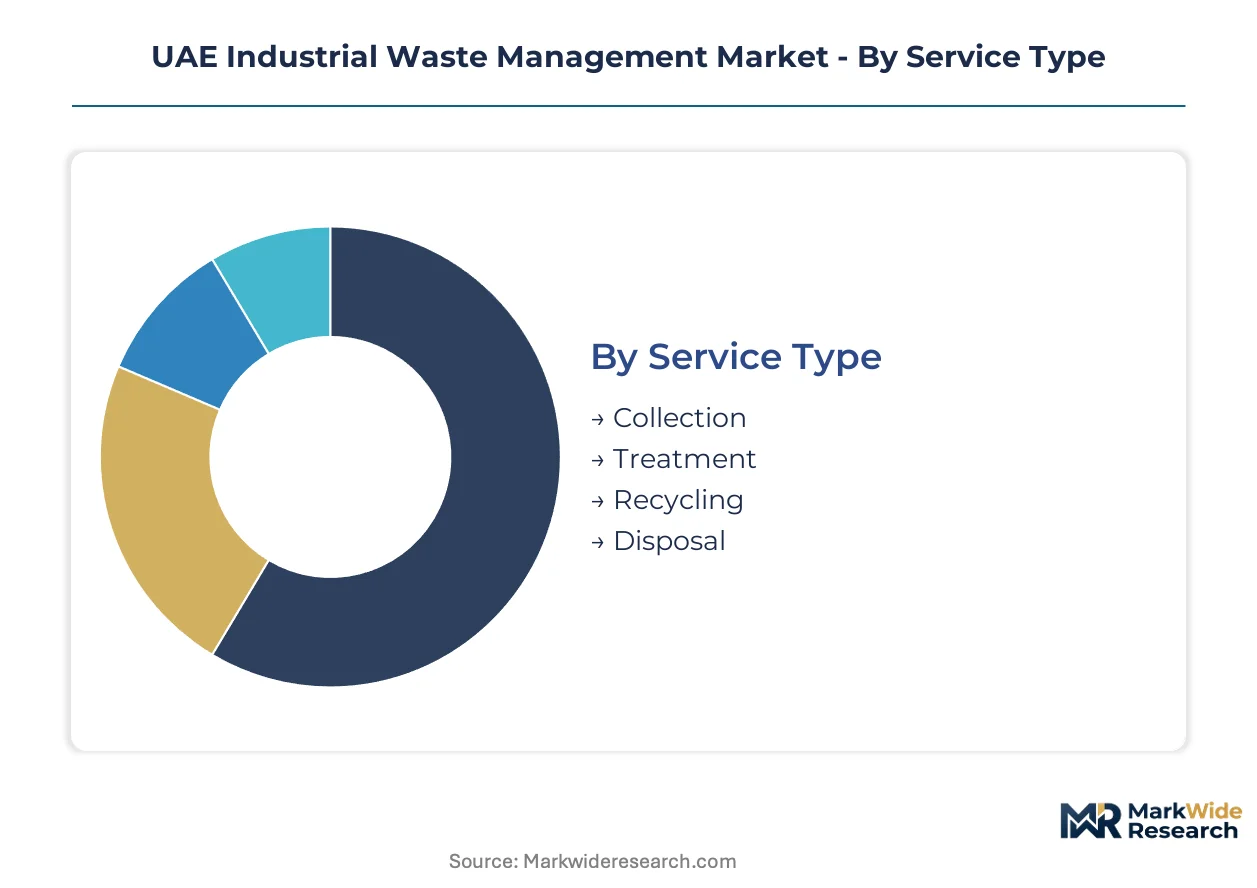
Service complexity and regulatory stringency vary sharply across waste streams in the UAE, requiring operators to match capital intensity with specific generator requirements. Segmentation reveals where thermal processing infrastructure commands premium pricing versus commoditized collection routes.
Service Type:
Mature collection networks coexist with emerging high-treatment services as landfill diversion mandates reshape contract structures.
- Collection:Fleet-based logistics operations dominate Sharjah and Dubai corridors, with GPS-tracked container deployment now mandatory under MOHAP's digitized manifesting rules. Pure-play haulers face margin compression as generators bundle services with treatment providers.
- Treatment:Thermal and chemical stabilization processes command the largest value share, with rotary kiln incineration and plasma gasification units concentrated at Ruwais and Jebel Ali. Abu Dhabi petrochemical clusters justify captive energy recovery investments.
- Recycling:Metallurgical slag reprocessing and solvent recovery are gaining traction among Dubai Industrial City manufacturers seeking virgin material cost offsets.
- Disposal:Secure landfill placement now requires pre-treatment certification, limiting revenue to operators with integrated upstream capabilities.
Treatment handles the majority of throughput; recycling is expanding most quickly on share.
Industry Vertical:
Cost tier differentiation separates capital-intensive hazardous streams from volume-driven construction debris.
- Oil & Gas:Drilling muds, produced water sludge, and contaminated soils generate the highest per-tonne service values, with ADNOC downstream operators piloting distributed plasma units at remote wellpads.
- Chemicals:Spent catalysts and solvent residues from Ruwais refineries contain recoverable vanadium and nickel fractions, creating metal recovery revenue layers atop disposal fees.
- Manufacturing:Automotive coating facilities in Dubai Industrial City are extending contract tenures to five-year frameworks with indexed pricing for solvent waste processing.
- Construction:Inert debris volumes are largest by tonnage but command lowest unit economics, with diversion targets pushing aggregates toward crushing and reuse applications.
Oil & Gas contributes the highest margin per tonne; chemicals is climbing the fastest on value-added recovery penetration.
Waste Type:
Regulatory classification rigor creates distinct handling protocols across the hazard spectrum.
- Hazardous:Stabilization temperatures exceeding 1,100°C are mandated prior to secure landfill placement, with manifesting friction from pending MEE harmonization complicating cross-emirate movements.
- Non-Hazardous:Mechanical-biological treatment with energy recovery is displacing direct landfill for commercial and industrial mixed streams under federal diversion targets.
- Electronic:Precious metal recovery from printed circuit boards is emerging as a specialized sub-segment serving Dubai's technology manufacturing free zones.
- Organic:Food processing residues from UAE's agribusiness sector are feeding anaerobic digestion facilities with combined heat-and-power output.
Hazardous waste commands the strictest compliance overhead; organic streams are gaining share fastest on circular economy policy alignment.
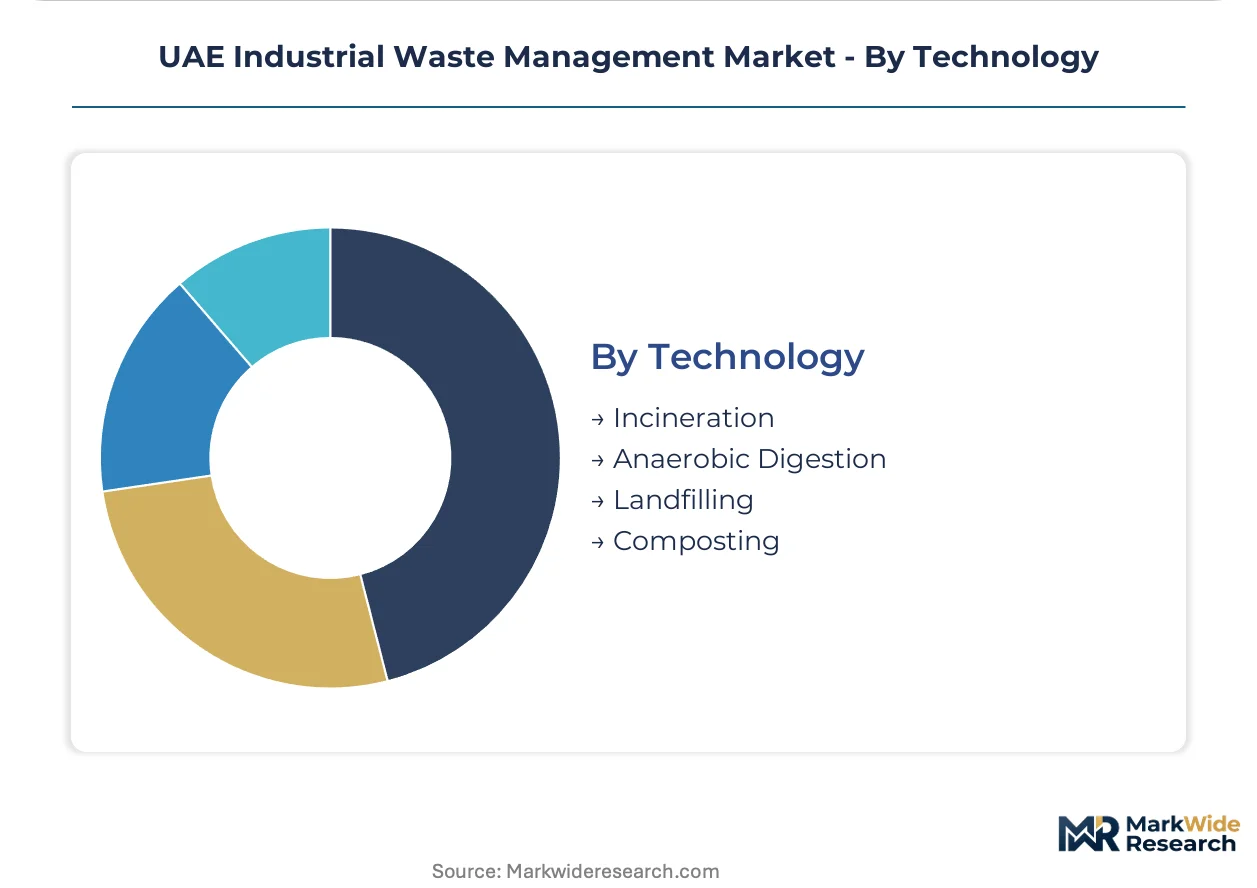
Technology:
Volume scale separates centralized hub economics from distributed unit deployment.
- Incineration:Rotary kiln and grate systems anchor thermal destruction capacity, though refractory material cost volatility is compressing unit economics for operators facing alumina-chrome price swings.
- Plasma Gasification:High-temperature syngas production is penetrating oil and gas sludge treatment as operators seek to offset virgin fuel costs and meet circular economy targets.
- Anaerobic Digestion:Biogas capture from organic industrial streams is scaling in Sharjah's food processing corridor, with grid injection revenue limited by Bee'ah's landfill-gas infrastructure dominance.
- Landfilling:Engineered cell construction with composite liner systems is now mandatory under Emirates Authority for Standardization and Metrology specifications, disqualifying legacy operators.
- Composting:Aerobic decomposition of non-hazardous organic waste serves agricultural off-take markets with lower capital barriers than thermal alternatives.
Incineration retains the largest installed base; plasma gasification is ascending fastest on technology maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Sharjah's industrial corridor show the highest price sensitivity due to landfill-gas infrastructure concentration, while Abu Dhabi petrochemical operators absorb premium thermal treatment costs to meet diversion mandates.
Dubai
Jebel Ali free zone manufacturing hubs generate concentrated solvent waste volumes from automotive coating facilities. Dubai Industrial Strategy 2030 fast-tracks permitting for combined heat-and-power waste facilities. Dubai Industrial City contract tenures are extending from annual to five-year frameworks with indexed pricing.
Abu Dhabi
ADNOC downstream operations produce drilling muds and produced water sludge requiring high-temperature stabilization. MOHAP's updated federal waste management regulations mandate landfill diversion targets for industrial generators. Ruwais refining complex expansion justifies dedicated incineration with energy recovery investments.
Sharjah
Bee'ah's integrated landfill-gas capture infrastructure dominates feedstock aggregation and grid injection revenue streams. Emirates Authority for Standardization and Metrology specifications disqualify legacy landfill operators without composite liner systems. Sharjah's food processing corridor scales anaerobic digestion facilities with biogas capture.
Northern Emirates
Ras Al Khaimah and Fujairah manufacturing bases generate lower hazardous waste volumes but face transport cost premiums to centralized treatment hubs. Federal circular economy policy framework accelerates permitting for integrated treatment facilities. Northern Emirates industrial parks rely on third-party logistics operators with certified telematics infrastructure for cross-emirate manifesting.
UAE Industrial Waste Management Market Competitive Landscape
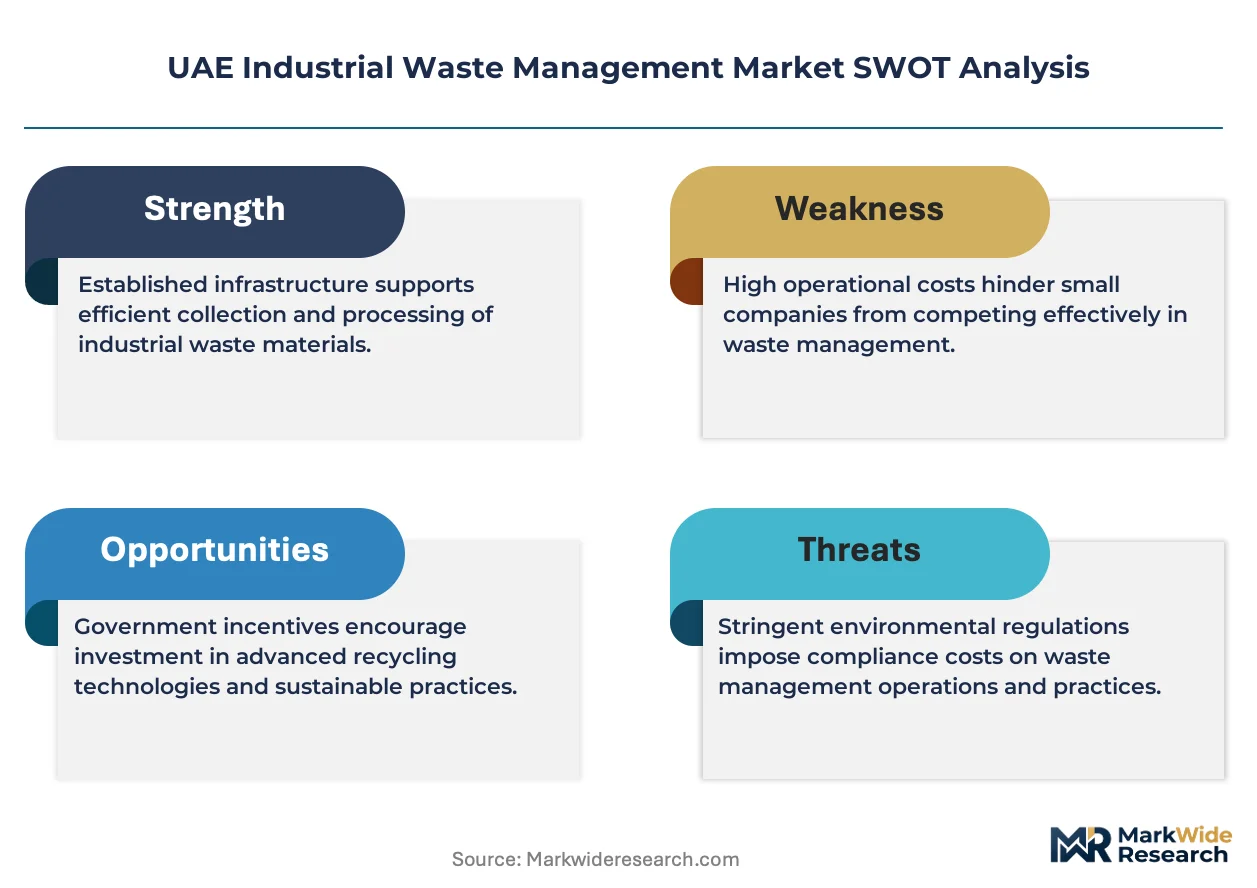
Capability concentration sits with integrated service providers possessing captive thermal processing infrastructure; scale advantage sits with fleet-based logistics operators covering multi-emirate collection routes. The market structure reflects a two-tier dynamic where pure-play haulers face margin compression against bundled service contracts. Strategic archetypes include landfill-gas-integrated regional champions, oil and gas-focused thermal specialists, and hazardous waste logistics operators serving petrochemical clusters. Dominant competitive moves encompass long-term service contracting extensions and vertical integration into energy recovery assets.
Within the integrated infrastructure tier, Bee'ah exemplifies landfill-gas capture dominance through its Sharjah corridor concentration. Averda and Veolia Middle East occupy positions as thermal treatment specialists anchored to Abu Dhabi and Dubai petrochemical demand respectively. These three operators represent the spectrum from regional captive infrastructure to multinational service contracting models.
| Leading Market Players |
|---|
| Averda |
| Sembcorp Industries |
| Bee'ah |
| Adgeco Group |
| Enviroserve |
| Tadweer |
| Dulsco Environment |
| Greenmountains |
| Veolia Middle East |
| Others |
Value Network & Pricing Analysis
Undercapacity in plasma gasification units across the Northern Emirates is compressing spot-market rates for thermal treatment while elevating long-term contract premiums for integrated providers with captive energy recovery assets. This utilization asymmetry between Sharjah's landfill-gas-saturated corridor and Abu Dhabi's petrochemical cluster is reshaping how generators structure procurement and how operators deploy capital.
Pricing Analysis
Aftermarket service revenue from residue metal recovery and extended treatment contracts now drives lifetime value for thermal processing operators. Contract structures stratify across premium tiers for hazardous waste with energy recovery guarantees, standard tiers for pre-treated industrial streams, and economy tiers for non-hazardous commercial volumes. Cost compression in pure-play collection services is intensifying because generators bundle logistics with treatment under MOHAP's digitized manifesting rules. Automotive coating facilities in Dubai Industrial City show highest price sensitivity due to solvent waste commoditization, while ADNOC downstream operators absorb premium thermal costs to meet federal diversion mandates.
Supply Chain Analysis
Refractory material sourcing exposure between China and South Africa dominates supply chain risk for rotary kiln operators facing alumina-chrome price volatility. Thermal treatment vessel fabrication draws from Germany, South Korea, and the UAE's own steel fabrication base. Plasma torch electrodes and specialized ceramic liners rest on Japanese and US component suppliers. Single-source vulnerability concentrates in high-temperature sensor arrays required for MOHAP's real-time emissions monitoring. Distribution runs through Jebel Ali free zone logistics corridors for equipment import, with localized assembly at Ruwais and Dubai Industrial City treatment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE industrial waste market reads as a service-attach opportunity where metal recovery revenue layers and long-term treatment contracts are expanding faster than standalone disposal hardware sales.
For Market Incumbents: Build regulatory compliance moats through MOHAP-certified telematics infrastructure that locks in multi-site generator panels. Incumbents should secure captive refractory supply agreements to offset alumina-chrome price volatility threatening rotary kiln economics. Vertical integration into plasma gasification technology protects against emerging entrants with distributed treatment models. Channel control over Sharjah's landfill-gas grid injection revenue streams limits third-party feedstock aggregation. For New Entrants and Emerging Players: Establish a beachhead in blockchain-secured waste tracking platforms serving Northern Emirates manufacturers lacking certified manifesting infrastructure. The most penetrable segment lies in spent catalyst metal recovery from Ruwais refineries, where vanadium and nickel fractions remain undervalued in incumbent disposal contracts. A targeted go-to-market angle combines mobile plasma units for remote wellpad drilling mud processing with guaranteed syngas offtake agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers with captive thermal processing infrastructure and long-term ADNOC service contracts. Five-to-ten year viability favors operators combining energy recovery assets with hazardous waste treatment permits under tightening federal diversion thresholds. Acquisition targets should display certified telematics integration and cross-emirate logistics capabilities. The critical inflection signal to watch is MOHAP's pending MEE hazardous waste classification harmonization, which will consolidate contractor panels and disqualify non-compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Gasification Capacity Buildout | ADNOC downstream pilots at remote wellpads collapse centralized incineration hub economics by eliminating double-handling transport costs. |
| Blockchain-Secured Manifesting Platform | Integration with MOHAP reporting systems creates first-mover advantage for logistics operators serving multi-site generators across emirates. |
| Spent Catalyst Metal Recovery Joint Venture | Ruwais refinery hydrotreating residue contains recoverable vanadium and nickel fractions currently undervalued in disposal contracts. |
| Refractory Material Backward Integration | Captive alumina-chrome supply agreements protect rotary kiln operators from price volatility compressing unit economics. |
| Combined Heat-and-Power Facility Permitting | Dubai Industrial Strategy 2030 fast-track approvals open greenfield development slots in Jebel Ali free zone corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with thermal treatment plant managers, hazardous waste logistics coordinators, petrochemical procurement leads, and MOHAP regulatory compliance officers. Secondary validation drew from Emirates Authority for Standardization and Metrology specifications, federal waste management regulations, customs data on refractory material imports, and SEC filings of multinational environmental service providers. Bottom-up generator volume estimates were triangulated against top-down market sizing from treatment facility capacity utilization rates.
Calibration anchored volume and value outputs to historical thermal processing deployment cycles, plasma gasification technology maturation curves, and regulatory compliance deadline schedules across the projection horizon. Segmentation dimensions modeled include service type complexity, industry vertical hazard classification, waste stream regulatory tier, treatment technology energy recovery potential, and emirate-specific permitting frameworks. CAGRs were derived from facility capex pipeline analysis and generator contract tenure extension patterns. Key forecast inputs incorporated MOHAP manifest digitization rollout timelines and ADNOC downstream expansion schedules.
Stress conditions across refractory material price bands, plasma torch electrode supply disruptions, and MEE harmonization implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding federal landfill diversion enforcement intensity and petrochemical cluster output growth. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
Europe Plastic Waste Management Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Europe Waste Management Market