
 Automotive Paints and Coatings Market | 2026-2036
Automotive Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Paints and Coatings Market Analysis
Aftermarket color-matching and repair services is reconfiguring margin pools away from bulk OEM supply contracts toward precision application networks. PPG Industries sustains technology leadership through advanced spectrophotometric color systems. Axalta Coating Systems Ltd. dominates refinish distribution channels across North America and Europe. BASF SE leverages integrated resin-to-coating chemistry to control raw material quality.
Automotive paints and coatings constitute multi-layer film systems—typically comprising electrodeposition primer, surfactant-modified basecoat, and cross-linked clearcoat—engineered to provide corrosion resistance, optical depth, and weathering durability on vehicle substrates. Waterborne technology leads OEM installations due to compliance with EPA emission thresholds and EU F-Gas Regulation limits on solvent release. Powder coating occupies the fastest-growing technology position for commercial vehicle and heavy equipment frames, driven by zero-VOC profiles and overspray recyclability. Clearcoat formulations command premium positioning within the product type hierarchy, as scratch-resistant and self-healing chemistries concentrate margin pools.
EPA, REACH, and ISO 12944 collectively dictate permissible solvent content, corrosion-test protocols, and substrate-specific adhesion standards across manufacturing and refinish operations. OEMs and aftermarket providers must now certify coating systems against multi-jurisdiction chemical registries before market entry. Stakeholders should monitor regulatory convergence between California Air Resources Board thresholds and EU Green Deal chemical restrictions to anticipate reformulation timelines and capital allocation for compliant production assets.
Market Dynamics
Waterborne coating chemistries are compressing solvent-based capacity across OEM assembly lines as EPA and EU REACH emission thresholds tighten formulation specifications. This technology transition is redistributing margin pools toward resin suppliers with captive aqueous polymer capabilities.
Growth Catalysts
- Electrification-driven substrate diversification:Battery enclosure manufacturers require specialized thermal-management coatings. PPG and Axalta are scaling ceramic-filled primer lines for aluminum-intensive EV architectures.
- REACH Annex XVII solvent restrictions:The EU's tightening VOC limits for decorative and industrial coatings are forcing refinish operators toward waterborne basecoat-clearcoat systems. Germany's KBA type-approval process now mandates compliant formulations for registered repair facilities.
- UV-cured clearcoat adoption:Commercial vehicle manufacturers in China are installing low-temperature cure lines to reduce energy intensity. NMPA-registered UV formulations are penetrating heavy-duty truck OEM specifications.
Market Restraints
- Titanium dioxide supply concentration:Pigment production clusters in China's Sichuan and Shandong provinces. Geopolitical friction or environmental shutdowns transmit immediate cost volatility to coating formulators.
- Isocyanate cross-linker dependency:Aliphatic HDI supply routes through BASF's Ludwigshafen and Covestro's Krefeld-Uerdingen sites create European concentration risk for premium automotive clearcoats.
- Application equipment retrofit requirements:Waterborne basecoats demand humidity-controlled spray booths and electrostatic bell modifications. Smaller refinish shops face capital barriers to compliance.
Strategic Opportunities
- India's PLI scheme for automotive manufacturing:The production-linked incentive framework is attracting final assembly investment to Gujarat and Tamil Nadu. Coating suppliers can anchor regional blending facilities adjacent to expanding Maruti Suzuki and Tata Motors paint shops.
- Self-healing clearcoat chemistry:Microcapsule-based scratch recovery formulations are advancing from concept to pilot production. OEMs in Japan are testing METI-subsidized demonstrator programs for premium vehicle lines.
- Digital color-matching platforms:Cloud-connected spectrophotometry is reducing refinish cycle times. North American collision repair networks are consolidating procurement through integrated color retrieval systems.
Industry Challenges
- Formulation chemist scarcity:Expertise in polyurethane dispersion stability and UV photoinitiator package design is concentrated among aging technical workforces in Germany and Japan. Knowledge transfer gaps threaten innovation pipelines.
- Multi-jurisdiction certification timelines:Coating systems require sequential EPA TSCA pre-manufacture notification, EU CLP classification, and China MEE new chemical registration. Synchronized launch schedules face 18-24 month validation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Paints and Coatings Market |
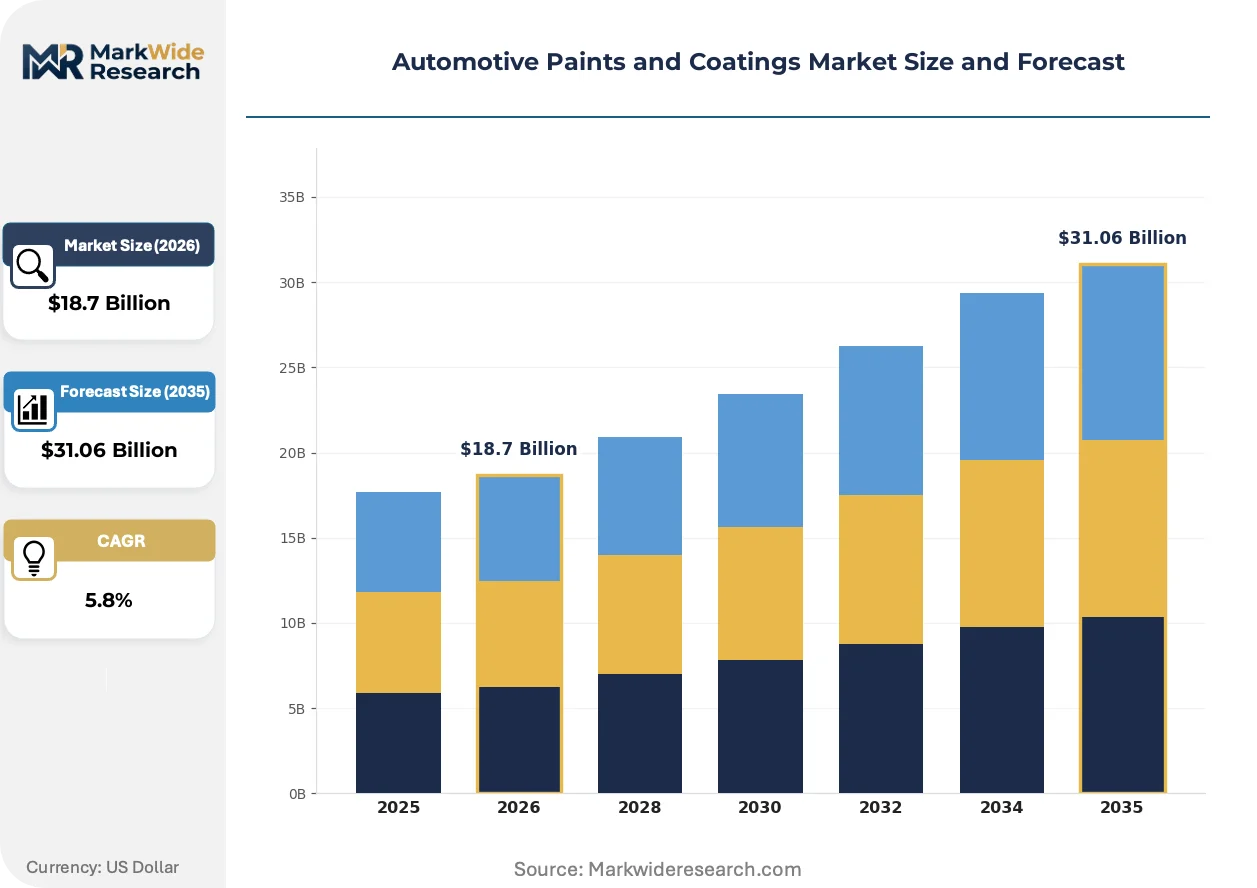
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basecoat, Clearcoat, Primer, Colorcoat Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Equipment Technology: Waterborne, Solventborne, Powder Coating, UV-Cured End User: OEMs, Aftermarket Providers, Body Shops, Custom Shops |
| Companies Covered | Akzo Nobel N.V., Nippon Paint Holdings Co., Ltd., PPG Industries, Inc., RPM International Inc., Kansai Paint Co., Ltd., Axalta Coating Systems Ltd., The Sherwin-Williams Company, 3M Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Paints and Coatings Market Emerging Trajectories
Active material science breakthroughs are compressing traditional layer counts while expanding functional performance boundaries. Formulation platforms now integrate corrosion inhibition, thermal management, and aesthetic depth within single film builds.
Polyurethane-acrylic hybrid waterborne basecoats are hybridizing OEM coating architectures. Volkswagen's Zwickau and Chattanooga assembly plants have converted full production lines to two-layer wet-on-wet systems. This chemistry is hybridizing capital allocation decisions, as dual-cure capability reduces spray booth footprint requirements by eliminating intermediate flash zones.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin blowing agent transitions in automotive insulation coatings. The industrial consequence is reformulation of cavity wax and underbody sealant products to maintain acoustic damping without high-GWP propellants. Commercial vehicle manufacturers in Poland and the Czech Republic are most affected, sourcing compliant alternatives through ECHA-registered substance inventories.
Collision repair networks are consolidating procurement through subscription-based color formula databases. Independent body shops in Texas and Florida are abandoning per-spray color retrieval fees for unlimited-access annual contracts. This pattern is most visible in US Sun Belt states where hail damage volume sustains high throughput operations.
Automotive Paints and Coatings Market Segmentation
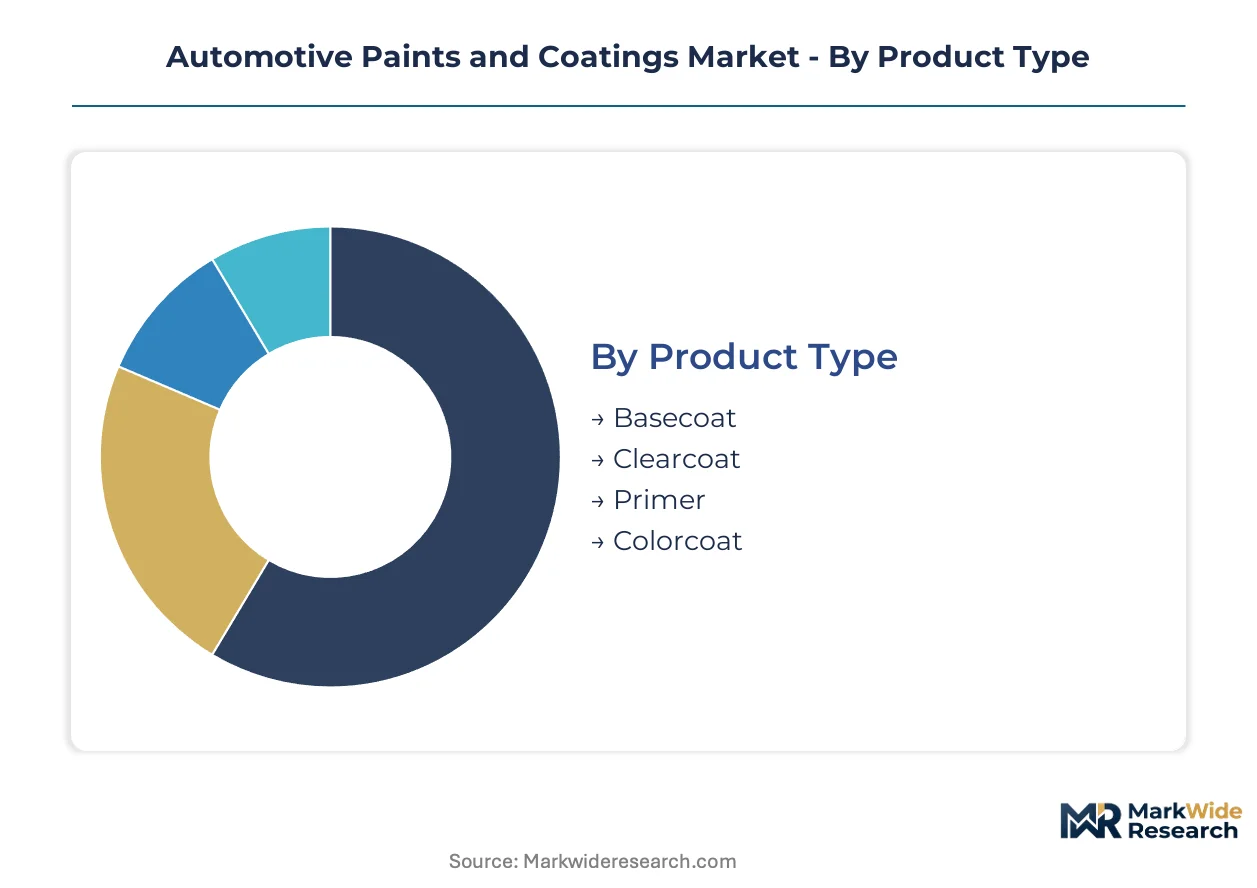
Automotive coating architectures distribute value across functional layers, each commanding distinct formulation expertise and capital requirements. Segmentation clarity enables suppliers to align R&D portfolios with specific performance thresholds and regulatory compliance burdens.
Product Type:
Mature film-build technologies coexist with emerging functional coatings as electrification reshapes substrate protection requirements.
- Clearcoat:Cross-linked polyurethane-acrylic systems provide weathering resistance and optical depth through controlled gloss retention. Premium passenger vehicle lines in Germany and Japan specify self-healing variants with microcapsule-based scratch recovery. EPA VOC thresholds and EU REACH solvent restrictions compress conventional solventborne capacity, redirecting investment toward waterborne and UV-curable platforms.
- Basecoat:Pigmented layers deliver colorimetric precision through metallic flake orientation and surfactant-modified resin systems. OEM assembly lines in China and India are converting to waterborne basecoats to satisfy emission protocols, while refinish networks face retrofit costs for humidity-controlled spray booths.
- Primer:Electrodeposition and surfactant-etched adhesion promoters establish corrosion resistance on galvanized steel and aluminum substrates.
- Colorcoat:Single-stage pigmented systems serve commercial vehicle and heavy equipment segments with simplified application protocols.
Clearcoat retains volume leadership; colorcoat holds the steepest expansion curve in cost-sensitive commercial applications.
Application:
Vehicle architecture diversity creates tiered performance specifications, from luxury passenger car optical standards to heavy equipment abrasion resistance.
- Passenger Vehicles:Multi-layer wet-on-wet systems dominate premium assembly, with Volkswagen's Zwickau and Chattanooga plants operating full waterborne conversions. Color-matching precision requirements sustain refinish margin pools through spectrophotometric retrieval systems.
- Commercial Vehicles:Powder coating penetration accelerates on heavy-duty truck frames and trailer assemblies, driven by zero-VOC profiles and overspray recyclability. China's NMPA-registered UV formulations are penetrating heavy-duty OEM specifications.
- Motorcycles:Compact part geometries favor electrostatic spray efficiency and rapid cure cycles.
- Heavy Equipment:Abrasion-resistant epoxy primers and high-build polyurethane topcoats address construction and agricultural machinery exposure.
Passenger vehicles anchor formulation value; commercial vehicles are expanding most quickly through powder and UV technology adoption.
Technology:
Regulatory convergence on solvent emissions is compressing legacy chemistry platforms while opening capacity allocation for compliant alternatives.
- Waterborne:Aqueous polyurethane-acrylic dispersions satisfy EPA emission thresholds and EU F-Gas Regulation limits. OEM installations lead adoption, with Asia-Pacific assembly lines expanding consumption of high-performance coating systems.
- UV-Cured:Photoinitiator-activated clearcoats enable low-temperature cure for temperature-sensitive substrates. Commercial vehicle manufacturers in China are installing energy-reduction lines to meet dual carbon goals.
- Solventborne:Conventional nitrocellulose and alkyd systems persist in aftermarket refinish where equipment retrofit barriers delay conversion.
- Powder Coating:Thermoset epoxy and polyester formulations serve commercial vehicle frames with near-zero waste profiles.
Waterborne technology commands installed capacity leadership; UV-cured platforms gain share fastest through energy intensity reduction.
End User:
Procurement concentration separates high-volume OEM supply contracts from fragmented aftermarket service networks.
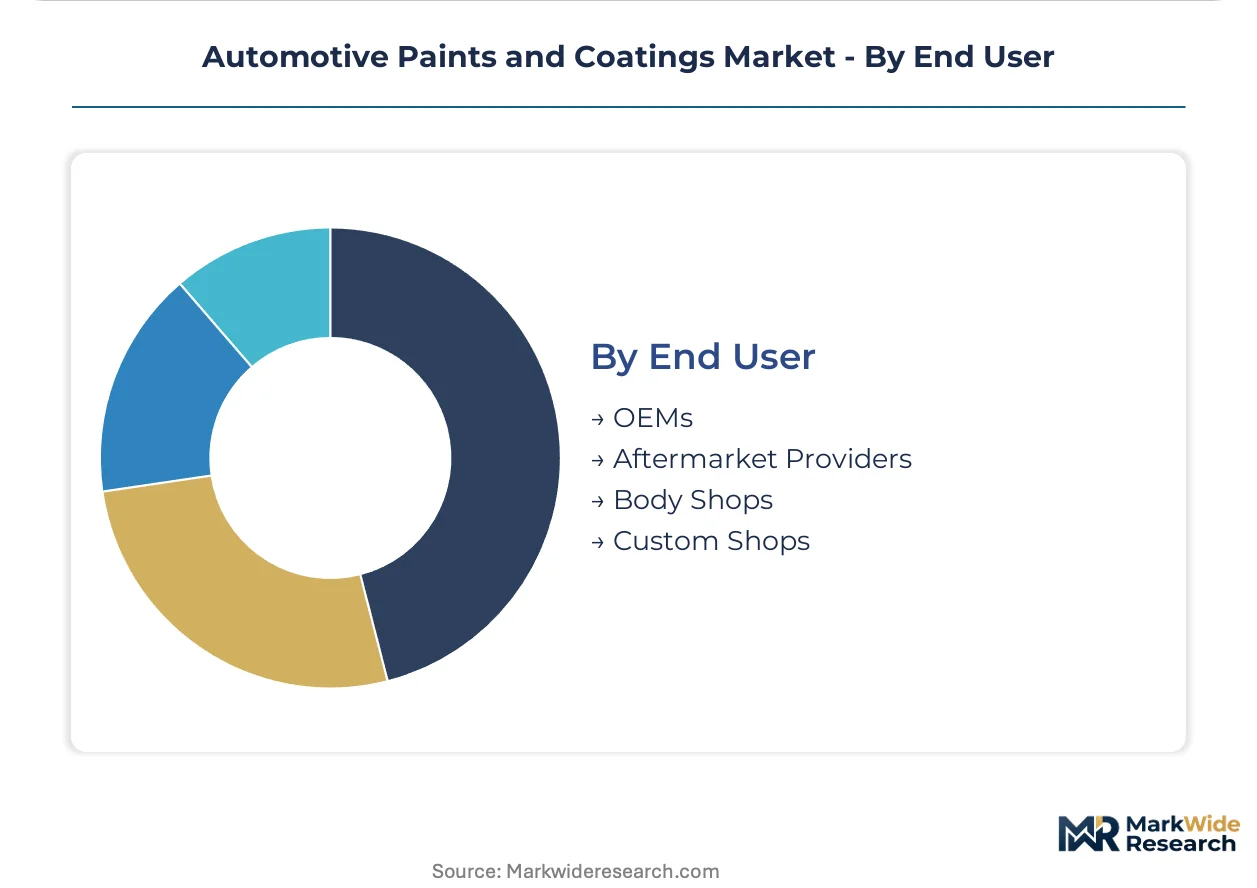
- OEMs:Integrated paint shops at final assembly facilities specify coating systems through multi-year supply agreements. India's PLI scheme for automotive manufacturing is attracting coating suppliers to anchor regional blending facilities adjacent to expanding Maruti Suzuki and Tata Motors operations.
- Aftermarket Providers:Collision repair networks consolidate procurement through subscription-based color formula databases. North American Sun Belt states sustain high-throughput operations through unlimited-access annual contracts replacing per-spray fees.
- Body Shops:Independent refinish operators face capital barriers to waterborne compliance, concentrating margin pools toward precision application networks.
- Custom Shops:Specialty finishers serve restoration and modification markets with artisan color-matching capabilities.
OEMs retain procurement volume leadership; aftermarket providers are climbing the fastest through digital platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Aftermarket refinish operators in India and Southeast Asia face acute capital barriers for waterborne spray booth retrofits. German and Japanese OEMs absorb premium clearcoat costs without volume elasticity, prioritizing self-healing and spectrophotometric precision over unit economics.
China
Commercial vehicle manufacturers in Shandong and Hebei provinces are installing NMPA-registered UV-cured lines to meet dual carbon goals. MEE chemical registration protocols now require 18-24 month validation timelines for new coating formulations. The Yangtze River Delta cluster around Shanghai anchors the highest concentration of electrodeposition primer capacity for EV battery enclosures.
Germany
Volkswagen's Zwickau assembly plant operates full waterborne conversions, eliminating intermediate flash zones through wet-on-wet polyurethane-acrylic systems. KBA type-approval mandates REACH Annex XVII compliant formulations for all registered repair facilities. BASF's Ludwigshafen site and Covestro's Krefeld-Uerdingen operations concentrate aliphatic HDI cross-linker supply for premium automotive clearcoats.
United States
EPA VOC thresholds compress solvent-based refinish capacity across Texas and Florida collision repair networks. Sun Belt states sustain high-throughput operations through subscription-based color formula databases replacing per-spray fees. PPG Industries anchors spectrophotometric color-matching technology leadership from its North American base.
India
Maruti Suzuki and Tata Motors are expanding paint shop capacity in Gujarat and Tamil Nadu under the PLI scheme for automotive manufacturing. CDSCO and BIS convergence on chemical safety standards is extending formulation validation timelines for imported resin systems. Regional blending facilities are anchoring adjacent to final assembly plants to reduce logistics costs for waterborne basecoat supply.
Japan
METI-subsidized demonstrator programs are piloting microcapsule-based self-healing clearcoats for premium vehicle lines. JIS standards for automotive coatings are tightening adhesion test protocols for aluminum-intensive EV architectures. Kansai Paint and Nippon Paint anchor formulation expertise concentrated in the Osaka and Kanto industrial corridors.
Automotive Paints and Coatings Market Vendor Landscape
Capability concentration sits with integrated resin-to-coating chemists; scale advantage sits with global distribution networks. The market structures around three tiers: multinational chemical conglomerates controlling captive polymer supply, specialized coating formulators with refinish channel dominance, and regional players serving cost-sensitive OEM contracts. Strategic moves center on backward integration into aqueous dispersion technology and geographic anchoring beside expanding assembly plants.
Among Dutch and Japanese coating specialists, Akzo Nobel N.V., Nippon Paint Holdings Co., Ltd., and Kansai Paint Co., Ltd. occupy positions exemplifying integrated formulation expertise. These entities represent archetypes of regional market leadership—European regulatory compliance mastery, East Asian precision colorimetric systems, and captive resin synthesis capabilities respectively. Their positioning reflects the industry pattern where geographic origin correlates with regulatory specialization and customer proximity advantages.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| PPG Industries, Inc. |
| RPM International Inc. |
| Kansai Paint Co., Ltd. |
| Axalta Coating Systems Ltd. |
| The Sherwin-Williams Company |
| 3M Company |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Shandong and Sichuan titanium dioxide clusters is compressing pigment pricing and forcing coating formulators toward long-term offtake contracts to lock in feedstock costs. This utilization dynamic simultaneously erodes spot-market supplier leverage and rewards integrated resin producers with captive aqueous polymer capabilities.
Pricing Analysis
Aftermarket refinish services generate disproportionate lifetime value through recurring color-matching subscriptions and extended service contracts. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified self-healing clearcoats from commercial vehicle colorcoats and generic refinish alternatives. Cost compression in the standard tier is intensifying because humidity-controlled spray booth retrofits concentrate margin pools toward precision application networks. Fleet operators and independent body shops exhibit acute price sensitivity; German luxury OEMs absorb premium positioning without volume elasticity.
Supply Chain Analysis
Upstream feedstock concentration in China's pigment production clusters, Germany's aliphatic HDI cross-linker sites, and Japan's photoinitiator corridors creates multi-point dependency for coating formulators. Formulation chemistry draws from titanium dioxide, polyurethane dispersions, and ceramic-filled thermal management compounds. Single-source vulnerability runs through BASF's Ludwigshafen and Covestro's Krefeld-Uerdingen operations for premium clearcoat cross-linkers. Distribution runs through refinish channel consolidators and OEM-integrated paint shops at final assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
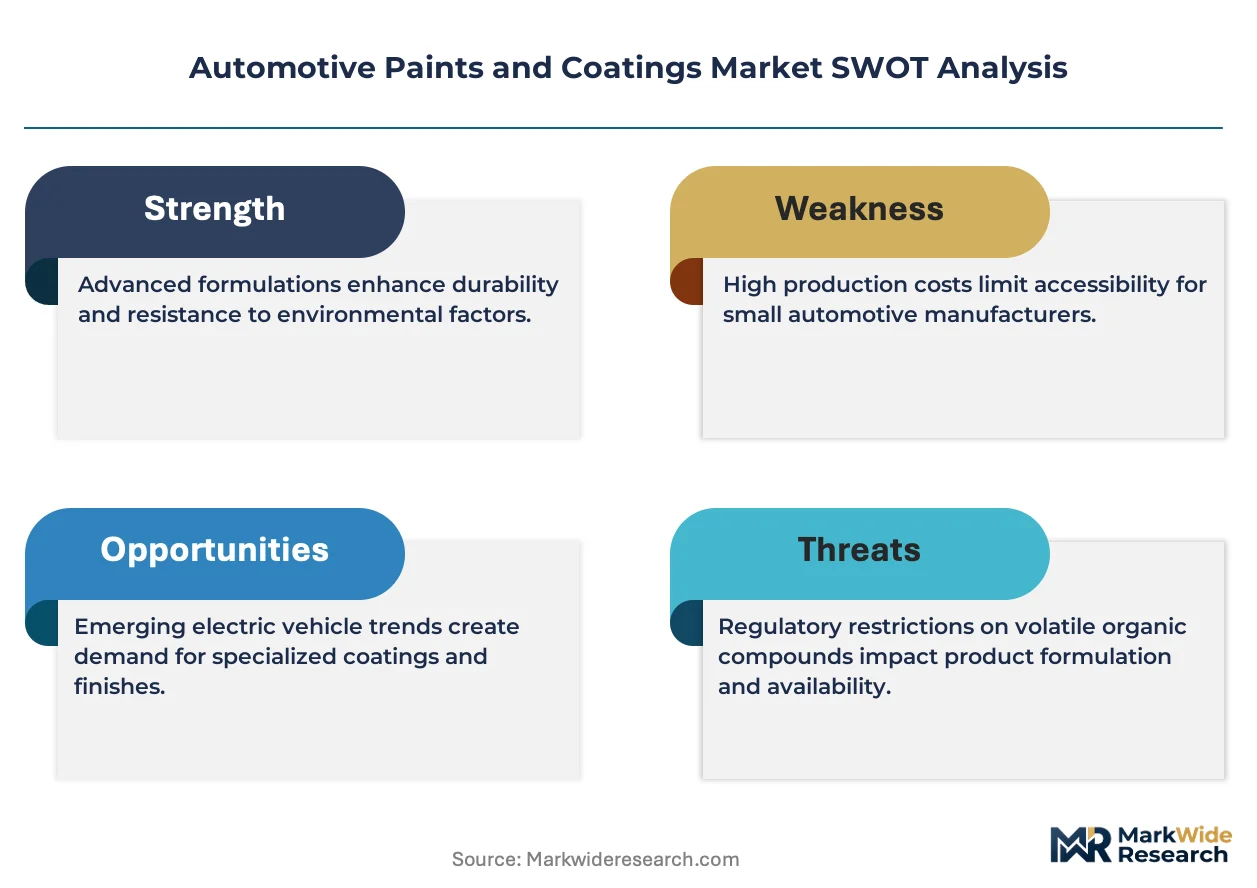
Automotive paints and coatings constitute a defensive-moat market where regulatory entrenchment creates formidable barriers: multi-jurisdiction certification timelines and EPA-EU REACH convergence lock in incumbents with compliant formulation libraries.
For Market Incumbents: Insulate formulation expertise through backward integration into aqueous polyurethane dispersion production and captive resin synthesis capabilities. Anchor regional blending facilities adjacent to expanding OEM assembly plants in India's Gujarat and Tamil Nadu corridors. Certification investment in NMPA-registered UV formulations and KBA type-approved repair systems creates switching-cost barriers against emerging Asian competitors.
For New Entrants and Emerging Players: India's aftermarket refinish networks present geographic underpenetration with acute capital barriers for waterborne compliance creating white-space opportunity. Target collision repair consolidation in North American Sun Belt states through cloud-connected spectrophotometry platforms. Specialty thermal-management coatings for EV battery enclosures offer the most penetrable segment with limited incumbent R&D focus.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across UV-cured and self-healing clearcoat pilot production lines as METI-subsidized demonstrator programs advance commercialization. Acquisition target archetype: regional coating formulators with established KBA or NMPA registration pathways and stranded capacity in humidity-controlled spray booth networks. Monitor CDSCO-BIS convergence timelines as inflection indicator for imported resin system validation delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aqueous Polymer Production | BASF's Ludwigshafen resin-to-coating chemistry controls raw material quality and reduces titanium dioxide cost volatility exposure. |
| Regional Blending Facility Anchoring | Maruti Suzuki and Tata Motors expansion in Gujarat and Tamil Nadu under India's PLI scheme attracts adjacent coating supply infrastructure. |
| UV-Cured Formulation Registration | NMPA-registered clearcoats penetrate heavy-duty truck OEM specifications in China's Shandong and Hebei provinces. |
| Digital Color-Matching Platform Deployment | Cloud-connected spectrophotometry reduces refinish cycle times across Texas and Florida collision repair networks. |
| Self-Healing Clearcoat Pilot Scale-Up | METI-subsidized microcapsule-based scratch recovery programs advance from concept to premium vehicle line testing in Japan. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, aftermarket refinish network managers, resin procurement leads, and regulatory affairs directors anchored the qualitative base. Primary fieldwork combined with secondary validation through EPA TSCA filings, ECHA REACH registrations, SEC 10-K disclosures, and vehicle production databases. Bottom-up coating consumption modeling triangulated against top-down OEM assembly line capacity analysis.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning coating layer function, vehicle architecture, cure technology platform, and end-user procurement concentration. CAGRs derived from regression analysis of historical technology transition curves and regulatory compliance timelines. Forecast inputs incorporated EV substrate diversification rates and waterborne conversion capital expenditure patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-subsidized Chinese coating specialists or accelerated EU Green Deal chemical restrictions would shift outcomes. Quarterly review of MEE registration timelines, KBA type-approval backlogs, and titanium dioxide spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market