
 South Africa Paints and Coatings Market | 2026-2036
South Africa Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Paints and Coatings Market Insights
Waterborne resin technology is reconfiguring formulation priorities across South African manufacturing plants. Akzo Nobel N.V. leverages its global R&D network to localize low-VOC architectural lines. Kansai Plascon anchors volume through its extensive retail distribution across townships and secondary cities. BASF differentiates via specialty additives that address subtropical UV degradation and coastal corrosion.
Paints and coatings constitute liquid or powder film-forming materials applied to substrates for protection, decoration, or functional performance; formulations typically incorporate binders, pigments, solvents or water carriers, and additives, with film thickness ranging from 25 microns for decorative finishes to 500 microns for heavy-duty protective systems. Architectural coatings dominate value generation through sustained residential construction in Gauteng and KwaZulu-Natal, while industrial coatings expand fastest as automotive assembly and mining equipment refurbishment intensify. Epoxy base materials capture premium margins in protective applications for harbors and petrochemical infrastructure.
SABS standards and the National Environmental Management Air Quality Act constrain solvent-based product lines and mandate VOC threshold compliance. The Department of Trade, Industry and Competition enforces local content preferences on state-funded construction projects, reshaping procurement criteria for public infrastructure coatings. Stakeholders must monitor regulatory enforcement intensity in coastal provinces and align formulation roadmaps with anticipated tightening of hazardous chemical classifications.
Market Dynamics
Waterborne resin adoption is collapsing solvent-based formulation economics across South African manufacturing plants, forcing capital reallocation toward compliant production lines and rewiring competitive advantage toward low-VOC capability.
Growth Catalysts
- Air Quality Act Enforcement:The National Environmental Management Air Quality Act mandates VOC threshold reductions that eliminate marginal solvent-based competitors and consolidate demand among compliant manufacturers.
- Gauteng Infrastructure Pipeline:Johannesburg and Pretoria anchor state-funded construction procurement that concentrates coating demand in a single metropolitan corridor.
- Epoxy Protective Systems:Harbor and petrochemical infrastructure expansion drives premium-grade protective coating specifications that capture extended project lifecycles.
Market Restraints
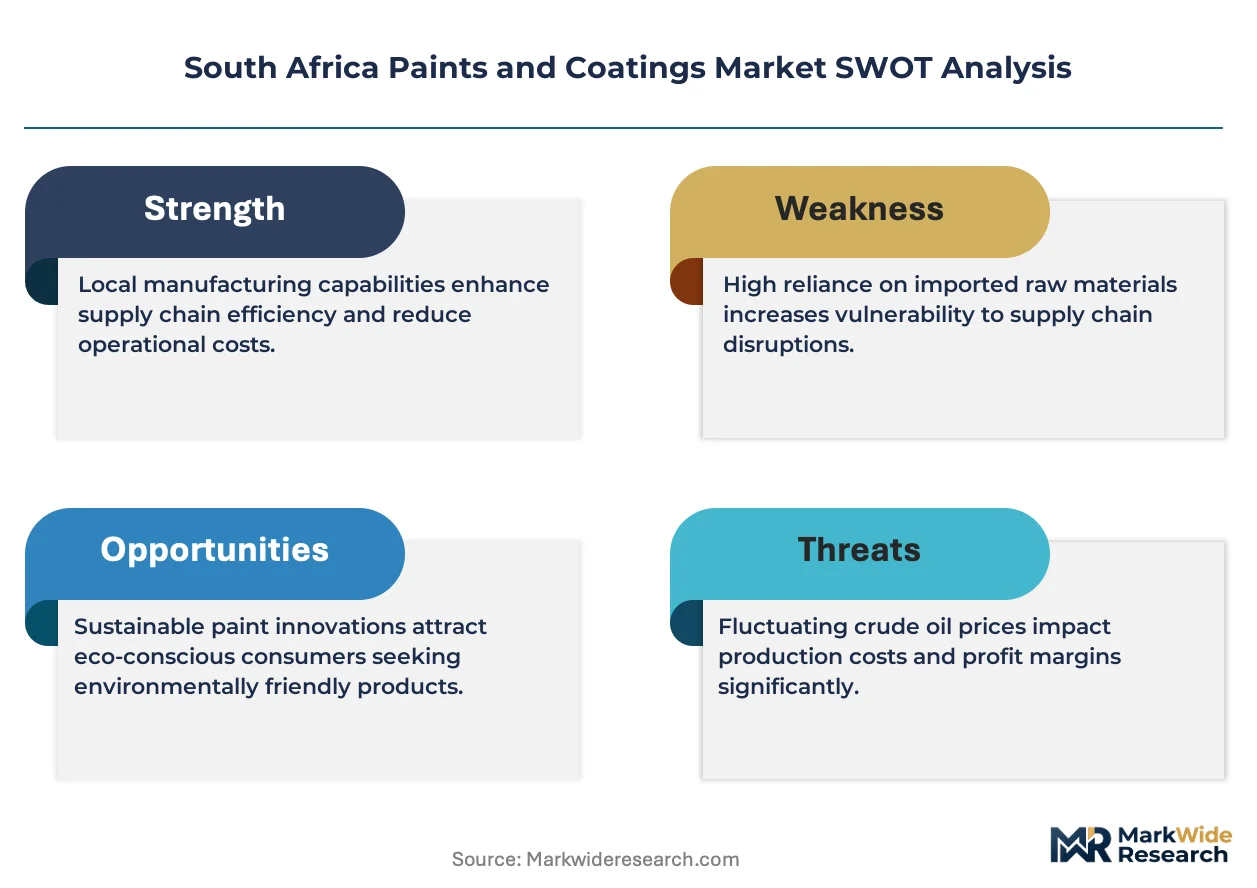
- Titanium Dioxide Import Dependency:Raw material concentration in Asian supply chains exposes formulators to exchange rate volatility and shipping cost spikes.
- SABS Certification Timelines:Extended product approval cycles delay new formulation launches and compress effective patent windows.
- Waterborne Performance Gap:Subtropical humidity conditions degrade water-based protective film integrity in coastal applications.
Strategic Opportunities
- KwaZulu-Natal Industrial Corridor:Durban-Richards Bay logistics and automotive assembly expansion creates underpenetrated demand for automotive refinish and equipment coatings.
- Local Content Preferences:Department of Trade, Industry and Competition procurement rules on state projects favor domestic manufacturing investment.
- UV-Additive Convergence:Combination of hindered amine light stabilizers with nano-pigmentation addresses coastal UV degradation in a single specification.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in waterborne polymer stabilization and VOC-compliant additive packages commands premium compensation.
- Legacy Equipment Retooling:Solvent-based spray booths and drying infrastructure require capital-intensive conversion to accommodate waterborne viscosity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Paints and Coatings Market |
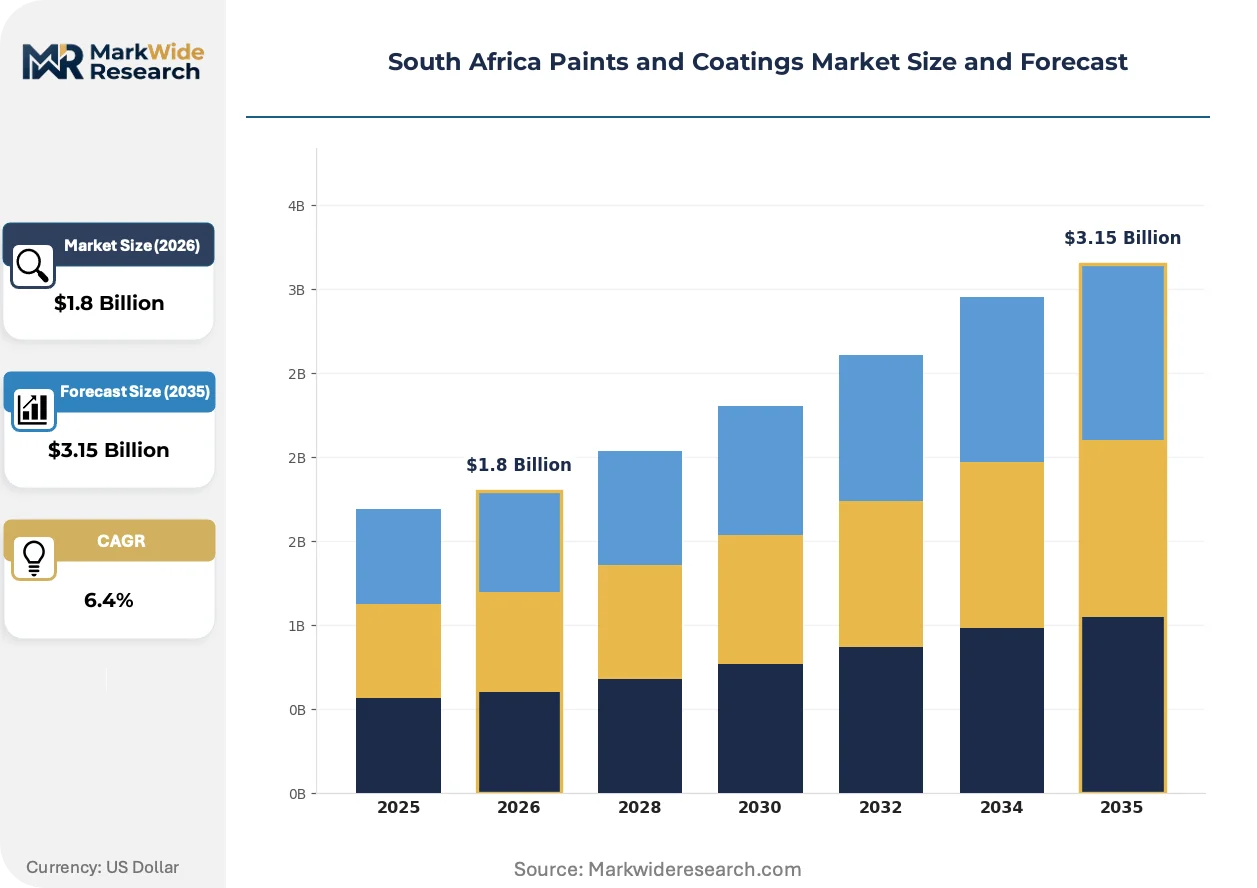
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Coatings, Industrial Coatings, Protective Coatings, Specialty Coatings Application: Residential, Commercial, Automotive, Marine Base Material: Acrylic, Alkyd, Epoxy, Polyurethane Sales Channel: Retail, Direct Sales, Distributors, Online |
| Companies Covered | Atlas Paints, Dekro Paints, Akzo Nobel N.V., BASF, Axalta Coatings Systems, PPG Industries, Inc., Kansai Plascon, Plascon, The Sherwin-Williams Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Paints and Coatings Market Trends and Innovations
Formulation chemistry and regulatory compliance are converging to compress product development cycles and restructure value capture toward specification-grade performance rather than commodity volume.
Waterborne acrylic-urethane hybrid technology is collapsing the performance gap between decorative and protective coating categories. Mining equipment maintenance divisions and automotive assembly plants are adopting these systems for moderate-duty corrosion protection. The technology is collapsing traditional tier boundaries that separated architectural from industrial specification grades.
The National Environmental Management Air Quality Act and SABS VOC thresholds are tightening in parallel, eliminating solvent-based product lines from state procurement eligibility. Industrial coating specifications now require third-party emission certification prior to tender submission. Protective coatings for harbor infrastructure face the steepest compliance trajectory due to proximity to dense coastal populations.
Buyer consolidation among major construction consortiums is compressing supplier qualification cycles and unbundling technical service from material supply. Tier-one contractors now demand dedicated on-site coating inspectors and warranty-backed application protocols. This pattern concentrates most visibly in Gauteng infrastructure megaprojects where single-source coating packages reduce interface risk.
South Africa Paints and Coatings Market Segmentation
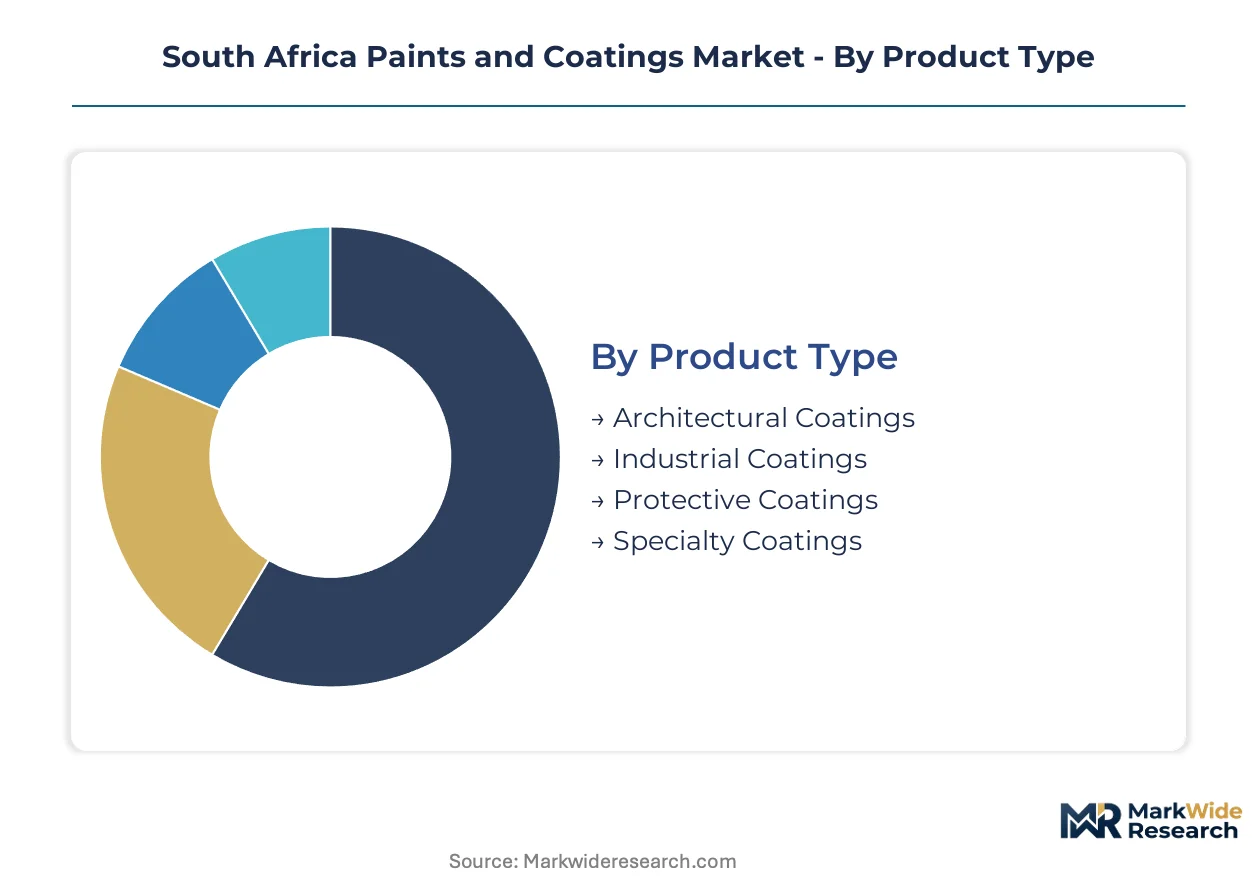
Segmentation in the South Africa paints and coatings market reveals how formulation chemistry, procurement channels, and end-use specifications create distinct competitive arenas. Each dimension carries regulatory and logistical implications that reshape supplier positioning across Gauteng infrastructure corridors and coastal industrial zones.
Product Type:
Use-case spectrum spans decorative interior finishes through heavy-duty corrosion protection, with formulation complexity and project scale determining margin structure and certification requirements.
- Architectural Coatings:Waterborne acrylic and alkyd formulations dominate residential and commercial building envelopes. Gauteng's state-funded housing programs and private residential construction in Johannesburg-Pretoria corridors concentrate procurement volume for low-VOC decorative systems.
- Industrial Coatings:Solvent-borne and high-solids systems serve manufacturing equipment and assembly line infrastructure. Automotive plants in Eastern Cape and KwaZulu-Natal drive specification-grade demand for chemical-resistant finishes that withstand process solvents and thermal cycling.
- Protective Coatings:Epoxy and zinc-rich primers address infrastructure longevity in harbor, petrochemical, and mining applications.
- Specialty Coatings:Functional films include intumescent fire protection, anti-graffiti surfaces, and conductive coatings for electronics manufacturing.
The dominant share belongs to Architectural Coatings, while Industrial Coatings is closing the gap fastest.
Application:
Cost tier separation runs from mass-market residential repainting through capital-intensive marine dry-dock specifications, with warranty terms and inspection protocols scaling accordingly.
- Residential:Decorative interior and exterior finishes for single-family homes and multi-unit housing. Township development programs and middle-class suburban expansion in Gauteng and Western Cape sustain volume for standard-grade emulsions and enamels.
- Commercial:Office, retail, and institutional building envelopes requiring durability certification and color consistency across large surface areas.
- Automotive:OEM assembly line coatings and aftermarket refinish systems. Durban-Richards Bay automotive logistics expansion and vehicle assembly operations in Eastern Cape anchor demand for basecoat-clearcoat systems and electrodeposition primers.
- Marine:Hull protection, tank linings, and offshore platform coatings exposed to saltwater immersion and cathodic stress.
Residential commands the largest volume base, though Automotive is expanding most quickly as assembly capacity localizes.
Base Material:
Volume concentration favors waterborne acrylics in decorative segments, while solvent-borne and high-performance chemistries retain protective application strongholds.
- Acrylic:Water-dispersed polymers dominate interior and exterior architectural finishes. SABS VOC compliance mandates and Air Quality Act enforcement accelerate substitution for alkyd solvent systems in Gauteng retail channels.
- Alkyd:Oil-modified polyester resins persist in metal decorative enamels and traditional wood finishes. Import dependency on soybean and linseed oil feedstocks exposes formulators to agricultural commodity volatility and exchange rate pressure.
- Epoxy:Two-component amine-cured systems deliver chemical resistance and adhesion to concrete and steel substrates.
- Polyurethane:Aliphatic and aromatic isocyanate-based films provide abrasion resistance and UV stability for flooring and exterior applications.
Acrylic holds the broadest application footprint, while Epoxy captures the steepest margin expansion in infrastructure specifications.
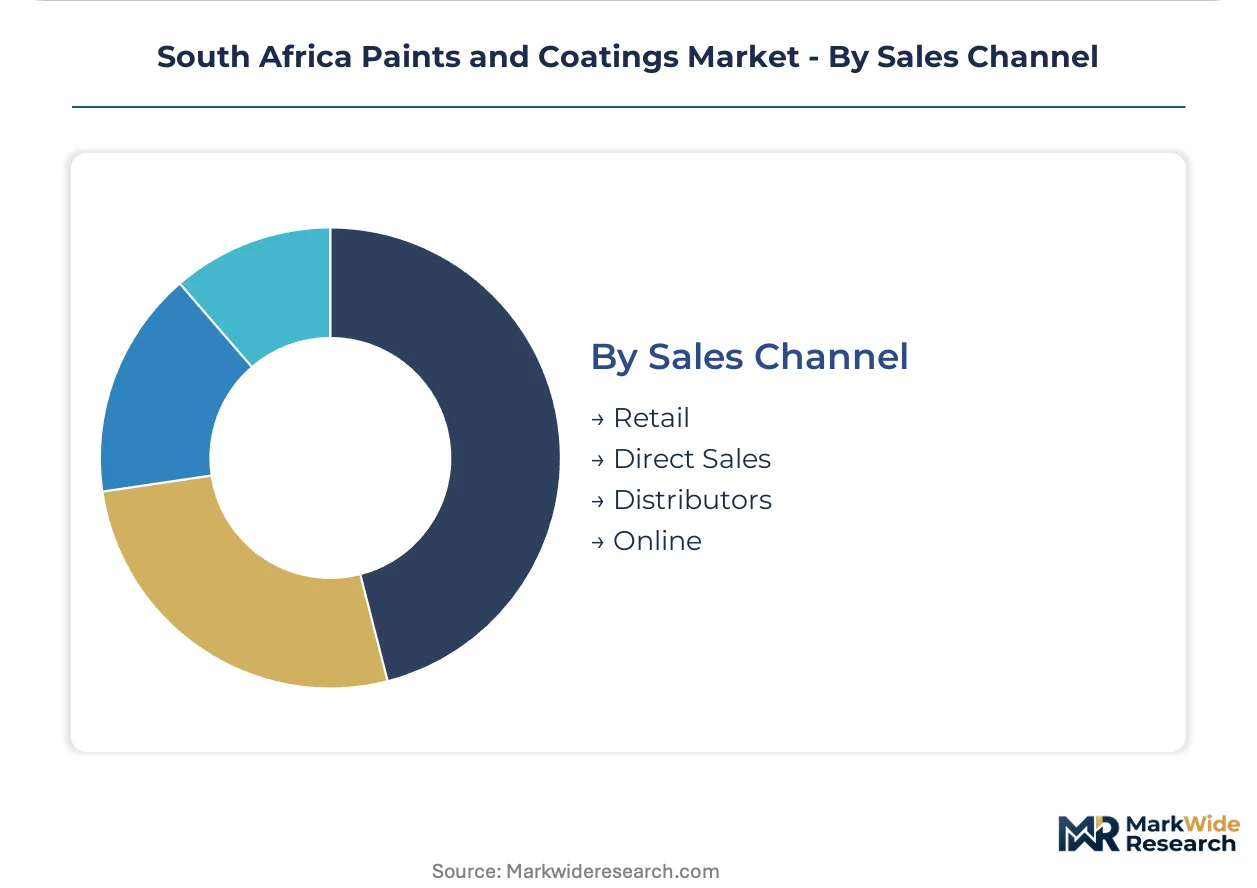
Sales Channel:
Customer type fragmentation splits between retail walk-up trade, project-integrated direct supply, and specification-driven distributor networks.
- Retail:Hardware stores, paint depots, and home improvement centers serving residential repainting and small commercial maintenance. Kansai Plascon's township and secondary city network exemplifies density-driven volume capture.
- Direct Sales:Manufacturer-to-contractor relationships for large infrastructure and industrial projects. Gauteng megaprojects increasingly require dedicated technical service and on-site quality assurance bundled with material supply.
- Distributors:Independent stocking distributors serving regional contractors and industrial maintenance divisions outside metropolitan cores.
- Online:E-commerce platforms and manufacturer-direct digital channels for standard-grade architectural products.
Retail maintains the widest geographic reach, while Direct Sales is gaining share fastest as contractor consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction procurement concentrates among state-funded infrastructure consortia and residential developers across South Africa's primary economic corridors. Gauteng's metropolitan demand dwarfs provincial counterparts, while coastal industrial zones anchor specialized protective coating requirements.
Gauteng
Johannesburg and Pretoria infrastructure megaprojects drive architectural coating procurement at scale. The Department of Trade, Industry and Competition enforces local content thresholds on state-funded construction, reshaping supplier qualification criteria. The Johannesburg-Pretoria corridor concentrates coating demand through housing programs and commercial development pipelines.
KwaZulu-Natal
Durban-Richards Bay logistics expansion and automotive assembly growth generate industrial coating demand. Air Quality Act enforcement tightens VOC thresholds in coastal population centers, eliminating non-compliant solvent-based formulations. The Durban port precinct and surrounding automotive supplier parks anchor specification-grade protective system requirements.
Western Cape
Cape Town residential construction and commercial property maintenance sustain decorative coating volume. SABS certification timelines delay new product launches, compressing effective market windows for reformulated lines. The Cape Town metropolitan area drives premium architectural specification demand through green building certification programs.
Eastern Cape
Automotive assembly operations in Port Elizabeth and East London anchor OEM coating specifications. The National Environmental Management Air Quality Act mandates emission certification prior to state tender submission, filtering supplier pools. The Coega Industrial Development Zone and surrounding automotive clusters concentrate electrodeposition primer and refinish system demand.
South Africa Paints and Coatings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent route-to-market strategies. Retail network density separates volume leaders from project-integrated technical suppliers. Three archetypes dominate: multinational formulators with global R&D pipelines, regional manufacturers with township distribution depth, and specialty additive suppliers with specification-grade technical service. Competitive moves center on waterborne production line conversion and direct contractor relationship consolidation for Gauteng megaprojects.
Within the multinational tier, Akzo Nobel N.V. and BASF occupy positions anchored by global technology access and localized formulation adaptation. Kansai Plascon represents the regional manufacturing archetype with extensive retail penetration across secondary cities and township markets. These three companies exemplify the strategic divergence between specification-driven project capture and volume-driven retail density that defines competitive positioning across South African coating procurement channels.
| Leading Market Players |
|---|
| Atlas Paints |
| Dekro Paints |
| Akzo Nobel N.V. |
| BASF |
| Axalta Coatings Systems |
| PPG Industries, Inc. |
| Kansai Plascon |
| Plascon |
| The Sherwin-Williams Company |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Gauteng waterborne production lines is compressing supplier margins and accelerating price competition among SABS-compliant manufacturers. This utilization squeeze is forcing formulators to absorb titanium dioxide exchange volatility rather than pass through costs, reshaping contract structures toward indexed raw material clauses.
Pricing Analysis
Cost-plus contracts with titanium dioxide indexation dominate procurement for industrial and protective coating tiers. Price differentiation separates SABS-certified premium grades from uncertified economy imports in retail channels. Pricing pressure stems from Asian import competition in architectural emulsions. Township retail buyers exhibit highest price sensitivity, while state infrastructure contractors prioritize warranty-backed technical service over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Kansai Plascon's Gauteng facilities and Akzo Nobel's Johannesburg plant for waterborne architectural lines. Raw material supply draws from Chinese titanium dioxide producers, German specialty additive suppliers, and Saudi petrochemical feedstock sources. Single-source vulnerability concentrates in titanium dioxide import channels through Durban port. Distribution runs through Kansai Plascon's township retail network, direct sales teams for Gauteng megaprojects, and independent distributors serving secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's paints and coatings market offers expanding service-attach opportunities as technical inspection and warranty-backed application protocols grow faster than base material supply. On-site coating supervision and certified applicator training now command premium pricing in infrastructure procurement.
For Market Incumbents: Pre-empt waterborne technology obsolescence by converting remaining solvent-based spray infrastructure in coastal plants. Lock in SABS certification pipelines for nano-pigmented UV stabilizer formulations before regulatory thresholds tighten. Vertical integration into titanium dioxide blending operations mitigates import cost volatility. For New Entrants and Emerging Players: Build out KwaZulu-Natal automotive refinish capacity to capture Durban-Richards Bay assembly expansion. The Eastern Cape Coega Industrial Development Zone presents underpenetrated demand for electrodeposition primers. Partner with existing SABS-certified laboratories to compress product approval timelines versus greenfield certification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across waterborne production line conversions and compliant spray booth infrastructure. Viable acquisition targets include regional distributors with Gauteng state project relationships and specialty additive formulators serving harbor protective specifications. Monitor SABS enforcement intensity in coastal provinces as inflection signal for compliance-driven consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Production Conversion | SABS VOC mandates eliminate solvent-based competitors from state procurement eligibility. |
| Backward Integration into Titanium Dioxide | Captive blending operations reduce exposure to Asian supply chain exchange volatility. |
| Technical Service Bundling | On-site coating inspectors and warranty protocols capture Gauteng megaproject direct sales. |
| KwaZulu-Natal Distribution Expansion | Durban-Richards Bay automotive growth creates underpenetrated refinish system demand. |
| UV-Additive Specialty Formulation | Hindered amine light stabilizer convergence addresses coastal degradation in single specification. |
Research Methodology
Initial hypotheses were tested against primary input from coating plant managers, procurement leads at construction consortiums, SABS certification officers, and technical R&D directors, then refined against customs trade data, SABS regulatory filings, Department of Trade Industry and Competition procurement records, and SEC disclosures from multinational suppliers. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by product type, application end-use, base material chemistry, and sales channel structure. CAGRs were derived from trend extrapolation of construction spend and automotive assembly capacity. Forecast inputs incorporated Air Quality Act enforcement trajectories and local content preference implementation intensity.
Stress conditions across titanium dioxide price volatility, SABS approval timeline extension, and Gauteng infrastructure spend fluctuation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement cadence and raw material supply continuity. Quarterly review of SABS certification backlog and coastal province VOC inspection intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Iran Paints and Coatings Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market
Paints & Coatings
Paint Buckets Market