
 Global Antifouling Paints and Coatings Market | 2026-2036
Global Antifouling Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antifouling Paints and Coatings Market Foresight
Marine coatings chemists with organotin-transition expertise is rotating toward silicone-based and foul-release formulation platforms as legacy tributyltin competencies depreciate under regulatory pressure. PPG Industries leverages its global marine supply chain to sustain specification-grade positioning across OECD-flag fleets. AkzoNobel N.V. dominates European port authority tenders through REACH-compliant product portfolios. Hempel A/S anchors Nordic offshore vessel demand with specialized submersible coating systems.
Antifouling paints and coatings are protective surface treatments formulated with biocidal or non-stick chemistries—typically copper oxide, zinc pyrithione, or polydimethylsiloxane matrices—to prevent biofouling organism attachment on immersed marine structures. These systems reduce hydrodynamic drag, fuel consumption, and hull maintenance intervals for vessels operating in temperate and tropical waters. Self-polishing copolymer formulations lead value contribution due to controlled biocide release rates that extend dry-dock cycles. Foul release technology, particularly silicone-based variants, captures expanding margin pools as ship operators prioritize fuel efficiency over upfront material cost. Copper-free technology segments accelerate fastest where MEE and ECHA restrictions constrain traditional heavy-metal formulations.
The IMO Anti-Fouling Systems Convention shapes global product registration requirements, while ECHA's biocidal product regulation and China's MEE discharge standards constrain active ingredient portfolios. The EPA's vessel general permit program and Japan's METI chemical substance controls further fragment compliance obligations across manufacturing and distribution networks. Stakeholders must monitor regulatory divergence between Asian manufacturing hubs and European end-markets to anticipate reformulation cost pass-through and specification lock-in effects.
Market Dynamics
Regulatory pressure on heavy-metal biocides is compressing formulation pipelines and forcing accelerated R&D cycles toward silicone-based and copper-free alternatives. The transition away from tributyltin legacy systems continues to reshape capital allocation across marine coatings laboratories.
Growth Catalysts
- IMO Anti-Fouling Systems Convention:Mandatory compliance timelines are pulling forward dry-dock retrofit schedules and expanding addressable fleet volume for certified coating systems.
- Silicone foul-release chemistry:Hydrodynamic efficiency gains from polydimethylsiloxane matrices are displacing conventional copper oxide specifications in fuel-conscious fleet operators.
- China's port infrastructure corridors:State-led spending around Shanghai and Guangzhou is sustaining procurement scale for specification-grade marine coatings.
Market Restraints
- Copper price volatility:Input cost swings for copper oxide disrupt margin planning for legacy formulation portfolios still dependent on heavy-metal biocides.
- Supply concentration in Nordic specialty chemical producers:Limited qualified manufacturers of advanced silicone precursors create bottleneck risk for foul-release scaling.
- ECHA biocidal product regulation:Active substance approval timelines extend 18-36 months, freezing formulation pipelines and delaying commercialization.
Strategic Opportunities
- Offshore wind installation vessels:Jack-up and service vessel fleets require specialized submersible coating systems with extended immersion cycles.
- Japan's METI green shipping mandates:Fuel efficiency regulations are creating specification pull for low-friction hull coatings in domestic coastal fleets.
- Digital hull monitoring convergence:Integration of drone-based biofouling detection with predictive maintenance platforms enables outcome-based coating service models.
Industry Challenges
- Organotin-to-silicone skill migration:Formulation chemists with legacy tributyltin expertise require 12-24 month retraining cycles for foul-release polymer engineering.
- MEE discharge compliance certification:China's environmental ministry approval timelines create dry-dock scheduling conflicts for vessels operating across multiple flag registries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antifouling Paints and Coatings Market |
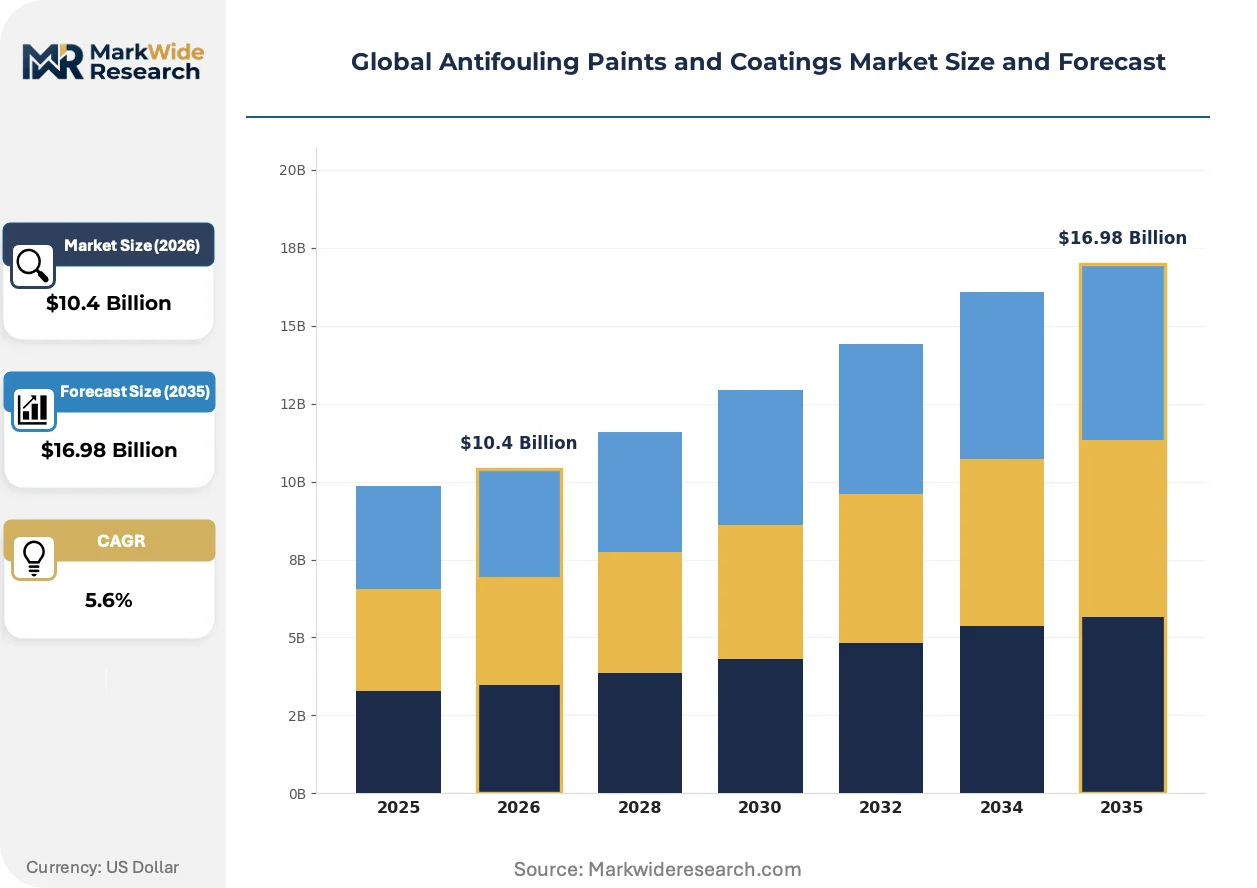
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $16.98 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Polishing Copolymer, Hard Antifouling, Hybrid, Non-Release, Silicone-Based Technology: Biocidal, Foul Release, Copper-Free, Epoxy, Fluoropolymer Application: Commercial Vessels, Military Crafts, Fishing Boats, Yachts, Submersibles End User: Shipbuilders, Aftermarket Service Providers, Port Authorities, Marine Contractors |
| Companies Covered | PPG Industries, Inc., Nippon Paint Marine Coatings Co., Ltd., AkzoNobel N.V., Kansai Paint Co., Ltd., The Sherwin-Williams Company, Hempel A/S, Chugoku Marine Paints, Ltd., BASF SE, Jotun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antifouling Paints and Coatings Market Shifts & Advancements
Marine coatings development is pivoting from biocidal defense to physical surface engineering, with controlled-release chemistry and smart application systems compressing traditional maintenance cycles. Three forces are restructuring competitive positioning.
Self-polishing copolymer technology is miniaturizing biocide release mechanisms through nanostructured polymer matrices that erode at predictable rates. Container line operators with 10,000+ TEU vessels are adopting these systems to extend dry-dock intervals beyond 60 months. The technology is miniaturizing the trade-off between coating longevity and environmental discharge compliance.
REACH authorization requirements for zinc pyrithione are forcing reformulation investments across European manufacturing footprints. The restriction timeline is accelerating copper-free platform development in Rotterdam and Hamburg port service networks. Nordic offshore vessel operators are now specifying silicone-based alternatives preemptively to avoid future compliance retrofit costs.
Fleet operators are consolidating coating procurement under long-term performance contracts that bundle application, monitoring, and maintenance. This unbundles traditional shipyard coating contracts and shifts margin capture toward integrated service providers. The model is most visible in Singapore and Dubai maritime clusters where port authorities are mandating hull condition transparency for berth allocation priority.
Global Antifouling Paints and Coatings Market Segmentation
Antifouling coatings segment by performance specification, regulatory compliance tier, and vessel operational profile. Each dimension carries distinct margin structures and certification requirements that shape procurement patterns across flag registries.
Product Type:
ECHA biocidal product regulation and IMO Anti-Fouling Systems Convention compliance timelines differentiate coating categories by active substance approval status and dry-dock retrofit urgency.
- Self-Polishing Copolymer:Controlled biocide release through hydrolyzable polymer matrices enables 60-month dry-dock intervals for container vessels. Container line operators with Shanghai and Guangzhou registry flags specify these systems to minimize fuel consumption penalties under Japan's METI efficiency mandates.
- Silicone-Based:Polydimethylsiloxane foul-release surfaces reduce hydrodynamic drag through low surface energy rather than biocidal action. Nordic offshore vessel operators and Singapore-flag service fleets adopt these systems preemptively to avoid copper discharge compliance costs.
- Hard Antifouling:Traditional insoluble matrix coatings with copper oxide loading remain specified for fishing boats in jurisdictions with extended ECHA approval timelines.
- Hybrid:Dual-layer systems combining biocidal primer with foul-release topcoat address transitional compliance requirements for vessels operating across multiple port state control regimes.
- Non-Release:Inert barrier coatings without active substance content serve specialized submersible applications where environmental discharge monitoring is continuous.
Established volume favors self-polishing copolymer systems; emerging adoption favors silicone-based alternatives.
Technology:
Formulation chemistry determines capital intensity, raw material sourcing, and regulatory pathway complexity across manufacturing footprints.
- Foul Release:Silicone and fluoropolymer matrices eliminate biocide discharge concerns entirely. Japanese coastal fleets and EU-flag offshore support vessels specify these technologies to satisfy tightening MEE and ECHA discharge standards without dry-dock cycle penalties.
- Copper-Free:Zinc pyrithione and organic booster biocide formulations capture specification share where heavy-metal restrictions constrain legacy portfolios. REACH authorization pressures in Rotterdam and Hamburg port networks accelerate platform development.
- Biocidal:Copper oxide and organotin-legacy systems retain cost-sensitive fishing boat and coastal cargo segments pending active substance reauthorization.
- Epoxy:High-build barrier primers provide substrate protection beneath active antifouling layers for vessels with extended immersion requirements.
- Fluoropolymer:Ultra-low surface energy variants command premium positioning in yacht and high-performance military craft specifications.
Biocidal chemistry retains installed-base dominance; copper-free platforms are climbing the fastest.
Application:
Vessel category determines coating performance requirements, inspection frequency, and specification authority concentration.
- Commercial Vessels:Container ships, tankers, and bulk carriers drive procurement scale through fleet renewal programs at Southeast Asian shipyards. Fuel efficiency regulations from IMO and Japan's METI mandate low-friction hull specifications for 10,000+ TEU vessels.
- Yachts:Aesthetics-critical applications favor fluoropolymer and silicone foul-release systems with high-gloss finish retention. Dubai and Singapore maritime clusters specify premium coating packages for superyacht newbuilds.
- Military Crafts:Naval specification regimes prioritize signature reduction and multi-year operational availability over commercial fuel efficiency metrics.
- Fishing Boats:Cost-constrained operators in China's provincial fleets balance copper-based legacy formulations against MEE discharge compliance timelines.
- Submersibles:Deep-immersion platforms require specialized coating systems with hydrostatic pressure resistance and extended cure schedules.
Commercial vessels anchor procurement volume; yacht specifications command the steepest margin premiums.
End User:
Procurement authority distribution and contract structure complexity vary sharply across customer categories.
- Shipbuilders:New construction yards in Shanghai, Guangzhou, and Southeast Asian corridors bundle coating specification into vessel construction contracts. State-led port infrastructure spending sustains large-scale procurement with multi-year supply agreements.
- Aftermarket Service Providers:Dry-dock operators in Singapore and Dubai maritime clusters consolidate coating application, inspection, and maintenance under performance-based contracts with outcome guarantees.
- Port Authorities:Rotterdam, Hamburg, and Japanese port regulators mandate hull condition transparency for berth allocation priority, creating specification pull for certified low-friction systems.
- Marine Contractors:Offshore installation and subsea service operators require specialized submersible coating systems with extended immersion cycle warranties.
Shipbuilders concentrate newbuild volume; aftermarket service providers are capturing specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE discharge standards in China anchor the dominant geography for antifouling coatings procurement. State-led port infrastructure spending around Shanghai and Guangzhou sustains large-scale fleet renewal programs. The analysis covers five countries where regulatory divergence and shipbuilding concentration reshape competitive positioning.
China
Shanghai and Guangzhou port corridors drive procurement scale through state-backed vessel construction subsidies. MEE certification timelines for copper-free formulations create dry-dock scheduling complexity for multi-flag operators. The Yangtze River Delta shipyards concentrate newbuild coating specification under multi-year supply agreements with integrated service providers.
Japan
METI fuel efficiency mandates pull specification demand for low-friction hull coatings across domestic coastal fleets. The Kansai region's Osaka-Kobe maritime cluster specializes in silicone foul-release application for offshore support vessels. Japanese shipyards prioritize REACH-compliant product portfolios to maintain European port access for export-bound newbuilds.
Germany
ECHA biocidal product regulation compresses formulation pipelines for copper oxide systems serving North Sea and Baltic fleets. Hamburg port authority tenders mandate hull condition transparency, creating specification pull for certified low-friction alternatives. The country's national chemical regulator extends active substance approval timelines, freezing legacy product commercialization.
Singapore
The maritime cluster consolidates coating procurement under performance-based contracts bundling application, monitoring, and maintenance. Port authority berth allocation rules prioritize vessels with documented hull condition transparency. Southeast Asian shipyard outsourcing funnels specification-grade demand through Singapore-based aftermarket service providers.
United States
EPA vessel general permit programs fragment compliance obligations for coatings operating across multiple flag registries. Gulf Coast shipyards serving offshore energy fleets specify specialized submersible systems with extended immersion warranties. California port authorities adopt discharge monitoring protocols that preempt federal standards for copper-based biocide restrictions.
Global Antifouling Paints and Coatings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the antifouling coatings market structure. The upper tier commands specification-grade positioning through global marine supply chains and REACH-compliant product portfolios. Specialist players anchor regional port service networks with silicone-based and copper-free formulation expertise. Competitive moves concentrate on strategic partnerships with shipyard operators and technology licensing for foul-release polymer engineering.
Among US-based diversified coatings manufacturers, PPG Industries, Inc. and The Sherwin-Williams Company occupy positions within the integrated leader tier through marine supply chain scale. Dutch-registered AkzoNobel N.V. exemplifies the European REACH-compliant specialist archetype. These three entities represent distinct geographic anchors for regulatory divergence strategies across OECD-flag fleet specifications.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Nippon Paint Marine Coatings Co., Ltd. |
| AkzoNobel N.V. |
| Kansai Paint Co., Ltd. |
| The Sherwin-Williams Company |
| Hempel A/S |
| Chugoku Marine Paints, Ltd. |
| BASF SE |
| Jotun |
| Others |
Supply & Pricing Matrix
Capacity utilization at Nordic silicone precursor facilities anchors price floors for foul-release formulations, compressing margins for second-tier manufacturers while rewarding integrated players with captive supply. This scale concentration shapes procurement leverage across Rotterdam and Singapore port service networks, where specification-grade positioning commands persistent premiums over commodity biocidal alternatives.
Pricing Analysis
Rotterdam-to-Singapore price spreads for silicone-based systems exceed those for copper oxide formulations, reflecting ECHA compliance certification premiums and specialized application labor. Three-tier pricing structure across premium foul-release, standard self-polishing copolymer, and economy hard antifouling levels segments buyer archetypes. Cost compression in copper-free tiers is intensifying because REACH authorization timelines extend active substance approval cycles. Fishing boat operators in China's provincial fleets exhibit highest price sensitivity, while Nordic offshore vessel operators prioritize fuel efficiency metrics over material cost.
Supply Chain Analysis
Baltic Sea transit corridors for silicone monomer feedstock underpin formulation security for European foul-release manufacturers. Manufacturing concentration centers on Germany, Japan, and China for advanced polymer precursors, with raw material portfolios drawing from copper oxide ore processing, polydimethylsiloxane synthesis, and zinc pyrithione active substance production. Single-source vulnerability in Nordic specialty chemical producers creates bottleneck exposure for scaling silicone-based alternatives. Distribution runs through shipyard-integrated service providers in Shanghai, Singapore, and Dubai maritime clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between Asian manufacturing hubs and European end-markets fragments competitive space, creating specialist niches for REACH-compliant formulation houses and MEE-certified application providers.
For Market Incumbents: Compound specification-grade positioning through backward integration into silicone precursor manufacturing, securing supply security against Nordic bottlenecks. Deepen port authority relationships in Rotterdam and Hamburg where hull condition transparency mandates concentrate procurement influence. Prioritize certification investment for copper-free platforms ahead of ECHA reauthorization timelines. For New Entrants and Emerging Players: MEE fast-track certification for copper-free formulations opens procurement access to China's Yangtze River Delta shipyards. Target Japan's coastal fleet retrofit cycle where METI efficiency mandates create specification pull for low-friction alternatives. Pursue joint development agreements with drone-based hull monitoring platforms to bundle predictive maintenance into coating service contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated service providers with silicone formulation expertise and port network density. The five-to-ten year viability window rewards acquisition of regional application specialists in Southeast Asian shipyard corridors. Watch ECHA biocidal product regulation approval velocity as the inflection signal for copper-free platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Precursor Backward Integration | Captive supply secures foul-release scaling capacity against Nordic bottlenecks. |
| REACH Compliance Certification Investment | Accelerates copper-free platform commercialization in Rotterdam and Hamburg networks. |
| Drone-Based Hull Monitoring Partnership | Enables outcome-based coating service models with predictive maintenance bundling. |
| Port Authority Performance Contracting | Consolidates specification influence through Singapore and Dubai berth allocation leverage. |
| Offshore Wind Vessel Coating Specialization | Addresses jack-up fleet demand for extended immersion cycle warranties in North Sea markets. |
Research Methodology
A spread of perspectives from marine coatings chemists, shipyard procurement directors, port authority technical officers, and regulatory affairs specialists converged on the working assumptions for formulation transition timelines. Primary field engagement with dry-dock operators in Shanghai, Singapore, and Rotterdam validated secondary intelligence from IMO convention documentation, ECHA biocidal product regulation filings, and customs trade data for copper oxide and silicone precursor flows. Bottom-up vessel fleet analysis and top-down coatings consumption estimates were triangulated against shipyard production schedules.
Product type, technology chemistry, vessel application category, and end-user procurement authority were modeled as core segmentation dimensions across the projection horizon. CAGRs were derived from regression analysis of historical fleet renewal patterns and regulatory compliance retrofit schedules. Forecast inputs incorporated MEE discharge standard enforcement intensity, ECHA active substance approval velocity, and METI fuel efficiency mandate adoption curves.
Underlying assumptions cover stable regulatory enforcement timelines and silicone precursor supply continuity, with deviation risk concentrated in ECHA authorization delays and copper price volatility. Practitioners should keep alternative scenarios live as MEE certification harmonization and IMO convention amendment cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Middle-East Paints and Coatings Market