
 Global Primer Market | 2026-2036
Global Primer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Primer Market Intelligence
Consolidation among large industrial end-users, particularly in the automotive and marine sectors, is rebalancing the competitive landscape for primer suppliers. The Sherwin-Williams Company leverages its extensive distribution network to serve both industrial and architectural segments. PPG Industries Inc. specializes in high-performance coatings for aerospace and automotive OEM applications. AkzoNobel NV sustains a strong position in marine and protective coatings through technological innovation.
A primer is a preparatory undercoat applied to materials before painting, designed to ensure better adhesion of the final coat. Its formulation creates a uniform surface, enhances durability, and offers protection against elements like corrosion. Water-based primers are gaining share over solvent-based types due to regulations on volatile organic compounds (VOCs). The construction sector constitutes a high-volume application, whereas automotive OEMs demand premium-priced, high-performance formulations.
Regulations such as the EU's REACH directive and rules set by the US Environmental Protection Agency (EPA) strictly limit VOC content in primers. In parallel, China's GB standards for coatings are aligning with these environmental benchmarks, impacting manufacturing processes. Future success for manufacturers depends on balancing the development of compliant, low-VOC water-based formulations with the high-performance demands of industrial end-users.
Market Dynamics
The primer market's evolution is governed by the tension between stringent environmental regulations demanding low-VOC formulations and the unyielding performance requirements of industrial end-users. This dynamic is forcing a fundamental shift in chemical formulation toward water-based and high-solids systems.
Growth Catalysts
- Regulatory Mandates:The EU's REACH framework and rules from the US Environmental Protection Agency (EPA) strictly limit VOCs, compelling a market-wide transition to compliant water-based or high-solids primers, particularly in the architectural and automotive refinish sectors.
- Infrastructure Investment:Massive infrastructure development and manufacturing expansion in China create sustained, high-volume demand for protective primers in construction, transportation, and heavy machinery applications to ensure asset longevity.
- Resin Technology Advancement:Innovations in acrylic and epoxy resin chemistry are improving the durability, adhesion, and application properties of water-based primers, making them increasingly suitable for demanding industrial environments previously dominated by solvent-based products.
Market Restraints
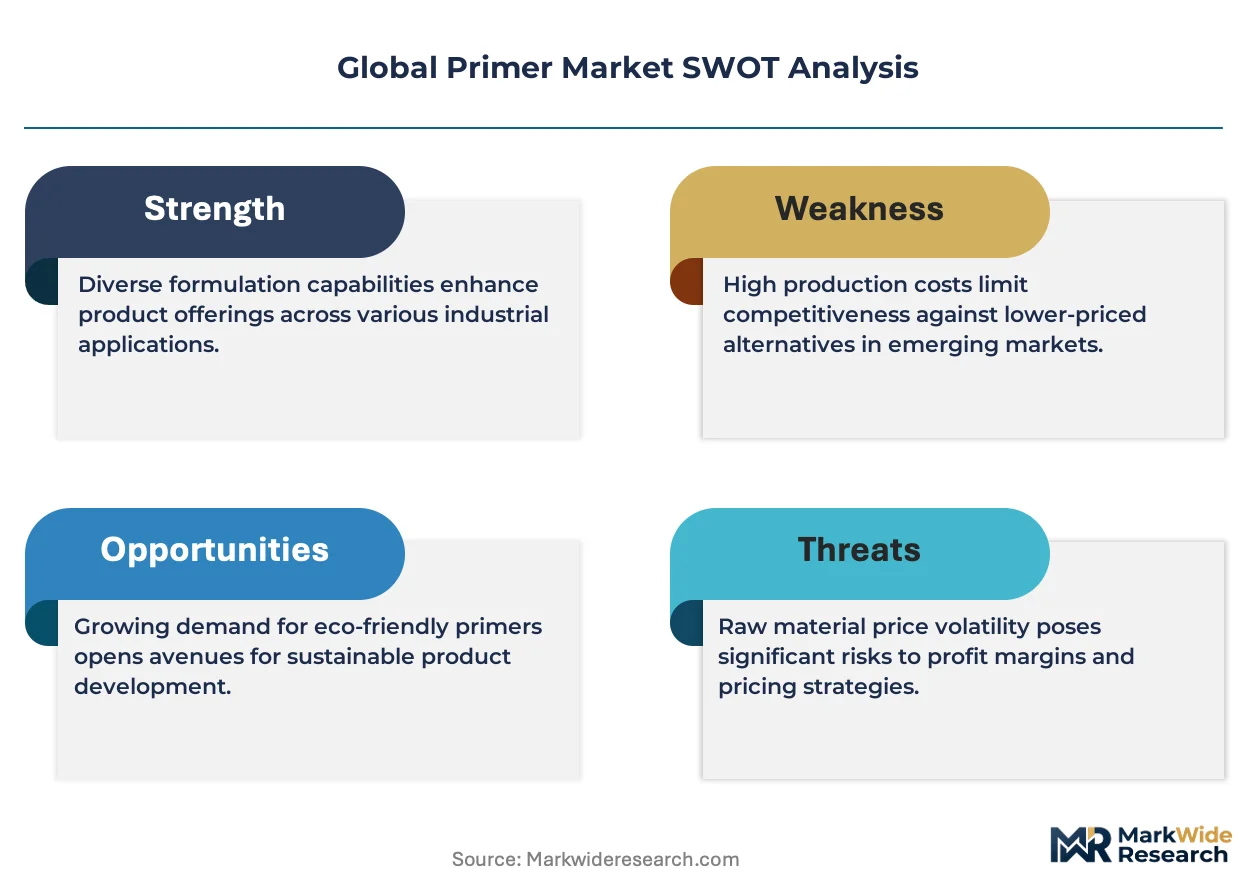
- Raw Material Price Volatility:Fluctuations in the cost of key inputs, especially titanium dioxide (TiO2), epoxy resins, and acrylic polymers, directly impact manufacturer margins and create pricing instability for end-users.
- Performance Gaps in Harsh Conditions:Certain high-performance water-based primers still exhibit limitations in adhesion and corrosion resistance under extreme conditions, such as saltwater exposure in marine applications, compared to traditional solvent-borne systems.
- Substitution from Integrated Materials:The increasing use of pre-treated metals, composites, and plastics that do not require a separate primer coat in sectors like automotive and consumer electronics presents a long-term substitution threat.
Strategic Opportunities
- Bio-Based Formulations:Developing primers from renewable, bio-based feedstocks presents an opportunity to meet corporate sustainability goals and appeal to environmentally conscious customers, moving beyond simple VOC reduction to address full lifecycle impact.
- Functional and Smart Coatings:There is an emerging market for primers with integrated functionalities, such as self-healing capabilities to repair minor scratches or thermal-insulating properties for energy efficiency in buildings.
- Expansion in Southeast Asia:Rapid industrialization and construction growth in countries like Vietnam and Indonesia offer new geographic markets for primer manufacturers, especially for protective and architectural coatings.
Industry Challenges
- Reformulation and Certification Costs:The significant investment and time required to reformulate entire product lines to meet new environmental standards, such as China's GB standards, and secure necessary certifications pose a major operational hurdle.
- Application Equipment Transition:Shifting from solvent-based to water-based systems often requires end-users in sectors like auto body repair and furniture manufacturing to invest in new spray equipment and facility ventilation, slowing adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Primer Market |
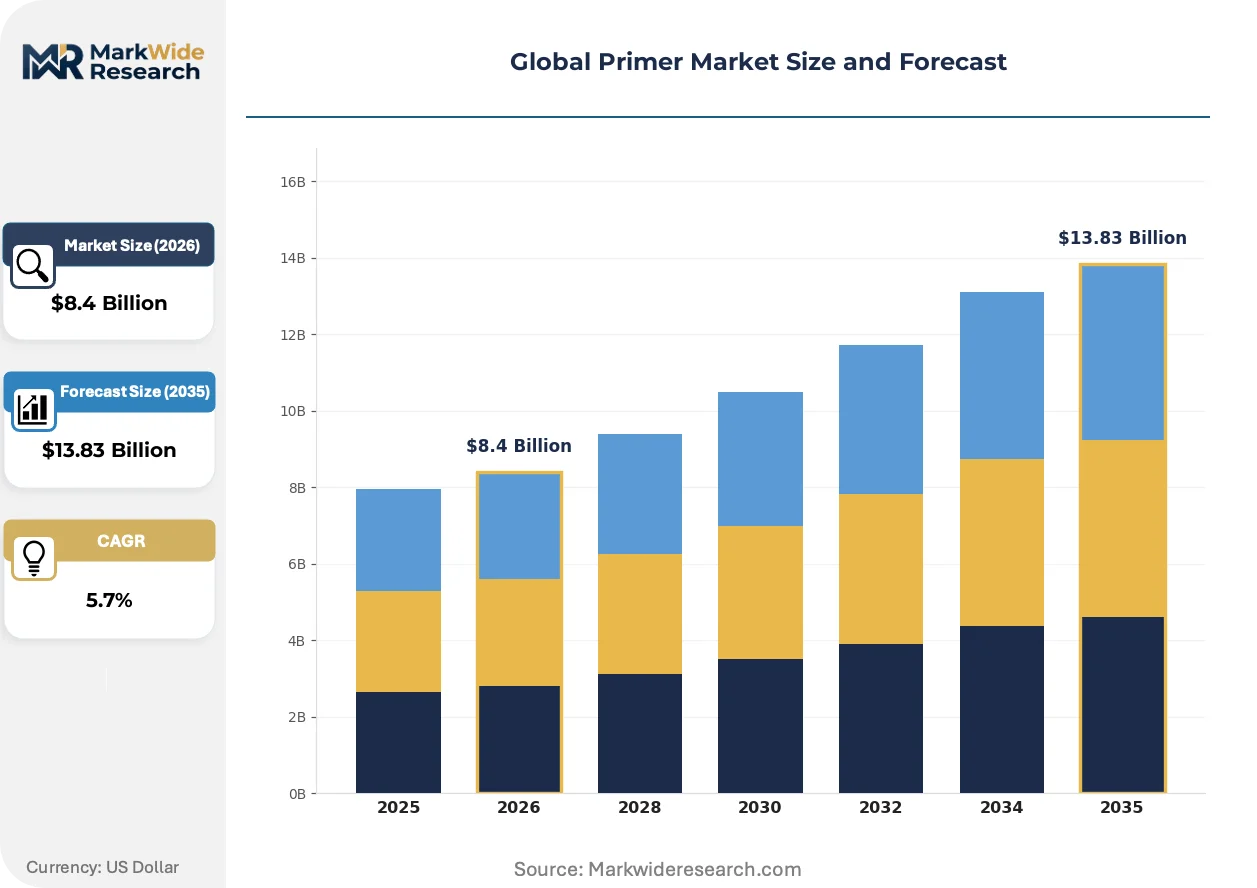
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Epoxy, Acrylic, Polyurethane, Alkyd Application: Construction, Automotive OEMs, Marine Coatings, Aerospace, Wood Finishing, Protective Coatings End User: Industrial Manufacturers, Vehicle Assemblers, Shipyards, Aircraft Fabricators, Furniture Producers, Infrastructure Developers Technology: Spray, Roll-On, Brush, Dip Coating, Electrodeposition, Powder Coating |
| Companies Covered | AkzoNobel NV, The Sherwin-Williams Company, Axalta Coating Systems LLC, PPG Industries Inc., BASF SE, Jotun Group, Asian Paints Ltd, Nippon Paint Holdings, Kansai Paint Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Primer Market Strategic Shifts & Innovations
Innovation in the primer market is reshaping product capabilities to meet a dual mandate of environmental compliance and enhanced performance. This is driving a move toward specialized formulations that deliver functional benefits beyond simple adhesion, altering how surfaces are prepared and protected.
Multi-functional primers that integrate several properties into a single coat represent a significant product evolution. Automotive and aerospace maintenance sectors are adopting these advanced formulations to shorten processing times. This technology is unifying previously distinct preparatory and protective layers, thereby compressing production schedules and reducing overall material consumption.
The EU Green Deal and its associated chemical strategies are creating a stricter regulatory environment for coating ingredients. This policy framework is forcing manufacturers to prove the safety and sustainability of their raw materials, leading to the deselection of certain additives and solvents. The marine and protective coatings segments are most impacted, accelerating research into alternative, compliant anti-corrosion agents.
Consolidation among large industrial end-users is altering purchasing behavior. Major automotive and aerospace OEMs are reducing their number of approved suppliers and seeking global partners who can guarantee consistent product quality and technical support across all manufacturing sites. This shift is most prominent in North America and Europe, where supply chain simplification is a key strategic priority.
Global Primer Market Segmentation
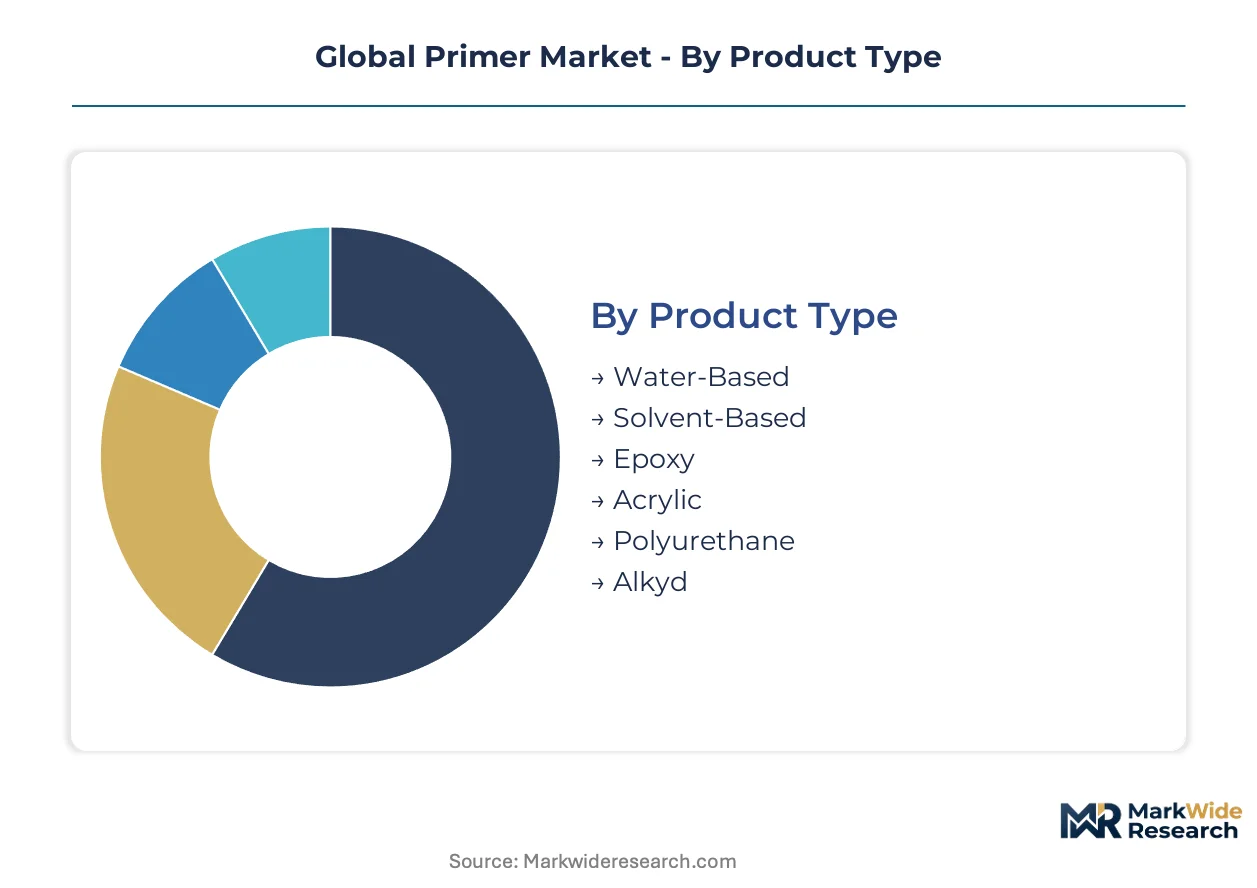
Understanding the primer market's segmentation reveals the diverse demands shaping product development and regulatory compliance. Distinct formulations serve specific applications, driven by performance requirements, environmental mandates, and end-user preferences. Analyzing these segments provides clarity on market dynamics and strategic opportunities for manufacturers.
Product Type:
The certification burden heavily influences product type selection, with various primer formulations requiring specific approvals from bodies like the US Environmental Protection Agency (EPA) and compliance with the EU's REACH framework.
- Water-Based:These formulations utilize water as the primary solvent, significantly reducing volatile organic compound (VOC) emissions. Demand concentrates in architectural and automotive refinish sectors due to stringent environmental regulations in Germany and California.
- Epoxy:Epoxy primers are thermosetting polymer formulations known for exceptional adhesion, chemical resistance, and durability. Infrastructure development in China and marine applications in Japan drive demand for these high-performance protective coatings.
- Solvent-Based:Offers robust performance where specific properties are paramount.
- Acrylic:Provides good adhesion and flexibility for construction surfaces.
- Polyurethane:Excellent abrasion resistance and flexibility for automotive and aerospace.
- Alkyd:Oil-based, providing good adhesion and corrosion resistance for metal and wood.
Water-Based primers sit at the top of the volume ranking, with Acrylic formulations climbing the fastest.
Application:
Volume and performance demands dictate the specific primer application, often requiring tailored formulations to meet durability and aesthetic criteria.
- Construction:This segment involves large-scale application on various building materials, including concrete, steel, and wood, to enhance paint adhesion and substrate protection. Massive infrastructure projects in China and residential development in India create sustained demand.
- Automotive OEMs:Primers for original equipment manufacturers (OEMs) demand high-performance, corrosion-resistant, and aesthetically critical formulations for vehicle bodies. Strict quality control and global supply chain requirements characterize procurement for manufacturers in Germany and the US.
- Marine Coatings:Protects ships from saltwater exposure and corrosion with specialized properties.
- Aerospace:High-performance primers ensure adhesion and corrosion protection for aircraft components.
- Wood Finishing:Prepares wood surfaces for topcoats, enhancing durability and smooth finishes.
- Protective Coatings:For heavy-duty industrial equipment, offering long-term corrosion and chemical resistance.
Automotive OEMs command premium pricing due to specialized performance, while Construction applications drive the largest overall volume.
End User:
Procurement patterns vary significantly among end-users, influencing the scale and technical support required from primer suppliers.
- Industrial Manufacturers:These users, spanning diverse sectors from machinery to electronics, require primers for component protection and surface preparation before assembly or finishing. Consolidation among large industrial end-users in Germany impacts supplier relationships.
- Infrastructure Developers:This segment includes entities involved in large-scale public and private projects, demanding primers for bridges, roads, and utilities to ensure long-term durability. Government-backed initiatives in India and Brazil drive significant volume.
- Vehicle Assemblers:Utilize primers as a critical step in vehicle painting processes.
- Shipyards:Apply specialized primers to marine vessels for corrosion protection.
- Aircraft Fabricators:Rely on high-performance primers for aerospace-grade adhesion.
- Furniture Producers:Use primers to prepare materials for finishing, enhancing quality.
Specialized needs of Aircraft Fabricators drive bespoke product development, while Infrastructure Developers prioritize cost-effectiveness for large-volume procurement.
Technology:
Application efficiency and precision are paramount, with distinct technologies optimizing primer delivery for various substrates and performance requirements.
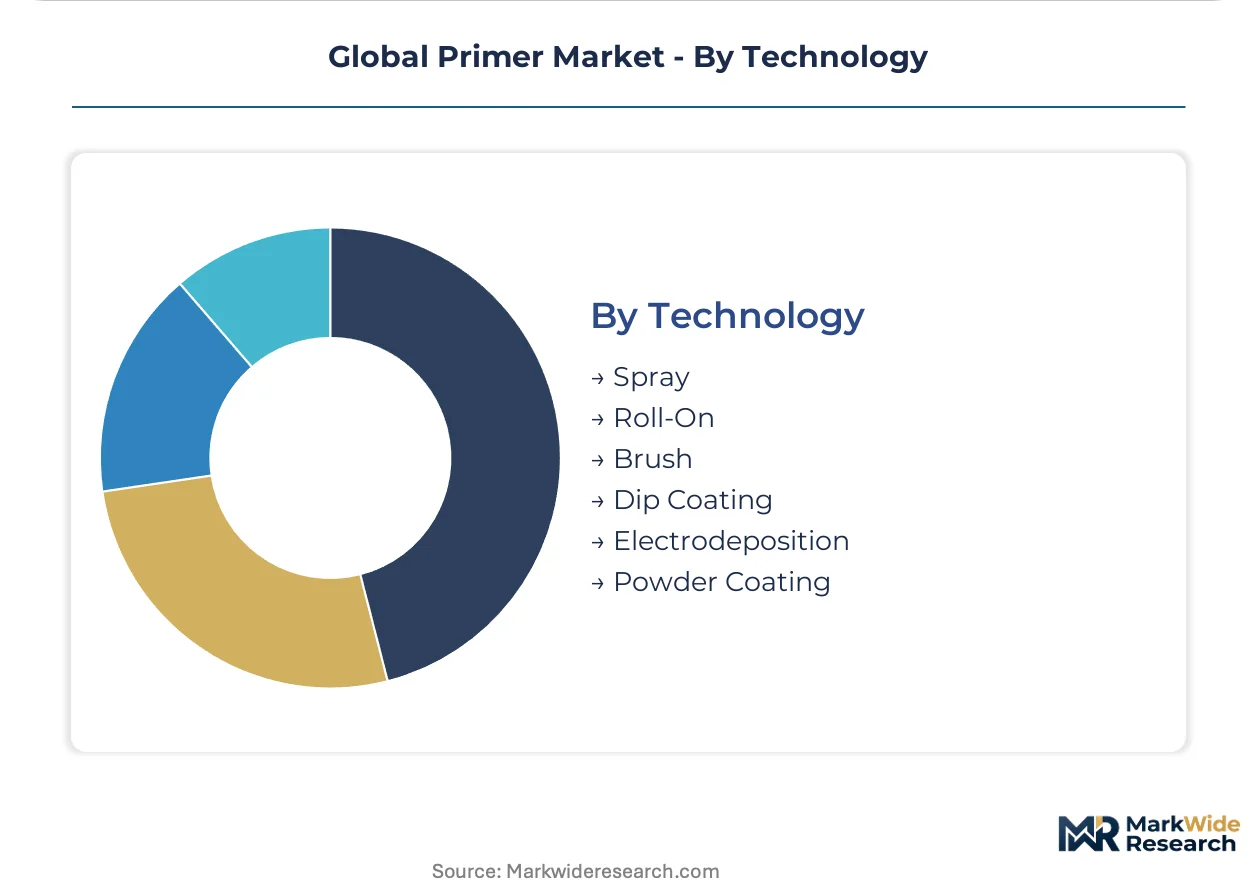
- Spray:This widely used method involves atomizing primer into fine droplets for even coating across large or complex surfaces. Automated spray lines in automotive manufacturing in the US and manual application in construction are common.
- Electrodeposition:Also known as E-coat, this process applies a uniform primer layer to conductive substrates by immersing them in a primer bath and applying an electric charge. This technology is critical for automotive body corrosion protection in Japan.
- Roll-On:Manual application with rollers, common for architectural and DIY projects.
- Brush:Provides precise application for detailed work, edges, or smaller areas.
- Dip Coating:Submerging components ensures complete coverage for intricate geometries.
- Powder Coating:Dry finishing applies powdered primer electrostatically, offering durability.
Powder Coating technologies advance sustainability goals, while Electrodeposition ensures superior corrosion resistance for critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China's extensive infrastructure projects drive significant volume demand for primers, Germany's market prioritizes specialized low-VOC formulations due to stringent environmental regulations. This regional contrast shapes product development and market penetration strategies for global primer manufacturers. Different regulatory frameworks and industrial concentrations influence primer consumption patterns across key geographies.
China
Massive infrastructure development and manufacturing expansion create sustained, high-volume demand for protective primers. China's GB standards for coatings are aligning with global environmental benchmarks, impacting local production. The Yangtze River Delta region, with its dense industrial and construction activity, represents a major consumption hub for various primer types.
United States
The US market sees strong demand from both the construction sector and automotive OEMs, particularly for high-performance and low-VOC primers. Regulations from the US Environmental Protection Agency (EPA) strictly limit VOC content, especially in states like California. Automotive manufacturing clusters in Michigan and the Southeast drive significant procurement for specialized primer formulations.
Germany
Stringent environmental regulations, including the EU's REACH framework, compel a market-wide transition to compliant water-based and high-solids primers. The automotive and industrial sectors in Germany demand high-performance coatings with reduced environmental impact. Major chemical and automotive industry centers in North Rhine-Westphalia and Bavaria are focal points for innovative primer development and application.
India
Rapid urbanization and residential development projects generate substantial demand for construction primers, particularly for architectural applications. Government-backed infrastructure initiatives further contribute to the volume demand for protective coatings. Industrial growth in states like Maharashtra and Gujarat fuels the need for primers in manufacturing and fabrication.
Japan
Automotive and marine applications are key demand drivers for high-performance primers in Japan, emphasizing durability and corrosion resistance. Strict JIS standards ensure quality control and performance benchmarks for coating materials. Automotive production hubs in the Kanto and Chubu regions utilize advanced electrodeposition primers for superior vehicle body protection.
Global Primer Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a dynamic market structure for primer suppliers. The competitive landscape features global coatings giants alongside regional manufacturers catering to specific local demands. Strategic archetypes include large-scale industrial suppliers and niche providers of advanced functional primers. Companies typically engage in portfolio diversification and geographic expansion to strengthen their market presence.
Global coatings specialists like The Sherwin-Williams Company and AkzoNobel NV represent the diversified archetype, leveraging extensive distribution networks and broad product portfolios. PPG Industries Inc. further exemplifies this trend, focusing on high-performance coatings for demanding sectors such as aerospace and automotive OEM applications. These companies often anchor premium-tier offerings, providing comprehensive solutions and technical support across multiple industrial and architectural segments.
| Leading Market Players |
|---|
| AkzoNobel NV |
| The Sherwin-Williams Company |
| Axalta Coating Systems LLC |
| PPG Industries Inc. |
| BASF SE |
| Jotun Group |
| Asian Paints Ltd |
| Nippon Paint Holdings |
| Kansai Paint Co. Ltd |
Cost & Logistics Intelligence
Titanium Dioxide price fluctuations cascade through the primer supply chain, directly influencing cost structures and subsequent pricing tiers for end-users. This volatility impacts manufacturers' margins and the final product cost across various applications.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-volume primer formulations. The dominant pricing model for industrial primers is contract-based long-term offtake, while architectural primers often follow a tiered premium-mid-economy differentiation. Price differentiation stems from quality grade, adherence to specific certifications like EU REACH, and the volume scale of procurement. Pricing softness for standard formulations reflects intense competition among regional suppliers, making construction applications highly price-sensitive. Automotive OEMs, however, prioritize performance over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the primer market's downstream logistics. Supply concentration for key raw materials like titanium dioxide, epoxy resins, and acrylic polymers largely originates from China and specialized chemical producers in Germany and the US. Raw material price volatility represents a significant structural risk, impacting manufacturing costs globally. Direct sales channels serve large industrial manufacturers, while extensive distributor networks manage the fragmented architectural and automotive refinish segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global primer market functions as a regulatory compounder, with the EU's REACH framework driving significant demand for compliant, low-VOC formulations. This regulatory push accelerates innovation towards sustainable product development and application efficiency.
For Market Incumbents: Anchor existing market share by expanding water-based product portfolios and investing in advanced resin technology. Incumbents should deepen vertical integration into key raw materials to mitigate supply chain volatility and consolidate smaller regional players to expand geographic reach in Southeast Asia. The threat of substitution from integrated materials, such as pre-treated metals, necessitates continuous R&D into multi-functional primers. Certification investment for new low-VOC formulations, particularly for China's GB standards, is a critical lever for sustained growth.
For New Entrants and Emerging Players: Bio-based formulations offer a technology-first wedge into the primer market, appealing to environmentally conscious customers. Target niche applications requiring specialized functional coatings, such as self-healing or thermal-insulating primers, and expand into rapidly industrializing regions like Vietnam. The architectural segment in developing economies presents the most penetrable market for cost-effective, compliant water-based solutions. A go-to-market angle focused on lifecycle sustainability and reduced environmental footprint can differentiate offerings.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing proprietary low-VOC resin technologies or unique application expertise. The market demonstrates long-term viability over the next 5-10 years, driven by evolving regulatory mandates and infrastructure growth. Acquisition targets should include firms with established certification portfolios for water-based epoxy or acrylic primers, particularly those serving automotive OEM or marine segments. The signal to watch is the accelerated adoption rate of advanced electrodeposition technologies in new industrial applications beyond automotive.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Shifts production processes to reduce environmental impact, aligning with EU Green Deal objectives for chemical strategies. |
| Capacity Expansion | Increases output of water-based primers to meet growing demand from China's infrastructure projects. |
| Long-term Supply Agreement | Secures stable access to critical raw materials like titanium dioxide, mitigating price volatility for manufacturers. |
| Joint Venture | Facilitates market entry and technology transfer for specialized functional coatings in Southeast Asian markets. |
| Certification Investment | Ensures product compliance with stringent regulations like the US EPA and China's GB standards, enabling market access. |
Research Approach
Multiple input streams—primary interviews, industry association reports, and government environmental agency publications—were reconciled to build a comprehensive data foundation. Primary research involved conversations with R&D directors, procurement leads from automotive OEMs, plant managers, and regulatory affairs specialists across key geographies. Secondary validation drew from customs/trade data, company annual reports, and technical journals. This approach utilized both bottom-up market sizing and top-down validation to ensure accuracy.
The data-stream reconciliation process underpinned an analytical framework designed to project market dynamics across the analysis window. Segmentation dimensions modeled included product type, application, end-user, technology, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends, projected demand influenced by infrastructure investment, and anticipated regulatory shifts. Key forecast inputs included projected construction spending in China and the US EPA's future VOC reduction targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility and evolving environmental regulations. These forecasts reflect assumptions regarding global economic stability and continued infrastructure development. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
ASEAN Paints and Coatings Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Automotive OEM Coatings Market