
 Fluorescent Paint Market | 2026-2036
Fluorescent Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescent Paint Market Analysis
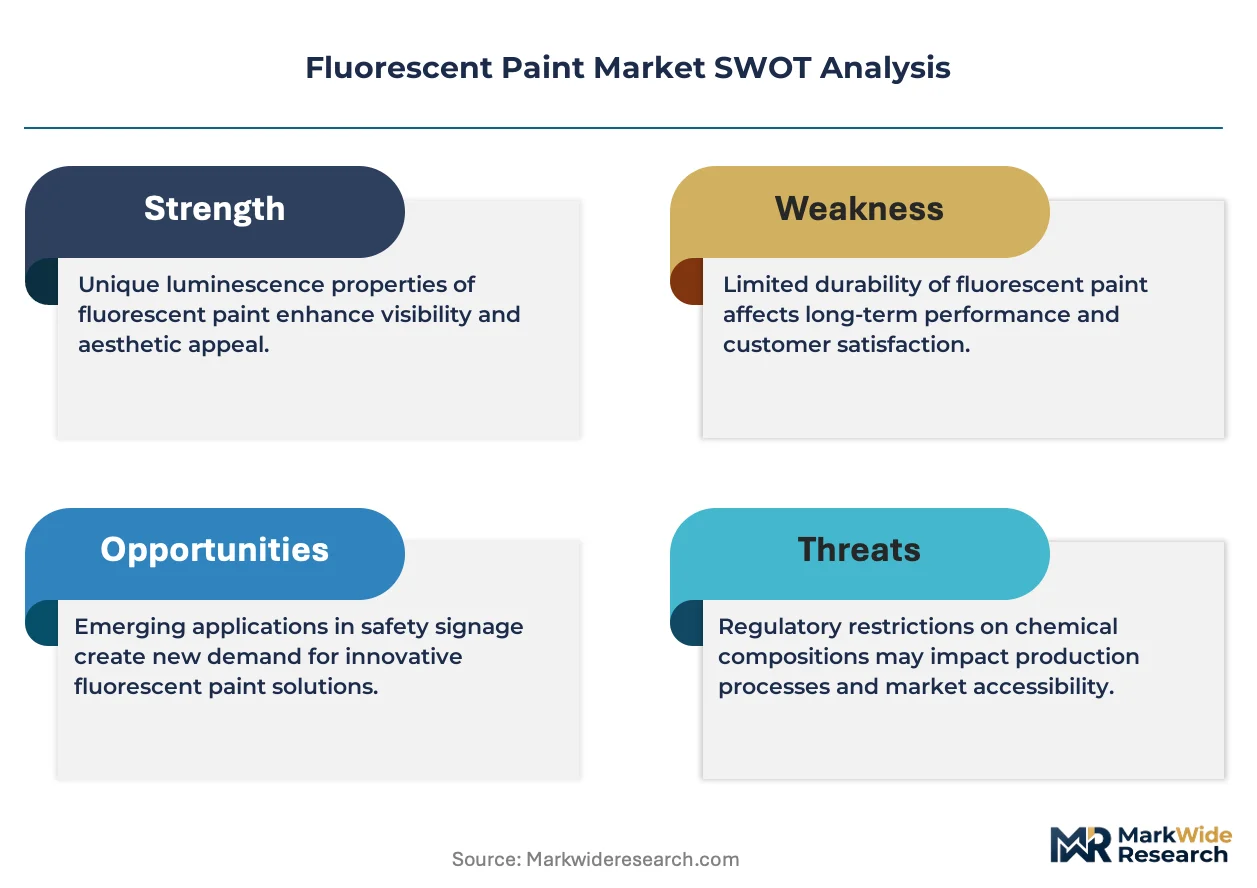
Transportation infrastructure is realigning fluorescent paint procurement priorities as highway authorities and transit operators prioritize high-visibility safety markings over decorative applications. Day-Glo Color Corp leverages its historic pigment expertise to dominate North American supply chains for road marking materials. Radiant Color N.V. anchors European demand through specialized photoluminescent formulations that meet stringent environmental standards. SINLOIHI competes across Asia-Pacific markets by sustaining manufacturing scale in solvent-based and water-based product lines simultaneously.
Fluorescent paint is a coating system incorporating daylight-fluorescent pigments that absorb ultraviolet radiation and re-emit visible light at wavelengths between 520 and 580 nanometers, creating apparent luminosity beyond surface reflectivity; manufacturers disperse these organic dye complexes into acrylic, alkyd, or polyurethane resin matrices to achieve adhesion, weatherability, and color saturation for safety signaling, artistic expression, and industrial identification. Acrylic formulations lead product type demand due to faster drying times and compatibility with low-VOC regulatory thresholds, while water-based variants represent the fastest-expanding margin pool as environmental compliance tightens across industrialized economies. Spray formats occupy a specialized niche in maintenance and touch-up applications where field application speed outweighs bulk coating efficiency.
EPA regulations under the National Volatile Organic Compound Emission Standards for Architectural Coatings constrain solvent-based product distribution in the United States, while REACH and the EU Green Deal accelerate phase-outs of hazardous pigment precursors across European manufacturing. China's MEE enforces GB standards limiting aromatic solvent content, reshaping formulation requirements for both domestic producers and import-dependent buyers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional product customization delivers superior compliance economics.
Market Dynamics
Water-based reformulation is absorbing capital allocation across the fluorescent paint sector as REACH, EPA, and China's MEE collectively tighten volatile organic compound thresholds, forcing manufacturers to rebuild resin platforms around acrylic emulsions.
Growth Catalysts
- Transportation infrastructure mandates:Highway authorities in the United States and Germany are expanding high-visibility safety marking programs for tunnels, bridges, and cycling corridors.
- REACH pigment phase-outs:ECHA restrictions on hazardous precursors are accelerating certified reformulation demand among European industrial coating buyers.
- Entertainment venue construction:China's urban development clusters in Chengdu, Wuhan, and Xi'an are driving sustained consumption of theatrical and architectural fluorescent coatings.
Market Restraints
- Raw material concentration:Daylight-fluorescent pigment synthesis depends on specialized aromatic intermediates concentrated among German and Chinese chemical suppliers.
- Performance gaps in water-based systems:Acrylic emulsions still exhibit inferior weatherability versus solvent-borne alkyds in extreme humidity or freeze-thaw cycles.
- Substitution by retroreflective sheeting:3M and Avery Dennison films are displacing paint in permanent road marking applications where durability requirements exceed coating lifecycles.
Strategic Opportunities
- India's industrial corridor expansion:Delhi-Mumbai and Bengaluru-Chennai infrastructure projects remain underpenetrated for certified safety marking systems.
- Photoluminescent hybrid formulations:Convergence of daylight-fluorescent and phosphorescent technologies enables dual-mode visibility products for emergency egress systems.
- E-commerce specification channels:Direct-to-contractor platforms are fragmenting traditional distributor control over maintenance and touch-up volumes.
Industry Challenges
- Formulation chemist scarcity:Expertise in daylight-fluorescent pigment dispersion and resin compatibility resides with a shrinking cohort of specialized coatings scientists.
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and GB standard compliance extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescent Paint Market |
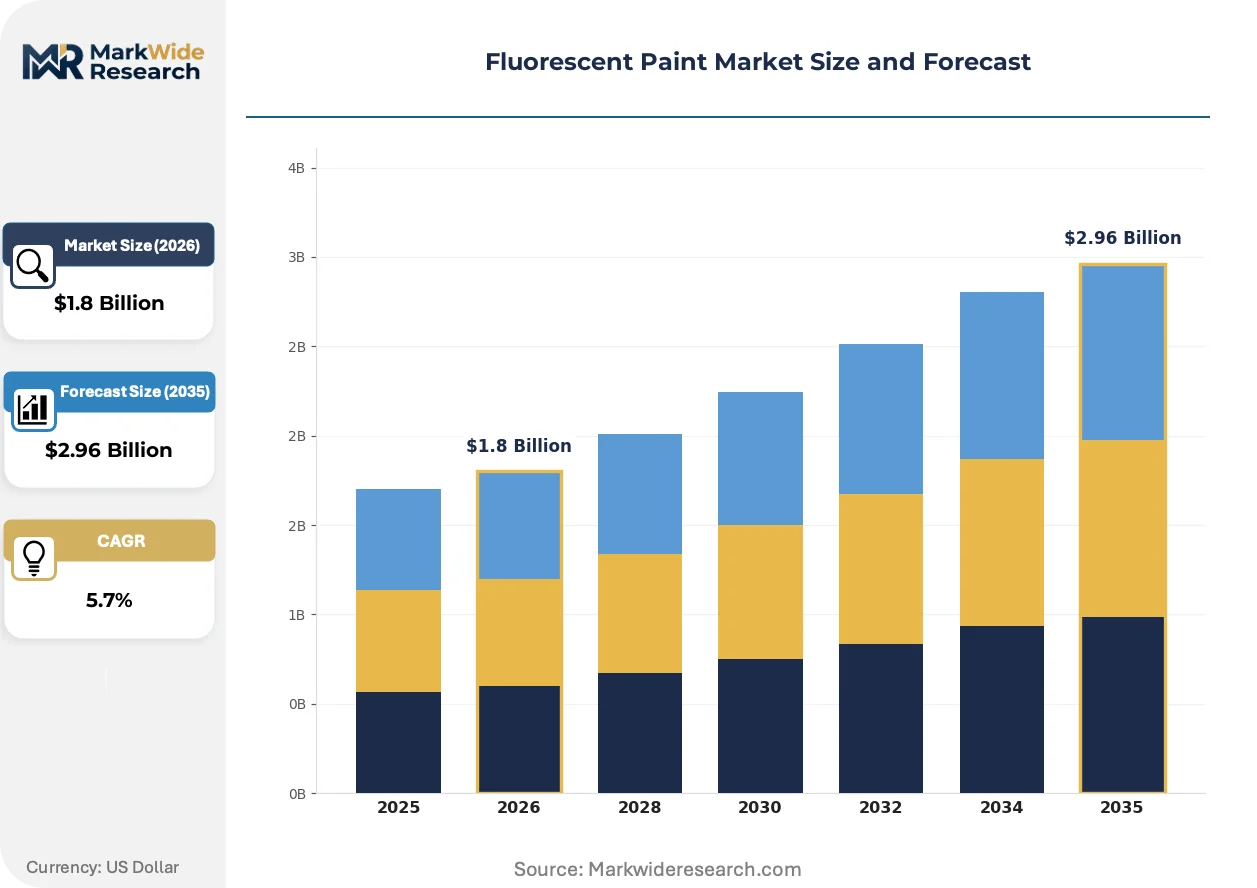
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Water-Based, Oil-Based, Spray Application: Decorative, Safety Markings, Art Supplies, Industrial Use End User: Artists, Construction, Transportation, Entertainment Distribution Channel: Online Retail, Specialty Stores, Wholesale, DIY Outlets |
| Companies Covered | Day-Glo Color Corp, Radiant Color N.V., SINLOIHI (Dai Nippon Toryo), Wanlong Chemical Co., Ltd., Luminochem, Vicome Corp, Hangzhou Aibai Chemical Co., Ltd., Brilliant Group Inc., Dane Color, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescent Paint Market Emerging Trajectories
Reformulation chemistry, regulatory harmonization pressures, and procurement decentralization are restructuring how fluorescent paint reaches end-users. Manufacturers now compete on compliance velocity rather than color breadth alone.
Waterborne acrylic-fluorescent hybrids are absorbing technical development resources across major formulators. These systems achieve sub-50 g/L VOC content while maintaining chromatic saturation for safety applications. Municipal procurement offices in California and the Netherlands are specifying these platforms exclusively. The technology is absorbing share from alkyd-based alternatives in interior marking segments where humidity exposure remains moderate.
REACH Annex XVII expansions are forcing pigment precursor substitutions across European manufacturing. ECHA's 2023-2024 candidate list updates targeted specific aromatic amines used in yellow-green fluorescent synthesis. German and Dutch coating producers are accelerating in-house synthesis of compliant alternatives. Water-based product lines are capturing disproportionate investment as solvent-borne pathways face structural regulatory risk.
Specification authority is migrating from centralized procurement offices to site-level maintenance supervisors. Large infrastructure operators in the United States and China are unbundling coating selection from master contractor agreements. Direct distributor relationships and mobile-enabled ordering platforms are replacing traditional three-tier distribution. This pattern concentrates in transportation authorities managing distributed asset networks across multiple climate zones.
Fluorescent Paint Market Segmentation
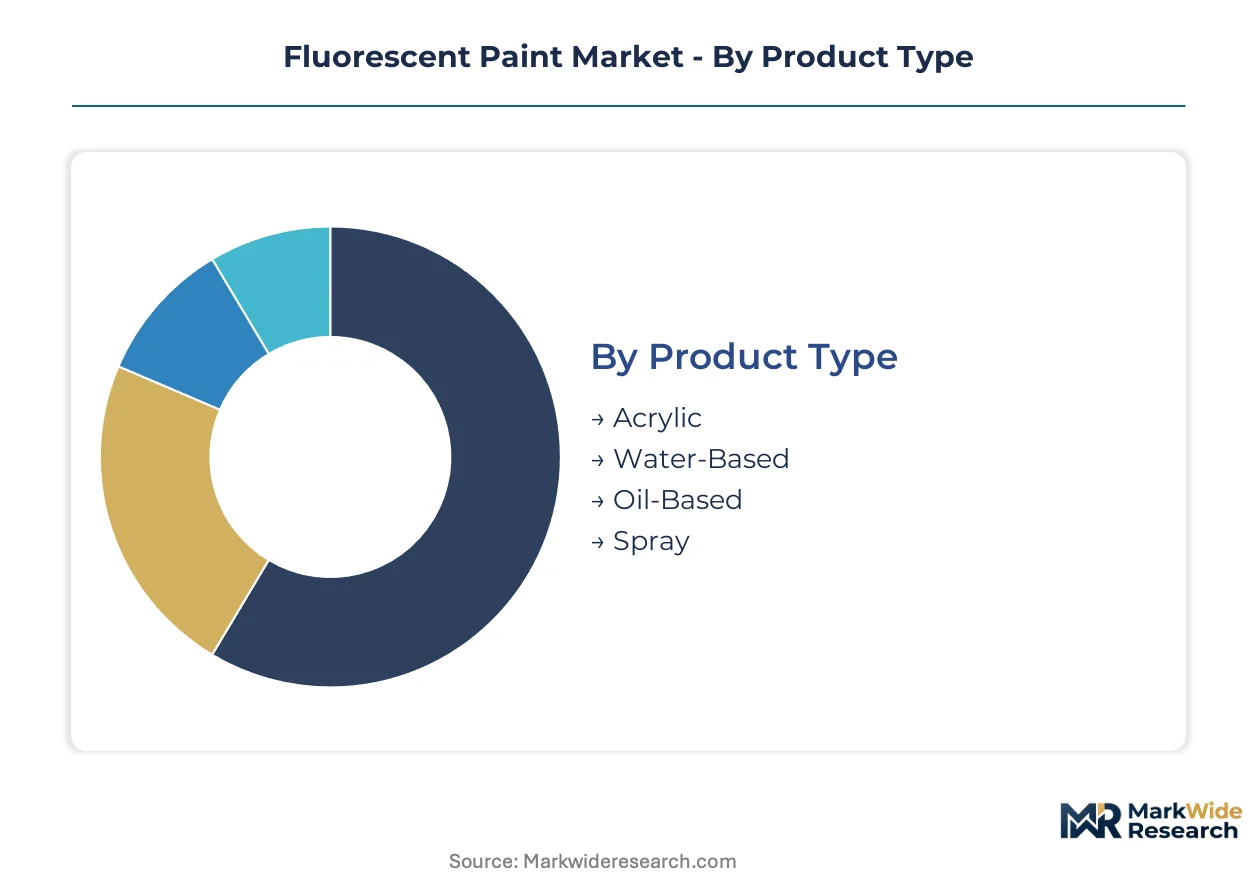
Fluorescent paint segmentation reveals how formulation chemistry, application environment, and procurement authority intersect to determine margin capture. Manufacturers must align resin platforms with regulatory thresholds while matching distribution formats to end-user technical sophistication.
Product Type:
Resin chemistry and carrier systems define performance ceilings, regulatory compliance pathways, and application economics across industrial and consumer markets.
- Acrylic:Thermoplastic resin matrices disperse daylight-fluorescent pigments with rapid ambient cure and UV stability for exterior safety markings. Municipal procurement offices in California and the Netherlands specify acrylic platforms exclusively for tunnel and cycling infrastructure where sub-50 g/L VOC thresholds apply.
- Water-Based:Acrylic emulsion carriers achieve chromatic saturation without aromatic solvents, absorbing disproportionate capital allocation as REACH, EPA, and China's MEE tighten emission standards. Performance gaps persist in extreme humidity or freeze-thaw cycles versus solvent-borne alternatives.
- Oil-Based:Alkyd resin formulations retain weatherability leadership in permanent exterior installations where coating lifecycle exceeds seven years.
- Spray:Aerosol or compressed-air delivery systems concentrate in maintenance and touch-up applications where field speed outweighs bulk efficiency.
Mature deployment sits with Oil-Based systems. Newer deployment is concentrated in Water-Based reformulations.
Application:
Functional requirements separate decorative color expression from regulated safety signaling, with divergent specification authority and compliance burdens.
- Safety Markings:High-visibility coatings for transportation infrastructure must meet retroreflectance and chromaticity standards under CIE 15:2004. Highway authorities in Germany and the United States are expanding tunnel, bridge, and cycling corridor marking programs.
- Decorative:Architectural and interior design applications prioritize aesthetic saturation over regulatory certification, with demand clustering in China's entertainment venue construction in Chengdu, Wuhan, and Xi'an.
- Art Supplies:Fine-art and craft formulations emphasize pigment load and lightfastness for studio and educational use.
- Industrial Use:Equipment identification and hazard coding require chemical resistance and adhesion to metal substrates in manufacturing environments.
Specification authority concentrates with Safety Markings. Volume expansion is climbing fastest in Decorative segments.
End User:
Procurement sophistication and technical specification capacity vary sharply across creator-driven, project-based, and institutional buyer categories.
- Transportation:Highway authorities and transit operators maintain centralized coating specifications with multi-year performance warranties and certified contractor networks.
- Construction:General contractors and specialty trades purchase through distributor relationships with project-scale volume pricing.
- Entertainment:Theatrical designers and venue operators source through specification channels for architectural and stage applications.
- Artists:Individual creators and educational institutions buy through retail and direct-to-consumer platforms with formulation transparency demands.
Contract value peaks with Transportation. Transaction velocity is expanding most quickly through Entertainment procurement.
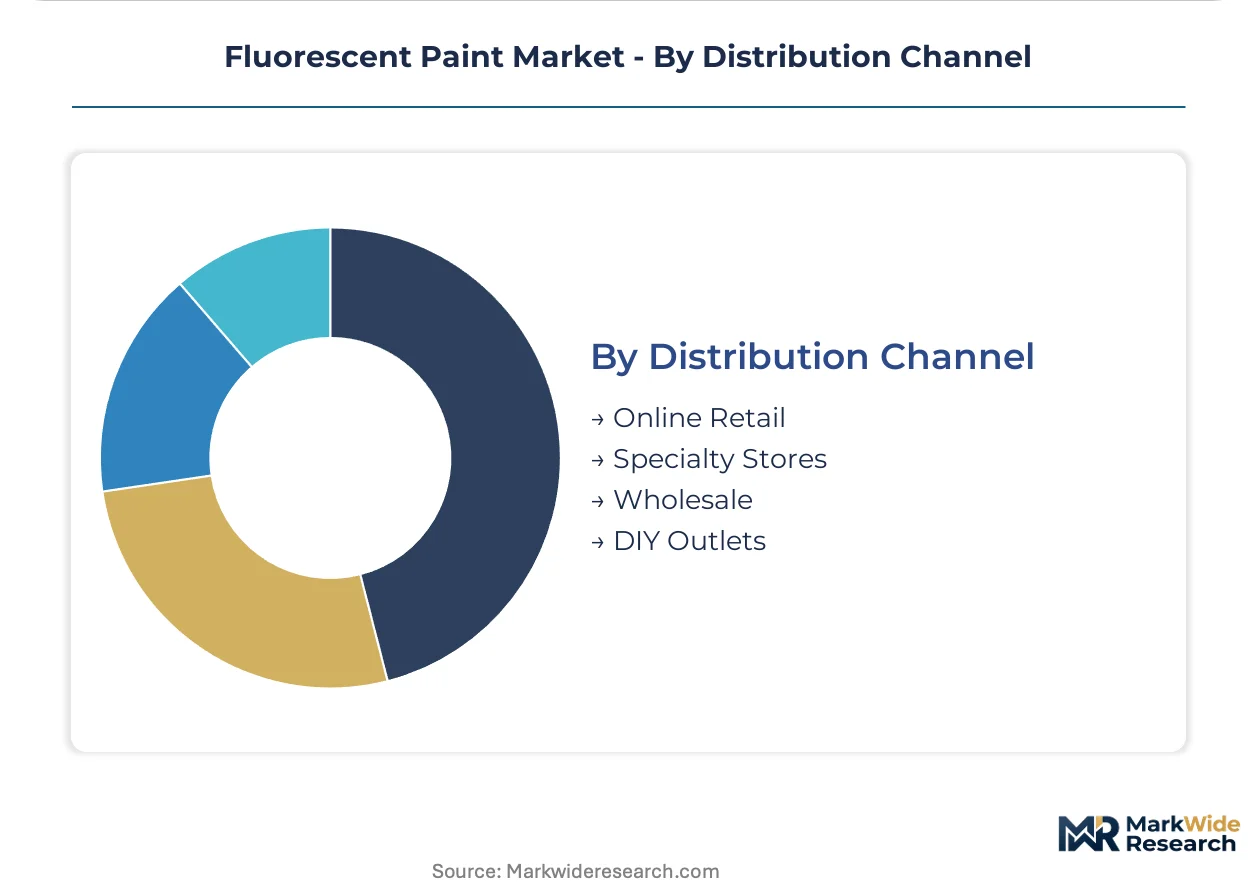
Distribution Channel:
Channel selection determines margin retention, technical support obligation, and access to specification authority at site or project level.
- Wholesale:Bulk supply to contractors and industrial accounts maintains volume concentration with compressed margins and limited technical service.
- Specialty Stores:Professional coating retailers offer color matching, substrate consultation, and certified product access for specification-driven buyers.
- Online Retail:Direct-to-contractor platforms fragment traditional distributor control over maintenance and touch-up volumes with mobile-enabled ordering.
- DIY Outlets:Mass-market retailers serve consumer and light commercial segments with standardized color ranges and self-service selection.
Relationship depth remains strongest through Specialty Stores. Digital penetration is gaining share fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal special economic zones concentrate fluorescent paint manufacturing capacity, while regulatory divergence across major economies forces formulators to maintain parallel product lines for compliance.
United States
Highway authorities in California and Texas are expanding tunnel and cycling corridor marking programs with sub-50 g/L VOC specifications. EPA enforcement under the National Volatile Organic Compound Emission Standards constrains solvent-based distribution channels. Day-Glo Color Corp anchors North American supply chains from its Cleveland operational base.
Germany
Autobahn maintenance contracts and municipal cycling infrastructure drive specification-grade demand for photoluminescent safety markings. ECHA restrictions on aromatic amine precursors under REACH Annex XVII force certified reformulation investments. Industrial coating producers in North Rhine-Westphalia accelerate in-house synthesis of compliant pigment alternatives.
China
Entertainment venue construction in Chengdu, Wuhan, and Xi'an sustains decorative coating consumption alongside transportation infrastructure upgrades. MEE enforcement of GB standards limits aromatic solvent content in manufacturing formulations. Yangtze River Delta chemical clusters absorb disproportionate capital allocation for water-based acrylic emulsion capacity.
India
Delhi-Mumbai and Bengaluru-Chennai industrial corridor projects remain underpenetrated for certified safety marking systems. BIS certification requirements for highway materials create compliance barriers for unqualified imports. Maharashtra-based contractors increasingly specify imported acrylic formulations for bridge and tunnel applications.
Netherlands
Municipal procurement offices in Rotterdam and Amsterdam specify waterborne fluorescent platforms exclusively for cycling infrastructure. EU Green Deal implementation accelerates phase-outs of hazardous pigment precursors across Dutch manufacturing. Specialty coating distributors in the Randstad region consolidate specification authority for maintenance and touch-up volumes.
Fluorescent Paint Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise concentrating among pigment-origin companies while regional fabricators compete on logistics proximity. The vendor base organizes into three tiers: daylight-fluorescent pigment specialists with captive synthesis capabilities, regional formulators blending purchased pigments into compliant resin systems, and toll manufacturers serving private-label demand. Consolidation pressures favor acquisition of formulation chemist teams over capacity expansion. Strategic partnerships between pigment suppliers and resin platforms accelerate compliant product development timelines.
Among North American specialists, Day-Glo Color Corp exemplifies the pigment-origin archetype with historic expertise in daylight-fluorescent synthesis. Radiant Color N.V. occupies a parallel position in European supply chains through its Belgian operational base. SINLOIHI represents the Asia-Pacific scale-driven tier, sustaining manufacturing across solvent-based and water-based product lines simultaneously. These three anchors illustrate how geographic regulatory divergence rewards multi-platform production capabilities over single-technology specialization.
| Leading Market Players |
|---|
| Day-Glo Color Corp |
| Radiant Color N.V. |
| SINLOIHI (Dai Nippon Toryo) |
| Wanlong Chemical Co., Ltd. |
| Luminochem |
| Vicome Corp |
| Hangzhou Aibai Chemical Co., Ltd. |
| Brilliant Group Inc. |
| Dane Color |
| Others |
Supply Flow & Price Mechanics
Captive synthesis of daylight-fluorescent pigments among German and Chinese chemical suppliers anchors both supply security and pricing power across the fluorescent paint value chain. Formulators without backward integration into pigment production face compressed margins as aromatic intermediate costs fluctuate.
Pricing Analysis
Premium pricing for sub-30-day lead times separates specification-grade safety marking contracts from spot decorative coating purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Cost compression in water-based acrylic tiers is intensifying because REACH and EPA compliance investments concentrate R&D overhead among fewer qualified suppliers. Municipal procurement offices exhibit lowest price sensitivity due to multi-year performance warranties, while entertainment venue contractors negotiate aggressively on decorative volumes.
Supply Chain Analysis
Freight cost differentials between Yangtze River Delta manufacturing clusters and European end-users favor regional toll manufacturing partnerships over direct export. Pigment synthesis concentrates in Germany and China; resin formulation clusters in the United States and Netherlands. Raw material dependencies span specialized aromatic amines, acrylic emulsion feedstocks, and photoluminescent rare earth compounds. Single-source vulnerability sits with German suppliers of yellow-green fluorescent precursors targeted by ECHA restrictions. Distribution runs through specialty coating distributors in industrialized markets and direct-to-contractor platforms for maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance velocity is consolidating the fluorescent paint vendor base as multi-jurisdiction certification timelines exceed 18 months and formulation chemist scarcity intensifies.
For Market Incumbents: Deepen captive pigment synthesis capabilities to insulate margin structures from ECHA aromatic amine phase-outs. Acquire specialized coatings scientists in North Rhine-Westphalia or Cleveland to compress reformulation cycle times. Retroreflective sheeting substitution from 3M and Avery Dennison threatens permanent road marking volumes; defend position through hybrid photoluminescent-fluorescent emergency egress formulations. For New Entrants and Emerging Players: Specialty distributors in the Randstad region and California municipal procurement offices offer specification channel access without incumbent distributor lock-in. Target India's Delhi-Mumbai industrial corridor where BIS certification barriers filter unqualified imports but demand for certified bridge and tunnel markings outpaces domestic supply. Lead with water-based acrylic platforms that leapfrog solvent-based incumbents facing structural regulatory risk. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to pigment-origin specialists seeking geographic formulation presence. Long-term viability favors vertically integrated players with captive synthesis and multi-platform production capabilities. Acquisition target archetype: regional formulators with certified water-based lines and stranded solvent-based assets convertible to compliant platforms. Watch for ECHA candidate list expansions targeting additional aromatic intermediates as inflection indicator for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | ECHA restrictions on aromatic amines make captive precursor production a margin defense mechanism. |
| Water-Based Acrylic Capacity Expansion | California and Netherlands municipal procurement offices specify sub-50 g/L VOC platforms exclusively. |
| Photoluminescent Hybrid Formulation Launch | Dual-mode visibility products capture emergency egress specification authority from single-technology competitors. |
| Direct-to-Contractor Platform Development | Mobile-enabled ordering fragments traditional three-tier distribution control over maintenance volumes. |
| Joint Venture with Regional Toll Manufacturer | Localized production in Yangtze River Delta clusters reduces freight exposure to European and North American end-users. |
Methodological Framework
Independent corroboration across formulation chemists at pigment-origin companies, procurement officers at German highway authorities, and specialty coating distributors underwrites the qualitative findings. Primary interviews engaged plant managers at acrylic emulsion facilities, technical R&D directors at safety marking formulators, and channel partners in the Randstad region. Secondary validation drew from ECHA candidate list updates, EPA National VOC Emission Standards documentation, and customs trade data for fluorescent pigment flows. Bottom-up volume estimates triangulated against top-down market sizing across resin chemistry, application function, and procurement authority segments.
Comparable-period anchoring to pre-REACH and post-REACH regulatory phases established baseline elasticity assumptions across the projection horizon. The analytical framework modeled demand by product type, application environment, and end-user procurement sophistication, with resin chemistry as the primary segmentation dimension. CAGRs derived from installed base attrition rates, infrastructure spending forecasts, and regulatory compliance adoption curves. Industry-specific inputs included tunnel and cycling corridor marking program announcements from California DOT and German Autobahn maintenance contracts.
Caveats apply where ECHA candidate list expansions or MEE GB standard enforcement could materially shift the outlook for solvent-based product viability. Forecasts reflect assumptions about reformulation technology maturation and raw material supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Primer Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Germany Industrial Wood Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
Paint Rollers Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
UAE Architectural Paints and Coatings Market