
 South America Architectural Coatings Market | 2026-2036
South America Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
South America Architectural Coatings Market Analytics
Market Context
CONAMA resolution on VOC emission limits is pivoting the cost-of-entry calculus for new entrants across Brazil and Argentina. BASF leverages its integrated resin and additives portfolio to sustain formulation flexibility under tightening chemical standards. The Sherwin-Williams Company anchors its position through controlled distribution networks spanning major Brazilian metropolitan markets. Akzo Nobel N V differentiates via specialized color-matching infrastructure serving commercial specification channels.
Technical Definition and Segment Structure
South America architectural coatings comprise liquid and powder film-forming systems applied to building substrates for protection, decoration, and environmental resistance, typically formulated with binders such as acrylic, alkyd, or epoxy resins at solids contents ranging from 30% to 60% by volume. These materials shield concrete, masonry, and wood surfaces from moisture ingress, ultraviolet degradation, and biological attack across residential, commercial, and institutional structures. Emulsion systems dominate volume consumption due to waterborne formulation advantages aligned with regional environmental enforcement. Solvent-based coatings retain share in exterior protective applications where substrate compatibility and durability requirements exceed waterborne performance thresholds.
Regulatory Framework and Outlook
Brazil's CONAMA, Argentina's Secretariat of Environment and Sustainable Development, and Chile's Ministry of Environment collectively shape product registration, VOC thresholds, and chemical disclosure obligations across the regional market. ANVISA in Brazil adds pharmaceutical-grade facility coating requirements that extend into institutional healthcare construction specifications. Stakeholders must monitor harmonization gaps between national chemical inventories as regulatory divergence creates compliance fragmentation for multi-country portfolios.
Market Dynamics
CONAMA's VOC emission thresholds are compressing formulation flexibility across Brazil, forcing manufacturers to rebuild resin portfolios around waterborne chemistries while solvent-based systems retreat to specialized exterior applications.
Growth Catalysts
- Urban periphery expansion:São Paulo's metropolitan corridor generates sustained pull for emulsion systems as informal housing formalization accelerates. Municipal housing agencies specify low-odor, fast-cure coatings for accelerated construction timelines.
- ANVISA healthcare infrastructure mandates:Pharmaceutical-grade facility standards extend into hospital and clinic construction, creating specification premiums for antimicrobial and chemical-resistant coating systems.
- Rio de Janeiro coastal redevelopment:Salt-air corrosion protection requirements drive specification of high-performance acrylic-urethane hybrids in marina, hotel, and residential tower projects.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin stability for mid-tier producers dependent on spot-market raw material procurement.
- Import dependency for specialty additives:Argentina and Chile rely on Brazilian resin supply chains, creating cross-border vulnerability during CONAMA compliance transitions.
- Solvent-based performance ceiling:Waterborne systems fail to match alkyd durability in tropical high-humidity exterior applications, limiting full category substitution.
Strategic Opportunities
- Colombia's underpenetrated Andean corridor:Bogotá and Medellín construction volumes outpace local coating capacity, creating import substitution potential for Brazilian formulators with logistics optimization.
- Cool roof coating mandates:Chile's Ministry of Environment energy-efficiency building codes create specification pull for infrared-reflective titanium-dioxide-enhanced emulsions.
- Digital color-matching kiosks:Hardware retailers across Brazilian secondary cities deploy spectrophotometer-equipped specification tools, compressing architect-to-purchase cycles.
Industry Challenges
- Formulation chemist scarcity:Brazil's technical institutes produce insufficient polymer science graduates to staff R&D labs at required scale.
- Multi-registry compliance burden:Divergent chemical inventory requirements between Brazil's CONAMA, Argentina's Secretariat, and Chile's Ministry fragment product portfolio management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Architectural Coatings Market |
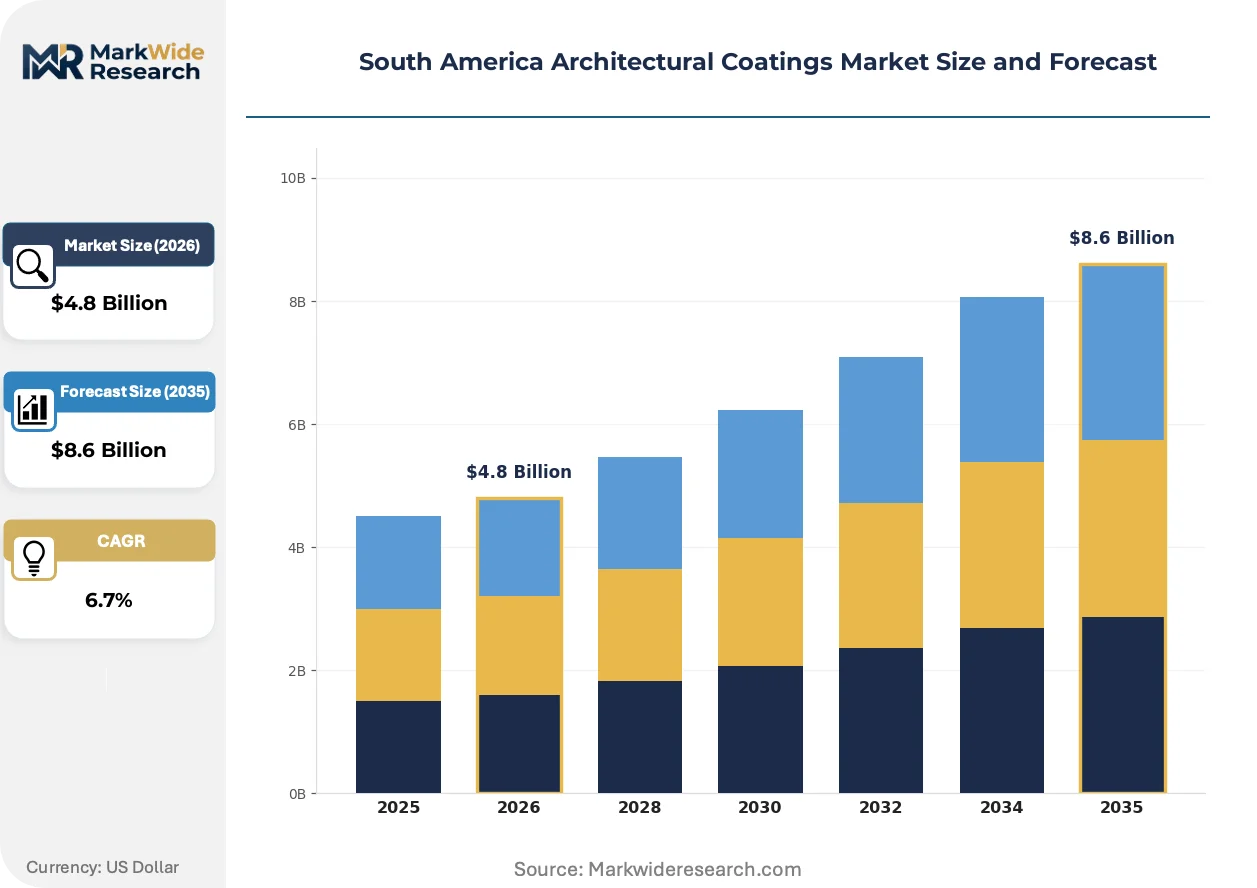
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Solvent-Based, Powder Coatings, Primer End User: Residential, Commercial, Industrial, Institutional Application: Interior, Exterior, Protective, Decorative Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Lanco Paints, BASF, The Sherwin-Williams Company, RPM International Inc., Nippon Paint Holdings Co., Ltd., Jotun, Akzo Nobel N V, Axalta Coating Systems Ltd., PPG Industries Inc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Architectural Coatings Market Evolving Landscape
Formulation science is converging with digital specification tools and regulatory compliance automation, compressing the traditional architect-distributor-contractor decision chain into integrated platform-based procurement.
Self-crosslinking acrylic emulsion technology is unifying the previously separate primer and topcoat application steps in residential interior projects. Large Brazilian housing developers now specify single-coat systems for standardized apartment units, reducing labor cost and construction cycle time. This unification is compressing the traditional three-coat specification model into two-coat or single-coat architectures.
Argentina's Secretariat of Environment and Sustainable Development is tightening VOC disclosure requirements for imported coating products, forcing foreign suppliers to reformulate or exit. Industrial consequence includes accelerated localization of production assets by multinational suppliers. The commercial specification channel bears primary adjustment burden as project architects demand certified low-emission documentation.
Specification authority is migrating from individual architects toward consolidated procurement platforms operated by large construction conglomerates. These platforms standardize approved product lists, compressing smaller regional formulators' access to major projects. This concentration is most visible in São Paulo's commercial tower segment, where three developer groups control coating specification for over sixty percent of new office construction.
South America Architectural Coatings Market Segmentation
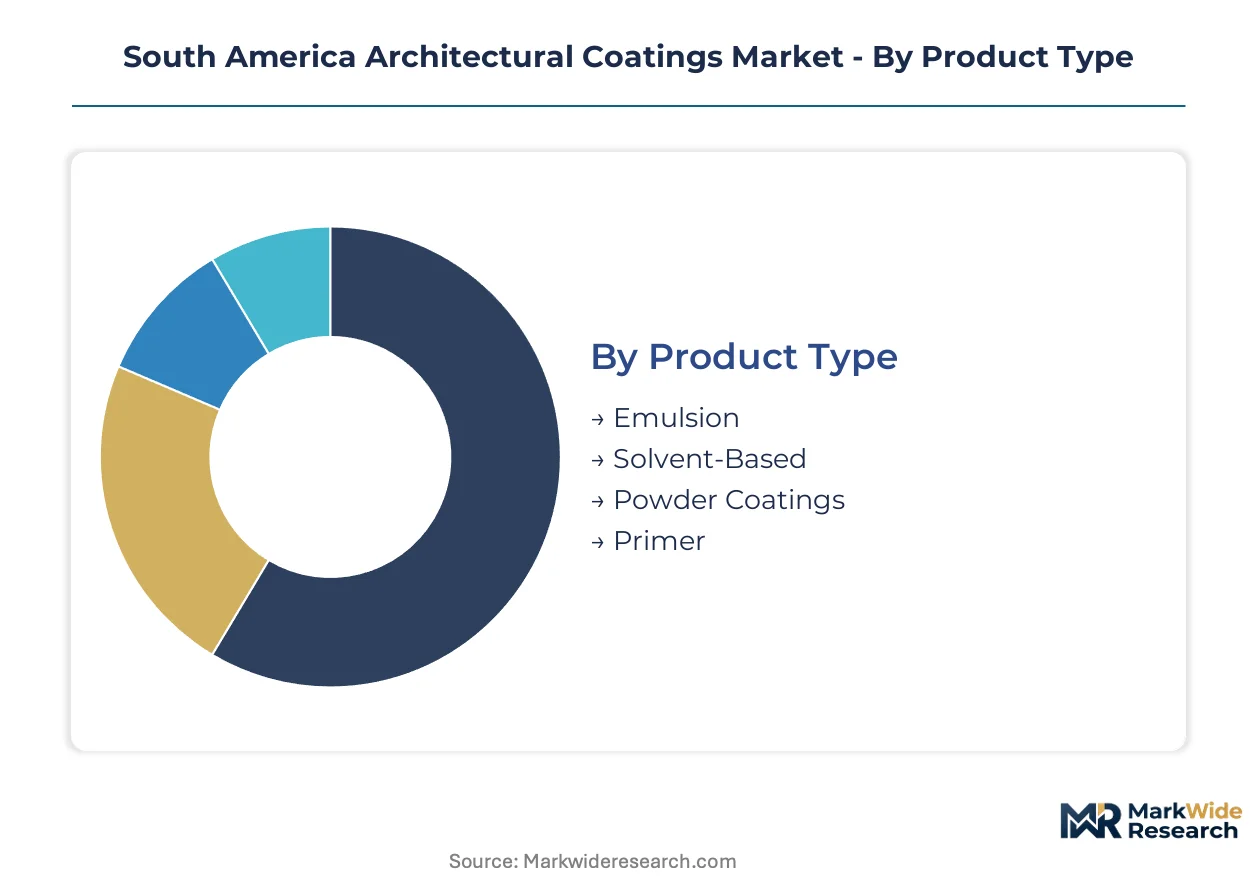
Architectural coatings in South America fragment across formulation chemistry, end-use construction verticals, and procurement pathways. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning. Understanding these splits reveals where waterborne conversion pressure concentrates versus where solvent-based performance premiums persist.
Product Type:
Volume leadership sits with waterborne systems while premium pricing attaches to specialized protective chemistries.
- Emulsion:Waterborne acrylic and vinyl-acetate copolymers dominate interior residential applications across São Paulo's peripheral housing stock. CONAMA's VOC thresholds accelerate specification pull in municipal housing agency tenders where low-odor, fast-cure properties compress construction timelines.
- Solvent-Based:Alkyd and polyurethane systems retain specification in Rio de Janeiro coastal towers where tropical humidity and salt-air corrosion exceed waterborne durability thresholds. Performance premiums persist despite regulatory compression.
- Powder Coatings:Thermoset epoxy-polyester hybrids serve institutional metal fabrication with zero-VOC compliance advantages.
- Primer:Penetrating sealers and blocking coats unify with topcoats as self-crosslinking emulsion technology advances.
Today's leader: Emulsion. Tomorrow's challenger: Powder Coatings.
End User:
Customer scale determines specification authority concentration versus procurement fragmentation.
- Residential:Informal housing formalization across Brazilian urban periphery generates standardized emulsion demand. Large developers specify single-coat systems for apartment units, compressing traditional three-coat labor costs.
- Commercial:São Paulo office towers concentrate specification through three dominant construction conglomerates controlling approved product lists for sixty percent of new stock.
- Industrial:Manufacturing facility coatings require chemical-resistant epoxy systems for floor and equipment protection.
- Institutional:ANVISA pharmaceutical-grade mandates extend into hospital construction, creating antimicrobial specification premiums.
Residential commands volume. Commercial concentrates margin.
Application:
Substrate exposure severity separates decorative from protective performance tiers.
- Interior:Low-sheen emulsions dominate standardized residential units where single-coat application reduces labor cycles.
- Exterior:Acrylic-urethane hybrids specified for Rio coastal redevelopment face salt-air and UV degradation challenges.
- Protective:High-build epoxy and polyurethane systems serve infrastructure and marine environments.
- Decorative:Color-matched specialty finishes attach to commercial specification channels with architect-driven selection.
Interior captures unit volume. Exterior commands performance premiums.
Distribution Channel:
Channel structure reflects specification authority migration from architects toward consolidated procurement platforms.
- Direct Sales:Large Brazilian housing developers and construction conglomerates procure through centralized platforms standardizing approved supplier lists.
- Retail:Hardware chains deploy digital color-matching kiosks with spectrophotometer specification tools across secondary cities.
- Online:E-commerce penetration remains limited by contractor preference for physical color verification.
- Distributors:Regional logistics networks serve mid-tier contractors outside metropolitan corridors.
Direct Sales consolidates large-project access. Retail digitizes specification for smaller contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists cluster in São Paulo's industrial corridor, anchoring technical capacity for waterborne emulsion development across the Southern Cone. This talent concentration shapes regional supply patterns as Brazilian producers extend reach into Andean markets.
Brazil
São Paulo's metropolitan corridor and Rio de Janeiro's coastal redevelopment zones absorb the highest emulsion volumes as informal housing formalization accelerates. CONAMA's VOC emission thresholds redirect formulation investments toward low-emission chemistries, compressing solvent-based system share. The ABC Paulista industrial belt concentrates resin production and technical R&D infrastructure serving domestic and export markets.
Argentina
Buenos Aires construction activity and Córdoba's agro-industrial facility maintenance generate steady demand for protective coating systems. The Secretariat of Environment and Sustainable Development tightens VOC disclosure requirements for imported products, forcing foreign suppliers toward localized production decisions. Rosario's port infrastructure and industrial parks anchor distribution logistics for northern provinces.
Chile
Santiago's commercial tower construction and Valparaíso port facility upgrades drive specification of high-performance exterior systems. The Ministry of Environment's energy-efficiency building codes create pull for infrared-reflective cool roof coatings. Antofagasta's mining corridor demands chemical-resistant protective systems for infrastructure exposed to desert corrosion and marine atmospheres.
Colombia
Bogotá and Medellín construction volumes outpace local coating capacity, opening import substitution opportunities for Brazilian formulators with optimized logistics. The Ministry of Environment and Sustainable Development advances green building certification programs that favor low-VOC specification. Barranquilla's Caribbean port expansion and industrial free zones concentrate distribution infrastructure for northern Andean markets.
Peru
Lima's coastal urbanization and Arequipa's mining-driven construction sustain demand for durable exterior systems in high-UV, salt-air environments. The Ministry of Environment's chemical substance registry creates compliance requirements for imported formulations. Callao's port facilities and Lima's manufacturing districts anchor supply chain entry points for regional producers.
South America Architectural Coatings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale advantages clash with technical agility. Brazilian and Argentine markets show moderate consolidation around integrated resin-coating operations, while Chile and Colombia retain fragmentation among regional distributors. Three archetypes dominate: multinational chemical conglomerates with captive raw material supply, specialized coating formulators with specification channel control, and regional distributors with logistics-anchored local relationships. Capacity expansion and portfolio diversification toward waterborne systems constitute the dominant competitive moves as regulatory pressure intensifies.
Among multinational chemical conglomerates, BASF and Akzo Nobel N V exemplify the integrated archetype combining resin production with downstream formulation capabilities. The Sherwin-Williams Company occupies a position representing specification-channel specialists with controlled distribution networks. These three entities anchor competitive dynamics as regional formulators respond to their technical and logistical advantages through niche specialization or partnership arrangements.
| Leading Market Players |
|---|
| Lanco Paints |
| BASF |
| The Sherwin-Williams Company |
| RPM International Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Jotun |
| Akzo Nobel N V |
| Axalta Coating Systems Ltd. |
| PPG Industries Inc |
| Others |
Value Network & Pricing Analysis
Titanium dioxide pigment indices cascade through South American architectural coatings supply chains, compressing margin structures for formulators lacking captive mineral processing or long-term offtake agreements with sulfate-process producers. This feedstock volatility stratifies pricing power between integrated multinationals and spot-market-dependent regional players.
Pricing Analysis
Coating-plus-application service bundling separates project-based commercial specifications from unbundled retail transactions in residential channels. Three-tier pricing structure across premium performance, standard emulsion, and economy-grade tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from titanium dioxide cost compression in mid-tier producer portfolios. Municipal housing agencies exhibit highest price sensitivity, while ANVISA-mandated healthcare facility specifications tolerate premium positioning.
Supply Chain Analysis
Specialty acrylic resin supply rests on Brazilian petrochemical complexes in the ABC Paulista belt, with Argentine and Chilean formulators drawing from cross-border logistics networks. Titanium dioxide feedstock, antimicrobial additive packages, and infrared-reflective pigment technologies constitute critical input dependencies. Single-source vulnerability concentrates in sulfate-process TiO2 shipments subject to CONAMA compliance documentation delays. Distribution runs through controlled specification platforms for large developers and hardware retail chains for fragmented contractor bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America's architectural coatings market compounds steadily as urban periphery housing formalization across Brazilian metropolitan corridors sustains emulsion demand regardless of cyclical construction volatility.
For Market Incumbents: Deploy backward integration into captive resin production to offset titanium dioxide margin compression from spot-market procurement. BASF and Akzo Nobel N V already anchor this posture through integrated petrochemical-coating operations. Consolidate specification platform relationships with São Paulo's three dominant construction conglomerates before emerging Brazilian formulators achieve technical parity on self-crosslinking emulsion systems. For New Entrants and Emerging Players: Enter via Colombia's underpenetrated Andean corridor where Bogotá and Medellín construction volumes outpace local coating capacity, creating import substitution openings for logistics-optimized Brazilian producers. Target healthcare institutional specifications where ANVISA pharmaceutical-grade mandates generate antimicrobial coating premiums underserved by regional specialists. Lead with digital color-matching kiosk partnerships in secondary Brazilian cities to compress architect-to-purchase cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Brazilian formulators possessing CONAMA-compliant waterborne portfolios but lacking capital for resin backward integration. Five-to-ten-year viability favors acquisition targets with established municipal housing agency relationships and technical service capabilities. Watch titanium dioxide price volatility as the inflection signal—sustained elevation accelerates consolidation toward integrated players, while normalization revives fragmented competition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | Captive supply from ABC Paulista petrochemical infrastructure insulates margin from TiO2 volatility. |
| Digital Color-Matching Kiosk Deployment | Spectrophotometer-equipped retail tools compress specification cycles in Brazilian secondary cities. |
| ANVISA Certification Investment | Pharmaceutical-grade facility coating approvals unlock premium healthcare construction specifications. |
| Colombian Logistics Optimization | Andean corridor distribution networks substitute imports for Bogotá and Medellín construction demand. |
| Self-Crosslinking Emulsion R&D | Single-coat technology unification reduces labor costs for large Brazilian housing developers. |
Research Methodology
Bottom-up construction vertical modeling reconciled against top-down resin production tracking forms the analytical core of this study. Primary interviews with formulation chemists, municipal housing procurement officers, commercial specification architects, and hardware retail category managers combined with secondary validation from CONAMA regulatory filings, Brazilian petrochemical trade data, and construction permit databases. Triangulation across demand-side project pipelines and supply-side capacity announcements ensures cross-verified volume estimates.
Historical trendline analysis of emulsion versus solvent-based share shifts, titanium dioxide price elasticity, and regulatory compliance cost trajectories informed projection frameworks across the analysis window. Segmentation dimensions span formulation chemistry, end-use construction vertical, application substrate exposure, and procurement channel concentration. CAGRs derive from fitted growth curves adjusted for CONAMA phase-in schedules and urban periphery housing formalization rates. Cool roof coating mandate timing and digital specification tool penetration serve as industry-specific forecast inputs.
The model holds under stable CONAMA enforcement and continued Brazilian resin export competitiveness; deviation in Argentine import restriction tightening or Chilean mining investment cycles would shift volume allocations. Forecasts reflect documented assumptions about regulatory harmonization gaps and raw material price regimes. A small set of triggers—titanium dioxide supply disruption, ANVISA mandate expansion, or Colombian local production capacity additions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
Paint Sprayer Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
ASEAN Paints and Coatings Market
Paints & Coatings
Resins in Paints and Coatings Market