
 Italy Food Emulsifier Market | 2026-2036
Italy Food Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Emulsifier Market Foresight
Consolidation among Italian bakery and dairy manufacturers is repositioning procurement power toward fewer, larger buyers with stricter ingredient specifications. Cargill Incorporated leverages its European supply network to secure long-term contracts with these consolidated processors. Palsgaard A/S specializes in tailored polyglycerol ester blends for premium confectionery applications. Kerry Inc. anchors its Italian presence through technical service centers that support reformulation projects for clean-label dairy products.
Food emulsifiers are surface-active compounds that reduce interfacial tension between immiscible phases such as oil and water, typically exhibiting hydrophilic-lipophilic balance values between 3 and 16 depending on molecular structure and intended stabilization function. These agents enable texture control, shelf-life extension, and uniform dispersion in processed foods through mechanisms including micelle formation and interfacial film stabilization. Lecithin dominates volume consumption across Italian food manufacturing due to its label-friendly profile and broad regulatory acceptance, while polyglycerol esters represent the fastest-expanding category driven by demand for trans-fat-free bakery systems. Sorbitan esters maintain stable margins in niche confectionery coatings where thermal stability requirements exclude alternative chemistries.
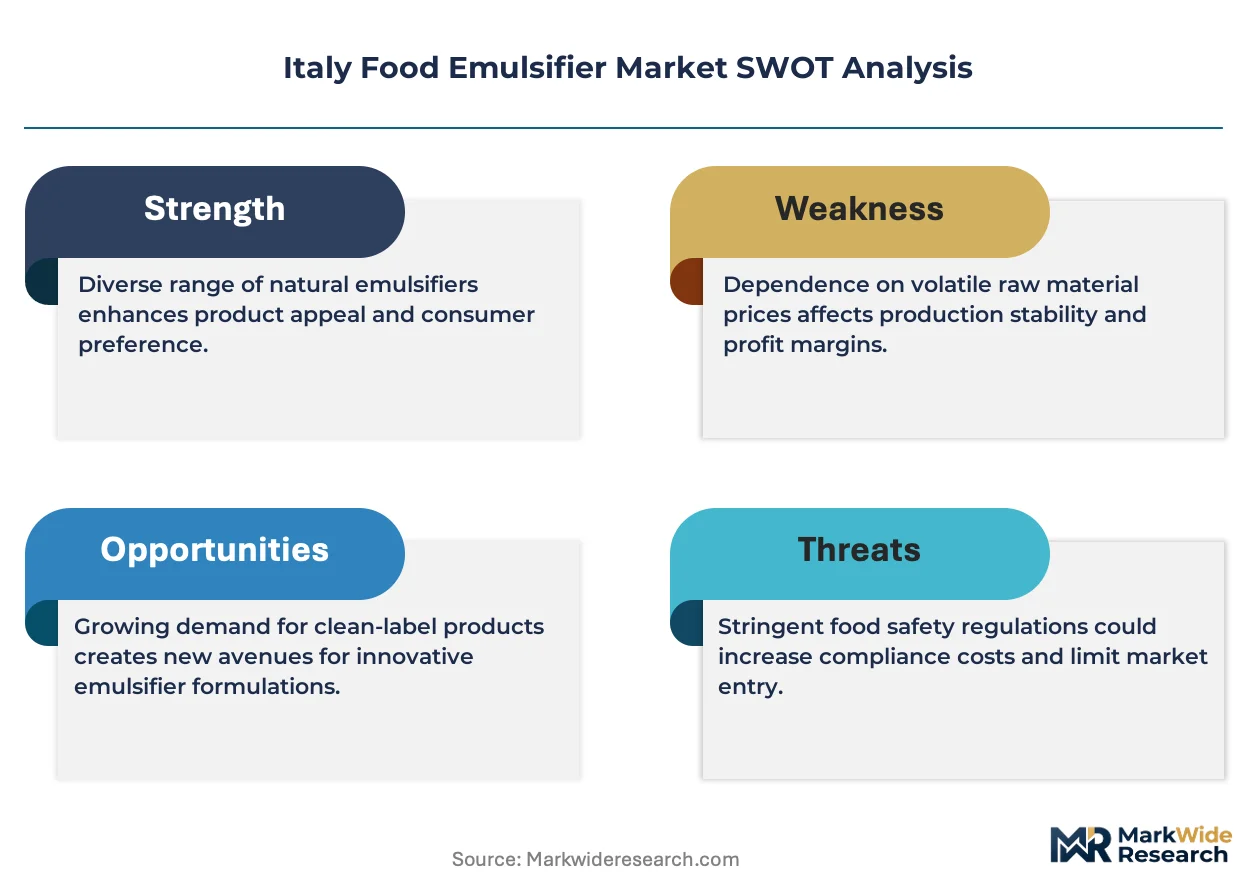
Italy's Ministry of Health enforces food additive specifications under EU Regulation 1333/2008, while the National Institute of Health validates novel emulsifier safety dossiers before domestic distribution approval. FSSAI-aligned importers face parallel conformity assessments that slow entry for non-EU suppliers. EFSA re-evaluations of permitted daily intakes for synthetic emulsifiers are compelling Italian formulators to accelerate plant-based substitutions ahead of potential restriction expansions. Stakeholders must monitor the interplay between EU-wide additive authorization reviews and Italy's regional enforcement intensity to anticipate reformulation cost shifts and sourcing reconfigurations.
Market Dynamics
Consolidation among Italian bakery and dairy processors is concentrating procurement power into fewer hands, forcing emulsifier suppliers to reconfigure technical service models and reformulation support capabilities around single large-account relationships.
Growth Catalysts
- EU Green Deal incentives:Italy's National Recovery and Resilience Plan directs capital subsidies toward sustainable food processing infrastructure, redirecting investment flows toward plant-derived emulsifier inputs.
- Clean-label dairy reformulation:Northern Italian dairy cooperatives are accelerating lecithin and polyglycerol ester adoption to replace synthetic stabilizers in premium cheese and yogurt lines.
- Trans-fat elimination mandates:EFSA guidance on cardiovascular risk reduction is compelling Bologna-based margarine producers to specify polyglycerol ester systems for bakery fat replacers.
Market Restraints
- Sunflower lecithin supply concentration:Ukrainian and Black Sea sourcing disruptions expose Italian formulators to raw material volatility and forced substitution into soy-derived alternatives with inferior label perception.
- EFSA re-evaluation timelines:Pending safety dossier reviews for synthetic emulsifiers under EU Regulation 1333/2008 are freezing new product development budgets until authorization clarity emerges.
- Enzymatic interesterification:This process technology threatens demand for chemical emulsifiers in industrial bakery shortenings by enabling fat structuring without additive labeling.
Strategic Opportunities
- Southern Italy underpenetration:Calabria and Sicily food manufacturing bases remain underserved by technical service infrastructure, creating first-mover advantage for emulsifier suppliers establishing regional application laboratories.
- Precision fermentation-derived lecithin:Convergence of synthetic biology and Italian biotech startup capacity offers pathway to GMO-free, allergen-reduced phospholipid production with domestic provenance claims.
- Direct-to-artisan distribution:E-commerce platforms specializing in ingredient supply to small-batch confectioners in Turin and Florence bypass traditional distributor markups and accelerate trial conversion.
Industry Challenges
- Reformulation chemist scarcity:Italian universities produce insufficient food science graduates with emulsion stabilization expertise, forcing manufacturers to recruit from German and Dutch talent pools at premium compensation.
- Clean-label certification complexity:Dual pursuit of EU organic regulation compliance and proprietary retailer standards requires parallel documentation systems that extend new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Emulsifier Market |
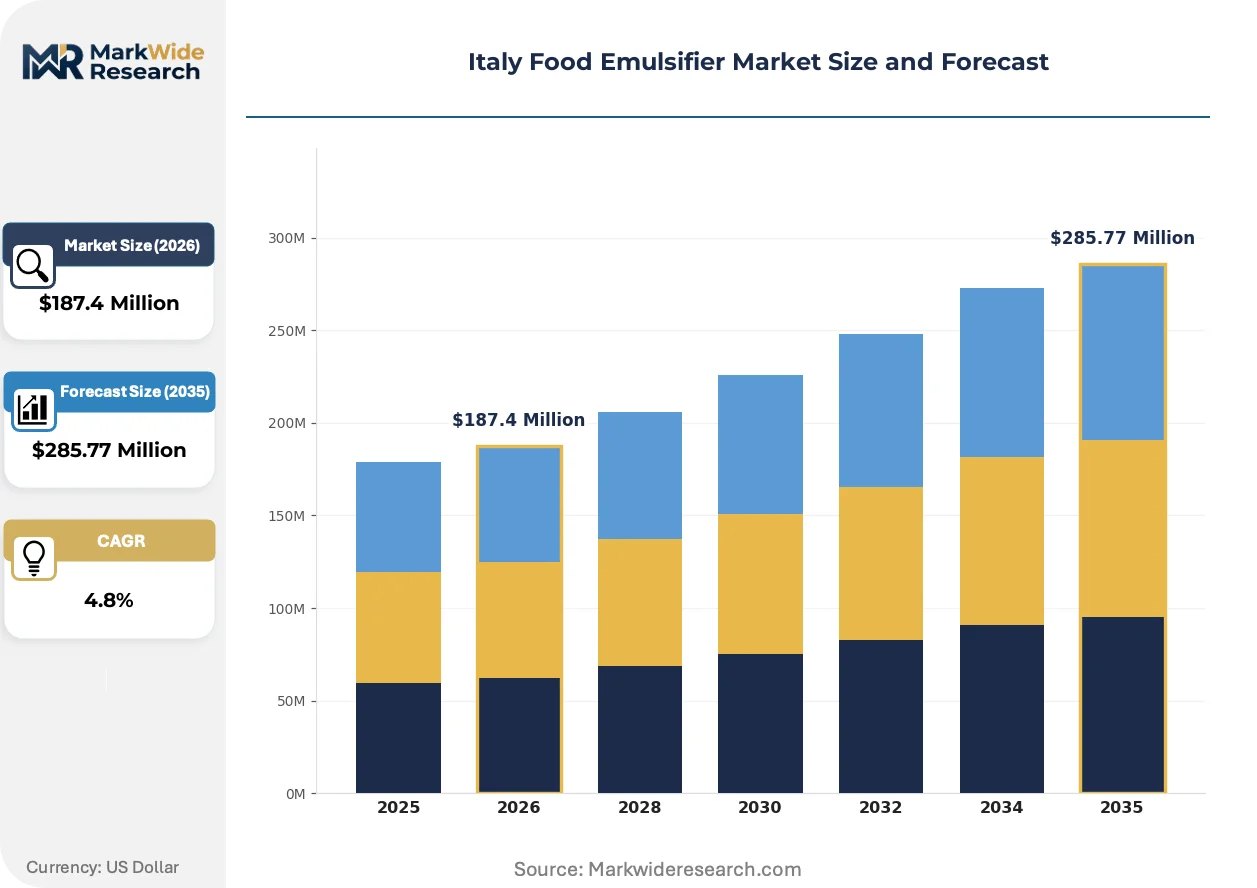
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Mono- and Diglycerides, Polyglycerol Esters, Sorbitan Esters Application: Bakery, Dairy Products, Sauces & Dressings, Confectionery Source: Naturally Derived, Synthetic, Plant-Based, Animal-Based End User: Food Manufacturers, Beverage Producers, Catering Companies, Retail |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ingredion Incorporated, Kerry Inc., DuPont de Nemours Inc., Puratos Group, BASF SE, Palsgaard A/S, Corbion N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Emulsifier Market Shifts & Advancements
Enzymatic modification processes and bio-based feedstock engineering are redefining performance benchmarks for Italian emulsifier procurement, with sustainability metrics now weighted equally against functional specifications in supplier selection protocols.
Enzyme-catalyzed lecithin hydrolysis is integrating into Italian margarine production lines to create lysophospholipids with superior water-binding capacity in reduced-fat spreads. Verona-based shortenings manufacturers are adopting this technology at pilot scale ahead of broader commercial rollout. The shift is integrating enzymatic process expertise into supplier technical service offerings, compressing competitive differentiation around application support depth rather than commodity chemistry alone.
REACH authorization requirements for bio-based surfactant precursors are tightening documentation burdens on Italian importers sourcing from non-EU fermentation facilities. The regulation is forcing reformulation project timelines to incorporate extended safety data sheet validation phases. Premium confectionery applications in Milan's industrial cluster are most affected, with several processors accelerating domestic phospholipid supplier qualification to bypass import compliance friction.
Specification-driven procurement is consolidating Italian bakery ingredient purchasing into centralized technical buying functions at major cooperatives. Regional distributors serving independent pastry shops in Emilia-Romagna are losing volume to direct manufacturer relationships as account minimums rise. The pattern is most visible across laminated dough applications where standardized emulsifier blends replace customized orders.
Italy Food Emulsifier Market Segmentation
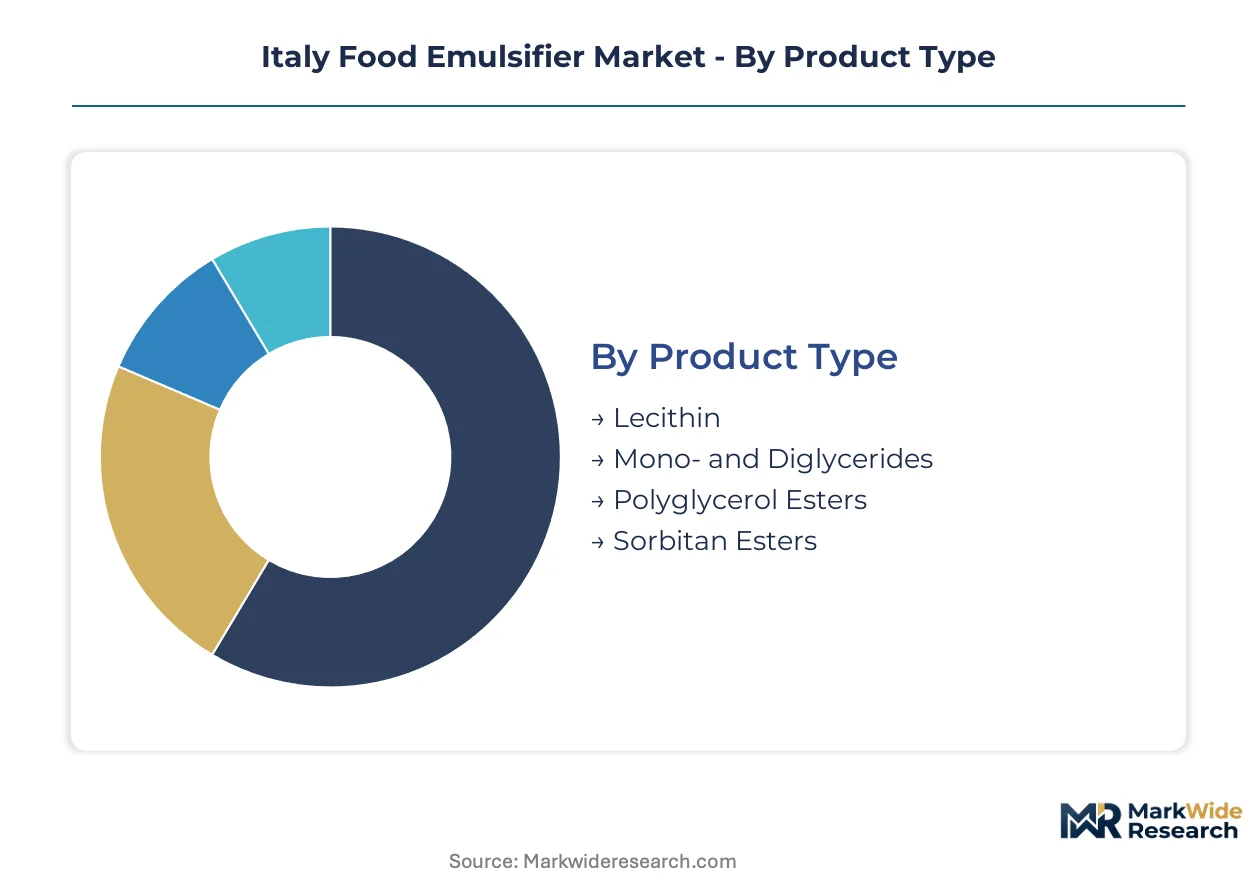
Emulsifier procurement patterns in Italy diverge sharply across product chemistries and end-use specifications, with reformulation cycles driving category switching. Understanding these segment boundaries clarifies where technical service investments yield account stickiness versus commodity displacement risk.
Product Type:
Replacement cycles accelerate where EFSA re-evaluations threaten synthetic authorizations, pushing formulators toward plant-derived alternatives with established safety dossiers.
- Lecithin:Phospholipid mixtures extracted from soy, sunflower, or egg yolk dominate Italian volume due to clean-label acceptance and broad regulatory clearance under EU Regulation 1333/2008. Northern Italian dairy cooperatives specify sunflower-derived grades for premium yogurt lines to avoid GMO labeling triggers.
- Polyglycerol Esters:These multi-hydroxyl emulsifiers enable trans-fat-free bakery systems through superior fat crystal modification. Bologna-based margarine producers specify them for laminated dough applications where thermal stability and mouthfeel control intersect.
- Mono- and Diglycerides:Partial esters of fatty acids and glycerol remain workhorse emulsifiers for industrial bread production across Emilia-Romagna.
- Sorbitan Esters:Lipophilic surfactants maintain niche positioning in Milan-area confectionery coatings requiring high-temperature processing tolerance.
Volume placements concentrate in Lecithin; the faster expansion belongs to Polyglycerol Esters.
Application:
End-use specifications fragment procurement requirements, with bakery and dairy commanding divergent technical service intensities.
- Bakery:Laminated dough, bread, and cake systems require emulsifiers that control starch retrogradation and fat dispersion. Industrial producers in Verona specify tailored polyglycerol ester blends for extended shelf-life claims in exported biscotti.
- Dairy Products:Cheese, yogurt, and spreadable fats demand emulsifiers that stabilize protein-fat interfaces without masking flavor. Lecithin dominates here due to its neutral taste profile and consumer recognition.
- Confectionery:Chocolate and coating applications in Turin prioritize thermal stability and gloss retention.
- Sauces & Dressings:Mayonnaise and vinaigrette systems require oil-in-water emulsion stability under refrigerated distribution.
Reformulation activity clusters in Bakery; margin capture is strongest in Dairy Products.
Source:
Raw material provenance now determines supplier qualification speed, with plant-derived options bypassing synthetic authorization delays.
- Plant-Based:Soy, sunflower, and rapeseed lecithin variants command premium positioning as direct replacements for synthetic emulsifiers. Italy's National Recovery and Resilience Plan subsidies favor capital investment in plant-derived processing infrastructure.
- Naturally Derived:Egg and milk phospholipids serve niche organic certification requirements in specialty dairy.
- Synthetic:Petrochemical-derived emulsifiers face frozen development budgets pending EFSA re-evaluation outcomes.
- Animal-Based:Tallow-derived mono- and diglycerides retain limited use in industrial shortening applications.
Procurement volumes favor Plant-Based; certification premiums attach to Naturally Derived.
End User:
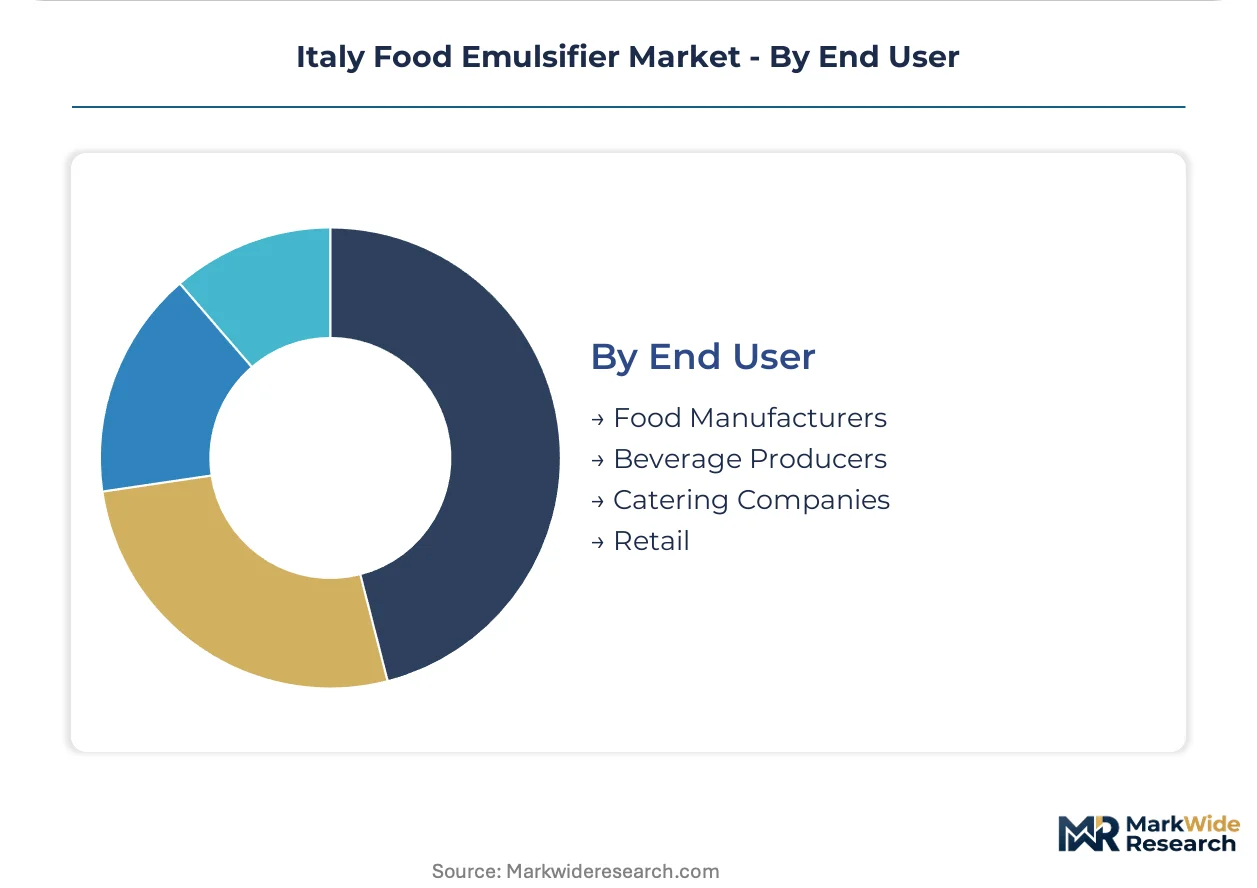
Customer scale dictates engagement model, with consolidated manufacturers extracting dedicated technical support while smaller accounts migrate to distributor channels.
- Food Manufacturers:Large-scale bakery and dairy processors in Milan, Bologna, and Verona specify custom emulsifier blends with embedded application support. These accounts drive multi-year contract structures and co-development relationships.
- Beverage Producers:Plant-based milk and flavored drink manufacturers require emulsifiers for flavor oil stabilization and cloud maintenance.
- Catering Companies:Institutional food service operators prioritize cost-optimized standard blends for sauce and dressing production.
- Retail:Artisan confectioners in Florence and Turin source through ingredient e-commerce platforms with small minimum order quantities.
Revenue concentration sits with Food Manufacturers; the steepest expansion trajectory runs through Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emulsifier procurement concentrates in Italy's northern industrial corridor, where Milan, Bologna, and Verona anchor demand from consolidated bakery and dairy processors. Southern regions remain structurally underpenetrated by technical service infrastructure.
Lombardy
Milan's metropolitan area hosts premium confectionery manufacturers specifying polyglycerol ester blends for thermal-stable coatings. Italy's Ministry of Health enforces EU Regulation 1333/2008 additive specifications through regional health authorities. The Monza-Brianza manufacturing belt attracts emulsifier suppliers establishing co-development partnerships with industrial chocolate processors.
Emilia-Romagna
Bologna-based margarine producers drive polyglycerol ester demand for trans-fat-free bakery fat replacers under EFSA cardiovascular risk guidance. The National Recovery and Resilience Plan channels capital subsidies toward sustainable food processing infrastructure in this region. Parma's dairy cooperative network specifies sunflower-derived lecithin for clean-label cheese and yogurt lines.
Veneto
Verona's industrial bakery sector pilots enzymatic lecithin hydrolysis for lysophospholipid production in reduced-fat spreads. REACH authorization requirements for bio-based surfactant precursors tighten documentation burdens on importers sourcing from non-EU fermentation facilities. The Verona-Brescia corridor concentrates shortenings manufacturing adopting tailored emulsifier blends for extended-shelf-life biscotti exports.
Piedmont
Turin's artisan confectionery base sources emulsifiers through ingredient e-commerce platforms with small minimum order quantities. EFSA re-evaluations of synthetic emulsifier safety dossiers freeze new product development budgets until authorization clarity emerges. The city's historic chocolate tradition sustains niche demand for sorbitan esters in high-temperature processing applications.
Tuscany
Florence's small-batch confectioners represent a fragmented retail channel bypassing traditional distributor markups through direct supplier relationships. Clean-label certification complexity—dual pursuit of EU organic regulation and proprietary retailer standards—extends new product introduction cycles. The regional food manufacturing base remains secondary to northern procurement volumes but offers margin capture through premium positioning.
Italy Food Emulsifier Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and enzymatic modification pathways. The supplier base concentrates around multinational ingredient conglomerates with European supply networks and specialized emulsifier houses with application-specific expertise. Three archetypes dominate: integrated agribusinesses with backward control over oilseed crushing, technical service-intensive specialists, and regional distributors serving artisan accounts. Consolidation among Italian processors is forcing competitive moves toward long-term contract structures and embedded reformulation support capabilities.
Within the integrated agribusiness tier, Archer Daniels Midland Company and Cargill Incorporated anchor positions through captive lecithin supply chains and pan-European distribution infrastructure. Kerry Inc. exemplifies the technical service archetype, maintaining Italian presence through application laboratories that support clean-label dairy reformulation. Palsgaard A/S occupies the specialist position, with polyglycerol ester expertise concentrated in premium confectionery segments. These three represent distinct competitive vectors—scale, service depth, and application focus—rather than overlapping positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion Incorporated |
| Kerry Inc. |
| DuPont de Nemours Inc. |
| Puratos Group |
| BASF SE |
| Palsgaard A/S |
| Corbion N.V. |
| Others |
Supply & Pricing Matrix
EU Green Deal compliance requirements gate qualified supply access and premium-tier pricing power for Italian food emulsifier suppliers. Buyers seeking plant-derived, clean-label certified inputs face constrained vendor pools that command margin premiums over commodity synthetic alternatives.
Pricing Analysis
Volume placements cluster in standard-grade lecithin with compressed margins, while premium-tier polyglycerol ester blends capture superior returns through embedded technical service. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in economy-tier synthetic emulsifiers is intensifying because EFSA re-evaluation uncertainty freezes development investment. Small-batch artisan confectioners in Turin and Florence exhibit highest price sensitivity, whereas consolidated dairy cooperatives in Emilia-Romagna prioritize performance specifications over unit cost.
Supply Chain Analysis
Direct-to-manufacturer channels handle consolidated processor demand, while regional distributors serve fragmented artisan accounts with higher markup structures. Raw material supply draws from Ukraine, Russia, and Argentina for sunflower lecithin, with Italian crushing capacity for soy and rapeseed alternatives. Black Sea sourcing disruptions create single-source vulnerability for premium non-GMO grades. Distribution runs through specialized food ingredient distributors with technical service capabilities in northern Italy, supplemented by direct e-commerce platforms penetrating southern underpenetrated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Regulation 1333/2008 enforcement creates a cost-of-compliance moat that favors established players with validated safety dossiers and clean-label certification infrastructure. New entrants face extended approval timelines and documentation burdens that incumbents have already absorbed.
For Market Incumbents: Deploy application laboratory expansion as the primary lever. Establish dedicated technical service centers in Calabria and Sicily to capture first-mover advantage in underpenetrated southern markets. Accelerate precision fermentation partnerships with Italian biotech startups to secure domestic phospholipid supply chains against import compliance friction. For New Entrants and Emerging Players: Begin with direct-to-artisan distribution through specialized e-commerce platforms serving Florence and Turin small-batch confectioners. Target beverage producers for plant-based milk emulsion stabilization as the most penetrable segment with technical service gaps. Pursue co-development relationships with emerging dairy alternatives manufacturers seeking clean-label positioning. For Investors and Strategic Acquirers: EFSA authorization clarity on synthetic emulsifier re-evaluations is the leading indicator that plant-derived substitution demand will accelerate or stabilize. Acquire technical service-intensive specialists with established Italian application laboratories rather than commodity-scale producers. Monitor National Recovery and Resilience Plan subsidy disbursement patterns as inflection signals for capital flow direction.| Strategic Initiative | Industry Significance |
|---|---|
| Application Laboratory Expansion | Technical service proximity to Bologna and Verona processors secures multi-year contract structures. |
| Precision Fermentation Partnership | Domestic phospholipid production bypasses REACH documentation burdens on non-EU imports. |
| Clean-Label Certification Investment | Dual EU organic and proprietary retailer compliance compresses competitor new product cycles. |
| Direct E-Commerce Platform Launch | Small minimum order quantities capture Turin and Florence artisan volume outside distributor channels. |
| Backward Integration into Oilseed Crushing | Captive sunflower and rapeseed supply secures non-GMO grade availability amid Black Sea disruption. |
Research Methodology
Trade publications, EU regulatory filings, and food industry association reports formed the secondary backbone for initial market sizing and competitive mapping. Primary interviews with procurement directors at Italian dairy cooperatives, application technologists at emulsifier suppliers, and regulatory affairs specialists at ingredient distributors validated segment assumptions. Bottom-up volume estimates from end-use application analysis were triangulated against top-down trade flow data.
Historical trendline analysis across production volumes, import-export flows, and price indices established baseline growth patterns. The modeling framework segmented by product chemistry, application end-use, raw material source, and customer scale throughout the forecast period. CAGRs were derived from regression analysis against macroeconomic indicators and policy incentive trajectories. Forecast inputs incorporated EFSA re-evaluation timelines and National Recovery and Resilience Plan subsidy allocation patterns.
Underlying measurement precision varies by segment; lecithin volume estimates carry tighter precision than emerging precision fermentation categories. Forecasts reflect assumptions about regulatory authorization continuity and raw material supply stability. Periodic stress-testing of base assumptions is recommended against EFSA safety dossier outcomes and Black Sea sourcing disruption scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Global Sodium Starch Glycolate Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Granulated Tapioca Market