
 Middle East and Africa Clean Label Ingredients Market | 2026-2036
Middle East and Africa Clean Label Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Clean Label Ingredients Market Foresight
A shift from single-source to multi-source procurement of natural extracts is rebalancing supply relationships across the region. Cargill leverages its regional grain processing footprint to secure steady feedstock for plant-derived emulsifiers. Chr. Hansen Holding A/S anchors its position through microbial fermentation expertise for natural colorants. Givaudan differentiates via integrated flavor and clean-label ingredient portfolios tailored to Middle Eastern taste profiles.
Clean label ingredients comprise food additives, colorants, sweeteners, and preservatives derived from natural or minimally processed sources, typically manufactured through physical extraction, enzymatic conversion, or controlled fermentation rather than synthetic chemical synthesis. These ingredients serve industrial food manufacturers seeking to eliminate artificial additives while maintaining shelf stability, sensory performance, and cost parity in finished consumer products. Natural colors and organic sweeteners command disproportionate margin pools as beverage and dairy alternative producers absorb premium pricing for certified formulations. Plant-based emulsifiers represent the fastest-growing product type, driven by vegan-label requirements and palm-oil reduction commitments among multinational food brands operating in the region.
South Africa's Department of Health labeling directives, Saudi Food and Drug Authority standards, and UAE Ministry of Industry and Advanced Technology technical regulations collectively tighten permissible additive lists and disclosure granularity. EMA-aligned standards in North African markets plus Gulf Standards Organization harmonization efforts are compressing reformulation cycles for imported ingredient portfolios. Stakeholders must monitor regulatory divergence between national food safety authorities and retail chain certification schemes to avoid supply disqualification.
Market Dynamics
Procurement consolidation across Gulf retail chains is compressing supplier qualification timelines and forcing ingredient portfolios toward multi-certification compliance before contract award.
Growth Catalysts
- SFDA additive disclosure mandates:Saudi Food and Drug Authority standards now require granular ingredient transparency, compelling packaged food manufacturers to reformulate with natural colorants and preservatives.
- Bakery sector concentration:GCC states' industrial baking clusters are absorbing plant-derived emulsifiers at accelerating rates to meet vegan-label requirements from multinational brand licensors.
- Fermentation capacity expansion:Controlled microbial production methods are displacing solvent extraction for natural colorants, improving yield consistency and supply security.
Market Restraints
- Feedstock price volatility:Organic sweetener manufacturers face margin pressure from beet and cane sugar price swings tied to climate-impacted harvests in North African supplier zones.
- Single-source extract dependency:Saffron-derived colorants and specific berry anthocyanins concentrate in Iranian and Moroccan supply corridors, creating geopolitical exposure.
- Technical shelf-life gaps:Natural preservative formulations currently underperform synthetic alternatives in ambient-stability metrics for ambient dairy applications.
Strategic Opportunities
- Nigerian beverage manufacturing:Lagos and Abuja industrial zones show underpenetrated demand for certified organic sweeteners as carbonated drink production scales.
- Enzymatic conversion convergence:Lipase-catalyzed interesterification is merging with traditional emulsifier production, opening patent-expired process licensing to regional compounders.
- UAE retail certification harmonization:MOHAP-aligned retail chain protocols are creating preferred supplier status for ingredients holding dual organic and halal credentials.
Industry Challenges
- Fermentation technologist scarcity:Industrial microbiology talent pools remain shallow across MEA, extending pilot-to-production timelines for novel natural colorant strains.
- Dual certification complexity:Simultaneous halal and organic audit requirements from Emirates Authority for Standardization and Metrology and international bodies stretch compliance calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Clean Label Ingredients Market |
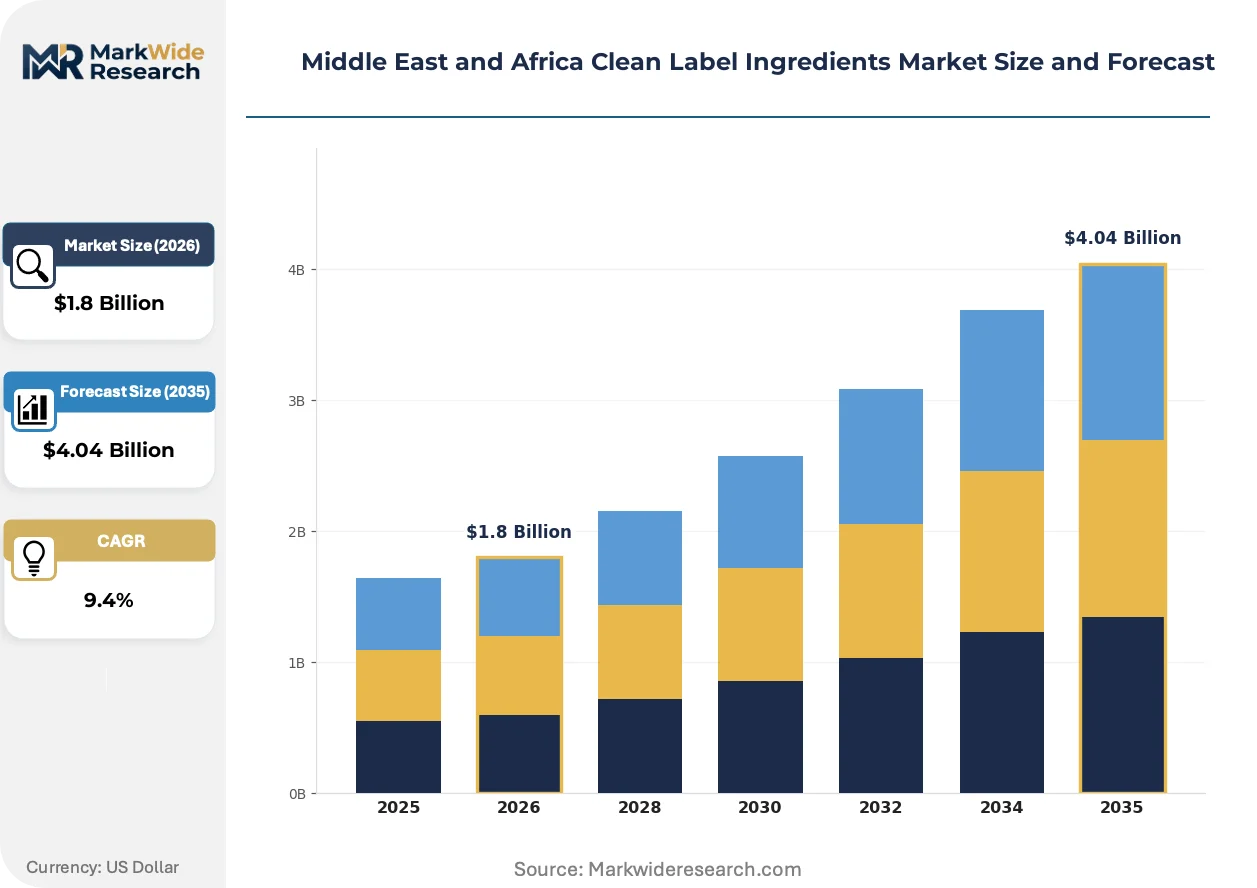
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Organic Sweeteners, Plant-Based Emulsifiers, Clean Label Preservatives Application: Food & Beverage, Bakery Products, Dairy Alternatives, Snacks Customer Type: Manufacturers, Retail Chains, Health-Conscious Consumers, Food Service Providers Packaging Type: Bulk Packaging, Eco-Friendly Containers, Single-Serve Packs, Flexible Packaging |
| Companies Covered | Chr. Hansen Holding A/S, Archer Daniels Midland Company, Cargill, Bell Flavors & Fragrances GmbH, Sensient Colors LLC, Firmenich SA, Givaudan, JJT Group, D D Williamson & Co, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Clean Label Ingredients Market Shifts & Advancements
Ingredient functionality is now inseparable from certification architecture, with procurement decisions flowing through retail-chain compliance portals rather than traditional distributor relationships.
Enzymatic interesterification is converging with physical refining to produce palm-oil-free emulsifiers with equivalent crystallization behavior. Pan-African baking and confectionery manufacturers are adopting these enzymatic routes ahead of European parent-company deadlines. The technology is converging with oleochemical fractionation to create regional supply autonomy from Southeast Asian palm derivatives.
South Africa's Department of Health labeling directives now mandate front-of-pack warning symbols linked to additive content thresholds. Industrial food manufacturers are pre-emptively eliminating targeted synthetic categories to avoid negative shelf positioning. Dairy alternative producers in Cape Town and Johannesburg industrial corridors are absorbing reformulation costs fastest to secure retail listing security.
Retail chain procurement portals are displacing traditional ingredient distributor networks across Saudi Arabia and UAE. Carrefour Saudi and Lulu Hypermarket now require direct supplier registration with certificate upload functionality, bypassing regional trading houses. This channel compression is most visible in Riyadh and Dubai, where packaged food contract manufacturers report 40% reduction in qualified supplier lists within eighteen months.
Middle East and Africa Clean Label Ingredients Market Segmentation
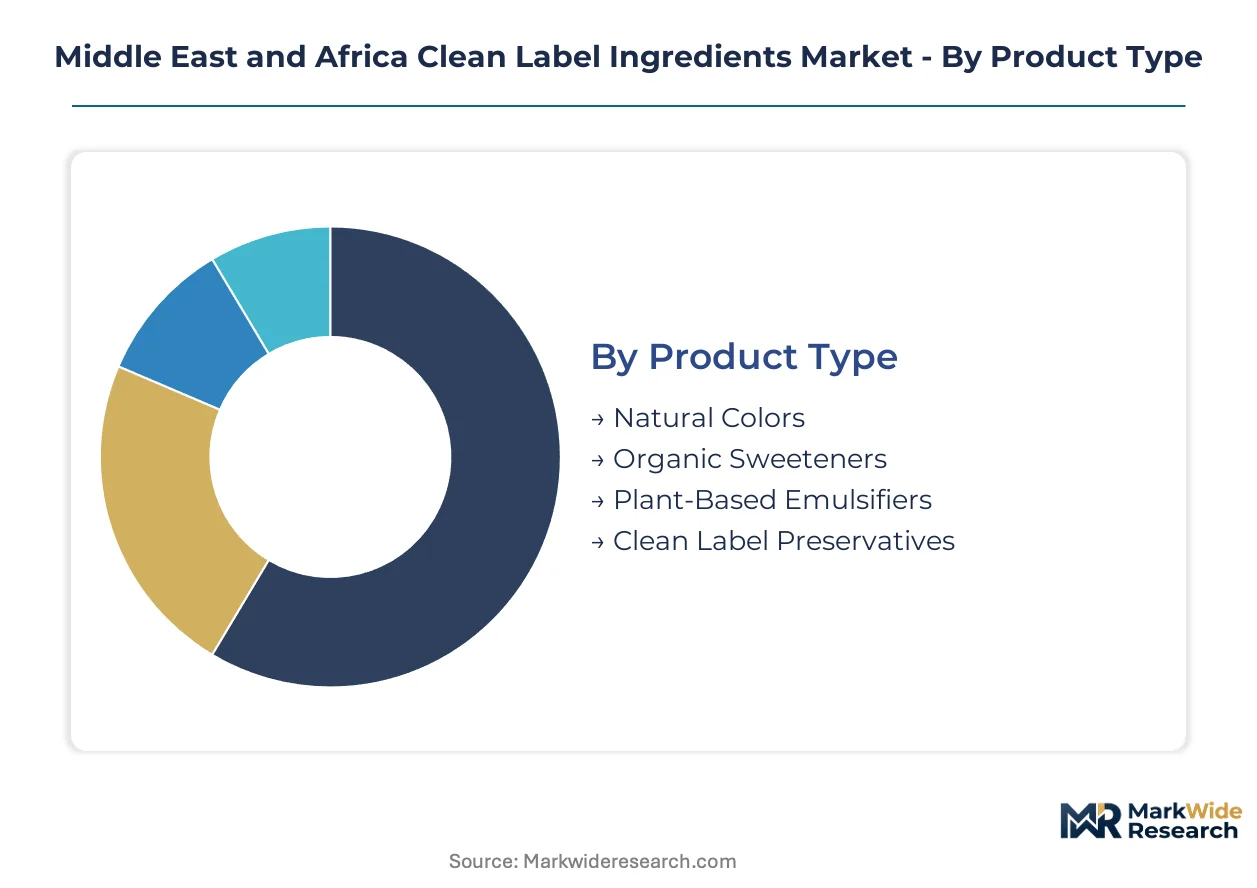
Ingredient procurement across the Middle East and Africa fragments across certification requirements, end-use performance thresholds, and channel-specific packaging protocols. Manufacturers navigate divergent specifications between industrial baking clusters in the GCC and retail-facing dairy alternative producers in South Africa.
Product Type:
Customization intensity spans from commodity-grade natural extracts to precision-fermented specialty ingredients requiring strain-specific validation protocols.
- Natural Colors:Anthocyanin and carotenoid formulations extracted from berries, turmeric, and annatto seeds. Saudi beverage manufacturers absorb premium pricing for heat-stable red alternatives to synthetic azo dyes in carbonated applications.
- Organic Sweeteners:Stevia glycosides, monk fruit extracts, and organic cane derivatives processed without synthetic solvents. South African dairy alternative producers in Cape Town industrial corridors pre-emptively reformulate to avoid front-of-pack warning symbols under Department of Health labeling directives.
- Plant-Based Emulsifiers:Lecithin and mono-diglyceride alternatives from sunflower and rapeseed sources.
- Clean Label Preservatives:Fermented vinegar derivatives, cultured dextrose, and rosemary extract formulations.
Leading the category by volume: Natural Colors. Expanding most quickly: Plant-Based Emulsifiers.
Application:
Volume concentration tracks industrial baking capacity expansion against fragmented snack manufacturing across North African coastal zones.
- Food & Beverage:Carbonated drinks, juices, and functional beverages requiring color stability across pH ranges and thermal processing. UAE Ministry of Industry and Advanced Technology technical regulations compress reformulation timelines for imported additive portfolios.
- Bakery Products:Industrial bread, pastry, and confectionery manufacturing concentrated in Riyadh and Dubai contract manufacturing zones. GCC baking clusters absorb enzymatically interesterified emulsifiers to meet multinational brand licensor vegan-label requirements.
- Dairy Alternatives:Oat, almond, and soy-based milk and yogurt applications.
- Snacks:Extruded and puffed products with extended ambient shelf-life requirements.
Dominant by procurement value: Food & Beverage. Steepest expansion trajectory: Dairy Alternatives.
Customer Type:
Channel power concentrates in retail chain procurement portals that displace traditional distributor relationships across Saudi Arabia and UAE.
- Manufacturers:Industrial food producers with direct formulation teams managing multi-certification compliance. Carrefour Saudi and Lulu Hypermarket supplier qualification timelines compress ingredient portfolio standardization requirements.
- Retail Chains:Supermarket and hypermarket operators with direct registration portals requiring certificate upload functionality. Dubai-based retail procurement systems bypass regional trading houses, reducing qualified supplier lists by forty percent within eighteen months.
- Health-Conscious Consumers:End-users driving demand pull through premium product selection.
- Food Service Providers:Restaurant chains and institutional catering operations with volume-scale procurement.
Highest volume concentration: Manufacturers. Fastest procurement system adoption: Retail Chains.
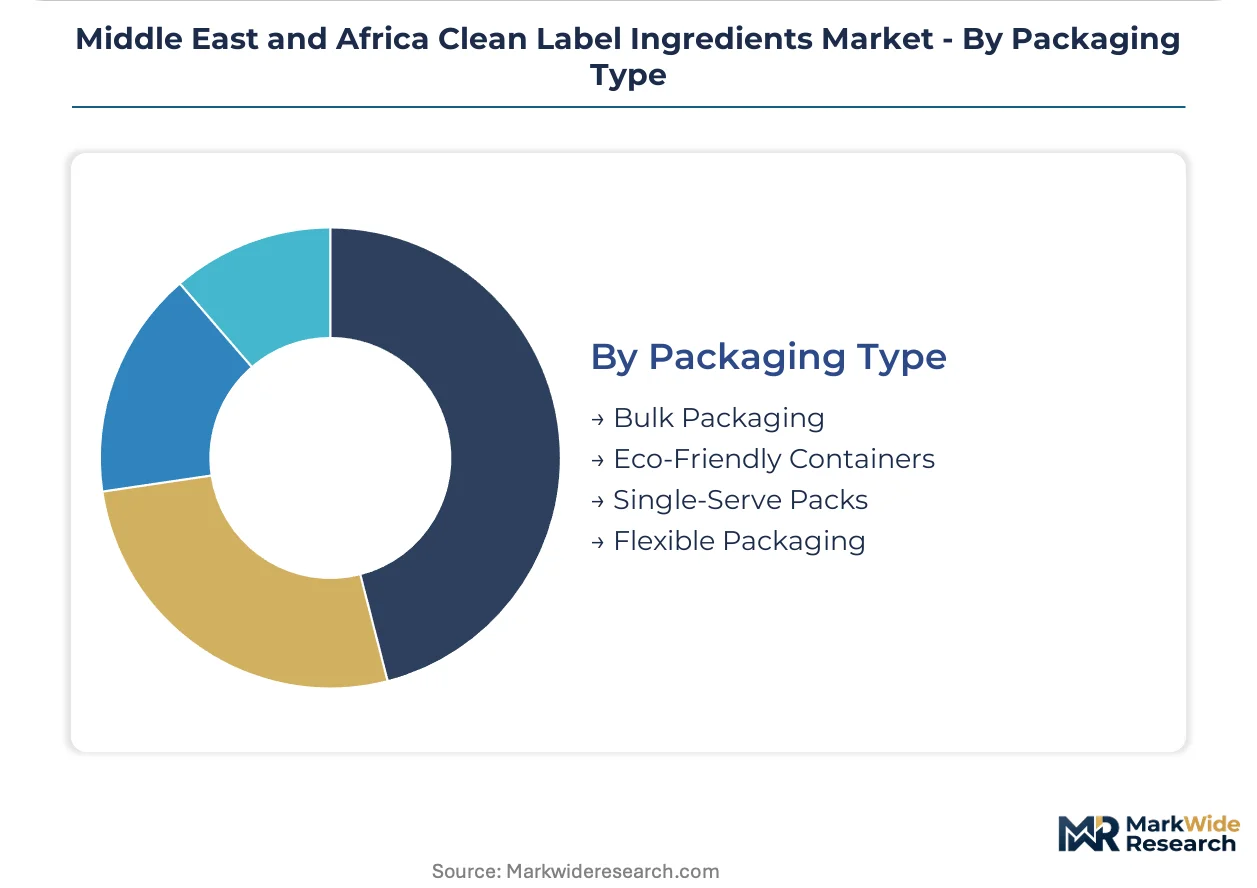
Packaging Type:
Format selection tracks supply chain configuration from bulk industrial tankers to retail-facing single-serve units.
- Bulk Packaging:Intermediate bulk containers and tanker deliveries for industrial-scale manufacturers. Lagos and Abuja beverage manufacturing zones show underpenetrated demand for certified organic sweetener bulk deliveries as carbonated production scales.
- Eco-Friendly Containers:Recyclable and biodegradable primary packaging aligned with retail chain sustainability protocols. MOHAP-aligned UAE retail certification schemes create preferred supplier status for ingredients holding dual organic and halal credentials.
- Single-Serve Packs:Portion-controlled formats for food service and premium retail channels.
- Flexible Packaging:Pouches and sachets for ingredient sampling and small-batch manufacturing.
Largest shipment volume: Bulk Packaging. Fastest format innovation: Eco-Friendly Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
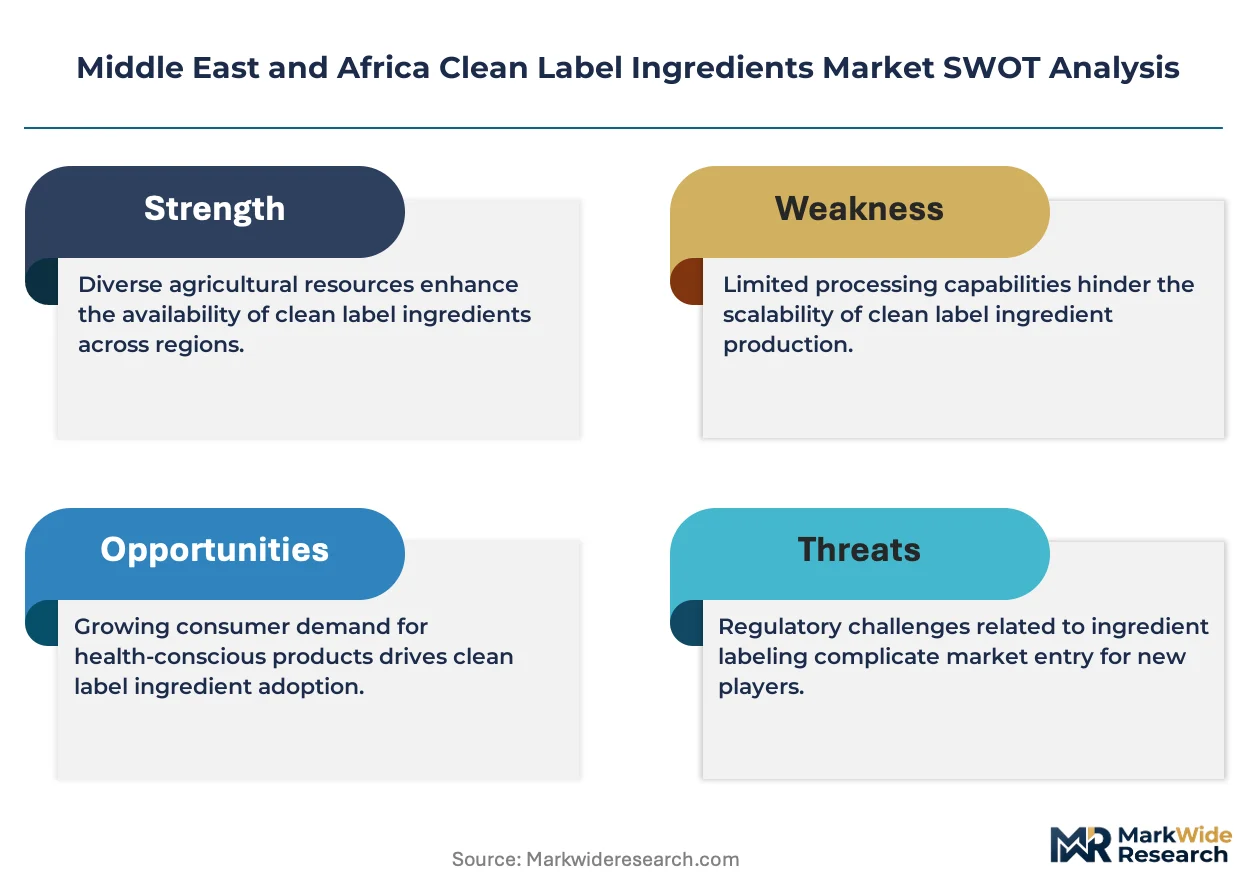
Saffron and berry anthocyanin supply corridors in Iran and Morocco anchor natural colorant procurement across the Middle East and Africa, with fermentation capacity expansion in South Africa and enzymatic processing clusters in the GCC reshaping regional ingredient flows.
Saudi Arabia
Packaged food manufacturers in Riyadh industrial zones absorb plant-derived emulsifiers at accelerating rates to meet vegan-label requirements from multinational brand licensors. SFDA additive disclosure mandates now require granular ingredient transparency, compelling reformulation with natural colorants and preservatives. Jeddah and Dammam contract manufacturing corridors report compressed supplier qualification timelines as retail chains enforce direct certification protocols.
United Arab Emirates
Dubai-based beverage producers command premium pricing for heat-stable natural color alternatives to synthetic azo dyes in carbonated applications. MOHAP-aligned retail certification schemes create preferred supplier status for ingredients holding dual organic and halal credentials. Abu Dhabi industrial zones concentrate enzymatic interesterification capacity for palm-oil-free emulsifier production serving pan-African baking manufacturers.
South Africa
Cape Town and Johannesburg dairy alternative producers pre-emptively reformulate to avoid front-of-pack warning symbols under Department of Health labeling directives. The country's fermentation technologist scarcity extends pilot-to-production timelines for novel natural colorant strains. Port Elizabeth industrial corridors anchor microbial production methods displacing solvent extraction for improved yield consistency.
Nigeria
Lagos and Abuja beverage manufacturing zones show underpenetrated demand for certified organic sweeteners as carbonated drink production scales. The country's national food safety authority tightens permissible additive lists alongside retail chain import certification requirements. Kano industrial clusters concentrate bulk procurement of natural preservatives for ambient dairy applications facing technical shelf-life performance gaps.
Morocco
Berry anthocyanin extraction facilities in Casablanca-Rabat corridors supply heat-stable red colorants to Saudi beverage manufacturers. EMA-aligned standards in North African markets compress reformulation cycles for imported ingredient portfolios. Tangier-Mediterranean industrial zones develop dual halal-organic audit capabilities to serve GCC retail procurement portals.
Middle East and Africa Clean Label Ingredients Market Competitive Landscape
Global majors compete with regional champions across certification architecture and feedstock security, producing a tiered structure where fermentation specialists, grain processors, and integrated flavor houses occupy distinct competitive positions. Market concentration tracks procurement portal consolidation, with retail chain direct registration requirements compressing qualified supplier lists. Three archetypes dominate: microbial fermentation specialists securing strain-specific validation protocols, agricultural processors leveraging regional grain footprints for plant-derived inputs, and integrated houses combining flavor expertise with clean-label ingredient portfolios. Competitive moves center on multi-certification compliance acceleration and enzymatic process licensing to regional compounders.
Among Denmark-based specialists, Chr. Hansen Holding A/S exemplifies the microbial fermentation archetype, while Cargill represents agricultural processors with regional grain processing footprints. Givaudan occupies a position within integrated flavor and ingredient houses, with these three anchoring distinct competitive vectors across the Middle East and Africa procurement landscape.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Archer Daniels Midland Company |
| Cargill |
| Bell Flavors & Fragrances GmbH |
| Sensient Colors LLC |
| Firmenich SA |
| Givaudan |
| JJT Group |
| D D Williamson & Co |
| Others |
Supply & Pricing Matrix
Organic sweetener feedstock costs from North African beet and cane harvests cascade through three distinct pricing tiers before reaching Gulf beverage manufacturers, with climate-impacted harvest volatility compressing margins most acutely at the commodity-grade end of the spectrum.
Pricing Analysis
Certification-bundled pricing separates premium-grade natural colorants with dual halal-organic validation from unbundled commodity extracts lacking retail portal compliance. Price differentiation rests on fermentation-derived strain specificity versus solvent-extracted commodity grades, with Saudi retail chains absorbing premiums for certified formulations. Pricing pressure intensifies in the standard tier as South African labeling mandates force accelerated reformulation timelines. Small-batch dairy alternative producers in Cape Town corridors exhibit highest price sensitivity, while multinational brand licensors in Riyadh zones demonstrate lowest sensitivity due to pass-through mechanisms.
Supply Chain Analysis
Return flows of spent fermentation biomass and solvent-extraction residues from Moroccan berry processing facilities feed circular economy loops for agricultural input recovery. Supply concentrates in Iran and Morocco for saffron-derived colorants and berry anthocyanins, with South African fermentation capacity and UAE enzymatic processing clusters providing geographic diversification. Raw material dependencies draw from North African cane and beet zones, Iranian crocus cultivation corridors, and GCC grain processing hubs. Single-source extract vulnerability in Iranian supply corridors creates structural risk exposure. Distribution runs through retail procurement portals in Saudi Arabia and UAE that displace traditional trading house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa clean label ingredients market functions as a vertical-integration race where control over fermentation strain libraries and enzymatic process patents determines margin capture across procurement portal channels.
For Market Incumbents: Anchor feedstock security through backward integration into North African organic sweetener cultivation and captive fermentation capacity expansion in South African industrial zones. Threat exposure from patent-expired enzymatic interesterification licensing demands accelerated proprietary strain development to defend formulation exclusivity. Certification investment in dual halal-organic audit capabilities secures preferred supplier status within MOHAP-aligned retail portals. For New Entrants and Emerging Players: E-commerce ingredient marketplaces offering direct certificate upload functionality bypass entrenched distributor relationships in Lagos and Abuja beverage manufacturing corridors. Underpenetrated Nigerian carbonated drink production zones present the most accessible white-space entry point. White-label enzymatic emulsifier production for pan-African baking manufacturers offers immediate revenue traction without proprietary strain development overhead. For Investors and Strategic Acquirers: Chr. Hansen's microbial fermentation technology licensing agreements with GCC compounders are the leading indicator that strain-specific validation protocols are becoming the primary value capture mechanism in natural colorant supply. Long-term viability across the analysis window favors acquisition targets possessing captive fermentation infrastructure and established retail portal registration status. Practitioners should monitor South African Department of Health enforcement actions against front-of-pack warning symbol violations as early signals of reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Cultivation | Captive organic beet and cane supply from North African growing regions insulates margin compression from climate volatility. |
| Dual Certification Acceleration | Simultaneous halal-organic audit completion unlocks preferred supplier status within MOHAP-aligned UAE retail procurement portals. |
| Enzymatic Process Licensing | Patent-expired lipase-catalyzed interesterification technology transfer to regional compounders expands addressable emulsifier market share. |
| Fermentation Capacity Expansion | Controlled microbial production methods in South African industrial zones displace solvent extraction for improved natural colorant yield consistency. |
| Retail Portal Direct Registration | Bypassing traditional distributor networks through Carrefour Saudi and Lulu Hypermarket supplier qualification systems compresses customer acquisition timelines. |
Research Methodology
Document review covered SFDA additive disclosure mandates, South African Department of Health labeling directives, and UAE Ministry of Industry technical regulations, complemented by interviews with fermentation technology directors at industrial food manufacturers, procurement leads at Saudi retail chains, regulatory affairs specialists at ingredient suppliers, and plant managers at enzymatic processing facilities. Secondary validation drew from Gulf Standards Organization harmonization documents, EMA-aligned North African market standards, and customs trade data for natural extract flows. Bottom-up demand modeling from end-use sector procurement patterns was triangulated against top-down supply capacity assessments across fermentation and extraction facilities.
Segmented outputs across product type, application, customer channel, and packaging format were generated through the analytical framework, with CAGRs derived from regression analysis against macroeconomic drivers and regulatory enforcement timelines. Industry-specific forecast inputs incorporated retail chain certification portal adoption curves and enzymatic process licensing velocity among regional compounders.
The model holds under stable regulatory enforcement intensity and continued retail chain procurement portal expansion; deviation in SFDA disclosure mandate timing or MOHAP certification protocol changes would shift reformulation demand curves. Practitioners should monitor South African front-of-pack warning symbol implementation rates and Nigerian national food safety authority additive list revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Asia-Pacific Food Enzymes Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Global Food Texturants Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Spain Food Acidulants Market