
 Australia Food Acidulants Market | 2026-2036
Australia Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Acidulants Market Outlook
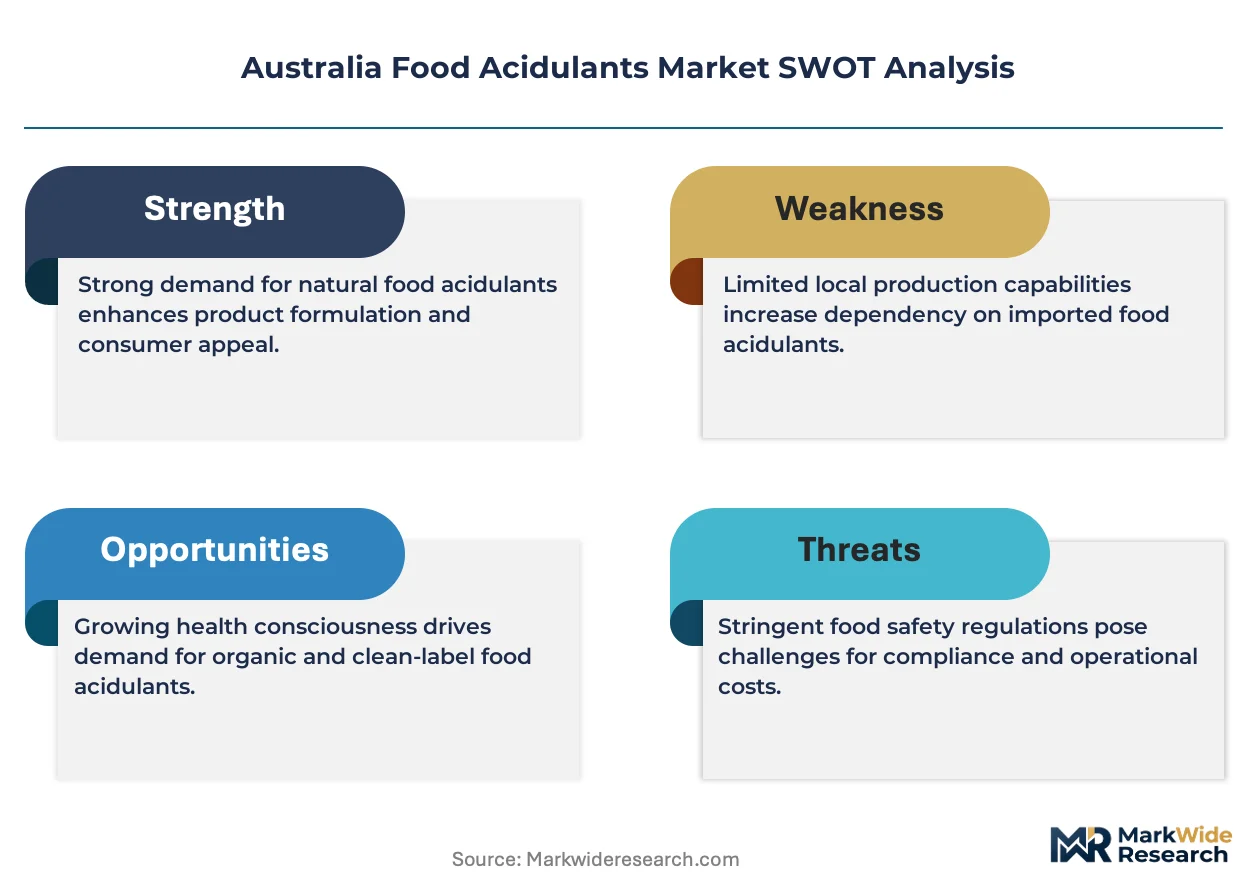
The Australia food acidulants market is pivoting on a widening split between premium acidulant grades with full traceability and commodity grades competing on bulk pricing. Tate & Lyle leverages its global ingredient portfolio to supply high-purity citric acid solutions to Australian beverage bottlers. Cargill Incorporated anchors its position through integrated fermentation capabilities that sustain consistent lactic acid output for dairy processors. Jungbunzlauer Suisse AG differentiates via specialty acidulant blends tailored to clean-label confectionery demands.
Food acidulants comprise organic and inorganic compounds—primarily citric, lactic, acetic, and phosphoric acids—used to regulate pH, enhance flavor profiles, extend shelf stability, and control microbial growth in processed foods. Citric acid dominates volume flows due to its versatility across beverage acidification and antioxidant synergy. Lactic acid commands margin premiums in dairy applications where fermentation-derived credentials support label positioning. Phosphoric acid retains structural importance in cola-type beverages despite formulation diversification toward milder acid profiles.
FSANZ standards govern maximum permissible levels and labelling declarations for acidulant additives in Australian food products. Food Standards Australia New Zealand also coordinates with the Department of Agriculture on import compliance for acidulant raw materials entering Australian ports. Stakeholders must monitor evolving FSANZ consultation papers on acidulant reclassification and track state-level waste discharge rules affecting acidulant manufacturing site approvals.
Market Dynamics
FSANZ labelling mandates are compressing formulation timelines as beverage manufacturers across New South Wales and Victoria race to reformulate acidulant blends ahead of disclosure deadline tightening. This regulatory pressure is splitting procurement between premium traceable grades and commodity bulk supply.
Growth Catalysts
- Functional beverage expansion:Sydney and Melbourne bottlers are scaling acidulant procurement for pH-stabilized electrolyte and probiotic drink lines, driving volume concentration in southeastern processing clusters.
- FSANZ additive reclassification consultations:Pending disclosure requirement expansions are accelerating R&D investment into clean-label acidulant alternatives ahead of anticipated mandate finalization.
- Dairy fermentation credentialing:Victorian dairy processors are prioritizing lactic acid with verified fermentation-derived status to support premium positioning in export markets.
Market Restraints
- Molasses feedstock volatility:Citric acid production costs fluctuate with Brazilian sugarcane harvest cycles, squeezing margin stability for Australian compounders dependent on imported fermentation feedstock.
- Port concentration risk:Acidulant raw material imports funnel through Melbourne and Sydney container terminals, creating single-point vulnerability for inland processors in Queensland and South Australia.
- Phosphoric acid substitution ceiling:Cola-type beverage reformulation toward milder acid profiles faces technical barriers in achieving equivalent shelf stability without phosphoric acid's microbial inhibition properties.
Strategic Opportunities
- Western Australia processing gap:Underdeveloped acidulant blending capacity in Perth creates whitespace for regional supply contracts with mining-camp catering and remote beverage distribution networks.
- FSANZ organic acid incentive alignment:Anticipated favourable treatment of fermentation-derived acidulants in upcoming standard revisions positions lactic acid for accelerated adoption in clean-label confectionery.
- Direct-to-manufacturer digital procurement:Emerging B2B platform channels are compressing distributor layers for mid-tier Victorian dairy processors seeking spot citric acid purchases.
Industry Challenges
- FSANZ compliance timeline compression:Reformulation validation cycles for acidulant label disclosure upgrades are stretching quality assurance teams at mid-sized Sydney beverage operations.
- Legacy pH control system integration:Automated acidulant dosing retrofitting in established Melbourne dairy plants requires capital outlay that conflicts with short procurement contract windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Acidulants Market |
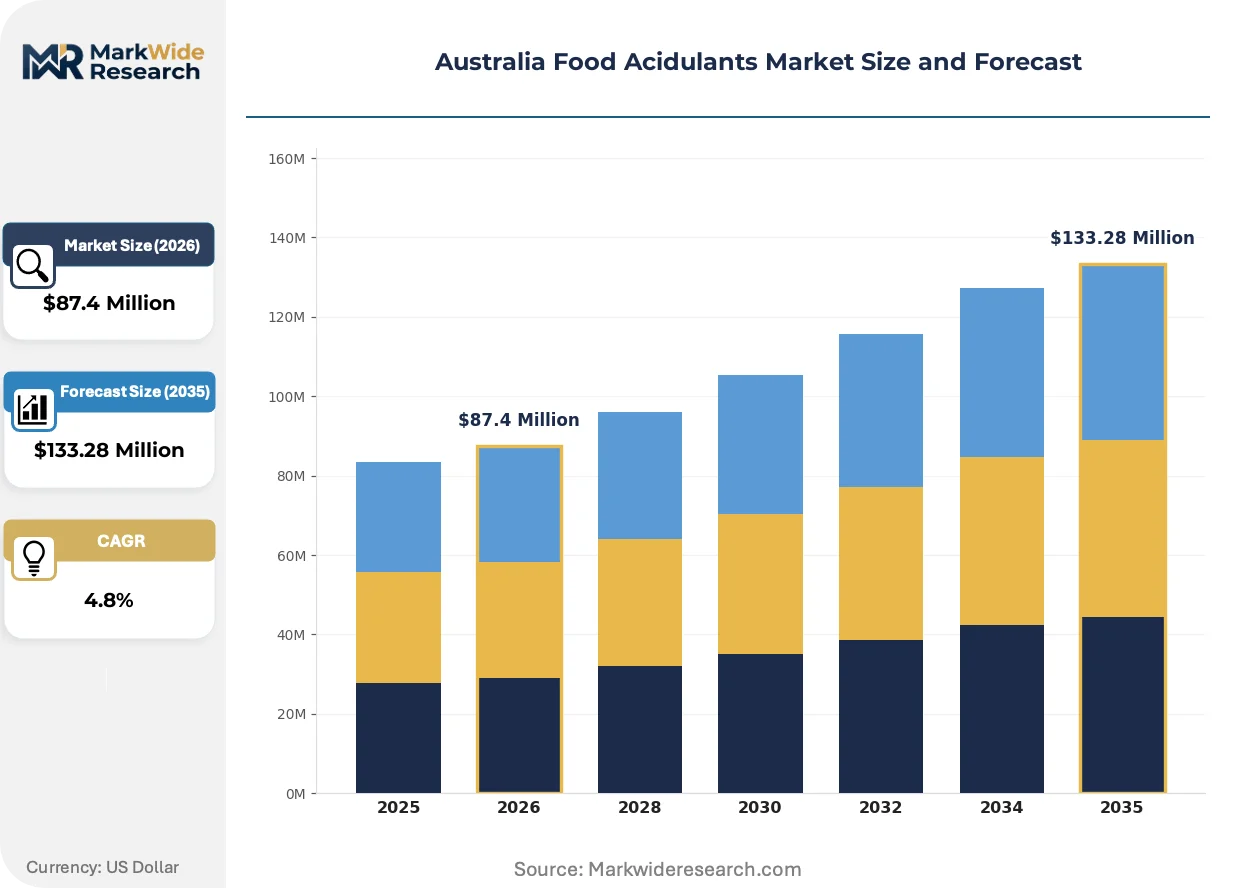
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $133.28 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Acetic Acid, Phosphoric Acid Application: Beverages, Dairy Products, Confectionery, Snacks End User: Food & Beverage Manufacturers, Culinary Professionals, Retail Consumers, Food Service Providers Packaging Type: Bags, Drums, Bulk Containers, Sachets |
| Companies Covered | Tate & Lyle, Cargill Incorporated, Archer Daniels Midland Company, Jungbunzlauer Suisse AG, Corbion, Brenntag North America, Inc., Bartek Ingredients Inc., Weifang Ensign Industry Co., Ltd., Univar Solutions LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Acidulants Market Strategic Shifts
Acidulant formulation is pivoting toward precision pH management systems that integrate real-time monitoring with automated dosing, compressing batch variability while tightening regulatory compliance windows for Australian processors.
Precision fermentation-derived acidulants are modularizing supply chain architecture by enabling regional production of citric and lactic acid variants from locally sourced carbohydrate feedstocks. Queensland bioprocessing pilot facilities are validating these systems for commercial scale-up. The technology is modularizing procurement geography away from concentrated import dependence toward distributed domestic fermentation capacity.
FSANZ Standard 1.3.1 additive labelling amendments are forcing granular disclosure of acidulant sub-types and concentrations on beverage packaging. Melbourne and Sydney bottlers are reformulating toward simpler acidulant profiles to reduce label complexity. Dairy processors in Victoria are most affected, accelerating shift toward single-acid systems that minimize declaration footprint.
Buyer concentration among national beverage chains is compressing acidulant supplier negotiation cycles from annual to quarterly terms. Direct sourcing agreements are displacing traditional distributor relationships for high-volume citric acid contracts. This pattern is most visible in New South Wales, where Coles and Woolworths private-label beverage procurement teams are consolidating acidulant vendor bases.
Australia Food Acidulants Market Segmentation
Acidulant procurement patterns across Australia diverge sharply between high-volume commodity grades serving mass-market bottlers and certified-traceability premium grades commanding margin premiums in export-oriented dairy operations. Segmentation clarity enables suppliers to align fermentation capacity, certification investments, and logistics configurations with distinct buyer value chains.
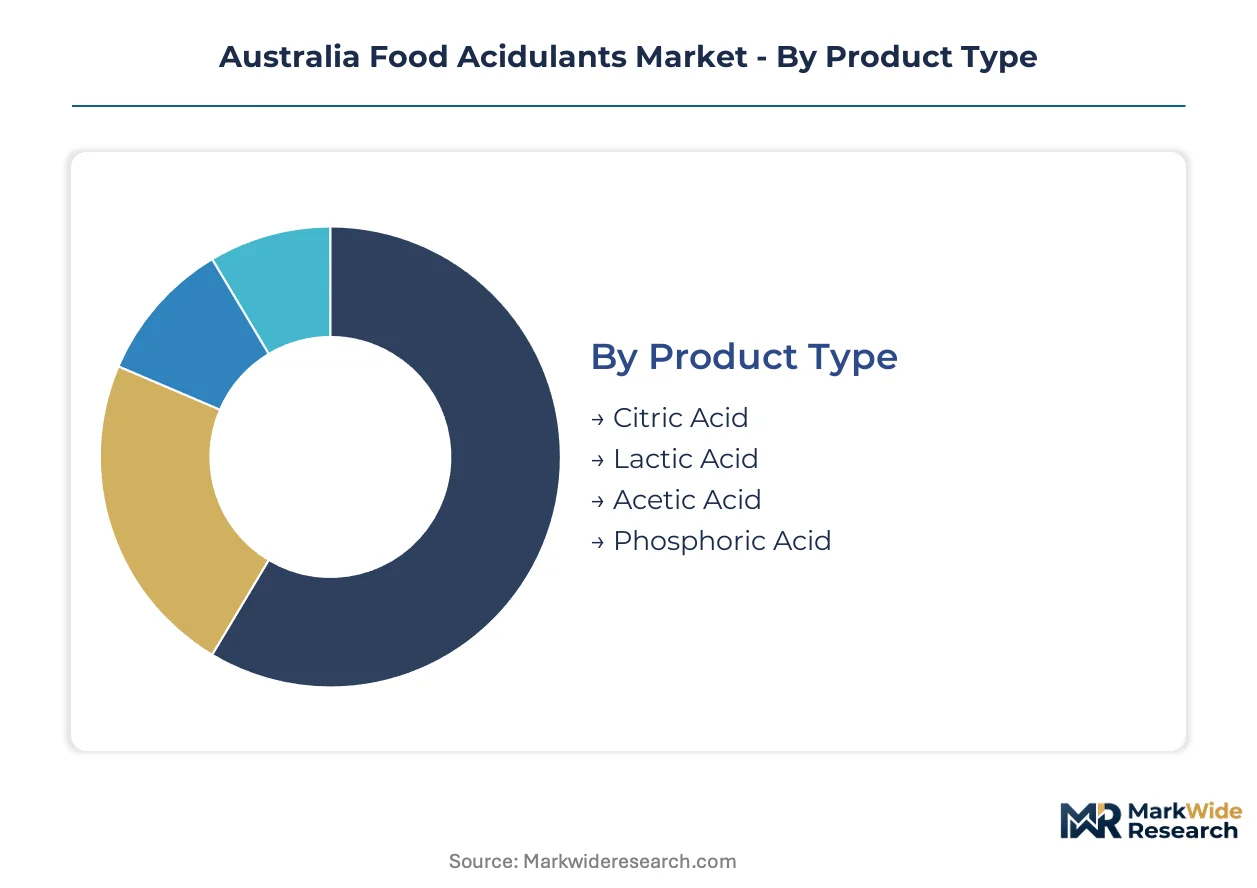
Product Type:
Citric acid dominates tonnage flows through Melbourne and Sydney ports, while lactic acid captures premium positioning through fermentation-derived credentialing demanded by Victorian dairy processors.
- Citric Acid:A tricarboxylic acid produced via Aspergillus niger fermentation of molasses or sucrose, prized for pH buffering across beverage acidification and antioxidant synergy. Procurement concentrates in New South Wales beverage clusters where bottlers require consistent USP-grade supply for carbonated and functional drink lines.
- Lactic Acid:An alpha-hydroxy acid derived from carbohydrate fermentation, commanding margin premiums in dairy applications where natural-origin labelling supports export market access. Victorian processors prioritize verified fermentation pathways to satisfy FSANZ disclosure requirements and Asian import protocols.
- Acetic Acid:A two-carbon carboxylic acid primarily deployed in pickled snack formulations and condiment acidification, with demand anchored in South Australian vegetable processing facilities.
- Phosphoric Acid:An inorganic mineral acid retaining structural importance in cola-type beverages despite technical barriers to complete substitution in shelf-stable formulations.
Mature deployment sits with citric acid. Newer deployment is concentrated in lactic acid.
Application:
End-use segmentation tracks the divergence between pH-stabilized functional beverage expansion and traditional dairy acidification, with confectionery representing an emerging clean-label battleground.
- Beverages:Acidification of carbonated soft drinks, electrolyte formulations, and probiotic drink lines, where Melbourne and Sydney bottlers are scaling procurement for pH-stabilized functional variants ahead of FSANZ disclosure tightening.
- Dairy Products:pH regulation and fermentation control in yogurt, cheese, and cultured butter production, with Victorian processors driving demand for fermentation-derived lactic acid with full supply chain traceability.
- Confectionery:Acid coating and flavor enhancement in gummy and hard candy applications, where clean-label reformulation is accelerating shift toward single-acid systems that minimize FSANZ declaration footprint.
- Snacks:Flavor acidification in seasoned chips and extruded products, with procurement concentrated among New South Wales contract manufacturers serving private-label retail programs.
Volume concentration anchors beverages. Margin expansion is climbing the fastest in dairy products.
End User:
Buyer structure segments between consolidated national beverage chains compressing supplier negotiation cycles and fragmented food service operators purchasing through distributor layers.
- Food & Beverage Manufacturers:Large-scale processors including Sydney and Melbourne bottlers and Victorian dairy cooperatives, directly sourcing acidulants through quarterly procurement cycles that displace traditional annual distributor contracts.
- Culinary Professionals:Restaurant and institutional kitchen operators purchasing acidulants through food service distributors, with demand concentrated in metropolitan Sydney and Melbourne hospitality clusters.
- Retail Consumers:Small-format sachet and bottle purchases for home fermentation and cooking applications, a marginal segment served through supermarket condiment aisles.
- Food Service Providers:Contract caterers and institutional feeding operations, including mining-camp catering networks in Western Australia where acidulant procurement runs through centralized procurement hubs.
Procurement scale concentrates with food and beverage manufacturers. Emerging demand patterns are surfacing in food service providers.
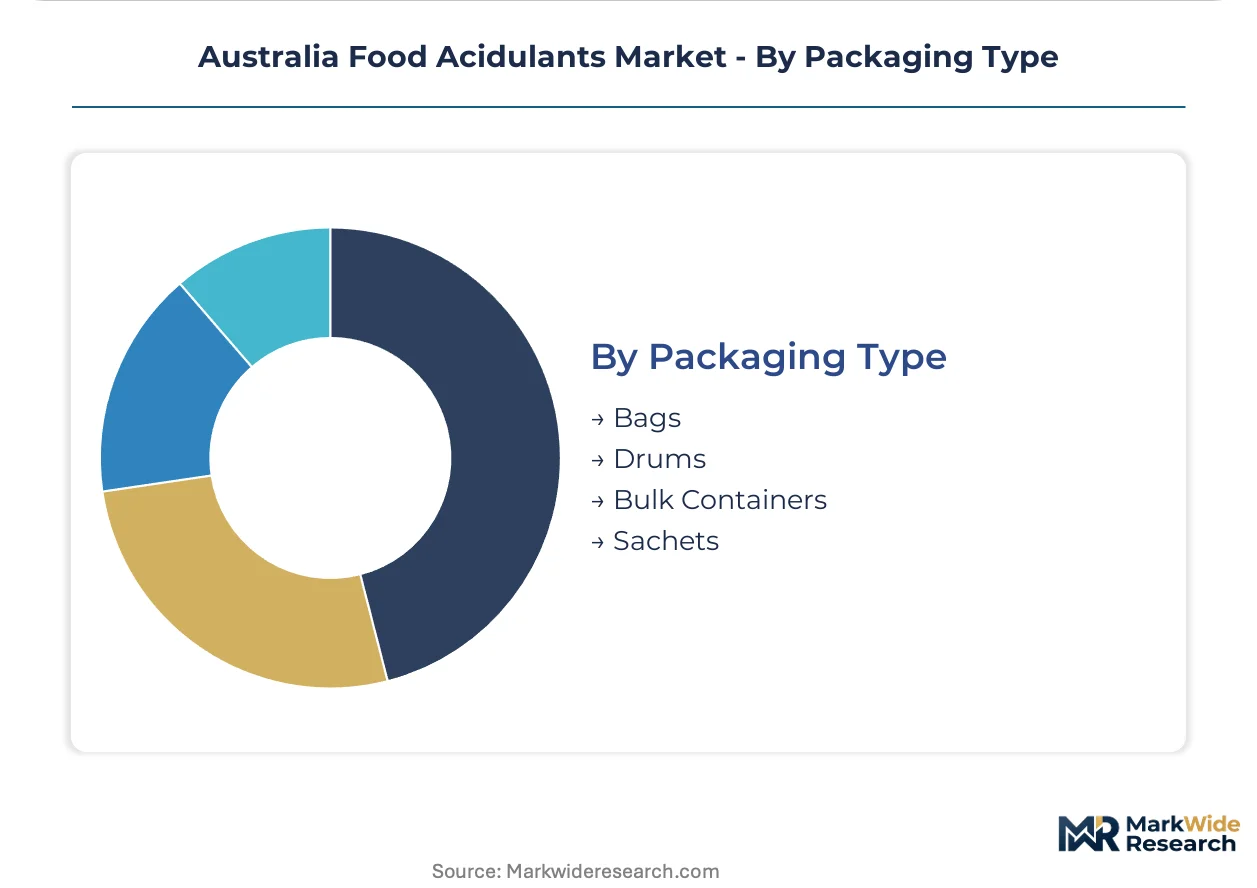
Packaging Type:
Packaging segmentation reflects the tension between bulk import efficiency through Melbourne and Sydney container terminals and distributed blending requirements serving regional processors.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for high-volume citric acid users, with import concentration creating single-point vulnerability for Queensland and South Australian processors distant from port infrastructure.
- Drums:Standard 200-liter polyethylene drums for mid-tier dairy processors requiring manageable batch sizes and flexible inventory rotation.
- Bags:Multi-layer paper and woven polypropylene sacks for dry acidulant variants, serving compounders and smaller beverage operations with moderate throughput requirements.
- Sachets:Single-use foil and laminate pouches for food service portion control and retail consumer formats, representing a low-volume, high-SKU complexity segment.
Logistics efficiency favors bulk containers. Format diversification is gaining share fastest in bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne anchor Australian acidulant procurement through concentrated beverage and dairy processing clusters that handle the majority of national import volumes.
New South Wales
Sydney bottlers drive citric acid demand for carbonated and functional drink lines, with procurement cycles compressing to quarterly terms under retailer consolidation. FSANZ labelling mandates are accelerating reformulation timelines ahead of disclosure deadline tightening. Port Botany handles the bulk of acidulant raw material imports serving southeastern processors.
Victoria
Melbourne dairy cooperatives prioritize fermentation-derived lactic acid with verified supply chain traceability for export market access. Victorian processors face the most acute FSANZ Standard 1.3.1 compliance pressure, driving shift toward single-acid systems. The state's dairy manufacturing corridor concentrates acidulant blending capacity for cultured product lines.
Queensland
Bioprocessing pilot facilities in Queensland are validating precision fermentation systems for regional citric acid production from locally sourced carbohydrates. State processors remain vulnerable to Melbourne and Sydney port concentration for imported acidulant supply. Emerging beverage manufacturing in Brisbane is scaling procurement for electrolyte and probiotic formulations.
Western Australia
Perth presents underdeveloped acidulant blending capacity relative to mining-camp catering and remote beverage distribution demand. The state's isolation from eastern port infrastructure creates procurement cost premiums for inland processors. Western Australia's food service providers run acidulant procurement through centralized hubs serving fly-in-fly-out operations.
South Australia
Adelaide vegetable processors anchor acetic acid demand for pickled snack and condiment formulations. The state's processors face similar port concentration vulnerability as Queensland, with supply chains funneling through Melbourne container terminals. South Australian compounders moderate throughput requirements through flexible bag-format procurement.
Australia Food Acidulants Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade and traceability dimensions, with fermentation-derived credentialing commanding price premiums in dairy applications. The vendor base stratifies between global ingredient conglomerates with integrated fermentation capabilities and regional distributors serving spot-market procurement. Three archetypes dominate: scale-driven multinationals with captive supply chains, specialty acidulant blenders targeting clean-label confectionery, and trading houses compressing distributor layers through digital B2B platforms. Competitive moves center on backward integration into fermentation feedstock control and direct sourcing agreements that displace traditional annual distributor contracts.
Within the multinational tier, Tate & Lyle and Cargill Incorporated occupy positions anchored by global ingredient portfolios and integrated fermentation infrastructure. Jungbunzlauer Suisse AG represents the specialty-blender archetype with European headquarters signaling concentration in fermentation-derived acidulant credentials. These three entities exemplify the competitive tension between scale-driven commodity supply and premium-grade certification investments that define procurement negotiations with Australian beverage and dairy processors.
| Leading Market Players |
|---|
| Tate & Lyle |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Jungbunzlauer Suisse AG |
| Corbion |
| Brenntag North America, Inc. |
| Bartek Ingredients Inc. |
| Weifang Ensign Industry Co., Ltd. |
| Univar Solutions LLC |
| Others |
Value Chain & Pricing Dynamics
Fermentation technician concentrations in Melbourne's biotechnology corridor compress labor-cost differentials between premium-grade and commodity acidulant tiers. Victorian processors pay margin premiums for certified-traceable lactic acid while New South Wales bottlers negotiate spot-market citric acid on bulk volume scales.
Pricing Analysis
Yield-guaranteed contract structures anchor acidulant pricing to consistent pH performance in finished beverage batches. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-verified grades from commodity bulk supply. Cost compression in standard-tier citric acid is intensifying because Brazilian molasses feedstock volatility squeezes compounder margins. National beverage chains show least price sensitivity due to quarterly procurement consolidation, while mid-tier dairy processors exhibit highest sensitivity to certification-grade premiums.
Supply Chain Analysis
FSANZ additive reclassification timelines are gating supplier qualification windows and compressing vendor onboarding cycles for new acidulant entrants. Manufacturing concentration centers on China, Brazil, and Thailand for citric acid fermentation capacity, with European suppliers anchoring premium lactic acid production. Australian procurement draws from molasses-derived feedstocks, sucrose substrates, and mineral phosphate sources. Single-source vulnerability runs through Melbourne and Sydney container terminals for Queensland and South Australian processors distant from port infrastructure. Distribution runs through integrated distributor networks for spot purchases and direct manufacturer agreements for high-volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian acidulant supply operates under fermentation capacity constraints that prop pricing premiums for verified-origin grades. Import bottleneck concentration at eastern ports sustains regional price differentials.
For Market Incumbents: Anchor market position through backward integration into carbohydrate feedstock sourcing and captive fermentation capacity additions in Queensland bioprocessing corridors. Tate & Lyle and Cargill should defend against specialty-blender encroachment by accelerating FSANZ pre-certification investments that compress new entrant qualification timelines. Channel control through direct sourcing agreements with Coles and Woolworths procurement teams remains the critical defensive lever. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Victorian dairy acidulants offers white-space entry for fermentation-credentialed regional suppliers. Target Western Australia's underdeveloped Perth blending capacity for mining-camp catering contracts. Queensland bioprocessing pilot facilities present the most penetrable geography for domestic citric acid scale-up. A digital B2B platform go-to-market angle compresses distributor layers for mid-tier processor spot purchasing. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation technology providers given FSANZ organic acid incentive alignment in anticipated standard revisions. Long-term viability favors modular bioprocessing assets capable of distributed regional production. Acquisition target archetype: Australian specialty acidulant blenders with clean-label confectionery formulations and existing FSANZ certification pathways. Watch Queensland pilot facility commercialization timelines as the inflection signal for domestic supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Queensland bioprocessing pilots validate modular citric acid production from local carbohydrate feedstocks. |
| Backward Integration into Feedstock | Cargill's captive molasses sourcing insulates margin stability from Brazilian harvest cycle volatility. |
| FSANZ Pre-Certification Investment | Jungbunzlauer's early disclosure compliance compresses competitor qualification windows for clean-label segments. |
| Direct-to-Manufacturer Digital Platform | Emerging B2B channels displace distributor layers for Victorian dairy processor spot citric acid purchases. |
| Western Australia Regional Blending Capacity | Perth facility development captures mining-camp catering demand currently served through eastern port supply chains. |
Study Parameters
FSANZ consultation archives, Australian Bureau of Agricultural and Resource Economics trade data, and company SEC filings formed the secondary backbone for this analysis. Primary interviews with beverage formulation chemists, dairy processing plant managers, acidulant procurement leads, and FSANZ regulatory affairs officers validated demand assumptions. Bottom-up volume estimates from individual processor procurement cycles were triangulated against top-down trade flow analysis.
Historical trendline analysis of import volumes through Melbourne and Sydney ports established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including acidulant grade tier, end-use application, packaging format, and state-level processing cluster. CAGRs were derived from regression analysis of volume trends adjusted for regulatory compliance timeline impacts. Forecast inputs incorporated FSANZ Standard 1.3.1 amendment schedules and precision fermentation technology maturation curves.
Inputs from FSANZ consultation papers and Australian customs records were available through the study window; gaps in proprietary processor procurement contract terms introduce uncertainty bands around quarterly pricing estimates. Forecasts reflect assumptions regarding molasses feedstock price stability and fermentation capacity expansion timelines. A model refresh is warranted upon material change in FSANZ organic acid reclassification outcomes or Queensland bioprocessing commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Pyranose Oxidase Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Nutraceutical Excipients Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market