
 Australia Feed Additives Market | 2026-2036
Australia Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Feed Additives Market Outlook
Veterinary pharmaceutical distributors are reshaping how feed additives reach Australian livestock producers, consolidating regional supply networks and tightening technical service requirements. DSM Nutritional Products AG leverages its premix manufacturing footprint to sustain direct relationships with large integrated poultry operators. Cargill Inc. competes through backward integration into grain origination, anchoring cost-advantaged additive formulations for Queensland feedlots. Novus International, Inc. differentiates via methionine analog specialization, occupying a narrow but defensible position in ruminant methionine supplementation.
Australia feed additives comprise biologically active compounds including enzymes, organic acids, probiotics, and antioxidant compounds formulated at precise inclusion rates to enhance feed conversion, gut health, and nutrient bioavailability in animal diets. Manufacturing employs spray-drying, microencapsulation, and fermentation-derived synthesis to achieve thermostability and targeted release in digestive tracts. Enzyme additives lead product type value generation due to persistent phytase and NSP-enzyme demand in wheat-based Australian rations. Probiotics represent the fastest-expanding category as APVMA antimicrobial reduction timelines accelerate live culture adoption. Acidifiers command concentrated margin pools in weaner pig and broiler starter applications where gastric pH modulation delivers measurable performance returns.
APVMA registration protocols govern active ingredient approval timelines and residue monitoring requirements for all imported and domestically manufactured feed additives. FSANZ standards intersect with feed safety through maximum contaminant thresholds that cascade into additive purity specifications. The Australian Competition and Consumer Commission monitors distributor consolidation for regional supply access impacts. Stakeholders must track APVMA re-registration schedules for legacy antibiotic growth promoters and position enzyme-probiotic portfolios ahead of formulation mandate transitions.
Market Dynamics
APVMA antimicrobial reduction mandates are compressing formulation windows for Australian livestock producers, forcing accelerated transitions toward enzyme-probiotic combinations before legacy growth promoter registrations expire.
Growth Catalysts
- APVMA Re-registration Schedules:Phased withdrawal timelines for antibiotic growth promoters create mandatory substitution demand, pulling live culture and phytase formulations into ruminant and poultry rations ahead of compliance deadlines.
- Queensland Feedlot Corridor Concentration:Intensive cattle finishing operations in the Darling Downs and Roma districts generate sustained bulk demand for rumen-protected amino acids and mycotoxin binders at scale.
- Victorian Dairy Belt Expansion:High-input dairy systems across Gippsland and northern Victoria deploy precision mineral and buffer additives to sustain production through seasonal pasture quality fluctuations.
Market Restraints
- Grain Price Volatility:Wheat and barley input costs fluctuate with global origination patterns, compressing margin pools for compound feed manufacturers who must absorb or pass through additive formulation costs.
- Import Concentration Risk:Active ingredient supply concentrates among European and North American fermentation specialists, exposing Australian formulators to currency and shipping cost instability.
- Thermostability Limitations:Live probiotic cultures face viability losses during pelleting temperatures above 85°C, restricting inclusion rates in steam-processed broiler and pig starter feeds.
Strategic Opportunities
- Tasmanian Aquaculture Adjacent:Salmon and trout feed additive requirements remain underdeveloped relative to livestock, presenting white space for gut health and pigment formulations tailored to cold-water species.
- FSANZ Residue Monitoring Alignment:Maximum contaminant threshold tightening creates premium positioning for certified contaminant-free additive lines in export-oriented supply chains.
- Direct-to-Producer Digital Channels:Veterinary pharmaceutical distributors are consolidating, opening bypass routes for additive manufacturers to engage large integrated operators through technical service platforms.
Industry Challenges
- Microbiology Formulation Expertise Gap:Live culture stabilization and strain compatibility screening require specialized fermentation knowledge scarce among traditional mineral and vitamin premixers.
- APVMA Registration Timeline Compression:Novel active ingredient approvals stretch across multi-year evaluation cycles, delaying commercialization of next-generation enzyme variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Feed Additives Market |
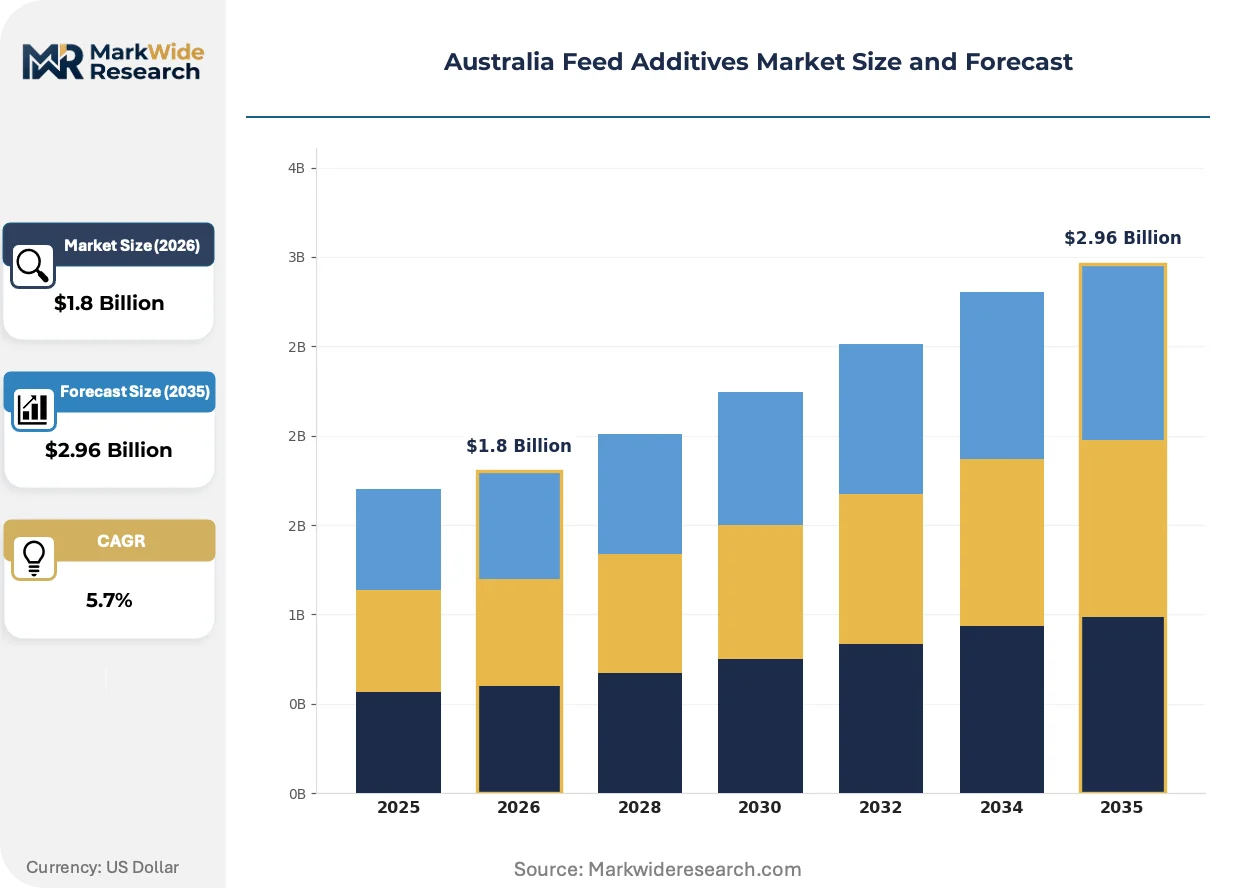
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Acidifiers, Enzymes, Probiotics Application: Livestock, Poultry, Aquaculture, Ruminants Form: Powdered, Liquid, Granular, Pelleted Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers |
| Companies Covered | SHV (Nutreco NV), Archer Daniels Midland Co., DSM Nutritional Products AG, Cargill Inc., BASF SE, IFF (Danisco Animal Nutrition), Solvay S.A., Novus International, Inc., Lonza Group Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Feed Additives Market Strategic Shifts
Multi-enzyme complex formulations are displacing single-activity additives across Australian wheat-based rations, while regulatory pressure on antimicrobial residues accelerates live culture adoption timelines.
Microencapsulation technology for rumen-protected methionine and lysine is collapsing the cost-performance gap between synthetic amino acids and intact protein sources in high-production dairy diets. Victorian dairy cooperatives are adopting these formulations at accelerated rates to maintain milk protein yields during spring pasture dilution periods. The structural consequence is compression of traditional blood meal and cottonseed meal inclusion rates in precision-formulated TMR systems.
APVMA's revised guidelines on antimicrobial resistance management now mandate veterinary prescription pathways for all remaining antibiotic growth promoters in pig and poultry feeds. This regulatory friction is redirecting formulation R&D budgets toward organic acid and medium-chain fatty acid blends with documented gut health mechanisms. Queensland broiler integrators are responding fastest, restructuring starter diet specifications to eliminate sub-therapeutic antibiotic dependencies before 2027 phase-out deadlines.
Large integrated livestock operators are consolidating procurement decisions at the corporate level, displacing decentralized purchasing through regional farm supply cooperatives. This buyer concentration is compressing distributor margins and demanding bundled technical service contracts covering nutrition consulting, feed analysis, and on-farm troubleshooting. The pattern is most visible across New South Wales Riverina poultry and feedlot operations, where direct manufacturer relationships now dominate volume flows.
Australia Feed Additives Market Segmentation
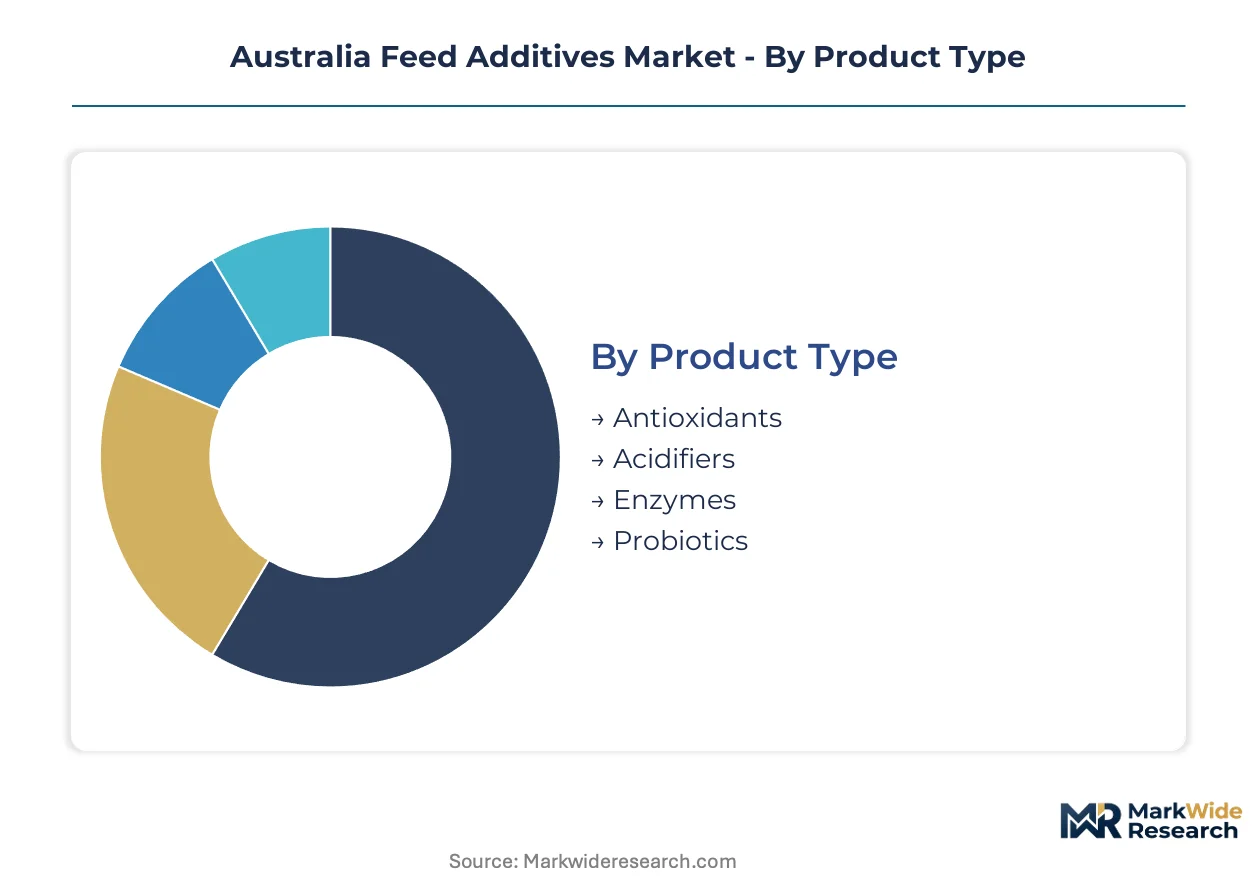
Australian feed additive procurement patterns diverge sharply across product categories and application contexts. Formulation requirements in Queensland feedlots differ fundamentally from Victorian dairy operations, creating distinct segment performance profiles.
Product Type:
Enzyme additives turn over fastest in formulation cycles as wheat-based rations drive persistent phytase and NSP-enzyme refresh rates, while probiotic cultures face slower adoption curves due to live culture stabilization challenges.
- Enzymes:Phytase and non-starch polysaccharide complexes dominate wheat-based Australian rations. Queensland poultry integrators and Darling Downs feedlots deploy multi-enzyme formulations to extract maximum metabolizable energy from local grain profiles.
- Probiotics:Live culture additives face thermostability constraints during pelleting above 85°C. APVMA antimicrobial reduction timelines compress substitution windows, accelerating Bacillus and Lactobacillus strain adoption across New South Wales broiler operations.
- Acidifiers:Organic acid blends command concentrated margin pools in weaner pig and broiler starter feeds where gastric pH modulation delivers measurable performance returns.
- Antioxidants:Ethoxyquin and BHT formulations protect lipid stability in high-fat premixes and extruded aquafeeds.
Enzymes anchor the volume base while probiotics gains share at the steepest rate.
Application:
Cost tier stratification separates intensive commercial operations from pasture-based systems, with high-input dairy and feedlot segments absorbing premium additive formulations while extensive grazing operations minimize supplementation.
- Ruminants:Dairy cattle operations in Gippsland and northern Victoria drive rumen-protected amino acid and buffer additive demand. Seasonal pasture quality fluctuations force precision mineral supplementation to sustain milk protein yields through spring dilution periods.
- Poultry:Broiler integrators across New South Wales Riverina and Queensland restructure starter diet specifications to eliminate sub-therapeutic antibiotic dependencies. Multi-enzyme complexes and organic acid blends dominate reformulation budgets.
- Livestock:Pig producers concentrate acidifier demand in weaner phases where gastric pH modulation reduces post-weaning growth checks.
- Aquaculture:Tasmanian salmon and trout operations remain underdeveloped relative to livestock, presenting white space for gut health and pigment formulations tailored to cold-water species.
Ruminants absorb the highest additive expenditure per head while poultry delivers the steepest volume expansion trajectory.
Form:
Supply concentration in steam-pelleting infrastructure across southeastern Australia dictates form selection, with thermal processing compatibility determining viable additive matrices.
- Powdered:Base premix carriers facilitate precise micro-ingredient dispersion in on-farm mixing systems. Victorian dairy cooperatives favor powdered mineral and vitamin blends for TMR integration.
- Pelleted:Steam-processed feeds above 85°C constrain live probiotic inclusion, favoring thermostable enzyme and antioxidant matrices. Queensland feedlot compounders specify pelleted formulations for handling efficiency.
- Liquid:Post-pelleting application systems enable heat-sensitive additive delivery in broiler and pig starter feeds.
- Granular:Intermediate flowability suits automated dispensing in mid-scale operations.
Pelleted forms dominate commercial compound feed channels while liquid application gains traction for heat-sensitive actives.
Distribution Channel:
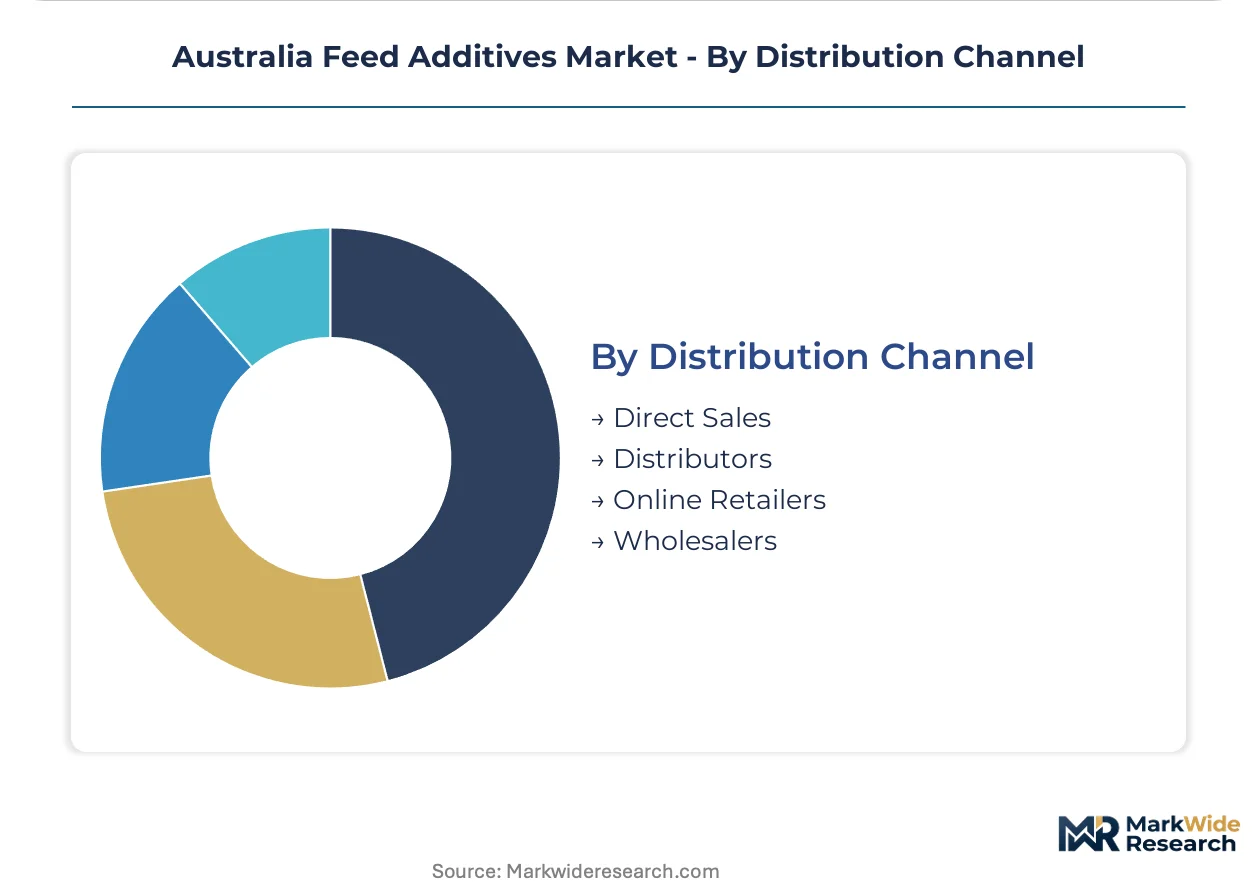
Customer type fragmentation separates large integrated operators from decentralized farm supply cooperatives, with procurement centralization reshaping channel economics.
- Distributors:Veterinary pharmaceutical distributors consolidate regional supply networks and tighten technical service requirements. These intermediaries dominate mid-scale livestock producer access across regional New South Wales and Victoria.
- Direct Sales:Large integrated poultry and feedlot operators bypass distributor tiers through direct manufacturer relationships. Bundled technical service contracts covering nutrition consulting and feed analysis accompany volume commitments.
- Wholesalers:Farm supply cooperatives retain relevance in extensive grazing zones where additive demand fragments across smallholder operations.
- Online Retailers:Digital channels emerge for standardized mineral premixes and generic acidifier blends in hobby farm and smallholder segments.
Distributors retain the broadest geographic coverage while direct sales capture the steepest share growth among large integrated operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
APVMA registration protocols govern active ingredient approval timelines across Australian states, with regulatory enforcement cascading through state agricultural departments and creating distinct operational conditions for feed additive procurement.
New South Wales
Broiler integrators across the Riverina restructure starter diet specifications to eliminate sub-therapeutic antibiotic dependencies. FSANZ maximum contaminant thresholds cascade into additive purity specifications for export-oriented poultry supply chains. The Riverina poultry cluster now dominates volume flows through direct manufacturer relationships.
Victoria
Gippsland and northern Victoria dairy operations deploy precision mineral and buffer additives to sustain production through seasonal pasture quality fluctuations. APVMA antimicrobial reduction timelines compress substitution windows for live culture adoption. Victorian dairy cooperatives are adopting microencapsulated rumen-protected methionine formulations at accelerated rates.
Queensland
Intensive cattle finishing operations in the Darling Downs and Roma districts generate sustained bulk demand for rumen-protected amino acids and mycotoxin binders. The state's feedlot corridor concentration creates scale advantages for compound feed manufacturers. Queensland feedlot compounders specify pelleted formulations for handling efficiency across bulk handling infrastructure.
Western Australia
Grain-sheep integration systems in the Wheatbelt minimize additive expenditure per head relative to intensive eastern states operations. The state's national pharmaceutical regulator enforces residue monitoring alignment with export market access requirements. Perth-based distributors serve extensive grazing zones where additive demand fragments across smallholder operations.
South Australia
Pig producers in the Adelaide Plains and southeast concentrate acidifier demand in weaner phases where gastric pH modulation reduces post-weaning growth checks. The state's agricultural department tracks APVMA re-registration schedules for legacy antibiotic growth promoters. The Murraylands pork cluster maintains relevance through regional farm supply cooperative networks.
Australia Feed Additives Market Competitive Environment
Multinational nutrition specialists and integrated agribusiness conglomerates split the market between premium formulation expertise and cost-advantaged grain origination. The vendor base concentrates among fermentation-derived active ingredient suppliers and premix manufacturing networks. Three archetypes dominate: premix specialists with direct large-operator relationships, grain-integrated formulators leveraging backward supply chain control, and narrow technology licensors occupying defensible positions in single-active categories. Competitive moves center on distributor consolidation for regional coverage and bundled technical service contracts covering nutrition consulting and feed analysis.
Within the premix specialist tier, DSM Nutritional Products AG and Novus International, Inc. exemplify divergent positioning strategies. DSM leverages its manufacturing footprint to sustain direct relationships with large integrated poultry operators through bundled service contracts. Novus occupies a narrow but defensible position in ruminant methionine supplementation via methionine analog specialization. Among grain-integrated agribusinesses, Cargill Inc. anchors cost-advantaged additive formulations for Queensland feedlots through captive supply of wheat and barley origination. These three companies represent the structural fault lines between technology-driven premium positioning and origination-driven cost leadership.
| Leading Market Players |
|---|
| SHV (Nutreco NV) |
| Archer Daniels Midland Co. |
| DSM Nutritional Products AG |
| Cargill Inc. |
| BASF SE |
| IFF (Danisco Animal Nutrition) |
| Solvay S.A. |
| Novus International, Inc. |
| Lonza Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European fermentation-derived active ingredient production is compressing supplier pricing power while simultaneously elevating buyer leverage across Australian feed additive procurement. Queensland feedlot operators and Victorian dairy cooperatives exploit this utilization slack to extract volume discounts on rumen-protected amino acids and enzyme complexes.
Pricing Analysis
Queensland-to-Victoria price spreads of 8-12% reflect freight absorption disparities between Darling Downs bulk compounders and Gippsland dairy premix buyers. Three-tier pricing structure across premium-certified, standard-grade, and economy generic levels stratifies the market, with APVMA registration status and FSANZ contaminant certification serving as the primary differentiation levers. Cost compression in economy-tier phytase formulations is intensifying because grain price volatility forces compound feed manufacturers to squeeze additive inclusion budgets. Smallholder graziers in Western Australia's Wheatbelt exhibit acute price sensitivity, while New South Wales Riverina poultry integrators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between European Union fermentation specialists and Australian formulators dominates supply chain risk calculus for live culture and enzyme actives. Active ingredient manufacturing concentrates in the Netherlands, Germany, and Denmark, with Australian formulators drawing from these hubs for thermostable phytase and Bacillus strain supplies. Raw material dependencies on wheat and barley origination, petroleum-derived encapsulation polymers, and pharmaceutical-grade fermentation substrates create multi-point vulnerability. Single-source concentration among three European enzyme houses amplifies disruption risk from currency fluctuation or shipping lane congestion. Distribution runs through veterinary pharmaceutical distributors for mid-scale producers, while direct manufacturer relationships now dominate large integrated operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia feed additives market is recovering from a cyclical trough driven by drought-induced herd liquidation and subsequent restocking demand. APVMA antimicrobial phase-out timelines are compressing substitution windows and accelerating capital deployment into enzyme-probiotic manufacturing capacity.
For Market Incumbents: Entrench position through backward integration into Australian-based fermentation capacity to mitigate European supply concentration risk and tariff exposure. Secure exclusive Bacillus strain licensing from Australian research institutions ahead of competitor R&D cycles. Prioritize bundled technical service contracts covering nutrition consulting and on-farm troubleshooting to defend margin pools against distributor disintermediation.
For New Entrants and Emerging Players: Tasmanian aquaculture additive supply remains structurally underpenetrated relative to livestock segments, presenting white space for cold-water species gut health formulations. Target salmon feedlot operators with post-pelleting liquid application systems that bypass thermostability constraints plaguing live culture competitors. Pursue direct-to-producer digital channels for standardized mineral premixes in hobby farm segments where distributor coverage fragments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microencapsulation manufacturing as Victorian dairy demand for rumen-protected methionine accelerates. Long-term viability favors acquisition targets possessing strain stabilization IP and APVMA registration expertise rather than commodity premix capacity. Monitor Queensland feedlot restocking rates as the inflection signal for additive volume recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive production of thermostable enzymes reduces European supply dependency and tariff exposure for Queensland feedlot compounders. |
| Microencapsulation Technology Licensing | Rumen-protected methionine formulations displace blood meal inclusion in Victorian dairy TMR systems during spring pasture dilution. |
| Direct-to-Producer Digital Channel Launch | Bypass of consolidating veterinary pharmaceutical distributors captures margin from New South Wales Riverina poultry integrators. |
| Tasmanian Aquaculture Formulation Development | Cold-water species gut health additives address underdeveloped salmon and trout feed segments relative to livestock markets. |
| APVMA Registration Pipeline Investment | Accelerated approval timelines for next-generation enzyme variants capture substitution demand ahead of antibiotic growth promoter phase-outs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with feedlot nutrition managers, dairy cooperative procurement directors, poultry integrator technical service leads, and veterinary pharmaceutical distributor executives. Secondary validation drew from APVMA registration databases, FSANZ contaminant threshold publications, Australian Bureau of Agricultural and Resource Economics trade data, and SEC filings of multinational nutrition specialists. Bottom-up volume modeling across Queensland feedlot corridors and Victorian dairy belts was triangulated against top-down market sizing from compound feed production statistics.
Calibration against historical substitution elasticities during prior antimicrobial reduction cycles anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, livestock application, thermal processing form, and procurement channel concentration. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends informed by grain price correlation analysis and premium additive adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by European fermentation houses or accelerated APVMA approval pathways for novel actives would shift outcomes. Macroeconomic deviation in grain markets, regulatory acceleration of antimicrobial bans, or breakthroughs in live culture thermostability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Citrus Fruit Coatings Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Food Stabilizer Systems Market