
 North America Food Additives Market | 2026-2036
North America Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Additives Market Analytics
Natural preservatives derived from rosemary extract and fermented cultures is shifting economics away from synthetic benzoates and sorbates across North American formulations. Cargill Incorporated leverages its integrated supply chain from botanical sourcing to finished extracts, anchoring cost advantages in clean-label antioxidant production. Archer Daniels Midland Company competes through fermentation-derived antimicrobial platforms, while Kerry Group PLC specializes in tailored preservative blends for refrigerated ready-to-eat segments.
Food additives comprise substances added to food to preserve flavor, enhance taste, improve appearance, or maintain nutritional value, typically used at concentrations below one percent by weight and governed by purity specifications such as Food Chemicals Codex grades. Their primary commercial purpose spans shelf-life extension, sensory optimization, and functional performance in processed and packaged goods. Preservatives command the largest share of product type value pools due to spoilage mitigation requirements in extended distribution networks, while nutraceuticals represent the fastest-expanding category as fortification demand intersects with beverage and dairy product innovation. Application concentration tilts toward beverages, where acidulants, emulsifiers, and natural colors address carbonated and functional drink formulation complexity.
The FDA oversees GRAS determinations and food additive petitions, while the USDA regulates additives in meat and poultry products through its Food Safety and Inspection Service, and Health Canada administers the Food and Drug Regulations for cross-border product harmonization. These frameworks shape reformulation timelines, label claim permissibility, and import compliance burdens for multi-jurisdictional suppliers. Stakeholders must monitor pending FDA rulemakings on precision fermentation-derived ingredients and evolving Canadian novel food assessments to anticipate approval bottlenecks and first-mover positioning in emerging additive categories.
Market Dynamics
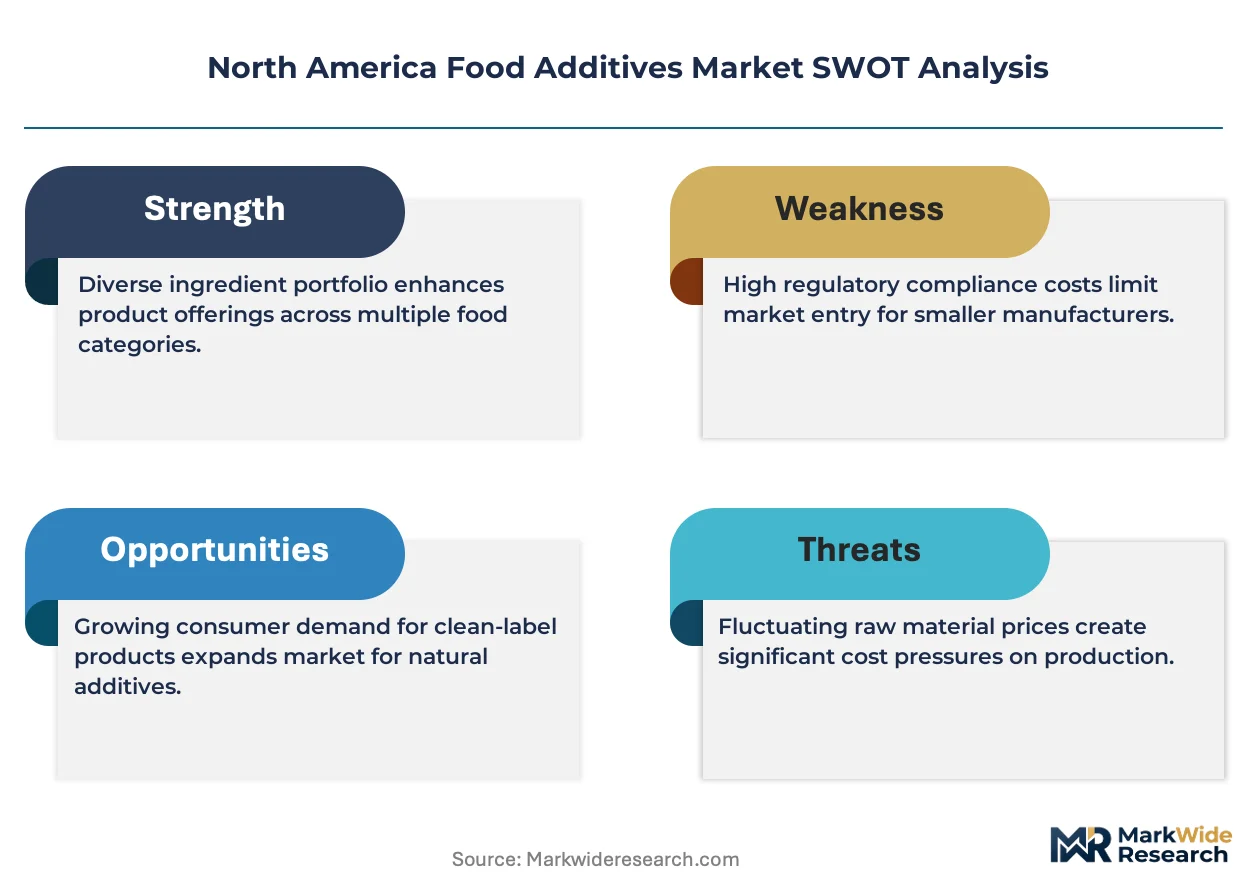
Clean-label reformulation mandates from major retailers are forcing additive suppliers to replace synthetic preservatives with botanical and fermentation-derived alternatives, compressing reformulation timelines and reshaping procurement specifications across processed food manufacturing.
Growth Catalysts
- GRAS Modernization:The FDA's updated Generally Recognized as Safe review framework accelerates approval pathways for novel natural preservatives, reducing time-to-market for clean-label antioxidants derived from rosemary and green tea extracts.
- Plant-Based Protein Fortification:Beverage and dairy manufacturers in the United States are integrating nutraceutical additives to enhance amino acid profiles and sensory performance in oat, pea, and almond-based formulations.
- Extended Distribution Networks:Refrigerated ready-to-eat meal expansion across North American retail channels amplifies demand for tailored antimicrobial blends that maintain safety across longer cold-chain logistics.
Market Restraints
- Botanical Supply Volatility:Rosemary extract and fermented culture feedstocks face harvest variability and climate exposure, creating input cost instability for natural antioxidant producers.
- Cross-Border Regulatory Friction:Divergent novel food assessment timelines between Health Canada's Food and Drug Regulations and FDA GRAS determinations delay synchronized product launches.
- Technical Performance Gaps:Natural antimicrobials exhibit narrower pH stability windows and shorter efficacy durations than synthetic benzoates, limiting direct substitution in high-acid beverage applications.
Strategic Opportunities
- Precision Fermentation Scale-Up:USDA Food Safety and Inspection Service guidance on fermentation-derived ingredients opens regulatory runway for antimicrobial peptides and bioactive compounds in meat and poultry applications.
- Functional Beverage White Space:Adaptogenic and nootropic additive integration into carbonated and still drinks targets stress-relief and cognitive performance claims among millennial and Gen Z consumers in Canada.
- Direct-to-Manufacturer Distribution:Digital procurement platforms enable mid-sized additive suppliers to bypass traditional distributor markups and capture margin in specialty emulsifier and colorant segments.
Industry Challenges
- Clean-Label Talent Scarcity:Food science programs produce insufficient formulation chemists trained in natural preservative synergy mapping and shelf-life modeling.
- Dual Certification Burden:Simultaneous FDA food additive petitions and Health Canada novel food notifications require parallel toxicology studies, doubling compliance expenditure for cross-border suppliers.
- Legacy Equipment Retrofit Costs:Natural colorants and emulsifiers demand modified mixing temperatures and pH controls, forcing capital outlays for processing line upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Additives Market |
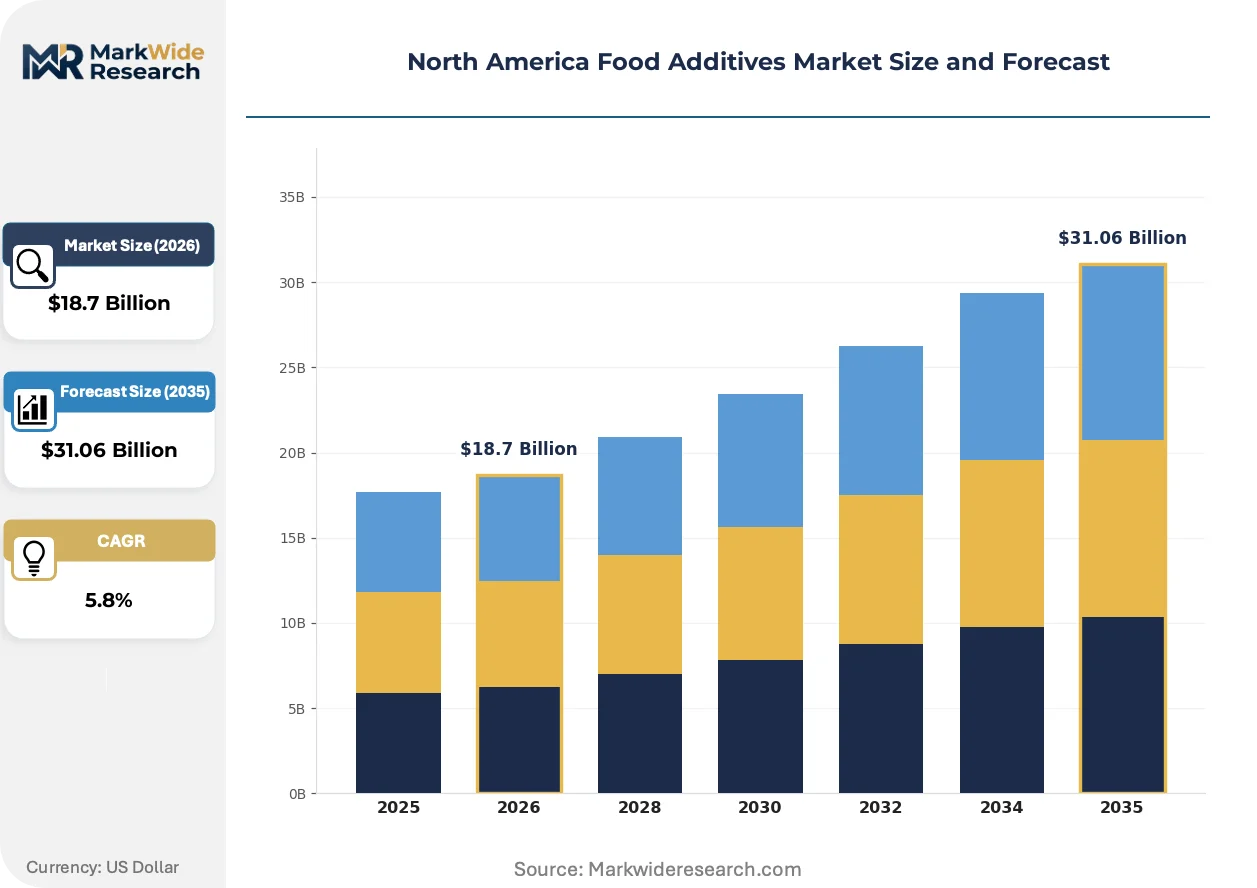
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Flavor Enhancers, Color Additives, Nutraceuticals Application: Beverages, Dairy Products, Bakery, Confectionery Form: Liquid, Powder, Granular, Concentrate Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Kerry Group PLC, BASF SE, International Flavors & Fragrances Inc., Novozymes A/S, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Additives Market Evolving Landscape
Bioprocessing advances and regulatory clarity on fermentation-derived inputs are converging to expand the functional additive palette, while procurement digitization and direct supplier relationships compress traditional channel structures.
Precision fermentation platforms for antimicrobial peptides and bioactive proteins are rewriting the economics of clean-label preservation. Mid-sized dairy and plant-based beverage manufacturers in the United States are adopting these inputs at pilot scale, with commercial volumes expected to follow GRAS affirmation. The technology is compressing minimum viable production runs and enabling regional supply models that bypass concentrated extract import dependencies.
The FDA's pending rulemaking on precision fermentation-derived ingredients is clarifying petition requirements for novel antimicrobial platforms. Food Safety and Inspection Service coordination with USDA on meat and poultry additive applications is streamlining dual-agency review pathways. Refrigerated protein product segments are responding by accelerating internal R&D timelines to secure first-mover positioning in fermentation-derived shelf-life extension.
Ingredient procurement from food manufacturers is consolidating toward direct supplier relationships with integrated botanical sourcing and extraction capabilities. Traditional distributor networks in emulsifier and acidulant categories are losing share to platform-enabled spot purchasing and annual contracting with traceability guarantees. This pattern is most visible in California and Texas, where large beverage co-manufacturers have disintermediated regional distributors for high-volume natural colorant procurement.
North America Food Additives Market Segmentation
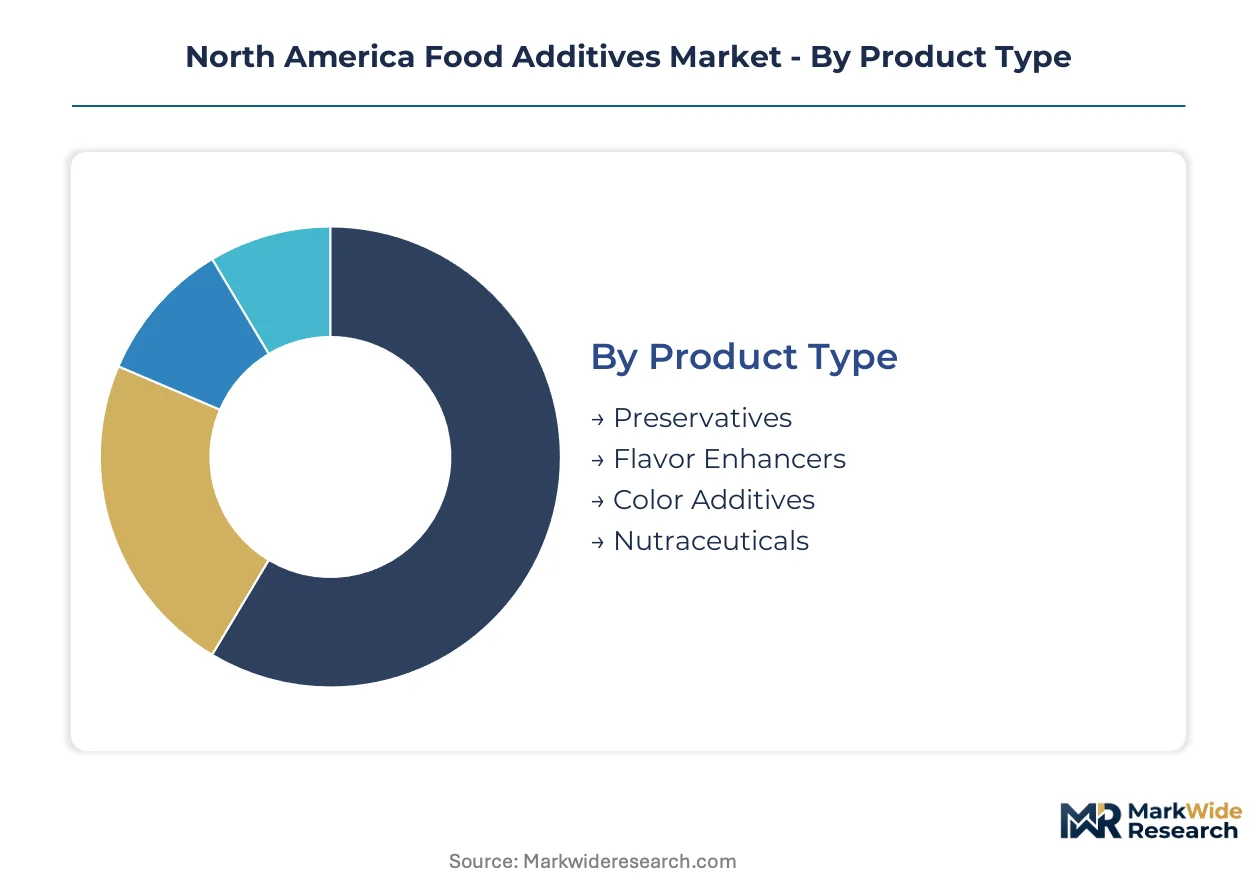
Food additive segmentation in North America reflects divergent technical requirements across preservation chemistry, sensory modification, and nutritional fortification. Procurement patterns vary sharply by application, with beverage manufacturers prioritizing acid-stable formulations while dairy processors emphasize cold-chain antimicrobial performance.
Product Type:
Functional chemistry distinguishes competitive positioning across natural and synthetic platforms.
- Preservatives:Antimicrobial systems span benzoate-sorbate synthetics, rosemary-derived antioxidants, and fermentation-cultured peptides. Extended distribution networks in the United States drive reformulation toward botanical and bioprocessed alternatives as FDA GRAS pathways modernize.
- Nutraceuticals:Protein fortification additives, amino acid premixes, and vitamin-mineral complexes enhance nutritional density in plant-based dairy and functional beverages. Demand concentrates in oat and pea protein applications where sensory masking and bioavailability optimization command premium formulation support.
- Flavor Enhancers:Umami compounds, natural extracts, and yeast-derived flavor precursors modify taste profiles without synthetic labeling triggers.
- Color Additives:Anthocyanin, carotenoid, and caramel-based natural pigments replace azo dyes in clean-label confectionery and beverage segments.
Mature deployment sits with Preservatives. Newer deployment is concentrated in Nutraceuticals.
Application:
End-use specifications dictate additive selection based on processing temperature, pH exposure, and shelf-life targets.
- Beverages:Acidulants, emulsifiers, and natural colors address formulation complexity in carbonated, functional, and plant-based drinks. High-acid environments in the United States favor acid-stable preservative systems and clouding agents for opacity control in juice and dairy alternatives.
- Dairy Products:Fermentation-derived antimicrobials and protein stabilizers maintain safety and texture across extended cold-chain distribution. Refrigerated ready-to-eat segments in Canada and the United States are integrating tailored antimicrobial blends for Listeria control.
- Bakery:Mold inhibitors, dough conditioners, and enzyme-based shelf-life extenders address moisture migration and staling.
- Confectionery:Heat-stable colorants, flavor encapsulation systems, and anti-blooming agents support chocolate and sugar confection processing.
Volume concentration favors Beverages. Margin expansion is steepest in Dairy Products.
Form:
Physical state determines handling economics, dissolution kinetics, and equipment compatibility.
- Liquid:Pumpable concentrates and suspensions enable automated dosing in high-throughput beverage and dairy processing lines. California and Texas beverage co-manufacturers favor liquid acidulants and emulsifiers for continuous blending operations.
- Powder:Spray-dried and agglomerated formats reduce transportation costs and extend stability in humidity-controlled supply chains. Bakery and confectionery applications in the United States and Canada prefer powder preservatives for dry-mix integration.
- Granular:Free-flowing particulates minimize dusting and improve dispersion in bulk handling systems.
- Concentrate:High-potency extracts and oleoresins reduce storage footprint and enable precise dilution at point of use.
Processing infrastructure in the United States tilts toward Liquid. Powder dominates cross-border Canadian distribution.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and traceability demands.
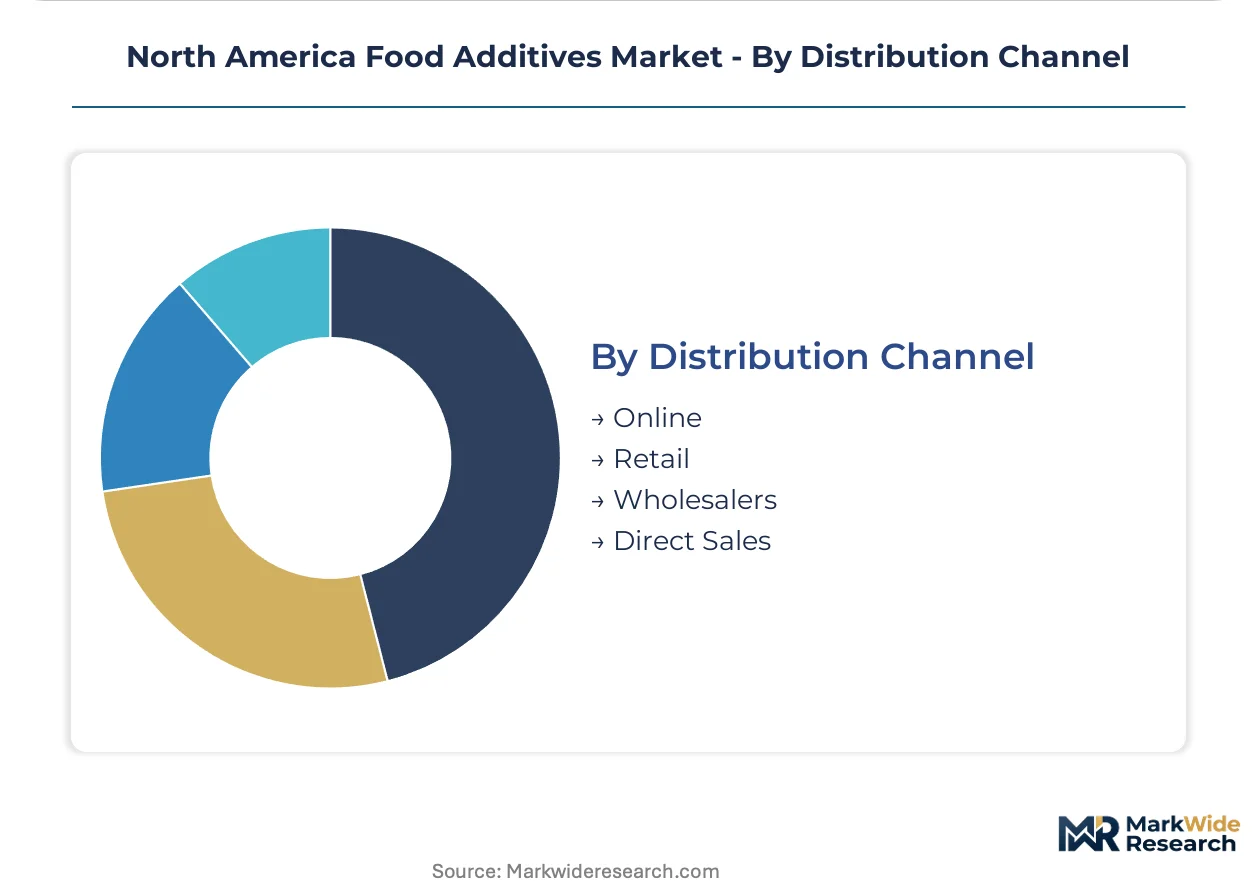
- Direct Sales:Integrated botanical sourcing and extraction capabilities enable additive suppliers to contract directly with large beverage and dairy manufacturers. California-based natural colorant procurement has shifted toward annual contracting with traceability guarantees, disintermediating regional distributors.
- Online:Digital procurement platforms compress lead times for mid-sized manufacturers seeking specialty emulsifiers and acidulants in spot quantities. Texas and Illinois processors utilize platform-enabled purchasing for formulation trial materials.
- Retail:Packaged additive sales serve small-scale food artisans and institutional kitchens through specialty ingredient suppliers.
- Wholesalers:Traditional distributor networks retain share in standard acidulant and preservative categories where technical service requirements are minimal.
Contract value concentrates in Direct Sales. Channel expansion is accelerating in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for food additives concentrates in the United States, where plant-based protein fortification and extended cold-chain distribution drive procurement volumes across beverage and dairy manufacturing clusters.
United States
Beverage co-manufacturers in California and Texas are accelerating direct procurement of natural colorants and acidulants, bypassing traditional distributor networks. FDA GRAS modernization is compressing approval timelines for rosemary-derived antioxidants and fermentation-cultured antimicrobials. Chicago and Minneapolis dairy processors are integrating tailored antimicrobial blends for refrigerated ready-to-eat segments requiring Listeria control across extended distribution.
Canada
Health Canada's Food and Drug Regulations govern novel food assessments for precision fermentation-derived ingredients, creating parallel compliance requirements with FDA pathways. Toronto and Montreal food manufacturers are importing botanical extracts under cross-border harmonization protocols for clean-label reformulation. British Columbia beverage startups are piloting adaptogenic additive integration for functional drink claims targeting millennial consumers.
Mexico
USMCA trade provisions facilitate additive ingredient flows into Mexican processed food manufacturing, particularly for emulsifiers and preservatives in confectionery and bakery segments. COFEPRIS regulatory alignment with FDA standards is accelerating GRAS-affirmed ingredient adoption in Mexico City and Guadalajara production facilities. Monterrey dairy processors are expanding cold-chain capacity, driving demand for antimicrobial systems compatible with extended shelf-life targets.
North America Food Additives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated botanical suppliers commanding premium positioning in clean-label antioxidant categories while fermentation-platform specialists capture emerging antimicrobial peptide demand. The vendor base organizes around three archetypes: agricultural conglomerates with captive extraction infrastructure, biotechnology firms scaling precision fermentation, and regional blenders serving refrigerated protein segments. Competitive moves concentrate on backward integration into botanical sourcing and strategic partnerships with beverage co-manufacturers seeking traceability guarantees.
Within the agricultural processing tier, Cargill Incorporated and Archer Daniels Midland Company exemplify integrated supply chain models spanning feedstock cultivation to finished extract production. Kerry Group PLC occupies a specialist position in tailored preservative blending for temperature-sensitive applications. These entities represent divergent strategic postures: conglomerate-scale raw material security versus formulation-specific technical service capabilities.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Kerry Group PLC |
| BASF SE |
| International Flavors & Fragrances Inc. |
| Novozymes A/S |
| DuPont |
| Others |
Value Network & Pricing Analysis
Rosemary extract commodity benchmarks cascade through North American additive supply chains, compressing margins for botanical antioxidant producers while concentrating pricing power with integrated suppliers controlling cultivation-to-extraction infrastructure. Cost pass-through mechanics stratify procurement tiers: large beverage co-manufacturers lock annual contracts with traceability premiums, mid-sized dairy processors absorb spot volatility, and small confectionery artisans face ingredient substitution pressures.
Pricing Analysis
High-volume preservatives trade on thin margins while specialty nutraceuticals and fermentation-derived antimicrobials capture premium pricing. Three-tier pricing structure separates FDA GRAS-certified botanical extracts from standard-grade synthetics and economy-tier commodity acidulants. Cost compression in synthetic benzoates is intensifying because of rosemary extract substitution mandates from major retailers. Small-scale bakery and artisan food producers exhibit highest price sensitivity; large beverage co-manufacturers with direct supplier relationships show lowest.
Supply Chain Analysis
Specialized fermentation technicians and extraction chemists concentrate in California, Illinois, and Minnesota manufacturing corridors, constraining scale-up velocity for precision fermentation platforms. Raw material flows draw from Moroccan rosemary cultivation regions, Midwestern corn feedstocks for fermentation substrates, and Canadian prairie pea protein isolates. Single-source vulnerability sits with concentrated botanical extract imports from Mediterranean suppliers. Distribution runs through direct supplier-manufacturer contracting with digital platform spot purchasing gaining share in specialty emulsifier categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American food additive economics function as a cost-of-compliance story where FDA GRAS modernization and Health Canada novel food assessments erect regulatory moats favoring capitalized incumbents with parallel toxicology study capabilities.
For Market Incumbents: Deepen backward integration into captive rosemary cultivation and fermentation feedstock production to neutralize botanical supply volatility. Expand technical service teams specializing in natural preservative synergy mapping to defend against biotechnology entrants scaling precision fermentation platforms. Prioritize dual-certification infrastructure for simultaneous FDA and Health Canada submissions. For New Entrants and Emerging Players: FDA precision fermentation guidance opens a window for antimicrobial peptide specialists to secure first-mover positioning in refrigerated ready-to-eat segments. Target white-space opportunities in adaptogenic beverage additives for millennial consumers in British Columbia and Pacific Northwest markets. Pursue direct-to-manufacturer digital procurement channels to bypass entrenched distributor relationships in specialty colorant categories. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized fermentation-platform specialists with validated GRAS pathways but constrained working capital in Illinois and Minnesota clusters. Long-term viability centers on regulatory submission capabilities rather than formulation chemistry alone. Watch FDA rulemaking finalization on precision fermentation-derived ingredients as inflection signal for antimicrobial peptide category acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Cultivation | Cargill's Moroccan rosemary sourcing secures supply continuity against climate volatility. |
| Precision Fermentation Scale-Up | ADM's antimicrobial peptide platforms reduce dependence on Mediterranean extract imports. |
| Direct-to-Manufacturer Digital Procurement | Kerry Group's platform bypasses distributor markups in Texas beverage co-manufacturing. |
| Dual-Jurisdiction Regulatory Certification | Parallel FDA-Health Canada submissions accelerate cross-border product launches. |
| Functional Beverage Additive Development | Adaptogenic integration targets stress-relief claims in British Columbia startup channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with formulation chemists, procurement directors at beverage co-manufacturers, regulatory affairs specialists, and plant managers at dairy processors provided operational validation. FDA GRAS notifications, Health Canada novel food assessments, USDA FSIS guidance documents, and industry association technical bulletins supplied structured secondary benchmarks. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Granularity-level modeling operated at product type, application, form, and distribution channel dimensions with geographic disaggregation to state and provincial clusters across the analysis window. CAGRs derived from trend extrapolation anchored in historical volume trajectories and elasticity-adjusted demand projections. Precision fermentation adoption curves and clean-label reformulation mandates served as category-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation scale-up would alter the outlook. Forecasts reflect assumptions regarding regulatory timeline adherence, botanical harvest stability, and cold-chain infrastructure expansion. Material deviation in FDA rulemaking finalization or rosemary crop yields warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Europe Food Coating Ingredients Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Food Grade Butyric Acid Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Middle East and Africa Food Starch Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
Distilled Monoglycerides Market
Food Additives and Ingredients
Lipase Food Enzymes Market