
 Food Antifoaming Agents Market | 2026-2036
Food Antifoaming Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Food Antifoaming Agents Market Analysis
Silicone polymer synthesis is fragmenting into multiple process pathways, altering how antifoam active ingredients reach food-grade specification. Dow Inc. leverages captive silicone intermediate production to secure raw material continuity across beverage and dairy accounts. BASF SE anchors its position through backward integration into fatty alcohol feedstocks, while Evonik Industries AG specializes in organomodified siloxane architectures for high-temperature frying applications.
Food antifoaming agents are surface-active formulations, typically comprising hydrophobic silica dispersed in polydimethylsiloxane or esterified fatty acids, designed to destabilize foam lamellae in aqueous food systems by reducing surface tension at the liquid-air interface. Silicone-based products dominate volume due to their thermal stability above 150°C and low dosage rates in deep-fat frying, whereas lactic acid esters represent the fastest-expanding category as clean-label dairy processors reject synthetic additives. Liquid formulations capture the largest share of form demand, though powder antifoams are gaining traction in instant dry-mix applications where water activity constraints complicate emulsion stability.
The FDA maintains food-contact substance notification requirements under 21 CFR 173.340 for silicone defoaming agents, while EFSA evaluates ester-based alternatives under the EU Food Improvement Agent Package. China's SAMR enforces GB standards for food additive purity that directly affect import eligibility for multinational suppliers. Stakeholders must monitor evolving maximum residue limits for process aids, as regulatory divergence between major jurisdictions threatens to partition formulation portfolios and complicate global manufacturing footprints.
Market Dynamics
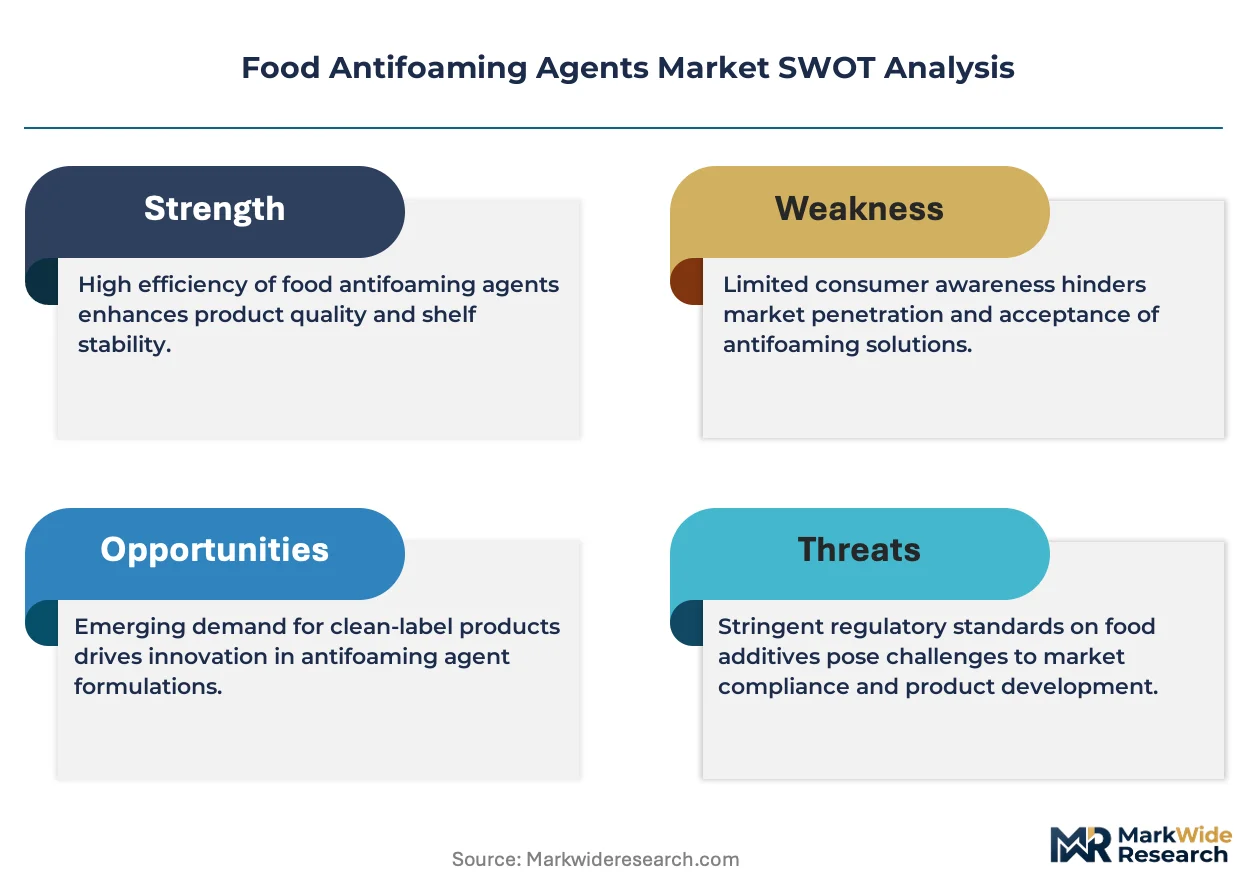
Silicone polymer feedstock concentration among three major chemical conglomerates is constraining formulation flexibility for mid-tier antifoam blenders serving dairy and beverage processors.
Growth Catalysts
- EU F-Gas Regulation:Tightening purity mandates for fluorinated process gases are accelerating silicone-based antifoam substitution in carbonated beverage filling lines across German and Italian bottling clusters.
- Clean-label dairy processing:Lactic acid ester formulations are displacing synthetic antifoams in yogurt and cheese production as processors pursue EFSA-compliant natural positioning for export markets.
- Deep-fat frying automation:Thermal stability requirements above 150°C in continuous frying systems are pulling organomodified siloxane architectures into snack food manufacturing.
Market Restraints
- Silicone intermediate concentration:Captive production of polydimethylsiloxane by Dow Inc., Wacker Chemie, and Elkem ASA limits third-party blender access to food-grade silicone oils.
- Fatty alcohol volatility:Palm kernel and coconut oil feedstock price swings directly compress margin structures for ester-based antifoam producers.
- REACH registration costs:ECHA substance evaluation fees for novel organomodified siloxanes deter mid-cap entrants from launching differentiated products.
Strategic Opportunities
- Instant dry-mix channel expansion:Powder antifoam formats are penetrating soup and sauce premix applications where water activity constraints previously excluded liquid emulsions.
- Plant-based beverage processing:Oat and almond milk foaming challenges are creating specification windows for lipid-silicone hybrid antifoams in Swedish and Danish dairy alternatives.
- China GB standard alignment:SAMR food additive purity certifications for imported silicone defoamers are opening procurement pathways for European blenders in Shanghai and Guangzhou beverage clusters.
Industry Challenges
- Food-contact substance notification timelines:FDA 21 CFR 173.340 review cycles for novel silicone defoamers extend 18-24 months, delaying product launches.
- Formulation-scale transfer complexity:Bench-scale organomodified siloxane prototypes fail to replicate performance in industrial 10,000-liter dairy processing tanks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Antifoaming Agents Market |
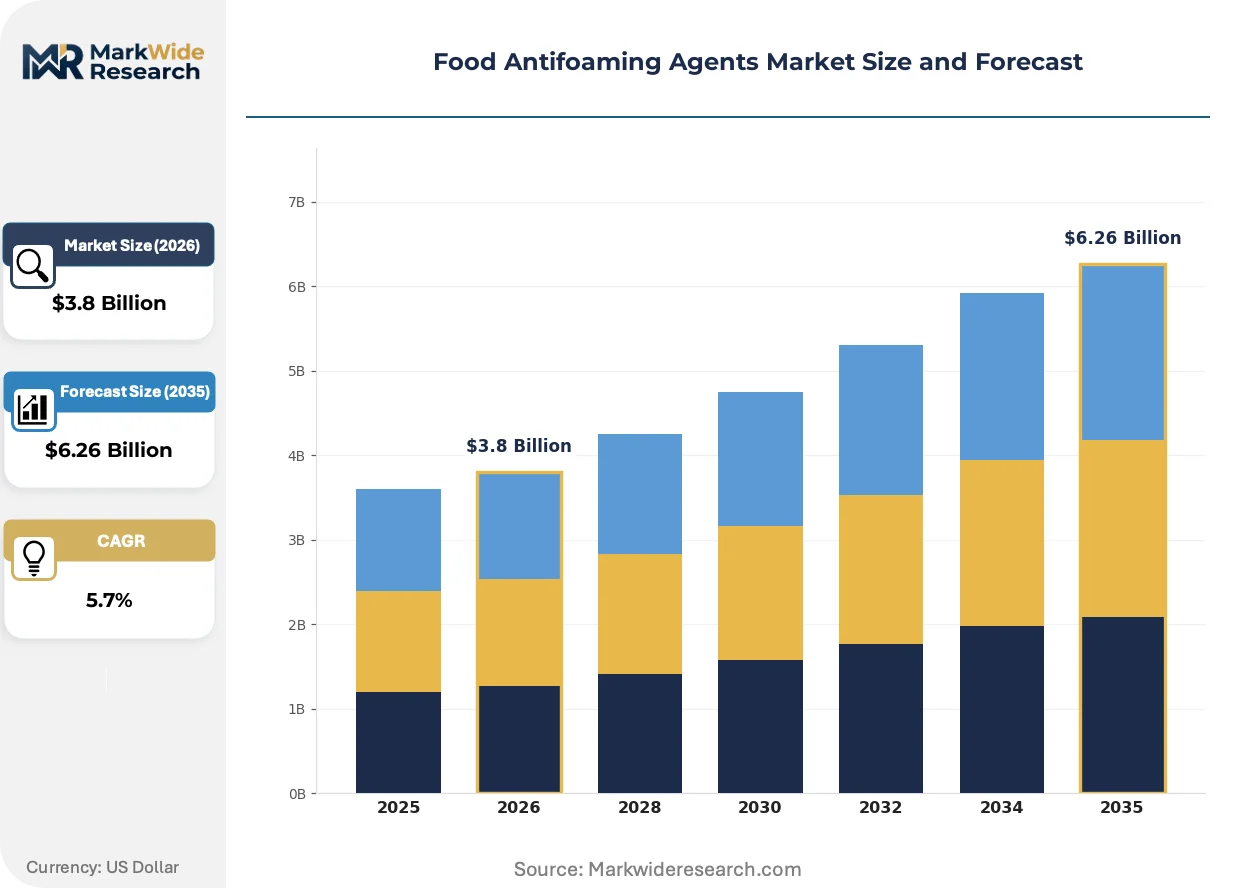
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
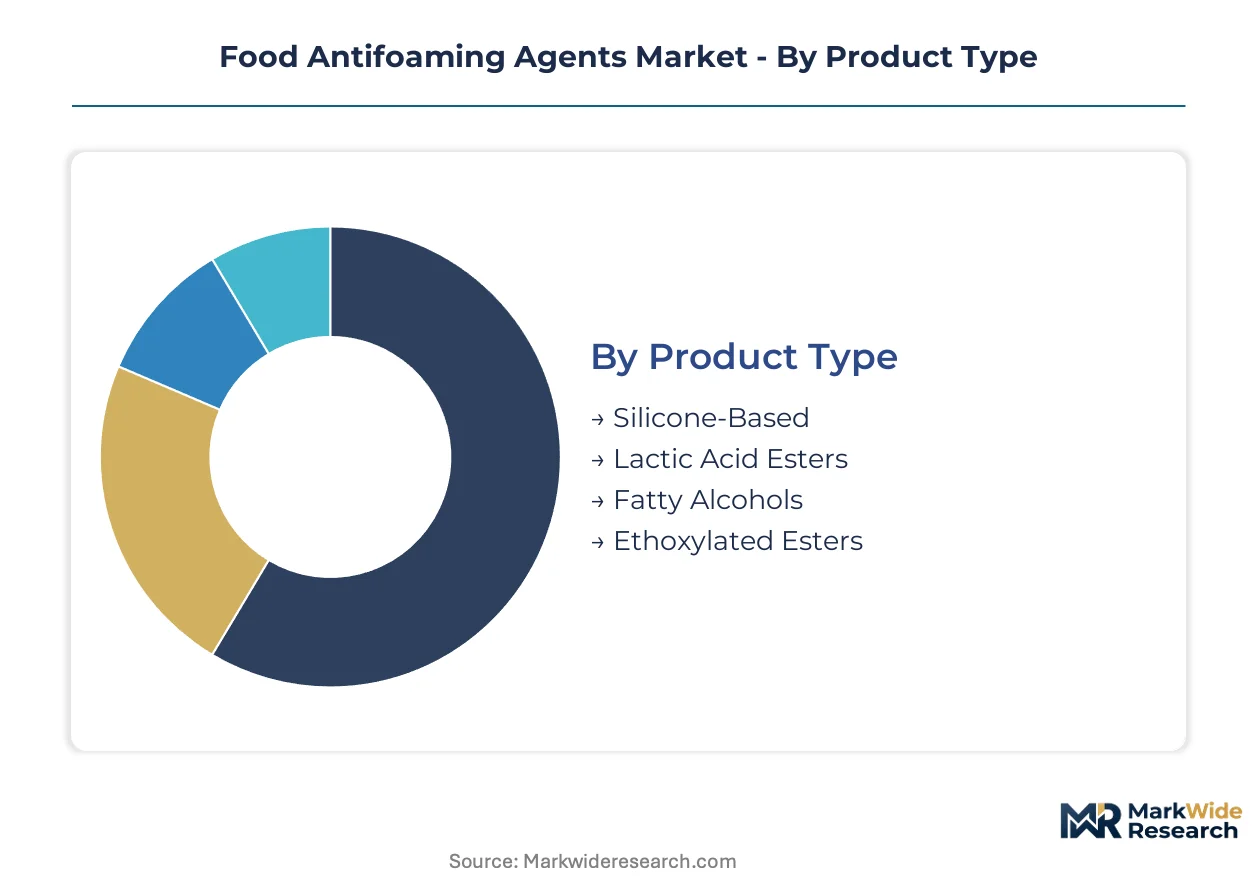
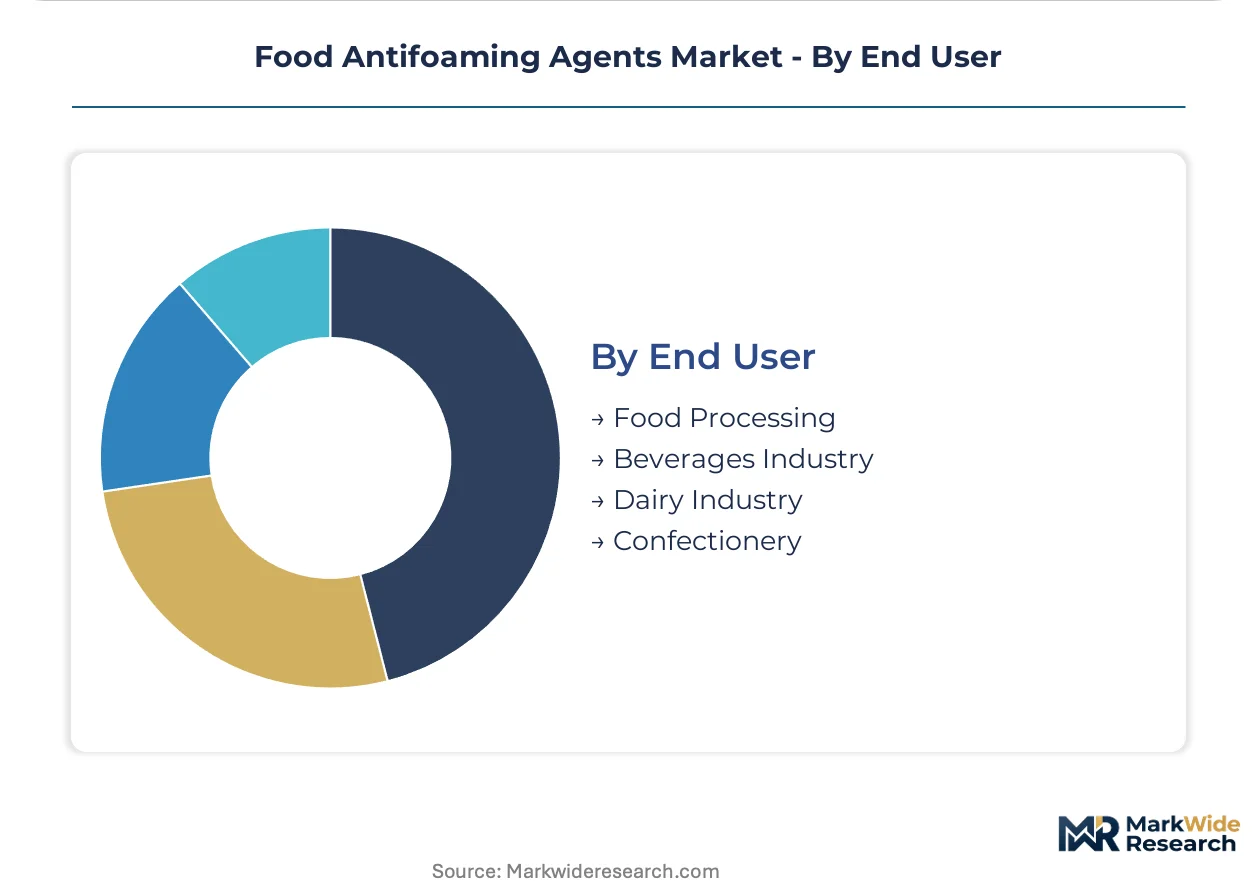
| Segmentation | Product Type: Silicone-Based, Lactic Acid Esters, Fatty Alcohols, Ethoxylated Esters Application: Beverages, Bakery, Dairy, Oil & Fats Form: Liquid, Powder, Emulsion, Granules End User: Food Processing, Beverages Industry, Dairy Industry, Confectionery |
| Companies Covered | Dow Inc., Ecolab Inc., BASF SE, Clariant AG, Elementis Plc, Evonik Industries AG, Ashland LLC, Kemira Oyj, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Antifoaming Agents Market Emerging Trajectories
Antifoam chemistry is bifurcating along thermal performance and clean-label axes, with silicone architectures defending high-temperature frying positions while ester formulations capture dairy and beverage share through natural positioning.
Microencapsulated powder antifoams with controlled-release silica shells are rendering obsolete conventional spray-dried emulsions in instant dry-mix applications. Soup and sauce manufacturers in the Netherlands and Belgium are adopting these formats to eliminate premix clumping. The technology is compressing liquid antifoam volume share in ambient-stable food categories.
EFSA's Food Improvement Agent Package is tightening maximum residue limits for process aids in dairy applications. The framework is forcing reformulation of legacy polydimethylsiloxane blends toward lower-viscosity variants that leave reduced surface films. French and German cheese processors are accelerating validation of lactic acid ester alternatives to preempt compliance gaps.
Direct procurement contracts between dairy cooperatives and antifoam blenders are displacing traditional distributor networks in Northern European markets. Arla Foods and FrieslandCampina are negotiating volume commitments with silicone and ester suppliers for three-year terms. The shift is most visible in Denmark and the Netherlands, where processor consolidation enables procurement leverage.
Food Antifoaming Agents Market Segmentation
Antifoam specification varies sharply across food processing environments, with thermal stress, pH conditions, and label positioning requirements driving formulation selection. Procurement patterns cluster around application-specific performance thresholds rather than commodity purchasing.
Product Type:
After-sales service intensity runs highest for silicone-based formulations, where technical field support for dosing equipment calibration and foam-control troubleshooting commands premium pricing.
- Silicone-Based:Hydrophobic silica dispersed in polydimethylsiloxane delivers thermal stability above 150°C. German deep-fat frying operations and Italian snack manufacturers specify these for continuous production lines where downtime costs exceed formulation premiums.
- Lactic Acid Esters:Esterified fatty acids from renewable feedstocks meet EFSA clean-label thresholds. French and Dutch dairy processors validate these for yogurt and cheese exports to markets with strict natural-positioning requirements.
- Fatty Alcohols:C8-C18 alcohol blends serve cost-sensitive beverage applications where moderate thermal exposure permits simpler chemistry.
- Ethoxylated Esters:Polyoxyethylene derivatives balance hydrophilic-lipophilic properties for emulsion stability in neutral-pH food systems.
Silicone-Based holds the largest share; momentum sits with Lactic Acid Esters.
Application:
Cost tier differentiation separates premium thermal-stable formulations from standard-grade options across processing categories.
- Beverages:Carbonated drink filling lines in German and Italian bottling clusters deploy silicone defoamers to prevent overflow during high-speed canning. EU F-Gas Regulation compliance accelerates substitution away from fluorinated process aids.
- Dairy:EFSA's tightening maximum residue limits for process aids force reformulation toward lower-viscosity variants. French cheese processors accelerate lactic acid ester validation to preempt compliance gaps.
- Bakery:Whipped topping and aerated batter production requires precise foam control without compromising final product texture.
- Oil & Fats:Continuous frying systems in Belgian and Dutch snack manufacturing pull organomodified siloxanes for thermal stability above 150°C.
Beverages commands the largest volume commitment; Dairy climbs the fastest on clean-label substitution.
Form:
Application environment dictates physical state selection, with water activity and storage stability as primary constraints.
- Liquid:Pumpable emulsions dominate installed dosing infrastructure across beverage and dairy processing lines. Dow Inc. and Wacker Chemie supply concentrated silicone oils for dilution at point of use.
- Powder:Microencapsulated formats with controlled-release silica shells penetrate soup and sauce premix applications in the Netherlands and Belgium. Ambient-stable categories are compressing liquid volume share.
- Emulsion:Pre-diluted aqueous dispersions simplify handling for smaller processors lacking blending equipment.
- Granules:Free-flowing solid carriers suit dry-mix applications where dust control and precise metering matter.
Liquid holds the largest share; Powder gains share fastest on instant dry-mix channel expansion.
End User:
Customer type determines procurement leverage, with consolidated cooperatives extracting volume terms unavailable to fragmented processors.
- Food Processing:Integrated snack manufacturers in Germany and Belgium specify thermal-stable silicone architectures for continuous frying automation.
- Dairy Industry:Arla Foods and FrieslandCampina negotiate three-year direct contracts with antifoam suppliers. Danish and Dutch processor consolidation enables procurement leverage absent in fragmented southern European markets.
- Beverages Industry:Carbonated bottling clusters in Germany and Italy concentrate demand for high-purity silicone defoamers meeting FDA 21 CFR 173.340 and REACH compliance simultaneously.
- Confectionery:Aerated candy and chocolate production requires precise foam control during mixing and tempering phases.
Food Processing holds the largest share; momentum sits with Dairy Industry on clean-label positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German silicone antifoam exports flow primarily into Italian beverage bottling corridors and French dairy processing networks, establishing a north-south trade corridor that concentrates formulation procurement decisions in Northern European chemical conglomerates.
Germany
Dairy processing clusters in Bavaria and Lower Saxony drive concentrated procurement of lactic acid ester formulations for yogurt and cheese exports. The EU F-Gas Regulation tightens purity mandates for food-contact chemicals, forcing reformulation of legacy silicone blends. Munich-based beverage equipment manufacturers specify high-purity silicone defoamers for carbonated drink filling lines serving export markets.
Italy
Carbonated beverage production in the Po Valley bottling corridor demands silicone-based antifoams for high-speed canning operations. REACH compliance frameworks govern import eligibility for multinational suppliers entering Italian procurement channels. Turin and Milan processing clusters are accelerating substitution away from fluorinated process aids under EU environmental directives.
France
Cheese processors in Normandy and the Rhône-Alpes region validate lactic acid ester alternatives to preempt EFSA maximum residue limit compliance gaps. The country's national food safety regulator enforces process aid thresholds that favor clean-label positioning for export-oriented dairies. Lille and Lyon antifoam blenders negotiate direct procurement contracts with cooperative processors.
Netherlands
Snack food manufacturers in the Rotterdam port cluster specify organomodified siloxane architectures for continuous frying systems requiring thermal stability above 150°C. ECHA substance evaluation fees for novel silicone derivatives deter mid-cap entrants from launching differentiated products. Amsterdam-based dairy alternatives processors create specification windows for lipid-silicone hybrid antifoams in oat and almond milk production.
China
Shanghai and Guangzhou beverage clusters open procurement pathways for European antifoam blenders meeting SAMR food additive purity certifications under GB standards. The country's national market regulator enforces import eligibility criteria that directly affect multinational supplier access. Pearl River Delta dairy processors are expanding silicone-based antifoam use in automated production lines.
Food Antifoaming Agents Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Captive silicone intermediate production defines the upper tier, while mid-cap blenders struggle with feedstock access constraints. Strategic archetypes include integrated chemical conglomerates with backward control over polymer feedstocks, specialty formulators focused on organomodified architectures, and regional blenders serving single-application verticals. Dominant competitive moves center on direct procurement contract capture with consolidated dairy cooperatives and technology licensing for powder microencapsulation formats.
Within the integrated chemical tier, Dow Inc., BASF SE, and Evonik Industries AG occupy positions that exemplify divergent strategic postures. Dow represents captive supply chain control through in-house silicone intermediate production. BASF anchors the fatty alcohol feedstock vector with upstream integration into renewable ester chemistry. Evonik sits within the high-performance specialization archetype, with organomodified siloxane expertise serving thermal-stress applications. These three entities collectively illustrate how raw material access, regulatory navigation capability, and application-specific formulation knowledge separate sustainable competitive positions from commodity blending operations.
| Leading Market Players |
|---|
| Dow Inc. |
| Ecolab Inc. |
| BASF SE |
| Clariant AG |
| Elementis Plc |
| Evonik Industries AG |
| Ashland LLC |
| Kemira Oyj |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
The Ruhr industrial corridor's silicone intermediate capacity directly shapes downstream pricing power for beverage and dairy antifoam blenders across Northern Europe. German chemical conglomerates leverage captive polydimethylsiloxane production to command premium positioning in thermal-stable formulations, while mid-tier blenders face margin compression from feedstock access constraints.
Pricing Analysis
Next-generation organomodified siloxane architectures command substantial premiums over standard polydimethylsiloxane emulsions and legacy fatty alcohol formulations. Three-tier pricing structure across premium, standard, and economy levels separates thermal performance grades, with EFSA-compliant clean-label certifications and REACH registration status as primary price differentiation drivers. Cost compression in standard-grade silicone emulsions is intensifying because of captive supply concentration among Dow Inc., Wacker Chemie, and Elkem ASA. Small-scale dairy processors in Southern Europe exhibit highest price sensitivity, while integrated snack manufacturers in Belgium and the Netherlands prioritize thermal stability over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for antifoam blenders sourcing hydrophobic silica feedstocks. Manufacturing concentrates in Germany, China, and the United States, with the Ruhr Valley, Pearl River Delta, and Gulf Coast petrochemical clusters anchoring global silicone intermediate output. Raw material flows draw from palm kernel and coconut oil plantations in Southeast Asia, petroleum-derived siloxane precursors in North America, and precipitated silica operations in China. Single-source vulnerability in food-grade silicone oil supply constrains formulation flexibility for independent blenders. Distribution runs through direct procurement contracts with consolidated dairy cooperatives in Denmark and the Netherlands, displacing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical field support for dosing equipment calibration and foam-control troubleshooting represents a service-attach layer expanding faster than base formulation sales, as dairy and beverage processors prioritize uptime guarantees over commodity purchasing.
For Market Incumbents: Entrench market position through backward integration into fatty alcohol feedstocks and certification investment for EFSA's evolving Food Improvement Agent Package compliance. Captive silicone intermediate production and three-year direct procurement contracts with Arla Foods and FrieslandCampina defend against emerging ester-based substitutes. Capacity addition in Bavaria and Lower Saxony dairy clusters reinforces geographic proximity to specification-setting processors. For New Entrants and Emerging Players: Powder antifoam formats in instant dry-mix soup and sauce applications represent the most penetrable entry point, as water activity constraints exclude established liquid emulsion suppliers from ambient-stable categories. Plant-based beverage processing in Swedish and Danish oat and almond milk operations offers specification windows for lipid-silicone hybrid formulations underserved by incumbent dairy-focused portfolios. SAMR GB standard alignment for China import eligibility provides a regulatory arbitrage go-to-market angle for European blenders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty formulators with organomodified siloxane expertise serving thermal-stress frying applications, as clean-label substitution pressures commoditized silicone emulsions. Long-term viability hinges on dual-track capability spanning both high-temperature silicone architectures and EFSA-compliant ester alternatives. Acquisition targets should demonstrate validated scale-up from bench to industrial 10,000-liter dairy tanks. The signal to watch is FDA 21 CFR 173.340 notification timeline compression for novel silicone defoamers, indicating regulatory pathway efficiency as competitive moat.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Feedstocks | BASF SE's upstream control over renewable ester chemistry secures margin stability against palm kernel oil volatility. |
| Long-term Supply Agreement with Dairy Cooperatives | Direct procurement contracts with FrieslandCampina displace distributor networks and lock in volume commitments. |
| Joint Venture for China GB Standard Alignment | European-Chinese partnerships accelerate SAMR certification pathways for Shanghai and Guangzhou beverage clusters. |
| Capacity Expansion in Powder Microencapsulation | Microencapsulated formats with controlled-release silica shells penetrate Netherlands and Belgium soup premix markets. |
| Green Manufacturing Transition for Clean-Label Positioning | Lactic acid ester formulations from renewable feedstocks capture EFSA-compliant dairy export demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy processing engineers, beverage plant managers, antifoam formulation chemists, and procurement leads at integrated snack manufacturers. Secondary validation drew from EFSA Food Improvement Agent Package documentation, FDA 21 CFR 173.340 filings, SAMR GB standard publications, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up segment sizing across silicone-based, lactic acid ester, and fatty alcohol product types was triangulated against top-down market value estimates.
Calibration against historical volume trajectories in German dairy processing and Italian beverage bottling anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry, application environment, physical form, and end-user procurement scale. CAGRs were derived from fitted growth curves incorporating EFSA regulatory timeline assumptions and clean-label substitution elasticity parameters. Forecast inputs included EU F-Gas Regulation compliance cost curves and SAMR import certification velocity for European suppliers.
Macroeconomic conditions sit as an overlay; deviation in palm kernel oil feedstock pricing, euro-yuan exchange rates, or ECHA substance evaluation fee schedules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timing and processor consolidation patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Lipase Food Enzymes Market
Food Additives and Ingredients
Wine Fining Agent Market