
 United States Nematicides Market | 2026-2036
United States Nematicides Market Size, Share, and Industry Trends Forecast 2026-2036
United States Nematicides Market Outlook
Biological efficacy standards for nematode suppression is collapsing the performance gap between conventional fumigants and microbials. Corteva Agriscience leverages its germplasm-nematicide bundling strategy to lock in row-corn acreage across the Corn Belt. FMC Corporation anchors its position through proprietary fluency chemistry that sustains residual activity in high-organic-matter soils. Syngenta competes with integrated seed treatment portfolios that extend nematicide delivery directly at planting.
Nematicides are crop protection agents specifically formulated to kill or suppress plant-parasitic nematodes, typically delivered as soil-incorporated fumigants, non-fumigant organophosphates, carbamates, or microbial preparations containing Pasteuria penetrans, Bacillus firmus, or Purpureocillium lilacinum spores. These compounds function by disrupting nematode chemoreception, inhibiting acetylcholinesterase enzyme activity, or colonizing nematode eggs and juveniles to prevent root penetration and gall formation. Biological formulations lead growth trajectories as farmer cooperatives in the Southeast and Pacific states adopt microbial inoculants with shorter re-entry intervals and favorable residue profiles. Granular and liquid delivery systems dominate commercial application, though emulsifiable concentrates capture expanding greenhouse and nursery segments where precision dosing equipment supports integrated pest management protocols.
EPA Office of Pesticide Programs registration requirements under FIFRA govern nematicide efficacy claims and ecological toxicity thresholds, while USDA NRCS conservation practice standards influence cost-share eligibility for reduced-risk pest management transitions. State-level Departments of Agriculture in California, Florida, and Georgia impose additional buffer zone mandates and groundwater monitoring for soil fumigants that restrict product mobility and shape distributor inventory decisions. Stakeholders must monitor evolving EPA endangered species assessments and state 24(c) special local need registrations that could abruptly alter product availability in high-value vegetable counties.
Market Dynamics
EPA ecological risk assessments for soil fumigants are compressing application windows and accelerating farmer migration toward microbial alternatives across California and Florida specialty crop zones.
Growth Catalysts
- Biological Registration Streamlining:EPA Office of Pesticide Programs has accelerated FIFRA registration timelines for biorational nematicides containing Pasteuria penetrans and Bacillus firmus.
- Root-Knot Nematode Pressure:Southeastern vegetable belt growers face recurring Meloidogyne infestations that mandate multi-season suppression programs.
- Conservation Cost-Share Programs:USDA NRCS conservation practice standards provide financial incentives for reduced-risk pest management transitions in high-value vegetable counties.
Market Restraints
- Fumigant Buffer Zone Mandates:California Department of Pesticide Regulation and Florida Department of Agriculture impose expanding setback requirements that restrict product mobility.
- High-Organic-Matter Soil Variability:Residual activity of carbamate and organophosphate chemistries degrades unpredictably in muck soils of the Everglades agricultural area.
- Groundwater Monitoring Costs:State-level 24(c) special local need registrations require continuous aquifer testing that elevates distributor compliance overhead.
Strategic Opportunities
- Greenhouse and Nursery Segments:Precision dosing equipment supports integrated pest management protocols in controlled-environment agriculture across the Pacific states.
- Seed Treatment Integration:Direct nematicide delivery at planting opens acreage in Corn Belt row-corn systems where soil-incorporated fumigants face labor constraints.
- Microbial Inoculant Formulations:Shorter re-entry intervals and favorable residue profiles attract cooperative adoption in Georgia and South Carolina vegetable operations.
Industry Challenges
- Biological Efficacy Validation:Field trial standardization for microbial nematicides lacks consensus protocols between university extension services and registrants.
- Application Equipment Retrofit:Existing fumigant injection rigs require modification for liquid biological delivery, demanding capital outlay from custom applicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Nematicides Market |
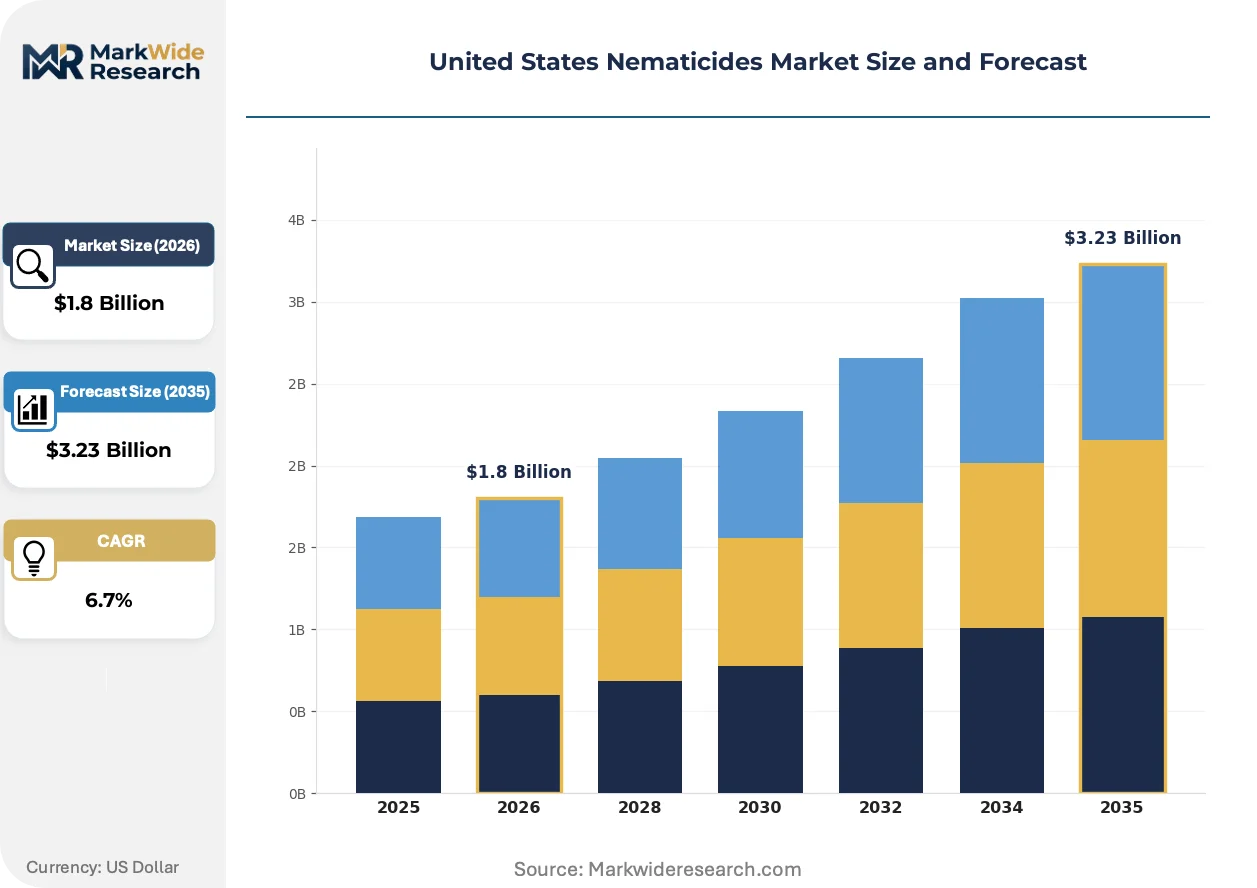
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inorganic, Organic, Biological, Synthetic Application: Agricultural Fields, Greenhouses, Nurseries, Turf Management Formulation: Granular, Liquid, Emulsifiable Concentrates, Soluble Powder End User: Farmers, Agricultural Cooperatives, Landscapers, Research Institutions |
| Companies Covered | Corteva Agriscience, FMC Corporation, Syngenta, Nufarm, American Vanguard Corporation, Bayer AG, ADAMA Agricultural Solutions, BioWorks, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Nematicides Market Strategic Shifts
Microbial fermentation platforms and precision application hardware are collapsing the performance gap between conventional chemistries and biological alternatives.
Spore-based formulations containing Purpureocillium lilacinum deliver egg-parasitic colonization that matches fumigant suppression levels in field trials. Specialty crop growers in California's Central Valley and Florida's Immokalee region are expanding microbial inoculant programs at double-digit adoption rates. Granular delivery systems is supplanting soil injection methods where buffer restrictions and labor shortages constrain fumigant deployment.
EPA revised endangered species assessments under FIFRA Section 7 consultation are triggering additional use restrictions for organophosphate nematicides in watersheds hosting salmonid populations. Industrial consequence includes forced product withdrawals from Pacific Northwest potato counties and accelerated label amendments. Vegetable growers in affected drainages are responding by pre-purchasing biological alternatives ahead of anticipated regulatory effective dates.
Cooperative procurement through farmer-owned supply entities is consolidating input purchasing power in the Southeast. Traditional distributor networks face margin compression as grower cooperatives in Georgia and the Carolinas negotiate direct manufacturer contracts for microbial nematicide volumes. This channel shift concentrates most visibly in cucurbit and solanaceous vegetable operations where application frequency creates annual contract leverage.
United States Nematicides Market Segmentation
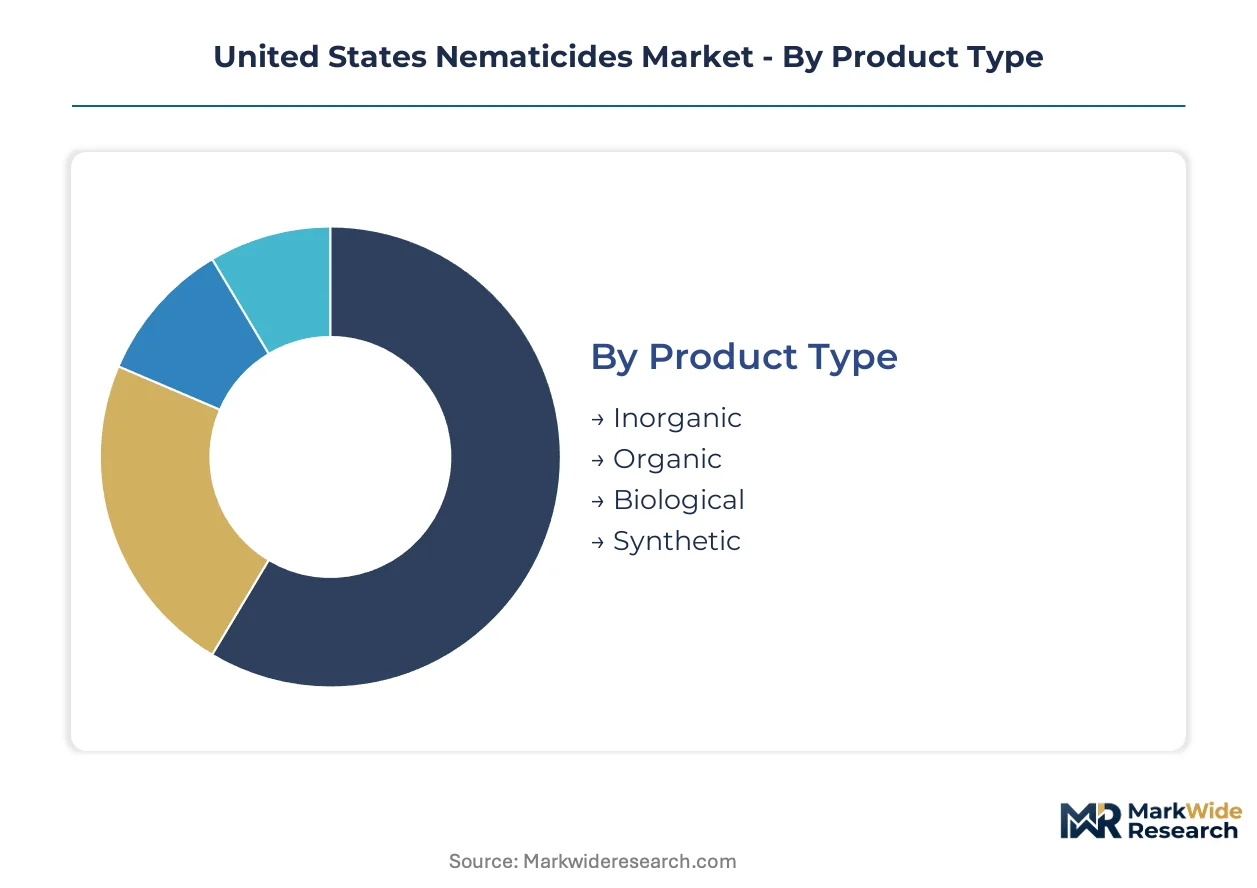
EPA registration pathways and state-level buffer mandates fragment nematicide demand across distinct product categories, application settings, and user capabilities. Segmentation reveals where biological alternatives displace fumigants and which delivery systems match labor constraints in high-value vegetable counties.
Product Type:
EPA ecological risk assessments and FIFRA registration timelines create divergent compliance burdens across chemistry classes, steering commercial investment toward lower-toxicity categories.
- Biological:Microbial preparations containing Purpureocillium lilacinum or Bacillus firmus colonize nematode eggs through enzymatic degradation. Demand concentrates in Florida's Immokalee vegetable belt and California's Central Valley, where EPA streamlining of biorational registrations accelerates cooperative procurement programs.
- Synthetic:Organophosphate and carbamate chemistries inhibit acetylcholinesterase enzyme activity in nematode nervous systems. California Department of Pesticide Regulation buffer zone mandates compress application windows in strawberry and pepper counties, forcing inventory drawdowns ahead of anticipated use restrictions.
- Inorganic:Metal-based formulations deliver contact toxicity through soil incorporation. USDA NRCS cost-share eligibility rarely extends to these older chemistries.
- Organic:Botanical extracts and plant-derived compounds function through nematode chemoreception disruption. Limited residual activity restricts adoption to organic-certified operations in Pacific states.
Biological handles the majority of throughput; Synthetic is the fastest mover on share as growers pre-purchase ahead of regulatory withdrawals.
Application:
Labor availability and buffer geometry determine whether soil-incorporated or precision-dosed delivery captures acreage in each production system.
- Agricultural Fields:Large-scale row-crop and specialty vegetable operations deploy granular broadcast or chemigation delivery across thousands of acres. The southeastern vegetable belt dominates volume, where root-knot nematode pressure in Georgia and South Carolina mandates multi-season suppression cycles.
- Greenhouses:Controlled-environment agriculture in Pacific states employs drip irrigation integration and fogging systems for precision dosing. Shorter re-entry intervals for biological formulations align with intensive harvest schedules in California's coastal nurseries.
- Nurseries:Containerized production systems require root-zone saturation without phytotoxicity to young stock. Oregon and Washington ornamental operations favor liquid drenches compatible with existing irrigation infrastructure.
- Turf Management:Golf course and athletic field maintenance programs prioritize cosmetic thresholds over yield protection. Florida's municipal contracts drive seasonal demand for fast-acting contact chemistries.
Agricultural Fields absorb the greatest product volume; Greenhouses are expanding most quickly as controlled-environment acreage proliferates.
Formulation:
Equipment capital requirements and soil organic matter variability dictate which physical form factors penetrate each customer tier.
- Liquid:Emulsifiable and suspension concentrates enable chemigation and foliar delivery with minimal equipment modification. High-organic-matter muck soils in Florida's Everglades agricultural area degrade residual activity unpredictably, forcing more frequent liquid reapplications.
- Granular:Clay-based carriers impregnated with active ingredients release through soil moisture activation. Corn Belt row-corn systems favor this format for at-planting integration with seeding equipment, avoiding separate fumigant injection passes.
- Emulsifiable Concentrates:Oil-in-water formulations support precision dosing through greenhouse injection pumps and nursery drip systems. Pacific states' controlled-environment segments specify this grade for compatibility with integrated pest management protocols.
- Soluble Powder:Dry formulations reconstitute for spray tank mixing in smaller-scale operations. Research institutions and cooperative demonstration plots prefer this flexibility for trial replication.
Liquid formulations command the largest installed base; Granular is climbing the fastest as Corn Belt labor constraints intensify.
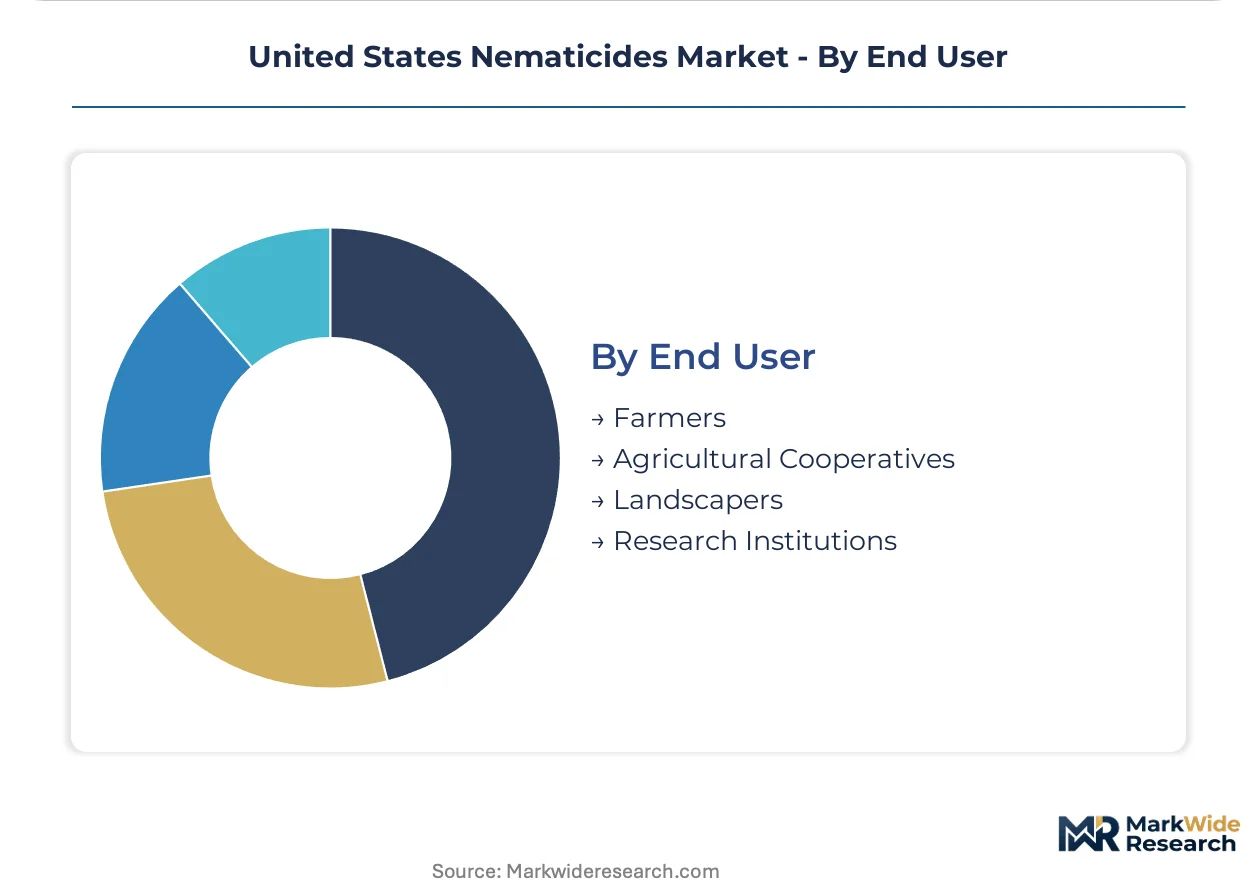
End User:
Purchasing scale and technical sophistication determine whether direct manufacturer relationships or distributor intermediaries dominate channel economics.
- Farmers:Individual growers managing fewer than 500 acres rely on retail agronomy services for product selection and application timing. California's high-value vegetable counties see the highest per-acre nematicide expenditure as growers self-apply to preserve crop insurance eligibility.
- Agricultural Cooperatives:Farmer-owned supply entities in Georgia and the Carolinas consolidate procurement volumes for direct manufacturer negotiation. Cooperative adoption of microbial inoculants proceeds at double-digit rates where annual contract leverage meets shorter re-entry interval requirements.
- Landscapers:Commercial turf maintenance contractors prioritize rapid knockdown and minimal irrigation dependence. Florida municipal bidding cycles concentrate seasonal demand.
- Research Institutions:University extension services and USDA ARS stations conduct field efficacy trials that influence label expansion. Standardized protocols between registrants and land-grant universities remain unresolved for biological product validation.
Agricultural Cooperatives move the greatest product tonnage; Research Institutions are gaining procurement priority as biological registration pipelines thicken.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States nematicides market exhibits minimal import dependence, with domestic formulation capacity serving specialty crop zones from California to Florida. Export activity remains limited to technical-grade active ingredients shipped to Latin American contract manufacturers.
California
Root-knot nematode pressure in strawberry and pepper counties drives per-acre expenditure rates exceeding national averages. California Department of Pesticide Regulation buffer zone mandates compress application windows for soil fumigants in Monterey and Ventura counties. Central Valley vegetable cooperatives are pre-purchasing microbial inoculants ahead of anticipated regulatory withdrawals.
Florida
Recurring Meloidogyne infestations in the Immokalee vegetable belt mandate multi-season suppression programs with shortened re-entry intervals. Florida Department of Agriculture imposes expanding setback requirements that restrict product mobility in muck soils. Everglades agricultural area growers face unpredictable residual activity degradation, forcing more frequent liquid reapplications.
Georgia
The southeastern vegetable belt concentrates demand for granular broadcast delivery compatible with reduced labor availability. USDA NRCS conservation practice standards provide cost-share eligibility for biological transitions in high-value cucurbit counties. Farmer-owned supply entities in the Carolinas negotiate direct manufacturer contracts for microbial nematicide volumes.
Pacific Northwest
EPA endangered species assessments under FIFRA Section 7 consultation trigger use restrictions for organophosphate nematicides in salmonid watersheds. Washington and Oregon potato counties face forced product withdrawals, accelerating label amendments. Vegetable growers in affected drainages stockpile biological alternatives ahead of regulatory effective dates.
Corn Belt
Row-corn systems favor at-planting granular integration with seeding equipment, avoiding separate fumigant injection passes. Corteva's germplasm-nematicide bundling strategy locks in acreage across Illinois and Iowa. Labor constraints intensify adoption of seed treatment delivery methods over soil-incorporated chemistries.
United States Nematicides Market Competitive Environment
Concentration sits with integrated agricultural science conglomerates possessing germplasm access and distribution infrastructure. The vendor base spans three distinct tiers: multinational crop protection majors with seed treatment portfolios, mid-cap specialists in biological fermentation, and regional distributors serving cooperative procurement channels. Strategic moves center on EPA registration pipeline positioning for biorational products and backward integration into microbial fermentation capacity.
Within the multinational tier, Corteva Agriscience, FMC Corporation, and Syngenta exemplify divergent competitive positioning. Corteva leverages bundling strategies across the Corn Belt. FMC anchors through proprietary chemistry sustaining residual activity. Syngenta competes with integrated seed treatment portfolios extending nematicide delivery at planting.
| Leading Market Players |
|---|
| Corteva Agriscience |
| FMC Corporation |
| Syngenta |
| Nufarm |
| American Vanguard Corporation |
| Bayer AG |
| ADAMA Agricultural Solutions |
| BioWorks |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day EPA registration review cycles for biorational nematicides compress inventory planning horizons while concentrating pricing power with domestic fermentation facilities holding active FIFRA approvals. This lead-time compression rewards manufacturers with backward-integrated microbial production capacity, as agricultural cooperatives pre-purchase biological volumes ahead of anticipated synthetic withdrawals.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Corn Belt row-corn systems, where Corteva's germplasm-nematicide bundling extracts premium positioning. Price differentiation separates EPA-registered biological formulations from pending-registration alternatives through certification tier and residual activity guarantees. Pricing pressure stems from cooperative procurement consolidation in Georgia and the Carolinas, where direct manufacturer negotiation compresses distributor margins. Small-scale vegetable growers in California's high-value counties exhibit highest price sensitivity due to per-acre expenditure volatility, while agricultural cooperatives leverage volume scale for least-sensitive procurement.
Supply Chain Analysis
EPA registration backlog clearance at the Office of Pesticide Programs constitutes the critical chokepoint determining product availability windows across the southeastern vegetable belt. Geographic supply concentration draws from domestic fermentation facilities in Iowa and Minnesota for microbial active ingredients, with specialty formulation capacity clustering in California and Florida. Raw material dependencies center on agricultural substrate feedstocks, spore culture media, and clay-based granular carriers. Single-source vulnerability runs through FIFRA-registered strain repositories held by limited microbial suppliers. Distribution runs through farmer-owned cooperative channels consolidating procurement volumes for direct manufacturer negotiation, bypassing traditional agronomy retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application services and technical support contracts attach to biological nematicide procurement faster than standalone product sales, as agricultural cooperatives demand field efficacy validation and equipment retrofit assistance bundled with microbial inoculant volumes.
For Market Incumbents: Compound defensive positioning through captive microbial fermentation capacity additions in Corn Belt states, locking in substrate supply agreements ahead of cooperative procurement consolidation. Accelerate EPA registration pipeline positioning for Pasteuria penetrans and Bacillus firmus strain expansions before endangered species assessments trigger additional organophosphate withdrawals. Channel control through direct cooperative contracts represents the critical lever against distributor margin compression. For New Entrants and Emerging Players: EPA biorational fast-track registration offers the most penetrable regulatory pathway for microbial specialists lacking established FIFRA portfolios. Target greenhouse and nursery segments in Pacific states, where precision dosing equipment integration commands premium positioning and shorter re-entry intervals align with intensive harvest schedules. Go-to-market execution should emphasize technical service bundling over price competition, capturing cooperative adoption through demonstration plot partnerships with university extension services. For Investors and Strategic Acquirers: Long-term, this sits as a biological platform consolidation play because microbial fermentation expertise and EPA registration infrastructure compound defensive moats as synthetic chemistries face progressive withdrawal. Acquisition targets should screen for FIFRA-registered strain libraries and existing cooperative supply relationships rather than standalone formulation capacity. Watch EPA endangered species assessment timelines for Pacific Northwest watersheds as the signal indicating acceleration of biological substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Fermentation | Captive spore production capacity insulates margin pressure from substrate volatility and registration delays. |
| EPA Biorational Registration Pipeline Expansion | Accelerated FIFRA timelines for Pasteuria penetrans and Bacillus firmus strains capture cooperative procurement shifts. |
| Cooperative Direct Supply Agreements | Farmer-owned entity contracts in Georgia and the Carolinas bypass distributor compression and secure volume commitments. |
| Seed Treatment Integration Development | At-planting delivery formats capture Corn Belt labor-constrained acreage from soil-incorporated fumigant alternatives. |
| Technical Service Bundling | Field efficacy validation and equipment retrofit support commands premium positioning over commodity biological pricing. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with EPA registration specialists, agricultural cooperative procurement managers, university extension nematologists, custom applicator equipment operators, and specialty crop growers in California and Florida. Secondary validation drew from EPA Office of Pesticide Programs registration databases, USDA NRCS conservation practice standards documentation, state Department of Agriculture 24(c) special local need filings, and FIFRA Section 7 consultation records. Bottom-up acreage estimates across vegetable belts and row-corn systems were triangulated against top-down manufacturer shipment data.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type chemistry classes, application settings from agricultural fields to greenhouses, formulation physical forms, and end-user purchasing archetypes. CAGRs were derived from trend extrapolation of biological adoption rates and regulatory withdrawal timelines for synthetic alternatives. Industry-specific inputs incorporated EPA registration pipeline status, buffer zone mandate expansion trajectories, and cooperative procurement consolidation patterns.
Decision-makers should treat outputs as directional under assumptions of continued EPA biorational streamlining and stable conservation cost-share funding; material deviation in endangered species assessment timelines or state-level groundwater monitoring requirements would warrant model refresh. Practitioners should keep alternative scenarios live as FIFRA registration backlogs and cooperative channel migration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
India Insecticide Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Fumigation Service Market
Crop Protection
South America Insecticide Market
Crop Protection
Tembotrione Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
Europe Herbicide Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Global Termite Control Market
Crop Protection
Organic Pesticides Market
Crop Protection
Nematicides Market