
 Potassium Humate Market | 2026-2036
Potassium Humate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Humate Market Analytics
Agricultural input distribution is fragmenting across emerging economies as traditional dealer networks lose ground to direct manufacturer partnerships and agritech platforms. Humintech GmbH leverages its European technical heritage to sustain premium positioning in specialty crop segments. Shenyang Humate Technology anchors volume supply through integrated lignite sourcing in northeastern China. Omnia Specialities competes via differentiated liquid formulation capabilities serving Australian broadacre farming.
Potassium humate denotes the potassium salt of humic acid extracted from oxidized lignite or leonardite deposits, typically containing 8-12% potassium oxide and 50-70% humic acid content by dry weight, functioning primarily as a soil conditioner and biostimulant that enhances cation exchange capacity and nutrient chelation in agricultural systems. Powder formulations occupy the dominant share of commercial volumes due to lower logistics costs and blending compatibility with NPK fertilizers, while liquid potassium humate represents the fastest-expanding format driven by fertigation adoption in protected horticulture across Spain and the Netherlands. Organic farming applications command margin premiums relative to conventional soil amendment uses, reflecting certification requirements and price inelasticity among specialty produce growers.
The European Union's Fertilizing Products Regulation and REACH framework establish compositional and environmental release standards for humic substance products entering member state markets. India's FSSAI and BIS standards govern allowable heavy metal thresholds in organic agricultural inputs. China's Ministry of Ecology and Environment enforces extraction site remediation rules affecting leonardite mining permits. Stakeholders must monitor evolving carbon intensity disclosure requirements under the EU Green Deal that could reshape sourcing economics for imported potassium humate feedstocks.
Market Dynamics
China's Ministry of Agriculture and Rural Affairs mandate on chemical fertilizer reduction is restructuring input procurement across intensive vegetable production zones, forcing distributors to rebalance portfolios toward certified biostimulant alternatives.
Growth Catalysts
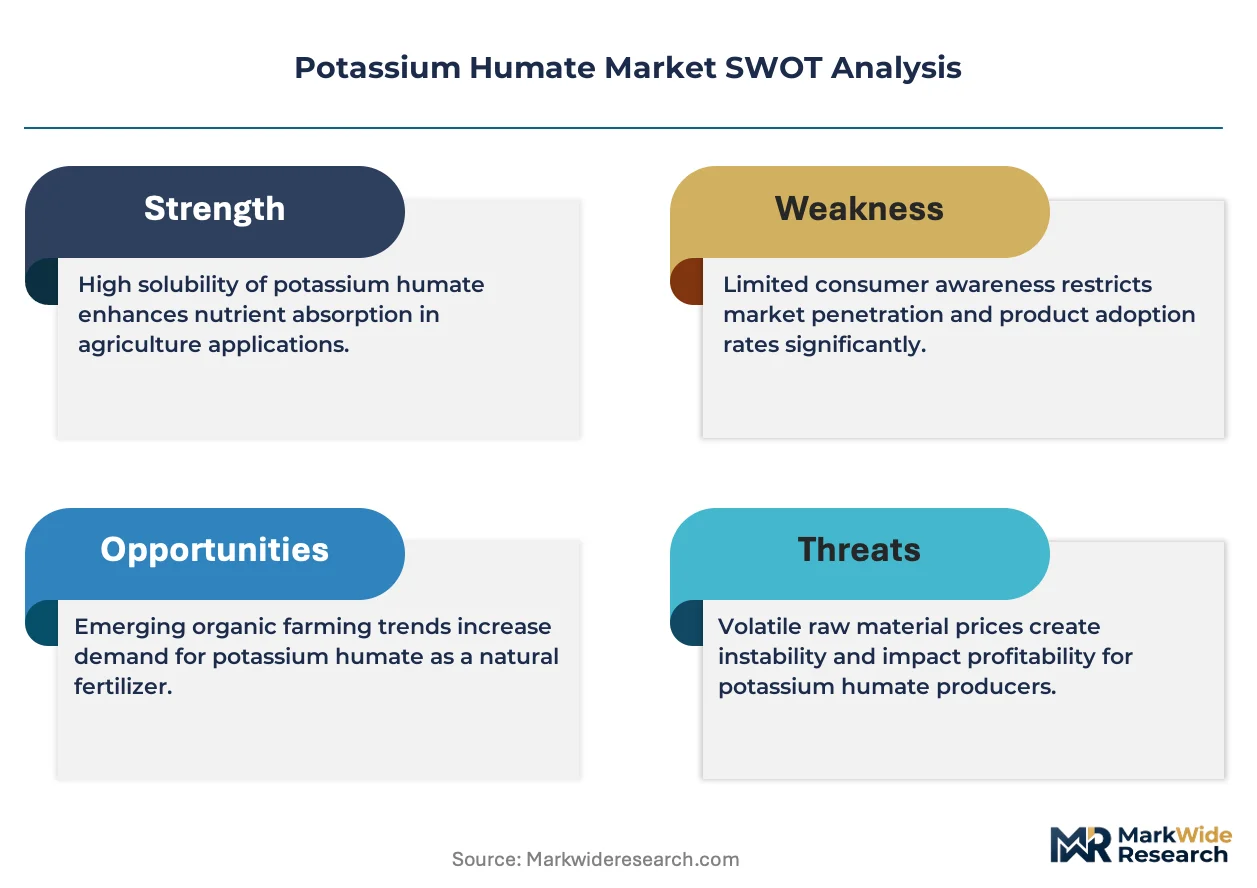
- EU Fertilizing Products Regulation:Standardized compositional requirements for humic substance products entering member state markets create compliance clarity that accelerates cross-border trade.
- Fertigation systems in protected horticulture:Spain and Netherlands greenhouse operators are retrofitting irrigation infrastructure to accommodate liquid potassium humate compatibility.
- Leonardite extraction in Inner Mongolia:Proximity to oxidized lignite deposits reduces feedstock transport costs for northeastern Chinese manufacturers serving Shandong Province demand.
Market Restraints
- Potassium oxide input volatility:MOP (muriate of potash) price swings transmit directly to potassium humate production economics, compressing margin predictability for blenders.
- Single-source leonardite dependence:Xinjiang and Inner Mongolia mining permits face tightening MEE extraction site remediation rules, concentrating supply risk.
- Synthetic biostimulant substitution:Amino acid and seaweed extract formulations compete for shelf space in specialty crop retail channels.
Strategic Opportunities
- Organic certification premiums in Brazil:Tightening MAPA standards for specialty crop exporters create price inelastic demand segments for certified-input suppliers.
- Carbon intensity disclosure under EU Green Deal:Import feedstock sourcing documentation requirements favor European leonardite processors with verifiable supply chain emissions data.
- Direct manufacturer partnerships:Agritech platforms in India bypass traditional dealer networks, enabling margin capture for producers willing to manage last-mile logistics.
Industry Challenges
- Heavy metal testing protocols:India's FSSAI and BIS allowable threshold enforcement creates certification timeline bottlenecks for imported feedstock processors.
- Liquid formulation stability:Shelf-life extension requires capex investment in chelation technology that mid-scale blenders struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Humate Market |
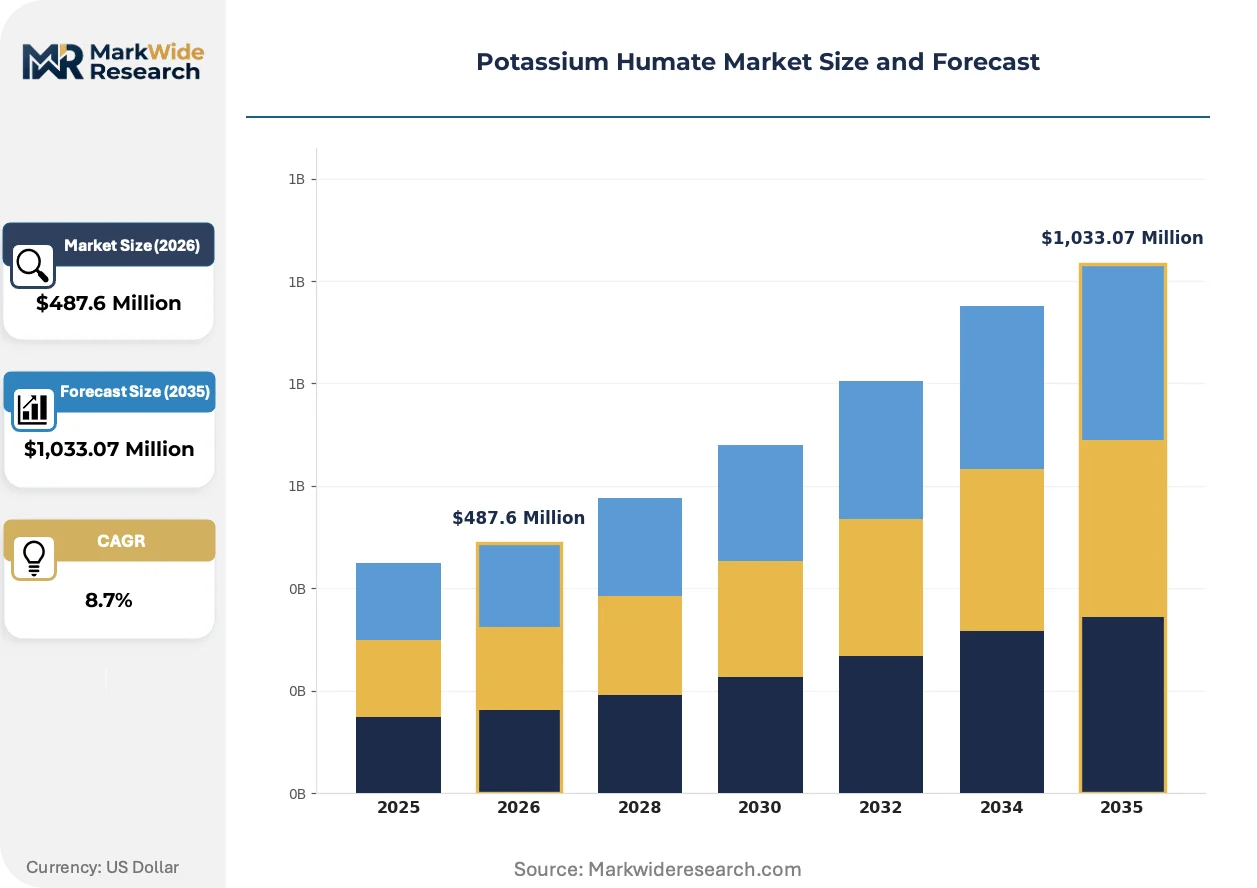
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Compact End Use Industry: Agriculture, Horticulture, Landscaping, Forestry Packaging Type: Bags, Drums, Bulk, Containers Application: Soil Amendment, Fertilizer, Organic Farming, Plant Growth |
| Companies Covered | Humintech GmbH, Humic Growth Solutions, Nutri-Tech Solutions, HGS BioScience, Shenyang Humate Technology, Xinjiang Double Dragon, Omnia Specialities, Jing Feng Humic Acid, Black Earth Humic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Humate Market Evolving Landscape
Formulation chemistry and application method convergence are compressing the traditional powder-versus-liquid segmentation, while regulatory disclosure requirements reshape competitive transparency.
Granular slow-release potassium humate is hybridizing with coated fertilizer technologies to create single-application products for broadacre grain operations. Australian wheat and canola growers in New South Wales are piloting these blends at scale. The technology is hybridizing procurement decisions, forcing traditional humate suppliers to partner with compound fertilizer manufacturers or cede volume to integrated input companies.
REACH framework environmental release standards for humic substance products are tightening documentation requirements for importers accessing EU member state markets. Industrial consequence includes mandatory third-party compositional verification that adds 8-12 week pre-market timelines. Specialty crop segments in Italy and Greece absorb these delays through advance contracting, while commodity grain distributors shift toward domestic European sourcing.
Certification-driven preference rotation is restructuring buyer segmentation as organic produce retailers enforce input traceability requirements upstream. Dutch auction houses and Spanish cooperative packing facilities now mandate batch-level documentation that conventional soil amendment buyers reject. The shift concentrates margin in certified supply chains while commoditizing undocumented product flows into conventional agriculture channels.
Potassium Humate Market Segmentation
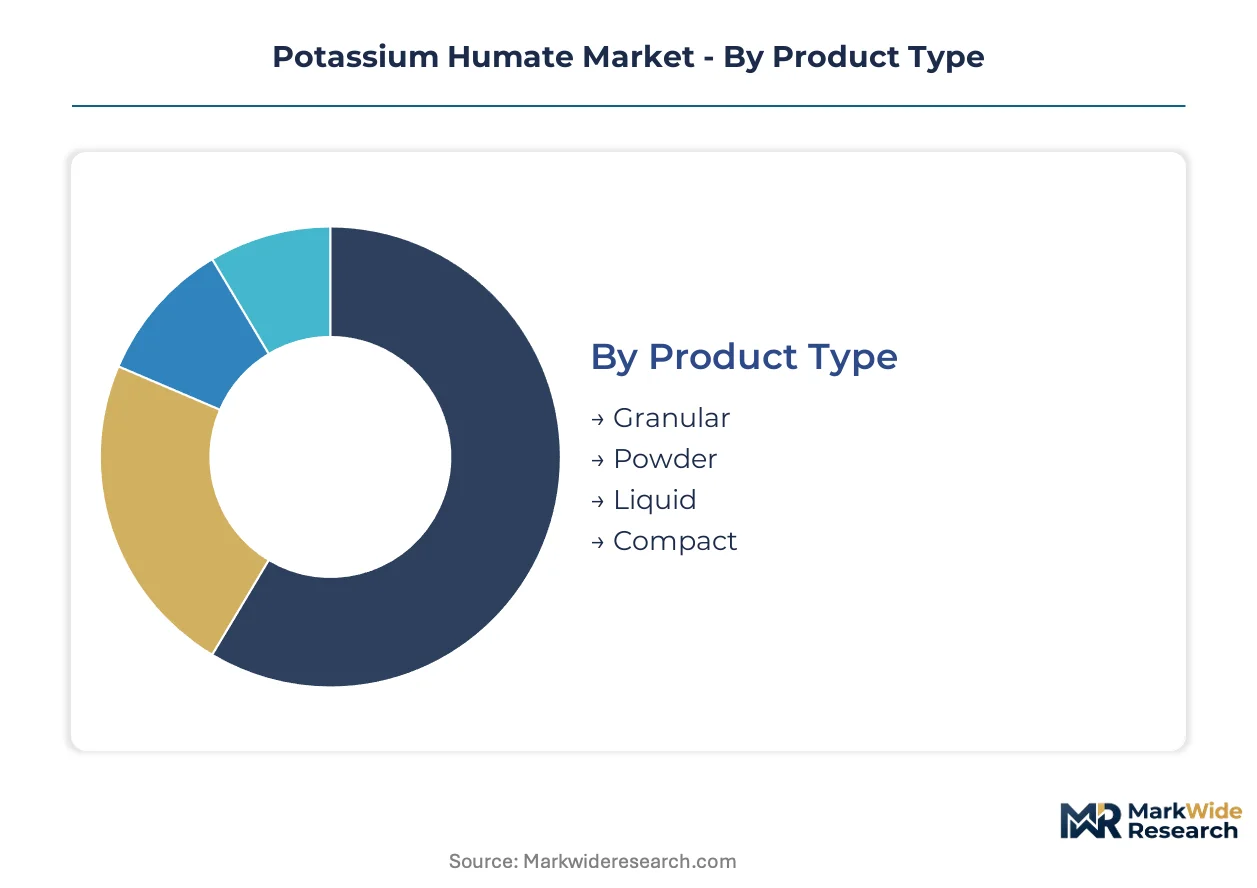
Potassium humate segmentation reflects divergent service intensity requirements across formulation chemistry and application protocols. Powder and liquid variants demand contrasting technical support for blending compatibility versus fertigation system integration.
Product Type:
After-sales service intensity varies sharply across physical states, with liquid formulations requiring ongoing technical consultation for irrigation system calibration and precipitation prevention.
- Granular:Slow-release pellets engineered through compaction of refined humic acid salts with potassium oxide carriers. Australian wheat growers in New South Wales pilot hybrid coated-fertilizer applications at scale, forcing traditional suppliers to partner with compound fertilizer manufacturers or surrender volume to integrated input companies.
- Powder:Fine-ground material containing 50-70% humic acid content by dry weight, optimized for dry blending with NPK fertilizers. Lower logistics costs and universal compatibility sustain dominant commercial volumes across Shandong Province's intensive vegetable production belt.
- Liquid:Soluble concentrate requiring chelation technology for shelf-life extension. Spain and Netherlands greenhouse operators retrofit irrigation infrastructure to accommodate fertigation compatibility, climbing the fastest among all formats.
- Compact:Compressed tablet or briquette form factor targeting precision application in specialty crop rows. Brazilian specialty crop producers adopt amid tightening MAPA organic certification standards.
Powder holds the largest share; momentum sits with liquid.
End Use Industry:
Cost tier stratification separates commodity grain operations from premium horticulture channels, with certification requirements driving price differentiation.
- Agriculture:Broadacre grain and oilseed production consuming potassium humate as soil conditioner. Conventional farming applications absorb undocumented product flows at compressed margins relative to certified channels.
- Horticulture:Protected cultivation systems in Spain and Netherlands command premium positioning through batch-level traceability mandates from Dutch auction houses and Spanish cooperative packing facilities.
- Landscaping:Turf management and ornamental plant maintenance requiring aesthetic performance validation. Municipal and commercial groundskeepers prioritize visual outcome predictability over compositional specifications.
- Forestry:Reforestation and plantation establishment applications with extended return timelines. Nurseries serving timber operations absorb longer certification timelines through advance contracting.
Horticulture captures margin premiums; agriculture anchors volume scale.
Packaging Type:
Customer type segmentation separates integrated compound fertilizer blenders from independent specialty distributors with divergent handling infrastructure.
- Bags:Standard woven polypropylene sacks of 25-50kg capacity serving retail agricultural input channels. Indian agritech platforms bypass traditional dealer networks for last-mile bagged product delivery.
- Drums:Sealed steel or plastic containers for liquid concentrate storage and transport. Shelf-life extension requirements favor drum packaging for chelated formulations with stability-sensitive chemistry.
- Bulk:Tanker truck or pneumatic discharge systems for compound fertilizer manufacturing integration. Volume procurement concentrates among northeastern Chinese manufacturers with captive lignite sourcing.
- Containers:Intermediate bulk containers and flexitanks for liquid export logistics. REACH framework documentation adds 8-12 week pre-market timelines for containerized EU-bound shipments.
Bulk commands procurement volume; containers expand with cross-border liquid trade.
Application:
Supply concentration patterns favor soil amendment commodity flows against fragmented organic certification channels with divergent documentation burdens.
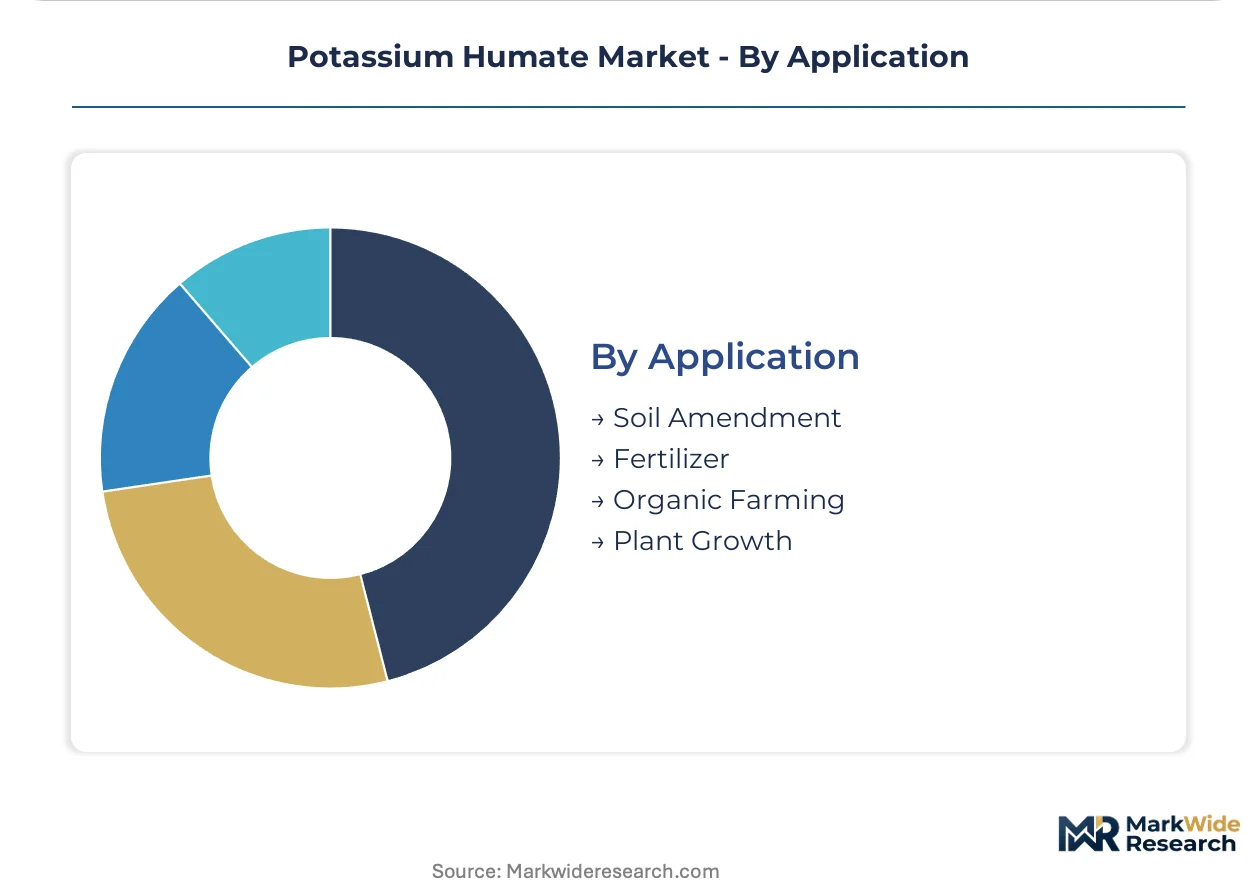
- Soil Amendment:Primary function enhancing cation exchange capacity and nutrient chelation in degraded agricultural systems. Conventional soil amendment buyers reject batch-level documentation requirements that certified channels mandate.
- Fertilizer:Direct nutrient delivery combining potassium oxide with humic acid biostimulant effects. MOP price volatility transmits directly to production economics, compressing margin predictability for blenders.
- Organic Farming:Certified input use satisfying retailer-enforced traceability requirements upstream. EU Green Deal carbon intensity disclosure requirements favor European processors with verifiable supply chain emissions data.
- Plant Growth:Biostimulant-focused applications targeting root development and stress tolerance. Amino acid and seaweed extract formulations compete for shelf space in specialty crop retail channels.
Soil amendment holds the largest share; organic farming captures steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European specialty crop channels while Chinese volume producers absorb compressed margins from feedstock proximity. This asymmetry shapes procurement patterns across intensive vegetable belts and protected horticulture clusters.
China
Shandong Province's intensive vegetable production belt anchors domestic consumption as the Ministry of Agriculture and Rural Affairs enforces chemical fertilizer reduction mandates. The Ministry of Ecology and Environment tightens extraction site remediation rules for Inner Mongolia leonardite mining permits. Northeastern manufacturers with integrated lignite sourcing dominate volume supply to provincial distributors.
Brazil
Specialty crop producers in São Paulo and Minas Gerais drive certified input adoption amid tightening MAPA organic certification standards for export-bound produce. National agricultural input distribution fragments as traditional dealer networks lose ground to direct manufacturer partnerships. Agritech platforms bypass legacy channels to capture margin in last-mile logistics.
Spain
Greenhouse operators in Almería and Murcia retrofit irrigation infrastructure to accommodate liquid potassium humate compatibility in fertigation systems. The EU Fertilizing Products Regulation establishes standardized compositional requirements that accelerate cross-border trade. Dutch auction houses and Spanish cooperative packing facilities mandate batch-level traceability documentation.
Netherlands
Protected horticulture clusters around Westland and Aalsmeer command premium positioning through retailer-enforced input traceability requirements. The EU Green Deal carbon intensity disclosure requirements favor processors with verifiable supply chain emissions data. REACH framework environmental release standards add mandatory third-party compositional verification timelines.
India
Intensive vegetable production in Maharashtra and Gujarat absorbs imported feedstock despite FSSAI and BIS heavy metal threshold enforcement creating certification bottlenecks. The country's national agricultural regulator maintains allowable contaminant standards that extend pre-market timelines for containerized shipments. Agritech platforms in Gujarat bypass traditional dealer networks for bagged product distribution.
Potassium Humate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock extraction and refined salt production. The vendor base separates between volume-driven lignite processors with captive mining assets and formulation-focused blenders serving specialty crop channels. Three archetypes dominate: integrated miners with backward control over leonardite deposits, technical specialists with chelation chemistry capabilities, and regional distributors with agritech platform partnerships. Competitive moves concentrate on direct manufacturer partnerships displacing traditional dealer networks and granular slow-release hybridization with coated fertilizer technologies.
Within the integrated mining tier, Shenyang Humate Technology and Xinjiang Double Dragon exemplify volume producers with northeastern Chinese lignite proximity. Humintech GmbH occupies a position among European technical heritage specialists sustaining premium positioning in specialty crop segments. Omnia Specialities sits within the differentiated formulation tier via liquid capabilities serving Australian broadacre farming. These three anchors represent distinct strategic postures without implying specific market share or financial performance.
| Leading Market Players |
|---|
| Humintech GmbH |
| Humic Growth Solutions |
| Nutri-Tech Solutions |
| HGS BioScience |
| Shenyang Humate Technology |
| Xinjiang Double Dragon |
| Omnia Specialities |
| Jing Feng Humic Acid |
| Black Earth Humic |
| Others |
Value Network & Pricing Analysis
Inner Mongolia leonardite mining concentration anchors feedstock costs for northeastern Chinese manufacturers, compressing margin pools for blenders without captive lignite access while European specialty crop channels capture certification premiums. MOP price volatility transmits directly through potassium oxide input costs, forcing procurement rebalancing across integrated and non-integrated supply tiers.
Pricing Analysis
Configured-to-order pricing for certified organic grades commands substantial premiums over standard powder formulations sold through conventional agricultural channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales technical intensity, with horticulture buyers in the Netherlands and Spain absorbing premium positioning through retailer-enforced traceability mandates. Cost compression in commodity soil amendment tiers is intensifying because MOP spot market swings transmit directly to production economics. Conventional grain operations in Australia and India exhibit highest price sensitivity, while Brazilian specialty crop exporters facing MAPA certification deadlines show relative inelasticity.
Supply Chain Analysis
Tariff exposure between China and key export destinations for containerized liquid shipments dominates supply chain risk planning for mid-scale blenders. Geographic supply concentration centers on China, Brazil, and Australia, with northeastern Chinese manufacturers drawing from Inner Mongolia and Xinjiang leonardite deposits. Raw material dependencies rest on oxidized lignite feedstock, MOP for potassium oxide enrichment, and chelation agents for liquid formulation stability. Single-source leonardite dependence creates vulnerability as MEE extraction site remediation rules tighten mining permit timelines. Distribution runs through agritech platforms bypassing traditional dealer networks in India and Brazil, alongside direct manufacturer partnerships serving European protected horticulture clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where REACH framework documentation requirements and EU Fertilizing Products Regulation compliance create 8-12 week barriers that favor incumbents with established verification protocols.
For Market Incumbents: Harden defensible positioning through backward integration into leonardite extraction assets in Inner Mongolia or Xinjiang, securing captive feedstock supply as MEE remediation rules tighten permit availability. Invest in chelation technology capacity to capture liquid formulation growth in Spanish and Dutch greenhouse retrofit cycles, defending against amino acid and seaweed extract substitutes gaining shelf space in specialty crop retail channels. For New Entrants and Emerging Players: Establish a beachhead in Indian agritech platform partnerships for bagged powder distribution, bypassing fragmented traditional dealer networks in Maharashtra and Gujarat vegetable belts. Target carbon intensity disclosure services for European importers facing EU Green Deal documentation requirements, offering verifiable supply chain emissions data as a differentiated service layer alongside physical product supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed formulation specialists possessing liquid chelation capabilities but lacking captive lignite sourcing. Long-term viability over the projection horizon favors processors with integrated mining assets or exclusive offtake arrangements with Inner Mongolia deposit operators. Watch for MEE permit revocation announcements as inflection indicators signaling supply concentration shifts and margin compression for non-integrated blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leonardite Mining | Captive feedstock supply from Inner Mongolia deposits insulates against MEE permit tightening and MOP volatility. |
| Chelated Liquid Formulation Capacity Expansion | Shelf-life extension technology captures fastest-expanding format demand from Spanish and Dutch fertigation retrofits. |
| Organic Certification Documentation Services | Batch-level traceability systems satisfy Dutch auction house and Spanish cooperative mandates for premium channel access. |
| Agritech Platform Direct Partnerships | Bypassing traditional dealer networks in Brazil and India enables margin capture in last-mile logistics. |
| Carbon Intensity Verification Infrastructure | EU Green Deal disclosure requirements favor processors with auditable supply chain emissions data for imported feedstocks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with specialty crop growers in Brazil and Spain, compound fertilizer procurement leads in Shandong Province, agritech platform operators in Gujarat, and leonardite mining license holders in Inner Mongolia. Secondary validation drew from Chinese Ministry of Agriculture and Rural Affairs fertilizer reduction mandates, EU Fertilizing Products Regulation implementation guidance, Indian FSSAI heavy metal threshold notifications, and Australian wheat grower cooperative trial data. Bottom-up volume estimates from application rates and cultivated hectares were triangulated against top-down trade flow analysis.
Calibration across the analysis window applied segment-specific growth assumptions for powder, liquid, and granular formats against end-use intensity in horticulture versus broadacre agriculture. Segmentation dimensions modeled include formulation chemistry, application protocol, certification tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for policy inflection points including China's chemical fertilizer reduction mandates and EU carbon disclosure phased implementation. Industry-specific forecast inputs incorporated MOP price correlation coefficients and greenhouse retrofit adoption curves in Mediterranean protected cultivation.
Stress conditions across leonardite permit revocation severity, MOP price spike magnitude, and synthetic biostimulant substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology adoption S-curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Agrochemical Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Superphosphates Market