
 India Agriculture Market | 2026-2036
India Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
India Agriculture Market Insights
The PLI scheme for food processing is pivoting capital toward integrated cold chain infrastructure and mechanized sorting facilities. Coromandel International Ltd leverages its coastal manufacturing footprint to dominate specialty fertilizer formulations. UPL Ltd anchors its position through deep distribution networks in Maharashtra and Gujarat cotton belts. Godrej Agrovet Limited sustains competitive intensity with its dairy-adjacent feed and crop protection portfolio.
India agriculture encompasses crop cultivation, livestock husbandry, aquaculture, and allied activities governed by soil chemistry parameters, monsoon-dependent irrigation cycles, and minimum support price mechanisms. The sector supplies raw biomass to food processing, textile fiber, and biofuel industries while employing roughly two-fifths of the national workforce. Crops and seeds represent the volume foundation, yet margin pools concentrate in pesticides where patent-protected molecules command pricing power. Fertilizers face structural pressure from urea subsidy distortions, while organic farming as an end-use channel is expanding fastest among export-oriented horticulture zones.
BIS seed certification standards and FSSAI residue limits shape product registration timelines and market access for agrochemical formulators. The CEA's rural electrification mandates and state-level groundwater extraction regulations are restructuring pump irrigation economics across Punjab, Haryana, and western Uttar Pradesh. Stakeholders must monitor how DGFT export restriction protocols and evolving EU MRL standards for Indian basmati and spices reroute procurement priorities toward residue-compliant production systems.
Market Dynamics
PLI scheme disbursements are redirecting private capital toward integrated cold chains and mechanized sorting infrastructure, compressing post-harvest losses while reconfiguring procurement relationships between food processors and horticulture clusters.
Growth Catalysts
- Export-oriented horticulture clusters:Maharashtra's grape and pomegranate belt commands premium offtake through residue-compliant production systems aligned with EU MRL standards.
- CEA rural electrification mandates:Grid connectivity expansion across Punjab, Haryana, and western Uttar Pradesh is restructuring pump irrigation economics and enabling precision agriculture equipment deployment.
- FSSAI residue limit enforcement:Stricter maximum residue limits are accelerating adoption of biopesticides and integrated pest management protocols among contract farming operations.
Market Restraints
- Urea subsidy distortions:Fertilizer pricing asymmetries suppress private investment in specialty nutrient formulations and constrain farmer switching toward balanced crop nutrition.
- Groundwater extraction regulations:State-level extraction caps in Punjab and Haryana are limiting expansion of water-intensive rice cultivation and threatening farm-level productivity.
- Monsoon-dependent irrigation cycles:Rainfall variability concentrates supply risk in unirrigated districts of Madhya Pradesh, Rajasthan, and Karnataka.
Strategic Opportunities
- Integrated cold chain infrastructure:PLI scheme capital is creating white space for temperature-controlled logistics networks connecting Maharashtra horticulture clusters to Jawaharlal Nehru Port export terminals.
- Organic farming in export zones:APEDA-organic certification corridors in Karnataka and Telangana offer premium market access for residue-free basmati and spice consignments.
- Drone-based crop monitoring:DGCA regulatory clarity on unmanned aerial vehicle operations is opening precision agriculture service markets in Gujarat cotton belts.
Industry Challenges
- BIS seed certification timelines:Extended varietal registration protocols delay commercialization of hybrid seeds and compress effective patent protection windows.
- Soil chemistry expertise scarcity:Agronomist shortages constrain adoption of site-specific nutrient management and precision fertilizer application.
- Legacy mandi infrastructure:APMC yard modernization requirements demand capital outlays that smaller traders cannot absorb, consolidating intermediary power.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Agriculture Market |
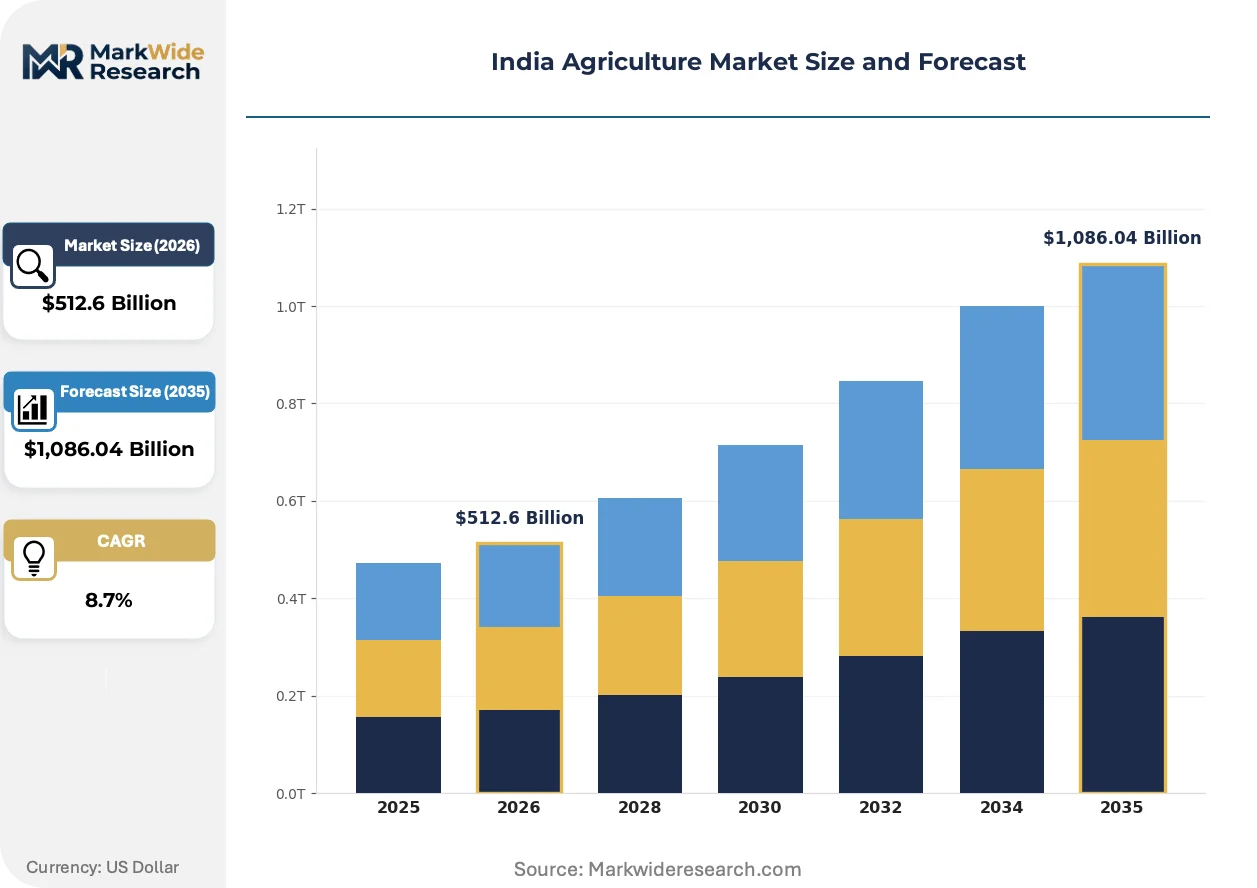
| Market Size in 2026 | $512.6 Billion |
| Market Size in 2035 | $1,086.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crops, Seeds, Fertilizers, Pesticides End Use Industry: Agronomy, Horticulture, Organic Farming, Aquaculture Distribution Channel: Retailers, Wholesalers, Cooperatives, E-commerce Packaging Type: Bags, Boxes, Bulk, Bottles |
| Companies Covered | Coromandel International Ltd, UPL Ltd, Godrej Agrovet Limited, Rallis India Ltd, Indian Farmers Fertiliser Cooperative Ltd, DuPont India, Nuziveedu Seeds Limited, Gujarat State Fertilizers and Chemicals Ltd, Chambal Fertilizers and Chemicals Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Agriculture Market Trends and Innovations
Mechanization and digitization are converging to compress cultivation cycles while regulatory pressure on chemical residues is accelerating biological input adoption across export-oriented production zones.
Drone-based pesticide application is consolidating fragmented aerial spraying services into licensed operator networks. Large horticulture estates in Maharashtra and Karnataka are contracting DGCA-authorized drone fleets for targeted fungicide deployment. This technology is consolidating variable-rate application capabilities previously distributed across manual labor pools and ground-based equipment owners.
FSSAI residue limit notifications are tightening enforcement protocols for basmati rice and spice consignments. Export-oriented processors in Haryana and Uttar Pradesh are deploying rapid testing infrastructure at farm-gate collection points. The spice processing segment is responding by backward integrating into contract farming arrangements with residue traceability mandates.
Food processors are unbundling procurement from traditional mandi intermediaries. Direct purchase agreements with farmer producer organizations are displacing commission-based trading in Maharashtra grape clusters and Andhra Pradesh chili belts. This disintermediation is most visible in districts where PLI scheme cold chain investments enable processor-controlled quality preservation from harvest to factory gate.
India Agriculture Market Segmentation
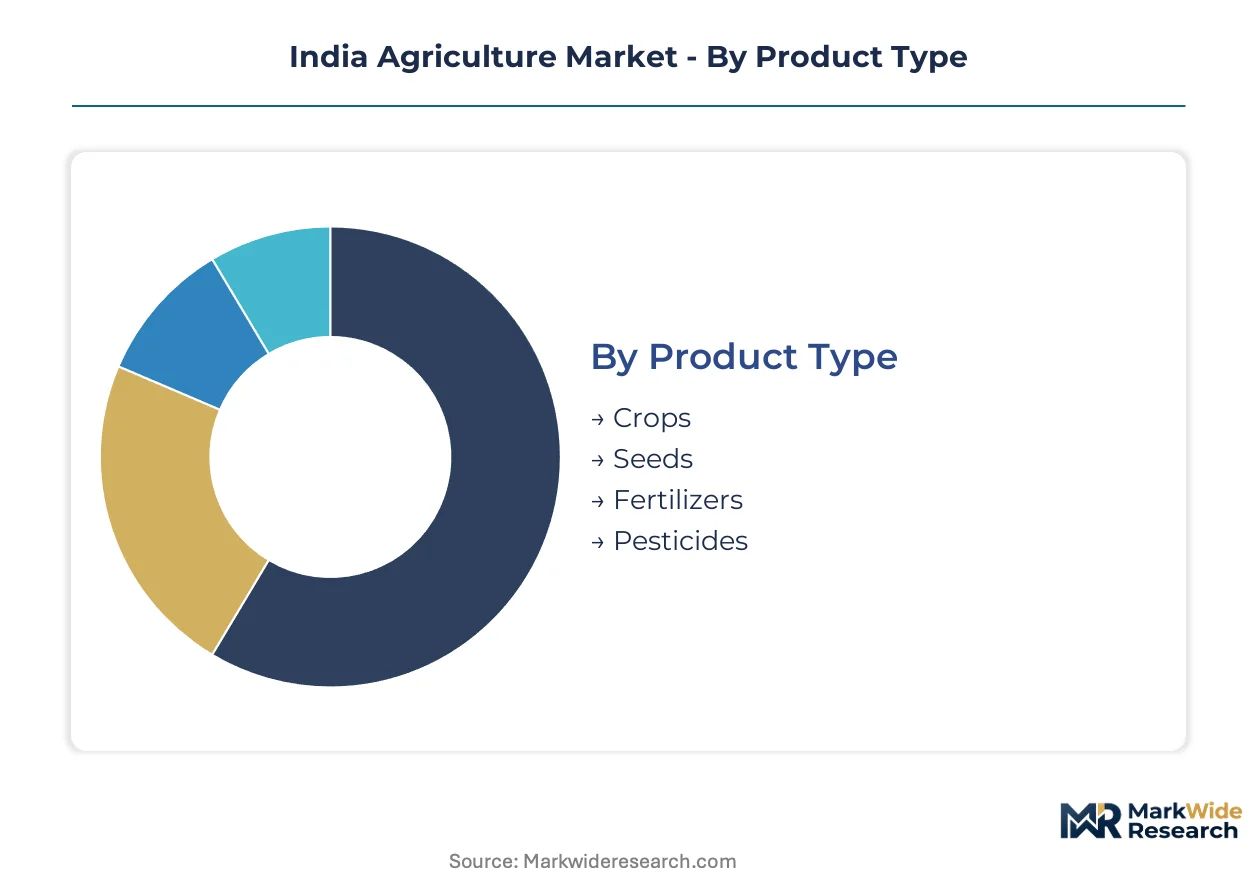
Segmentation in Indian agriculture reveals how procurement power concentrates differently across input categories versus output channels. Understanding these concentration patterns helps stakeholders identify where margin pools form and where regulatory leverage applies.
Product Type:
Supply concentration in input manufacturing determines pricing power and distribution economics across India's agricultural value chain.
- Crops:Field crops including cereals, pulses, and oilseeds constitute the volume foundation of Indian agriculture. Procurement concentrates in Punjab, Haryana, and western Uttar Pradesh where FCI minimum support price mechanisms create predictable offtake. Monsoon variability in Madhya Pradesh and Rajasthan introduces supply volatility that processors must hedge through buffer stock strategies.
- Seeds:Certified hybrid and genetically pure seeds command premium positioning through BIS varietal registration protocols. Demand clusters in Maharashtra cotton belts and Gujarat groundnut zones where farmer willingness-to-pay for yield assurance exceeds national averages. Patent protection windows compress effective commercialization periods for proprietary genetics.
- Fertilizers:Urea dominates volume through subsidized pricing, constraining balanced nutrition adoption. NPK complexes and micronutrient formulations face margin pressure from import dependency and rupee volatility.
- Pesticides:Patent-protected molecules in herbicides and fungicides capture disproportionate margin pools versus generic insecticide commoditization.
Today's leader: Crops. Tomorrow's challenger: Seeds.
End Use Industry:
Application maturity and export certification requirements create tiered margin structures across downstream channels.
- Agronomy:Conventional field crop management represents the mature volume base with established input protocols and mechanization penetration. Punjab and Haryana rice-wheat systems anchor equipment utilization rates for tractor and harvester OEMs.
- Horticulture:Grape, pomegranate, and mango clusters in Maharashtra command residue-compliant premium pricing aligned with EU MRL standards. APEDA export certification mandates are restructuring input procurement toward biopesticide-tolerant varieties.
- Organic Farming:Karnataka and Telangana certification corridors are gaining share fastest as European and North American buyers tighten residue traceability requirements. Conversion timelines and yield penalties constrain smallholder participation.
- Aquaculture:Andhra Pradesh shrimp belts and Gujarat brackish water zones drive specialized feed and probiotic demand. Coastal regulation zone notifications limit pond expansion in traditional production centers.
Agronomy holds current volume dominance. Horticulture captures expanding premium pools.
Distribution Channel:
Channel economics reflect working capital intensity and last-mile reach requirements across India's fragmented farm landscape.
- Retailers:Village-level input shops maintain proximity advantage for smallholder purchasing decisions. Inventory financing constraints limit product range breadth in eastern Uttar Pradesh and Bihar.
- Wholesalers:Mandi-adjacent distributors aggregate procurement for processing industries and institutional buyers. Commission structures face compression from direct purchase agreement expansion.
- Cooperatives:Gujarat and Maharashtra dairy-linked societies leverage member trust for input bundling. Fertilizer subsidy pass-through mechanisms create working capital advantages versus independent retailers.
- E-commerce:Agri-input platforms are concentrating fastest in Karnataka and Telangana where smartphone penetration and logistics density enable same-day delivery commitments. Product authenticity verification remains a adoption barrier.
Retailers maintain current reach supremacy. E-commerce presents the steepest expansion trajectory.
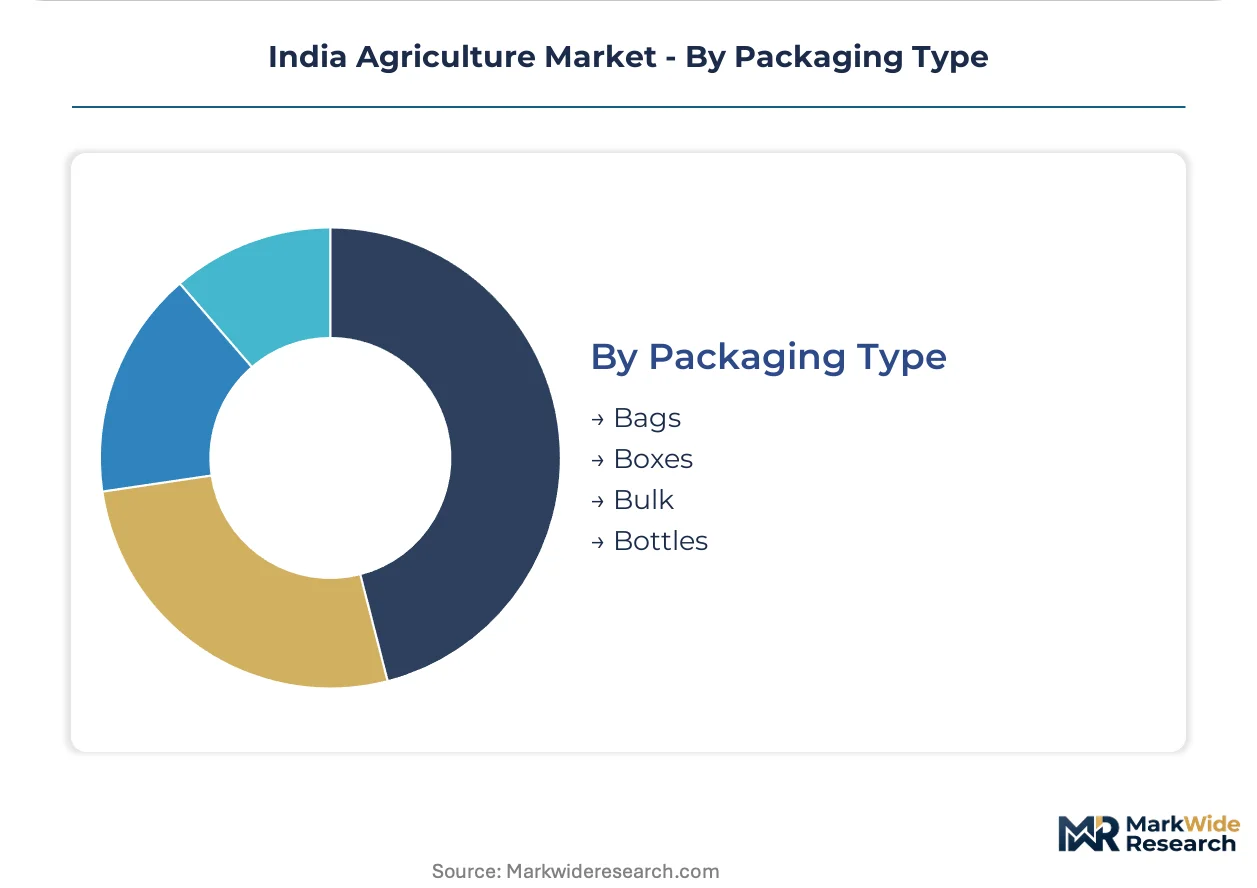
Packaging Type:
Packaging selection correlates with customer scale, storage infrastructure, and regulatory labeling mandates.
- Bags:Woven polypropylene dominates seed and fertilizer unitization through cost efficiency and mechanical handling compatibility.
- Boxes:Corrugated formats concentrate in horticulture export corridors where stacking strength and print quality support brand differentiation.
- Bulk:Tanker and silo delivery systems serve integrated food processors and ethanol distilleries with captive storage infrastructure.
- Bottles:HDPE containers carry liquid formulations and bio-stimulants where dosing precision and child safety closures command regulatory compliance.
Bags retain cost-driven dominance. Bulk formats are climbing fastest among commercial farming operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Green Revolution took root in Punjab and Haryana during the 1960s, establishing these northwestern plains as the cradle of mechanized cereal production. This historical foundation continues to shape procurement patterns and infrastructure deployment across Indian agriculture.
Punjab
Rice-wheat procurement dominance drives input demand cycles aligned with FCI minimum support price calendars. State-level groundwater extraction caps under the Punjab Preservation of Subsoil Water Act constrain paddy acreage expansion. Ludhiana and Jalandhar equipment clusters supply tractor and harvester OEMs serving the Indo-Gangetic belt.
Haryana
Basmati export corridors in Karnal and Kurukshetra districts command residue-compliant input protocols under APEDA certification mandates. FSSAI enforcement of maximum residue limits accelerates biopesticide adoption among contract farming operations. The Yamuna belt concentrates food processing investments linking farm-gate collection to cold chain infrastructure.
Maharashtra
Grape and pomegranate clusters in Nashik and Solapur districts capture premium offtake through EU MRL-aligned production systems. PLI scheme disbursements redirect capital toward integrated cold chains connecting horticulture belts to Jawaharlal Nehru Port export terminals. Pune-based distribution networks anchor crop protection and specialty fertilizer formulation supply.
Gujarat
Cotton and groundnut cultivation in Saurashtra and North Gujarat sustains deep distribution networks for hybrid seeds and agrochemicals. DGCA regulatory clarity on unmanned aerial vehicle operations opens precision agriculture service markets across the cotton belt. Coastal manufacturing footprints support fertilizer and pesticide formulation for western India supply.
Karnataka
APEDA-organic certification corridors in Mysuru and Hassan districts offer premium market access for residue-free spice and coffee consignments. E-commerce agri-input platforms concentrate in Bengaluru and Hyderabad logistics catchments enabling same-day delivery commitments. Smartphone penetration and logistics density support digitized procurement channel expansion.
India Agriculture Market Competitive Landscape
The competitive structure tilts toward diversified conglomerates with captive distribution networks. Input manufacturing concentrates among fertilizer cooperatives and crop protection formulators with deep rural reach. Three archetypes dominate: coastal manufacturing specialists leveraging import-adjacent formulation economics, dairy-adjacent conglomerates bundling feed and crop protection portfolios, and cooperative structures capturing subsidy pass-through advantages. Consolidation pressures emerge through direct purchase agreement expansion and cold chain infrastructure investments that favor integrated operators over fragmented traders.
Within the coastal manufacturing tier, Coromandel International Ltd and Gujarat State Fertilizers and Chemicals Ltd occupy positions anchored to port-proximate production economics. UPL Ltd exemplifies the distribution-intensive archetype through its presence in Maharashtra and Gujarat cotton belts. Godrej Agrovet Limited represents dairy-adjacent diversification into crop inputs, while Indian Farmers Fertiliser Cooperative Ltd anchors the cooperative structure with member-linked procurement advantages. Rallis India Ltd and Chambal Fertilizers and Chemicals Ltd sit within regional formulation specialists serving northern and western India demand clusters.
| Leading Market Players |
|---|
| Coromandel International Ltd |
| UPL Ltd |
| Godrej Agrovet Limited |
| Rallis India Ltd |
| Indian Farmers Fertiliser Cooperative Ltd |
| DuPont India |
| Nuziveedu Seeds Limited |
| Gujarat State Fertilizers and Chemicals Ltd |
| Chambal Fertilizers and Chemicals Ltd |
| Others |
Pricing and Supply Chain Analysis
EU MRL compliance standards gate both qualified supply and premium-tier pricing access for Indian agricultural exports, bifurcating procurement networks into residue-certified premium channels and domestic spot markets. This regulatory filter concentrates pricing power among integrated operators capable of traceability documentation from farm gate to port terminal.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification grade and volume scale. Premium tiers command residue-compliant basmati and spice consignments with full APEDA traceability, while economy tiers serve unbranded domestic mandi trade. Price differentiation stems from FSSAI enforcement intensity and cold chain infrastructure ownership. Cost compression in standard tiers is intensifying because urea subsidy distortions suppress balanced nutrition adoption. Smallholder cooperatives exhibit highest price sensitivity, whereas export-oriented horticulture estates demonstrate lowest sensitivity due to EU offtake premiums.
Supply Chain Analysis
Single-source vulnerability sits with China for technical-grade pesticide intermediates and with Russia-Ukraine corridors for potash fertilizer imports. Active ingredient synthesis draws from Chinese chemical parks, while phosphoric acid feedstock rests on Moroccan and Jordanian mining concentration. Tariff exposure on imported urea and DAP creates margin volatility for domestic formulators. Distribution runs through cooperative networks in Gujarat and Maharashtra, mandi-adjacent wholesalers in Punjab and Haryana, and emerging agri-input e-commerce platforms in Karnataka and Telangana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Agriculture Market functions as a geographic-arbitrage play where EU residue standards create 40-60% price premiums over Middle Eastern and African destinations, justifying backward integration investments despite higher compliance costs.
For Market Incumbents: Extend cold chain infrastructure ownership into Maharashtra grape and pomegranate belts to capture disintermediation gains from PLI scheme capital deployment. Deepen captive supply of biopesticide formulations to defend against FSSAI residue limit tightening. Channel control through farmer producer organization contracting represents the critical defensive lever against e-commerce platform encroachment. For New Entrants and Emerging Players: Begin with drone-based precision agriculture services in Gujarat cotton belts where DGCA regulatory clarity has opened licensed operator markets. The most penetrable white space sits with residue traceability software for APEDA certification corridors in Karnataka and Telangana. A go-to-market angle anchored to processor-funded equipment leasing bypasses smallholder capital constraints. For Investors and Strategic Acquirers: Roll-up economics work for regional agri-input distributors because APMC modernization requirements are consolidating intermediary power and eliminating sub-scale traders. Long-term viability hinges on 5-10 year conversion of domestic horticulture toward export-oriented residue compliance. The acquisition target archetype is cooperative-linked wholesalers with working capital advantages from fertilizer subsidy pass-through. The signal to watch is EU MRL notification frequency for Indian spice consignments as an inflection indicator for biopesticide adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Cold Chain Expansion | PLI scheme capital deployment compresses post-harvest losses and reconfigures processor-farmer procurement relationships. |
| Backward Integration into Biopesticide Manufacturing | FSSAI residue enforcement and EU MRL alignment create captive demand for residue-tolerant input formulations. |
| Drone Operator Network Licensing | DGCA regulatory clarity enables precision agriculture service markets across Gujarat and Maharashtra cotton belts. |
| APEDA Certification Corridor Development | Organic and residue-free certification infrastructure unlocks premium European and North American offtake channels. |
| Direct Purchase Agreement Scaling | Processor-controlled procurement from farmer producer organizations displaces commission-based mandi intermediation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with agrochemical formulators, food processing procurement heads, cooperative society managers, and APEDA certification officers with secondary validation. Secondary sources included DGFT export restriction notifications, FSSAI residue limit gazettes, CEA rural electrification mandates, and state-level groundwater extraction regulations. Bottom-up crop acreage and input consumption estimates were triangulated against top-down GDP agricultural value-add benchmarks.
Historical reference periods anchored the forecast window to pre-pandemic baselines and post-PLI scheme implementation trajectories across the modeling period. Segmentation dimensions modeled included product type, end-use industry, distribution channel, and packaging format alongside state-level regulatory cluster differentiation. CAGRs were derived from weighted regression of input intensity trends and export certification velocity. Industry-specific forecast inputs incorporated monsoon variability indices and EU MRL notification frequency.
Caveats apply where monsoon failure severity, rupee depreciation against dollar-denominated input imports, or sudden DGFT export restriction protocols could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Africa Compound Feed Market