
 Rapeseed Oil Market | 2026-2036
Rapeseed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Rapeseed Oil Market Intelligence
Crushing-plant operator expertise is bifurcating as automated solvent extraction spreads across new facilities while artisanal cold-press skills command premium contract terms. Cargill Incorporated leverages its Canadian Prairie elevator network to anchor North American origination flows. Bunge Limited competes through port-adjacent crush capacity in Rotterdam and Hamburg. Louis Dreyfus Company sustains Black Sea origination relationships that supply Mediterranean refiners.
Rapeseed oil is a triglyceride extract from Brassica napus seeds containing roughly 7% saturated fat, 61% monounsaturated oleic acid, and 32% polyunsaturated linoleic and alpha-linolenic acids, produced via pre-press solvent extraction or mechanical cold-pressing for food-grade and industrial applications. Refined oil dominates food-service procurement due to neutral flavor and high smoke point, while cold-pressed oil occupies specialty retail shelves at significant premiums. Biofuels application is accelerating fastest as renewable diesel hydrotreaters absorb growing oilseed volumes.
The EU Green Deal and F-Gas Regulation shape crop rotation incentives and processing emissions standards across European crush facilities. Health Canada and the country's national pharmaceutical regulator enforce omega-3 labeling and novel-food approvals that constrain product-positioning claims. Stakeholders must monitor renewable diesel offtake agreements and crush-margin volatility as biofuel policy outpaces food-demand growth.
Market Dynamics
The renewable diesel buildout is redirecting rapeseed crush capacity from food-grade refining toward hydrotreated vegetable oil (HVO) offtake contracts, tightening edible-oil supply chains and compressing food-service margins.
Growth Catalysts
- EU Green Deal biofuel mandates:Binding renewable energy targets for transport are pulling rapeseed oil into HVO production, creating dedicated demand streams separate from food applications.
- Canadian Prairie crushing expansion:Export-oriented infrastructure investments in Alberta and Saskatchewan are connecting origination to Asian and European biofuel markets.
- Clean-label food processing:German and French food manufacturers are reformulating with high-oleic rapeseed oil to meet retailer clean-label requirements.
Market Restraints
- Input cost volatility:Natural gas and hexane solvent prices swing crush margins unpredictably, particularly for European facilities dependent on spot energy markets.
- Black Sea supply concentration:Ukrainian and Russian seed exports remain vulnerable to port disruptions, forcing Mediterranean refiners to maintain costly buffer stocks.
- Regulatory friction:Health Canada's novel-food approval pathway delays omega-3 positioning claims, constraining premium product launches.
Strategic Opportunities
- Underpenetrated specialty retail:Cold-pressed organic rapeseed oil commands 40-60% premiums in North American natural-foods channels with limited domestic supply.
- Technology convergence:Near-infrared spectroscopy and AI-driven sorting are enabling real-time oil-content grading at primary elevators, improving origination efficiency.
- Regulatory tailwind:Germany's KBA vehicle-type approval incentives for renewable diesel are accelerating long-term offtake contracting for crush operators.
Industry Challenges
- Skill bifurcation in crush operations:Automated solvent-extraction facilities require process-control engineers while artisanal cold-press units need traditional mechanical expertise, creating competing talent pipelines.
- Capex intensity for HVO integration:Pre-treatment and degumming upgrades to meet hydrotreater specifications demand capital allocations that strain mid-sized processors.
- Certification timeline compression:ISCC EU and RSB sustainability certifications now require 12-18 month validation cycles that delay biofuel contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapeseed Oil Market |
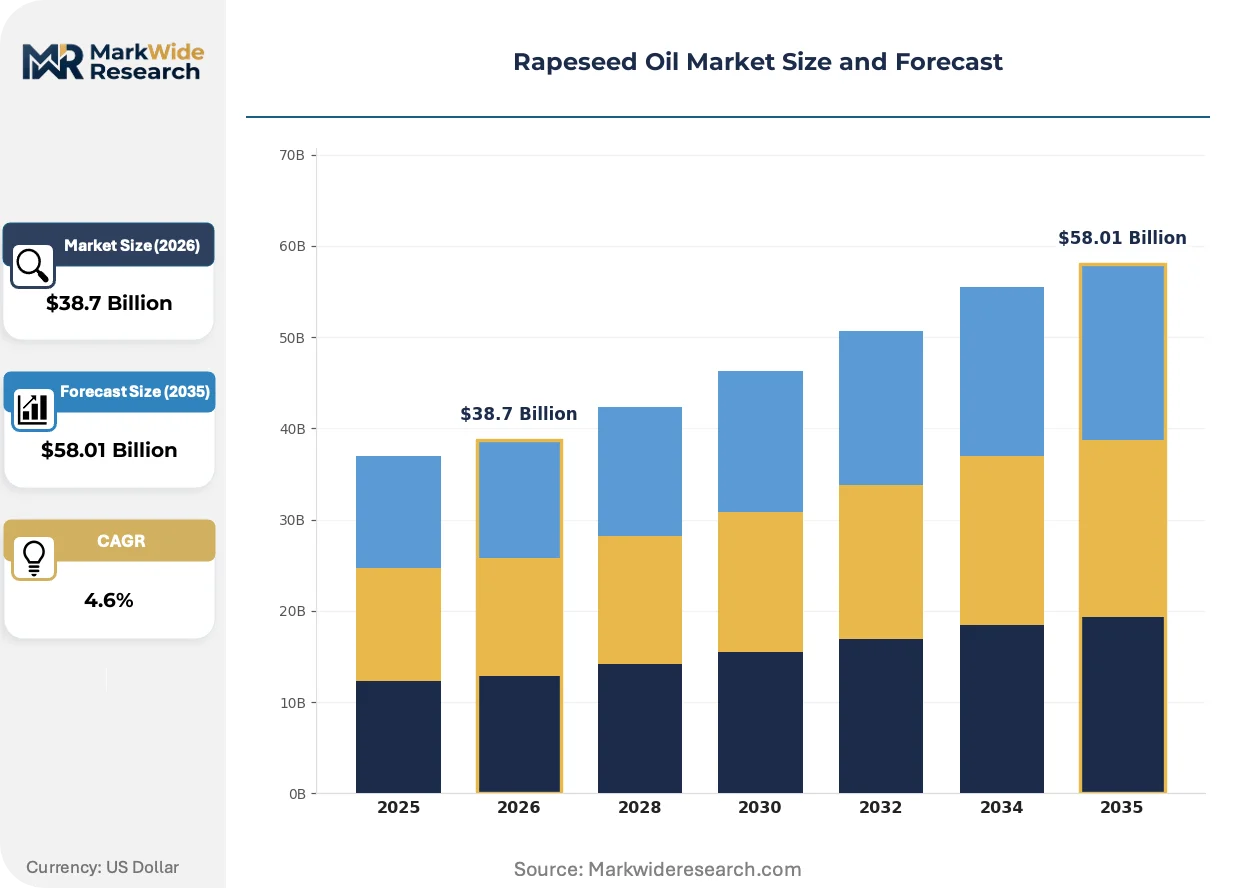
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Organic Oil, Cold-Pressed Oil Application: Food Industry, Biofuels, Cosmetics, Pharmaceuticals End User: Restaurants, Food Processors, Retail Chains, Manufacturers Distribution Channel: Wholesale, Online Retail, Supermarkets, Specialty Stores |
| Companies Covered | Louis Dreyfus Company, Cullise Ltd., Archer-Daniels-Midland Company, Ola Oils Limited, Interfat SA, Bunge Limited, Conagra Brands, Yorkshire Rapeseed Oil, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapeseed Oil Market Strategic Shifts & Innovations
Digital origination platforms and renewable diesel process chemistry are restructuring how rapeseed oil moves from farm to refiner, compressing traditional merchant intermediaries.
Mechanical cold-pressing technology is fragmenting the premium edible-oil segment. Small-scale processors in France's Burgundy region and Canada's Manitoba are deploying skid-mounted expeller systems for traceable, low-temperature extraction. Specialty retailers and direct-to-consumer channels are absorbing this output at 2-3x refined-oil pricing. The technology is fragmenting regional supply chains into parallel food-service and artisanal streams.
REACH and the EU F-Gas Regulation are tightening solvent-recovery and emissions standards at European crush facilities. Hexane capture rates now face mandatory 99.5% efficiency thresholds, requiring carbon-adsorption retrofits. Northern European processors in Rotterdam and Hamburg corridors are absorbing compliance costs fastest, widening operating-cost spreads against Black Sea competitors.
Buyer consolidation among renewable diesel refiners is compressing contracting cycles. Neste, Diamond Green Diesel, and REG are negotiating 3-5 year offtake agreements directly with crush operators, bypassing traditional merchant houses. This pattern is most visible in the US Gulf Coast and Singapore refining hubs where HVO capacity is concentrating.
Rapeseed Oil Market Segmentation
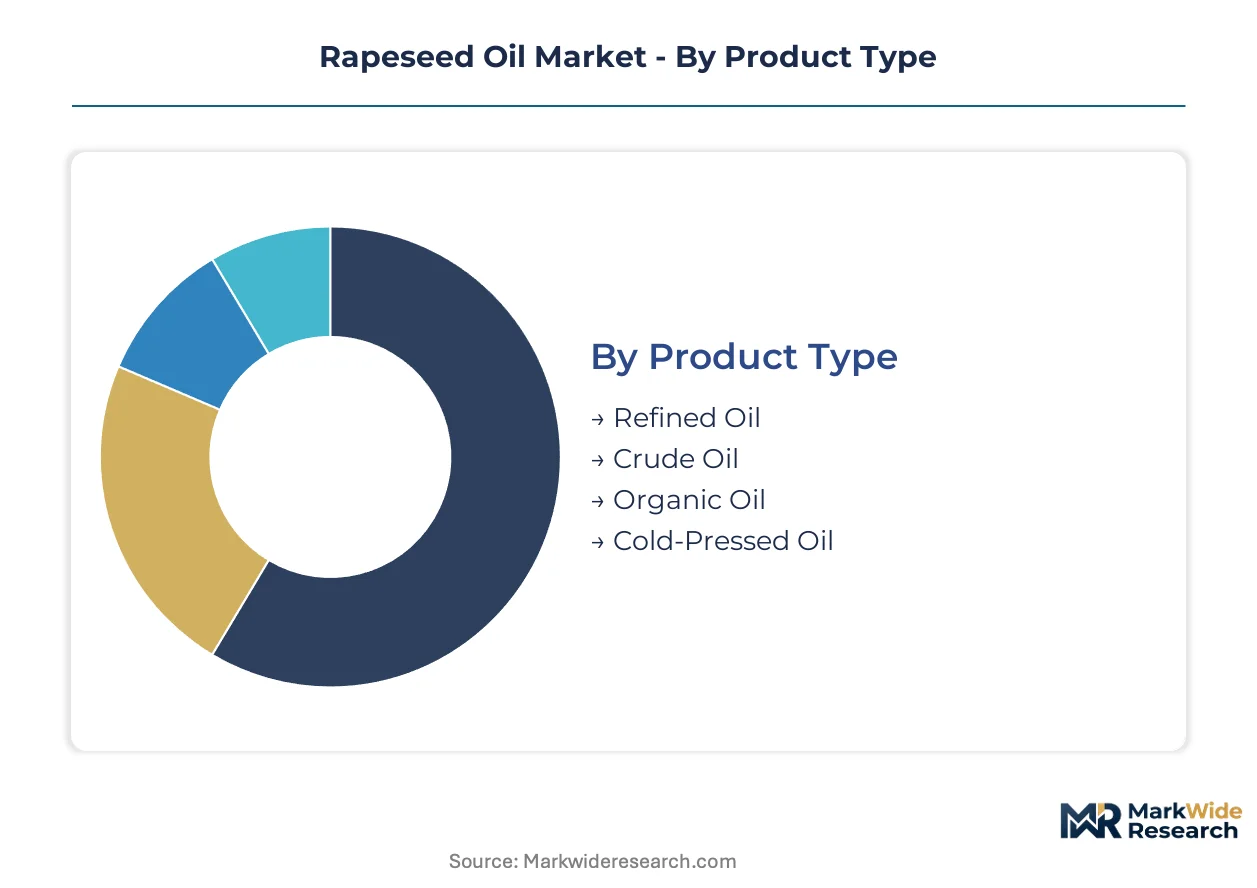
Rapeseed oil segmentation reflects divergent processing standards, end-use specifications, and channel economics. Regulatory thresholds for biofuel sustainability certification and food-grade solvent residues create distinct compliance burdens across product tiers.
Product Type:
REACH and the EU F-Gas Regulation impose differentiated hexane-recovery mandates on solvent-extracted grades versus mechanical-pressed alternatives, fragmenting capital requirements and margin structures.
- Refined Oil:Neutral-flavor triglyceride oil processed through degumming, neutralization, bleaching, and deodorization to achieve sub-0.1% free fatty acid content and 230°C+ smoke points. German and French food-service distributors concentrate procurement here, driven by retailer clean-label reformulation timelines that demand consistent oxidative stability.
- Cold-Pressed Oil:Mechanical extraction below 40°C preserves phospholipids and tocopherols, yielding grassy flavor profiles and 15-18 month shelf lives. Burgundy processors and Manitoba micro-crushers supply North American natural-foods channels where 40-60% premiums over refined grades sustain small-batch economics.
- Crude Oil:Pre-press solvent-extracted oil retaining 1-3% phosphatides and 0.5-1.5% FFA; refiners in Rotterdam and Singapore purchase for downstream processing into food or HVO feedstock.
- Organic Oil:Certified seedstock from EU Regulation 2018/848-compliant rotations; limited crush capacity in France and Poland constrains supply expansion.
Refined oil handles the majority of throughput; cold-pressed oil is gaining share fastest on premium positioning.
Application:
Cost-tier differentiation separates commodity biofuel offtake from high-margin pharmaceutical and cosmetic grades, with HVO contracts compressing food-industry supply availability.
- Biofuels:Hydrotreated vegetable oil production consumes degummed oil meeting <0.02% phosphorus and <0.5% moisture specifications for catalyst protection. Neste, Diamond Green Diesel, and REG negotiate 3-5 year direct contracts with Canadian and European crush operators, bypassing traditional merchant intermediaries.
- Food Industry:High-oleic varieties (75%+ oleic acid) serve frying and bakery applications where oxidative stability extends fry-life cycles. German processors reformulate with these grades to meet retailer clean-label requirements.
- Cosmetics:Refined-bleached-deodorized oil with <0.1% moisture and peroxide values under 2 meq/kg supplies emollient formulations; certification to COSMOS or ECOCERT standards commands 25-35% premiums.
- Pharmaceuticals:Super-refined grades meeting Ph.Eur. or USP monographs for parenteral lipid emulsions; Health Canada's novel-food pathway delays omega-3 positioning claims in Canadian markets.
Food industry volumes dominate current offtake; biofuels application is expanding most quickly on policy-mandated demand.
End User:
Customer-type concentration shapes contract structures, with institutional buyers locking multiyear supply against spot-market exposure for smaller retail channels.
- Food Processors:Industrial bakeries and snack manufacturers in Germany, France, and the Netherlands contract for 12-24 month refined-oil supply with price-adjustment clauses tied to Rotterdam CIF benchmarks.
- Retail Chains:Supermarket private-label programs in Canada and the UK specify high-oleic or cold-pressed grades with ISCC EU chain-of-custody documentation for sustainability claims.
- Restaurants:Food-service distributors supply 10-20 liter jugs to independent operators; margin compression from biofuel-driven supply tighting forces inventory optimization.
- Manufacturers:Renewable diesel refiners and oleochemical plants purchase crude or degummed oil for downstream processing; pre-treatment capex requirements strain mid-sized processor balance sheets.
Food processors anchor contract volumes; manufacturers are climbing fastest on HVO integration timelines.
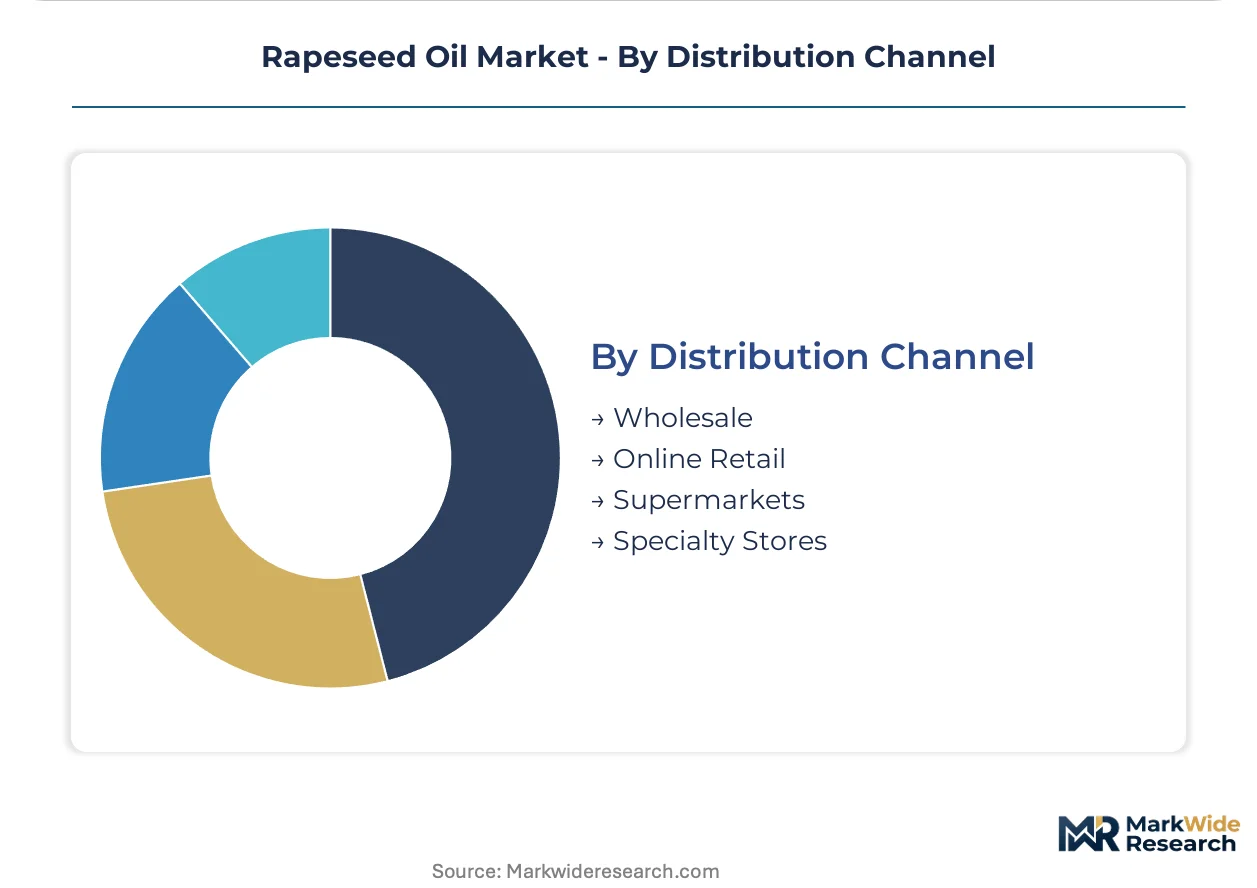
Distribution Channel:
Channel maturity stratifies between consolidated wholesale flows to industrial buyers and fragmented specialty retail serving premium segments.
- Wholesale:Bulk tanker and flexitank shipments from crush facilities to refiners and food manufacturers; Cargill's Prairie elevator network and Bunge's Rotterdam port capacity anchor North American and European origination.
- Supermarkets:Standardized 1-5 liter bottles of refined high-oleic oil; German and UK retailers drive clean-label SKU proliferation.
- Specialty Stores:Natural-foods independents and farm-shop networks in France's Burgundy and Canada's Manitoba stock cold-pressed organic grades at 2-3x refined-oil pricing.
- Online Retail:Direct-to-consumer subscriptions for artisanal cold-pressed oil; limited cold-chain infrastructure constrains geographic reach.
Wholesale channels move the bulk of volume; specialty stores are expanding most rapidly on premium segment fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany channels nearly half its rapeseed crush toward hydrotreated vegetable oil production, while France and Canada retain heavier food-industry tilts. This consumption-mix differential fragments procurement strategies and margin structures across major producing regions.
Germany
The KBA vehicle-type approval system accelerates renewable diesel offtake contracting from crush operators. EU Green Deal biofuel mandates bind transport-sector blending quotas, pulling seed oil away from edible applications. Crushing clusters in Hamburg and Magdeburg retrofit degumming lines to meet hydrotreater phosphorus specifications below 0.02%.
Canada
Export-oriented infrastructure in Alberta and Saskatchewan connects Prairie origination to Asian biofuel markets. Health Canada and the country's national pharmaceutical regulator enforce omega-3 labeling constraints that delay premium product launches. Elevator networks around Saskatoon and Regina deploy near-infrared spectroscopy for real-time oil-content grading.
France
Clean-label reformulation by industrial bakeries drives high-oleic rapeseed oil procurement from Burgundy and Champagne crush facilities. EU Regulation 2018/848 organic certification requirements constrain seedstock availability from compliant crop rotations. Artisanal cold-press operations in Burgundy supply specialty retail channels at 2-3x refined-oil pricing.
Netherlands
Port-adjacent crush capacity in Rotterdam serves as Europe's primary transshipment hub for Black Sea and Canadian seed oil. REACH and the EU F-Gas Regulation mandate 99.5% hexane recovery efficiency, requiring carbon-adsorption retrofits at solvent-extraction plants. Refiners cluster along the Rotterdam-Antwerp corridor to access hydrotreater feedstock markets.
Ukraine
Black Sea port disruptions force Mediterranean refiners to maintain costly buffer stocks against supply interruptions. The country's national agricultural regulator oversees export licensing for seed and oil shipments through Odesa corridor terminals. Crushing infrastructure concentrates in Dnipropetrovsk and Poltava regions with riverine access to port facilities.
Rapeseed Oil Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with origination scale and port-adjacent processing capacity determining competitive position. The upper tier controls elevator networks and crush facilities that anchor regional supply chains, while mid-sized operators compete on specialty grades and sustainability certification. Three archetypes dominate: integrated agribusinesses with origination-to-refiner networks, port-based processors with HVO feedstock specialization, and regional cold-press specialists serving premium edible channels. Capacity expansion and direct offtake contracting with renewable diesel refiners represent the dominant competitive moves, compressing traditional merchant intermediaries.
Among integrated agribusinesses, Cargill Incorporated, Bunge Limited, and Louis Dreyfus Company occupy positions defined by geographic origination strengths. Cargill exemplifies the Prairie-elevator-network archetype, anchoring North American seed flows through Saskatchewan and Alberta infrastructure. Bunge represents port-adjacent processing specialization, with Rotterdam and Hamburg facilities positioned for European biofuel feedstock delivery. Louis Dreyfus Company sits within the Black Sea origination tier, sustaining supplier relationships that feed Mediterranean refiners despite corridor volatility.
| Leading Market Players |
|---|
| Louis Dreyfus Company |
| Cullise Ltd. |
| Archer-Daniels-Midland Company |
| Ola Oils Limited |
| Interfat SA |
| Bunge Limited |
| Conagra Brands |
| Yorkshire Rapeseed Oil |
| Cargill Incorporated |
| Others |
Cost & Logistics Intelligence
ISCC EU and RSB sustainability certifications gate both biofuel contract eligibility and price differentiation across rapeseed oil tiers, forcing crush operators to absorb 12-18 month validation cycles before accessing premium HVO offtake streams. Buyers without certification face exclusion from Neste and Diamond Green Diesel procurement, compressing their pricing power against certified competitors.
Pricing Analysis
Long-term offtake contracts spanning 3-5 years dominate renewable diesel procurement, while food-service buyers rely on 12-24 month agreements with Rotterdam CIF benchmark adjustments. Price differentiation rests on phosphorus content below 0.02% for hydrotreater feedstock and organic certification under EU Regulation 2018/848. Cost compression in refined edible grades is intensifying because biofuel demand tightens seed oil availability. Food processors show highest price sensitivity, whereas renewable diesel refiners accept premiums for guaranteed supply.
Supply Chain Analysis
Strait of Hormuz transit vulnerability and Black Sea port disruptions expose Mediterranean refiners to supply interruptions, forcing costly buffer stock maintenance. Geographic concentration centers on Canada, Ukraine, and Germany for origination, with crush capacity clustering in Rotterdam and Hamburg corridors. Raw material dependencies include natural gas for solvent extraction, hexane for processing, and high-oleic seed varieties for premium food grades. Single-source vulnerability runs through Ukrainian export licensing controlled by the country's national agricultural regulator. Distribution runs through bulk tanker shipments to refiners, supplemented by flexitank routes for smaller food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The renewable diesel buildout represents a high-growth disruption reshaping rapeseed oil value capture, with EU Green Deal biofuel mandates creating dedicated demand streams that outpace traditional food applications.
For Market Incumbents: Consolidate origination infrastructure in the Canadian Prairies and Black Sea corridors to defend against merchant house disintermediation. Expand degumming capacity to meet hydrotreater phosphorus specifications below 0.02%, locking 3-5 year direct contracts with Neste and Diamond Green Diesel before specialty crushers capture niche premiums.
For New Entrants and Emerging Players: Lead with cold-pressed organic positioning in underpenetrated North American natural-foods channels where 40-60% premiums over refined grades sustain small-batch economics. Target Burgundy-style artisanal production in Manitoba and Saskatchewan, deploying skid-mounted expeller systems for traceable, low-temperature extraction with direct-to-consumer subscription models.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across HVO pre-treatment and degumming upgrades, favoring processors with balance sheet capacity to absorb carbon-adsorption retrofits for 99.5% hexane recovery compliance. Acquisition targets should display port-adjacent crush capacity with ISCC EU certification progress and existing renewable diesel offtake relationships. Watch for crush-margin volatility signals as biofuel policy outpaces food-demand growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Origination | Cargill's Prairie elevator network anchors North American supply security against Black Sea disruption. |
| HVO Feedstock Certification Investment | ISCC EU validation unlocks 3-5 year direct contracts with renewable diesel refiners bypassing merchants. |
| Cold-Press Capacity Fragmentation | Burgundy and Manitoba micro-crushers capture 2-3x refined-oil pricing in specialty retail channels. |
| Port-Adjacent Crush Expansion | Rotterdam and Hamburg facilities access EU biofuel mandates through KBA vehicle-type approval incentives. |
| Near-Infrared Grading Technology Deployment | Real-time oil-content assessment at Prairie elevators improves origination efficiency for export markets. |
Research Approach
A spread of perspectives from crush plant operators, renewable diesel refinery procurement heads, food-service distributors, and specialty retail buyers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EU customs data, ECHA REACH filings, and Canadian grain handling statistics. Bottom-up seed production estimates and top-down biofuel demand projections were triangulated against crush capacity utilization rates across the analysis window.
Segmentation dimensions modeled include product type (refined, cold-pressed, crude, organic), application (biofuels, food industry, cosmetics, pharmaceuticals), and end-user category (food processors, retail chains, restaurants, manufacturers). CAGRs were derived from supply-demand balance modeling incorporating crush-margin volatility and policy mandate trajectories. Industry-specific forecast inputs encompassed HVO capacity buildout timelines and EU Green Deal implementation pacing.
Forecasts assume regulatory continuity in EU Green Deal biofuel mandates and REACH hexane recovery standards; material policy shifts would require re-modeling demand trajectories. Black Sea export corridor stability and Health Canada novel-food approval timelines represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as renewable diesel refiner consolidation and certification timeline compression evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market