
 Africa Rice Market | 2026-2036
Africa Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Rice Market Outlook
Premium-grade parboiled rice is rotating toward dominance across African wholesale channels. Ultimate Rice Millers leverages backward integration into paddy sourcing to secure supply continuity during seasonal shortfalls. Big Bull Rice Mills anchors its position through specialized long-grain processing infrastructure concentrated in the Niger Delta corridor. Lakaji Farms differentiates via farm-to-retail traceability systems that command price premiums in urban Lagos and Abuja markets.
Rice is the seed of the grass species Oryza sativa, typically milled to remove hull and bran layers, with final moisture content standardized between twelve and fourteen percent for tropical storage stability. Its primary commercial purpose centers on caloric provision for human diets and as an input substrate for processed food manufacturing. Long grain varieties dominate export-oriented volume pools, while specialty rice segments capture concentrated margin in diaspora-directed channels. Local markets and wholesale distribution together handle the majority of throughput, though supermarket penetration is accelerating in South African and Kenyan metros.
Nigeria's National Agency for Food and Drug Administration and Control enforces mandatory fortification standards that reshape milling equipment requirements across West Africa. Egypt's Agriculture Ministry and the country's plant quarantine authority regulate varietal approval and cross-border seed movement, directly constraining market access timelines. Stakeholders must monitor how harmonized seed certification frameworks under the African Continental Free Trade Area reshape competitive positioning between established Sahelian suppliers and emerging East African producers.
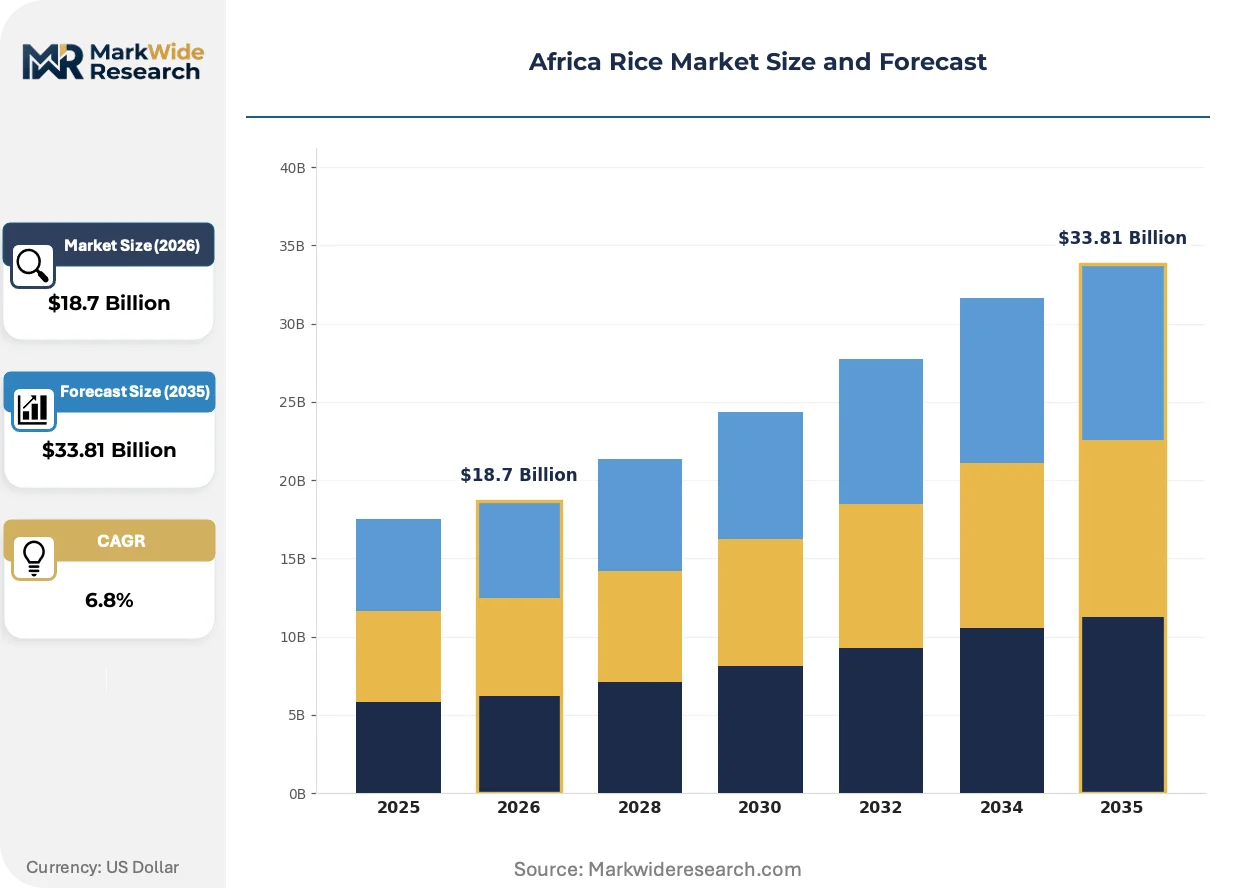
Market Dynamics
Urban household consumption in West African cities is compressing traditional wholesale channels and forcing millers to reconfigure distribution toward supermarket and e-commerce fulfillment models.
Growth Catalysts
- Nigeria's food fortification mandate:Mandatory micronutrient standards under NAFDAC are retrofitting milling infrastructure and creating certified supply tiers that command urban price premiums.
- Seed certification protocols:Harmonized frameworks under the African Continental Free Trade Area are accelerating varietal registration and cross-border seed movement for commercial farms.
- Irrigated acreage expansion:Egypt's Nile Delta and Nigeria's Niger Valley are converting rain-fed plots to controlled water systems, stabilizing paddy yields against monsoon variability.
Market Restraints
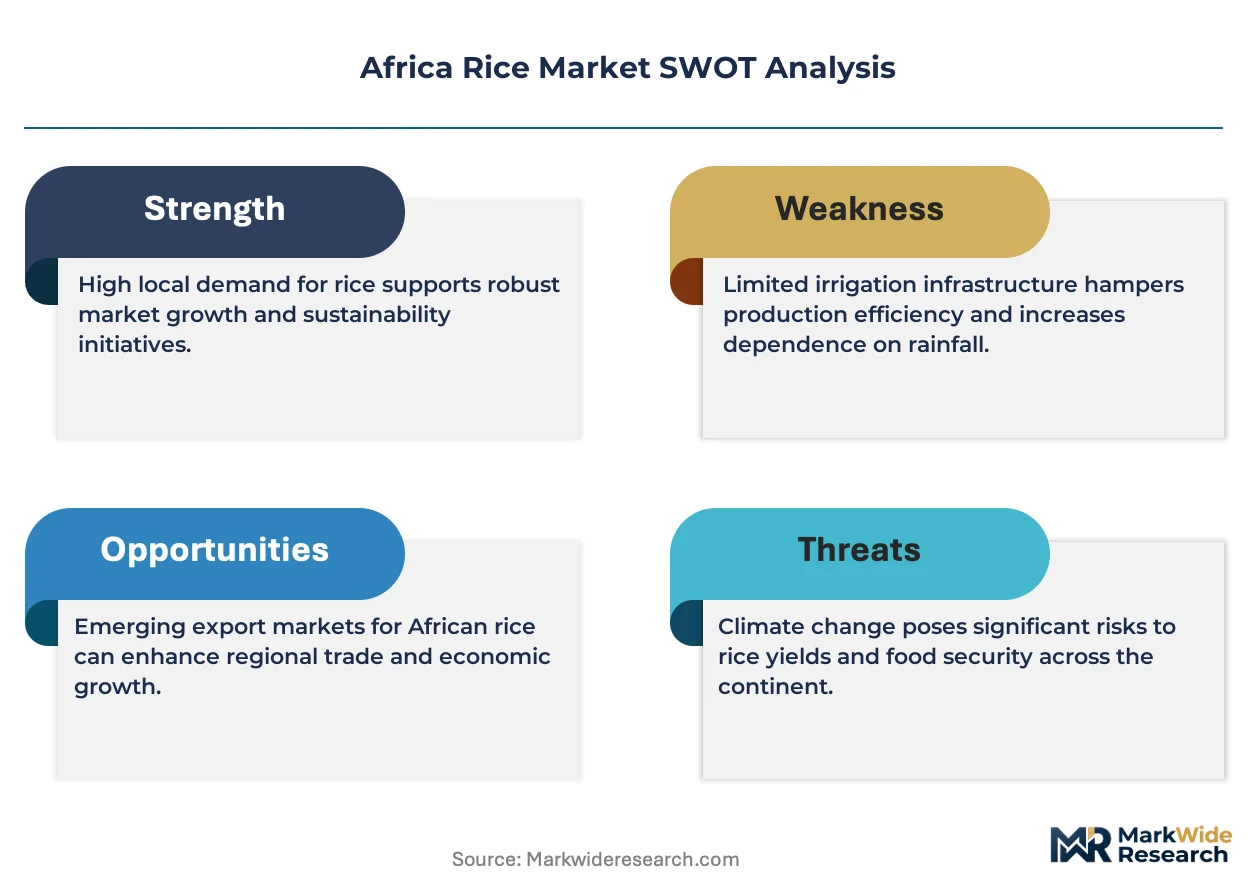
- Input cost volatility:Fertilizer and diesel prices swing with global energy markets, squeezing margins for rain-dependent smallholders who lack forward-contracting capacity.
- Supply concentration risk:Milling capacity clusters in the Niger Delta corridor and Greater Cairo, creating bottlenecks when seasonal flooding or currency crises disrupt logistics.
- Technical limitation:Post-harvest loss rates remain elevated due to inadequate drying and storage infrastructure at the farm-gate level across Sahelian production zones.
Strategic Opportunities
- Underpenetrated East African markets:Tanzania and Ethiopia exhibit per-capita consumption gaps against West African benchmarks, offering volume expansion for regional traders.
- Farm-to-retail traceability systems:Blockchain-enabled provenance tracking is capturing price premiums in Lagos and Abuja supermarket channels.
- Supermarket penetration acceleration:South African and Kenyan retail chains are consolidating procurement, creating dedicated supplier tiers for private-label rice.
Industry Challenges
- Certification timeline compression:NAFDAC fortification compliance and AfCFTA seed registration are running on overlapping deadlines, straining miller administrative capacity.
- Skill gaps in precision agriculture:Irrigated farm expansion outpaces agronomist availability for water management and integrated pest control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Rice Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Grain, Medium Grain, Short Grain, Specialty Rice End Use: Food Processing, Household Consumption, Export, Animal Feed Distribution Channel: Online Retail, Supermarkets, Wholesale, Local Markets Packaging Type: Bags, Jute, Vacuum Sealed, Pouches |
| Companies Covered | Ultimate Rice Millers, Big Bull Rice Mills, Lakaji Farms, Beloxxim Sa, Obasanjo Farms, Elephant Rice Mills, Fellour Rice Mills, Rizwan Rice Mills, Golden Penny Rice, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Rice Market Strategic Shifts
Processing technology and distribution infrastructure are converging to reshape how African rice moves from paddy to consumer, with digitization and regulatory alignment as the dominant vectors.
Mechanized parboiling systems are replacing traditional soaking and steaming methods. Large-scale millers in the Niger Delta corridor are adopting continuous-flow steamers that reduce energy consumption and standardize grain quality. This equipment is miniaturizing to serve mid-capacity processors, enabling tier-two millers to achieve export-grade output without full-scale infrastructure investment.
Egypt's plant quarantine authority and agriculture ministry are tightening varietal approval timelines for imported seed stocks. The regulatory friction is redirecting investment toward domestic breeding programs and shortening the lag between trial and commercial release. West African seed distributors are responding by establishing in-country multiplication facilities rather than relying on direct importation.
Urban consumers in Lagos, Abuja, and Accra are shifting toward packaged branded rice over open-market bulk purchases. Supermarket chains and e-commerce platforms are capturing this transition through subscription delivery models and loyalty programs. The behavioral pivot is most visible in Nigeria's federal capital territory, where dual-income households prioritize convenience and fortification certification over per-kilogram price minimization.
Africa Rice Market Segmentation
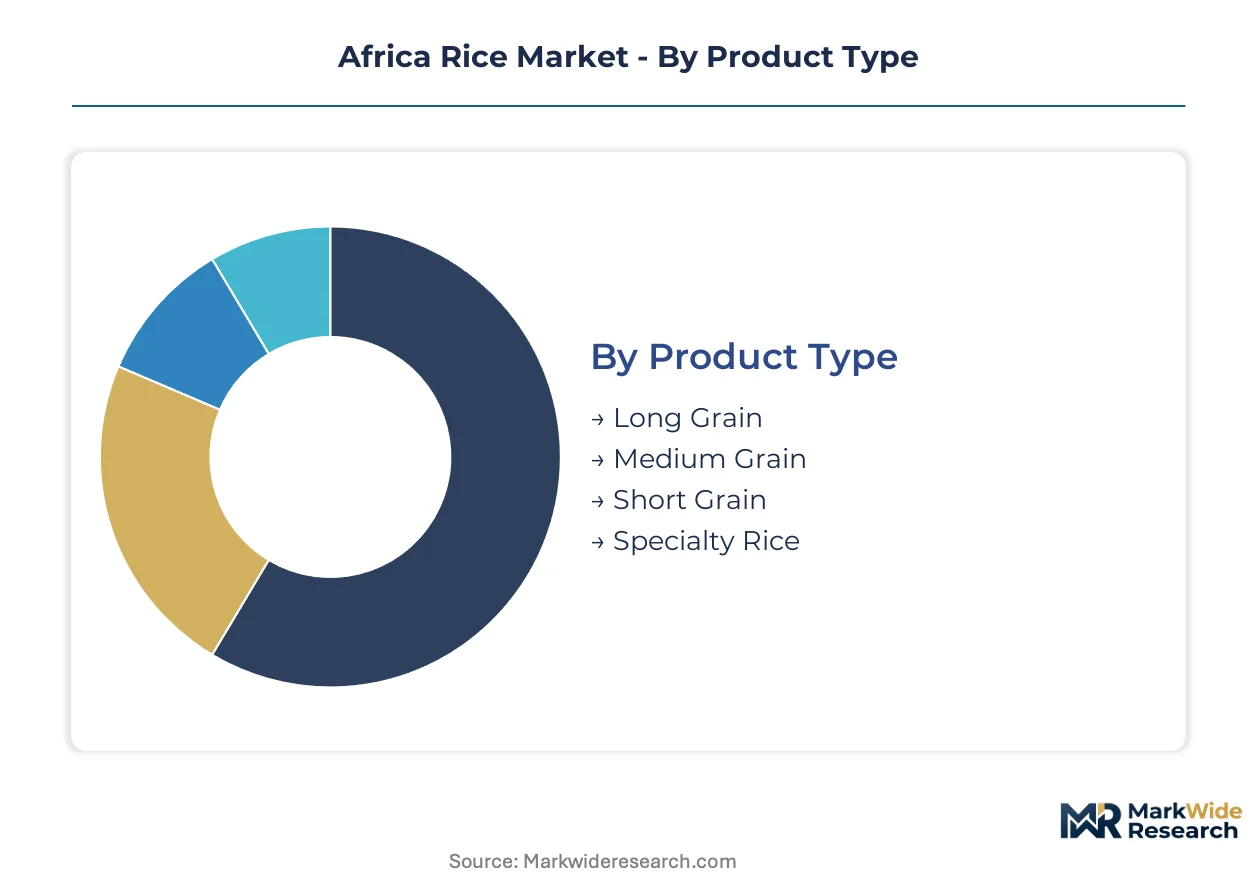
Rice markets fragment along grain morphology, end-use application, and channel infrastructure. Each segmentation axis reveals distinct margin structures and regulatory exposure across African production zones.
Product Type:
Substitution pressure from wheat and cassava starches hits short grain hardest in urban West African diets, while long grain maintains institutional lock-in through parboiling infrastructure.
- Long Grain:Slender kernels with length-to-width ratios exceeding 3:1 dominate Nigerian and Egyptian milling output. Demand concentrates in Lagos and Abuja household channels where NAFDAC fortification mandates favor standardized grain dimensions for optical sorting compliance.
- Specialty Rice:Aromatic and pigmented varieties command diaspora-directed premiums in European and North American export channels. Supply concentrates in Côte d'Ivoire's forest zones and Madagascar's highlands where terroir-linked branding supports price differentiation.
- Medium Grain:Plump, rounded kernels suit Egyptian koshari and West African jollof preparations. Procurement runs through institutional catering contracts in Cairo and Dakar.
- Short Grain:Sticky texture profile limits adoption outside East African communities and specific ceremonial applications. Local markets in Tanzania and Ethiopia handle residual volume.
Long grain anchors the volume base while specialty rice gains share at the steepest rate.
End Use:
Cost tier stratification separates caloric-commodity applications from value-added processing, with export channels facing the steepest certification burdens.
- Household Consumption:Direct human consumption absorbs the majority of milled output across Nigerian and Egyptian markets. Urban Lagos and Abuja households drive uptake of packaged, fortified grades through supermarket and e-commerce channels.
- Food Processing:Breweries, confectioners, and extruded snack manufacturers utilize broken rice and starch fractions. Demand concentrates in South African and Kenyan industrial zones where formal sector procurement standards apply.
- Export:Parboiled long grain moves through Lagos and Port Harcourt terminals toward diaspora markets. Plant quarantine protocols in destination jurisdictions constrain varietal eligibility and residue limits.
- Animal Feed:Rice bran and polishing residues supply poultry and aquaculture operations in the Niger Delta and Nile Delta corridors. Price linkage to maize and soybean meal determines substitution elasticity.
Household consumption anchors the volume base while food processing climbs the fastest as industrialization deepens.
Distribution Channel:
Volume concentration in traditional wholesale channels is accelerating toward formal retail as urban household purchasing patterns shift.
- Local Markets:Open-air trading in Nigerian and Ghanaian urban centers handles unpackaged bulk rice. Price transparency and immediate availability sustain penetration among price-sensitive consumers.
- Supermarkets:South African chains and Nigerian retail consolidators are capturing branded rice volume through private-label programs. Loyalty programs and subscription delivery entrench repeat purchase in Lagos and Nairobi metros.
- Wholesale:Aggregator networks in the Niger Delta corridor and Greater Cairo supply institutional buyers and regional redistributors. Seasonal liquidity constraints and currency volatility strain working capital requirements.
- Online Retail:E-commerce platforms in Nigeria and Kenya are building dedicated grocery logistics for packaged rice. Last-mile cost structures limit penetration outside dense urban cores.
Local markets anchor the volume base while online retail expands most quickly from minimal base.
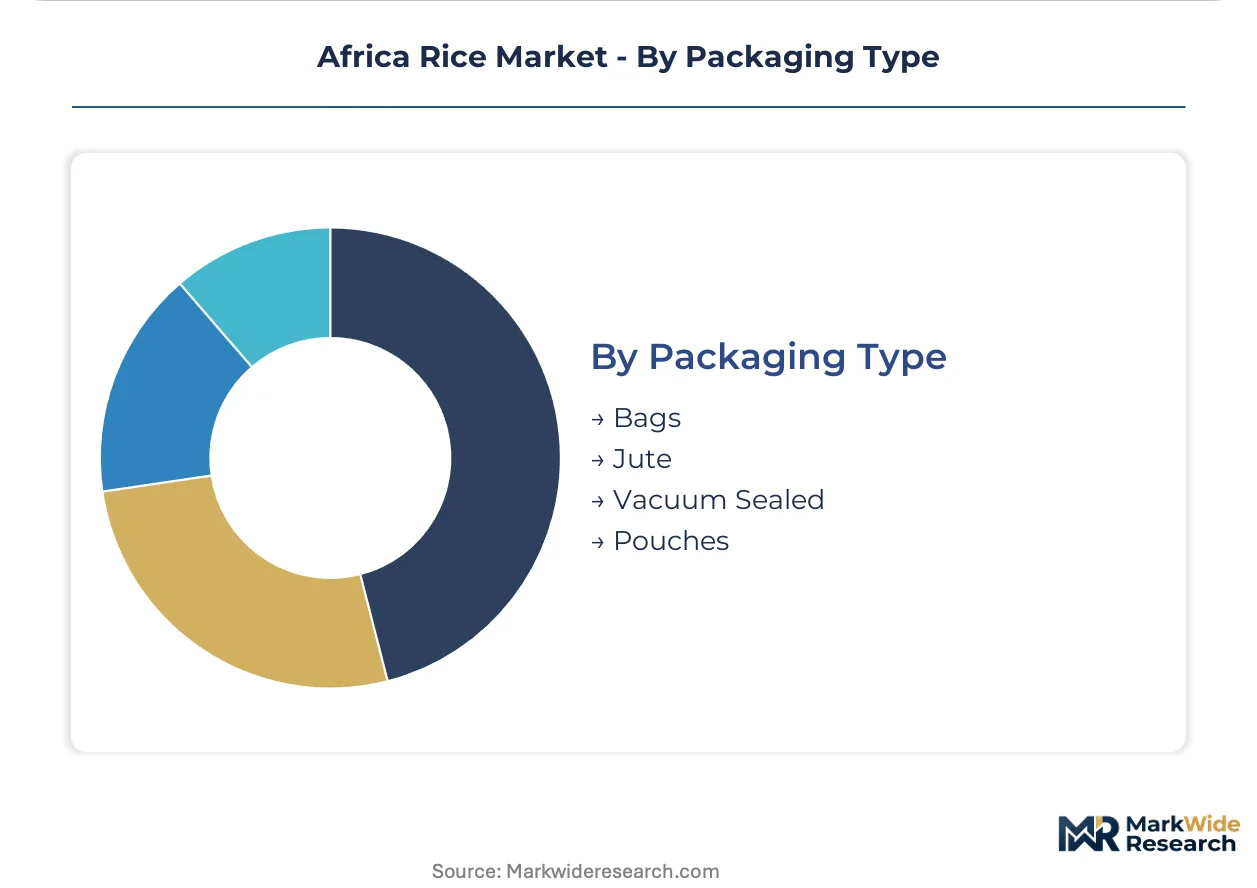
Packaging Type:
Margin structure varies sharply by material cost and shelf-life extension capability, with vacuum technology capturing premium positioning.
- Bags:Woven polypropylene dominates mass-market distribution across West African wholesale channels. Unit economics favor 25kg and 50kg formats for household stocking and institutional procurement.
- Vacuum Sealed:Oxygen-exclusion packaging extends storage stability to 24 months in tropical humidity conditions. Urban Lagos and Abuja supermarkets command price premiums for fortified, long-grain grades in this format.
- Pouches:Laminated plastic films serve single-family and trial-size positioning in Kenyan and South African retail. Convenience positioning targets dual-income urban households.
- Jute:Natural fiber packaging persists in export-oriented and heritage-positioned segments. Regulatory friction in destination markets limits growth trajectory.
Bags anchor the volume base while vacuum sealed gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Africa's rice trade deficit shapes regional production incentives. Import substitution drives government-backed irrigation investments across West and East African production zones. National food security mandates accelerate varietal registration and milling capacity expansion in key consumption centers.
Nigeria
Lagos and Abuja urban households absorb fortified parboiled grades through supermarket channels. NAFDAC enforces micronutrient standards that retrofit milling equipment across the Niger Delta corridor. Kano and Kebbi states anchor paddy supply through federal anchor-borrower programs targeting rain-fed to irrigated conversion.
Egypt
Nile Delta controlled-water systems stabilize yields for export-oriented long-grain production. The Agriculture Ministry and plant quarantine authority regulate varietal approval timelines for imported seed stocks. Greater Cairo milling clusters process Delta paddy for Middle Eastern and European diaspora markets.
Côte d'Ivoire
Forest zone terroir supports aromatic and pigmented specialty varieties for premium export channels. National agricultural investment programs rehabilitate colonial irrigation schemes in the Bandama River basin. Abidjan port infrastructure handles regional re-export toward landlocked Sahelian markets.
Tanzania
Per-capita consumption gaps against West African benchmarks attract regional trader expansion. The national agricultural regulator oversees seed certification alignment with AfCFTA harmonization protocols. Morogoro and Mwanza production zones develop milling capacity for domestic urban and cross-border East African supply.
Ethiopia
State-led commercial farm development targets self-sufficiency in irrigated lowland areas. Federal agricultural transformation initiatives standardize post-harvest handling and storage infrastructure. The Awash Valley concentration hosts integrated paddy-to-milling operations for Addis Ababa institutional procurement.
Africa Rice Market Competitive Environment
Concentration sits with integrated millers controlling upstream paddy supply and downstream distribution networks. The competitive structure tiers between large-scale processors with parboiling infrastructure and mid-capacity specialists serving regional wholesale channels. Three archetypes dominate: backward-integrated millers securing supply continuity, equipment-heavy processors leveraging optical sorting compliance, and farm-to-retail traceability operators capturing urban premiums. Capacity expansion and certification-tier differentiation constitute the dominant competitive moves as fortification mandates reshape equipment requirements.
Among Nigeria-based integrated operators, Ultimate Rice Millers exemplifies supply-chain control through captive paddy sourcing, while Big Bull Rice Mills anchors large-scale processing infrastructure in the Niger Delta corridor. Lakaji Farms occupies a position within the traceability-specialist tier, commanding price premiums through farm-to-retail systems in Lagos and Abuja supermarket channels.
| Leading Market Players |
|---|
| Ultimate Rice Millers |
| Big Bull Rice Mills |
| Lakaji Farms |
| Beloxxim Sa |
| Obasanjo Farms |
| Elephant Rice Mills |
| Fellour Rice Mills |
| Rizwan Rice Mills |
| Golden Penny Rice |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Niger Delta parboiling clusters shapes both supply concentration and price floors for West African rice. Large-scale millers achieve optical-sorting economies that mid-cap processors cannot match, forcing tier-two operators toward specialty grades or geographic niches to escape commoditization pressure.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in African rice markets. Price differentiation hinges on NAFDAC fortification certification and volume scale, with certified supply tiers commanding urban premiums in Lagos and Abuja. Cost compression in economy grades is intensifying because fertilizer and diesel input volatility squeezes rain-dependent smallholder margins. Open-market bulk buyers exhibit highest price sensitivity, while supermarket procurement officers prioritize traceability and certification compliance over per-kilogram minimization.
Supply Chain Analysis
Inventory cycles at Lagos and Port Harcourt terminals compress to six-to-eight weeks during harvest peaks, stretching to fourteen weeks when seasonal flooding disrupts Niger Valley logistics. Geographic supply concentration centers on Nigeria, Egypt, and Côte d'Ivoire, with paddy sourcing drawing from rain-fed Sahelian zones and controlled-water Delta systems. Raw material dependencies include fertilizer imports, diesel for mechanized drying, and polypropylene packaging resins. Single-source vulnerability concentrates in the Niger Delta milling corridor, where currency crises and seasonal flooding create simultaneous logistics and working capital bottlenecks. Distribution runs through wholesale aggregator networks supplying institutional buyers and regional redistributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's rice market rewards defensive moats built on regulatory entrenchment. NAFDAC fortification mandates and AfCFTA seed certification protocols create switching costs that lock in compliant millers while excluding informal processors from formal retail channels.
For Market Incumbents: Fortify supply continuity through backward integration into irrigated paddy sourcing in Kano and Kebbi states. Invest in continuous-flow parboiling equipment to maintain optical-sorting compliance advantages as NAFDAC tightens micronutrient enforcement. Channel control through exclusive supermarket supply agreements in Lagos and Abuja protects margin against emerging traceability-specialist competitors.
For New Entrants and Emerging Players: Anchor in Tanzania and Ethiopia per-capita consumption gaps against West African benchmarks. Target Morogoro and Mwanza production zones where milling capacity lags demand growth and AfCFTA harmonization accelerates cross-border seed movement. A farm-to-retail traceability go-to-market angle captures price premiums in Nairobi and Dar es Salaam supermarket channels without requiring full-scale parboiling infrastructure.
For Investors and Strategic Acquirers: Mid-cap processors with regional wholesale lock-in but underutilized equipment represent the most defensible acquisition archetype. Long-term viability across a five-to-ten year window hinges on irrigation conversion rates and regulatory compliance tier consolidation. Watch for inflection when AfCFTA seed certification timelines compress varietal registration from multi-year to single-year cycles, accelerating competitive shakeout between compliant and non-compliant millers.
| Strategic Initiative | Industry Significance |
|---|---|
| Irrigated Acreage Conversion | Federal anchor-borrower programs in Kano and Kebbi reduce monsoon dependency for paddy supply security. |
| NAFDAC Certification Investment | Micronutrient fortification compliance creates supermarket procurement eligibility and price tier separation. |
| Backward Integration into Paddy | Captive sourcing through Niger Valley irrigation schemes insulates margin from seasonal spot market volatility. |
| Traceability System Deployment | Blockchain-enabled provenance tracking commands urban premiums in Lagos and Abuja retail channels. |
| Regional Wholesale Network Consolidation | Aggregator acquisition in Greater Cairo and Niger Delta corridors builds distribution moats against new entrants. |
Study Parameters
A standing panel of mill operations directors, seed certification officers, supermarket category buyers, and agricultural extension agents provided ongoing calibration throughout this study. Primary interviews with these stakeholders combined with secondary validation against customs records, national agricultural ministry statistics, and AfCFTA harmonization protocol documents. Bottom-up paddy production estimates and top-down consumption surveys were triangulated to establish market sizing consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across grain morphology, end-use application, distribution channel infrastructure, and packaging technology tiers. CAGRs were derived from regression analysis of historical consumption patterns against urbanization rates and irrigation investment flows. Key forecast inputs included diesel price volatility scenarios and NAFDAC enforcement intensity assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued federal irrigation subsidy assumptions; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
United Kingdom Commercial Greenhouse Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Palm Kernel Expeller Market