
 Livestock and Meat Market | 2026-2036
Livestock and Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Livestock and Meat Market Foresight
REACH is repositioning chemical and veterinary residue thresholds for imported meat across European supply chains. Tyson Foods leverages its vertically integrated poultry operations to sustain margin control from feed milling through retail distribution. JBS anchors its competitive footprint through beef processing scale across North and South American facilities. Cargill competes via grain-trading integration that secures captive feedstock for livestock finishing operations.
Livestock and meat encompasses the commercial production, slaughter, and preparation of animal protein for human consumption, involving carcass yields typically graded by fat cover, marbling score, and lean maturity to determine culinary suitability and pricing tiers. The primary industrial purpose centers on converting feed energy into edible protein through managed breeding, nutrition science, and controlled-environment finishing systems. Poultry leads volume throughput due to feed conversion efficiency and shorter production cycles, while fresh processing commands premium positioning in retail and food service channels. Cured and processed segments concentrate margin pools where shelf-stable formats reduce cold-chain dependency and extend geographic reach.
The USDA enforces pathogen reduction and Hazard Analysis Critical Control Point standards that govern slaughter facility design and microbial testing protocols. The EU Green Deal and Farm to Fork Strategy mandate methane emissions tracking and antibiotic-use reductions that reshape herd management economics. Brazil's MAPA and Australia's DAWE administer export certification regimes that determine market access eligibility for third-country trade. Stakeholders must monitor divergence between regional sustainability mandates and the capital requirements for compliance-aligned facility retrofits.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing production timelines for livestock operators while simultaneously demanding capital-intensive methane abatement retrofits. This regulatory pressure layer compounds with feed cost volatility to reshape herd economics across major exporting regions.
Growth Catalysts
- REACH residue protocols:ECHA's tightening veterinary threshold standards for imported meat are accelerating compliance investments among third-country exporters seeking European market access.
- Cellular agriculture R&D:Cultivated protein bioreactor technology is drawing venture capital into hybrid product pipelines that blend conventional and novel protein formats.
- Brazil-Argentina-Australia export concentration:Grass-fed and grain-finished beef demand from Asian food service operators is pulling disproportionate volume through these three supply origins.
Market Restraints
- Soybean-meal price volatility:Feed input cost swings compress finishing margins for integrated poultry and pork operations dependent on South American crop cycles.
- Slaughter capacity concentration:Brazil and the United States together control disproportionate share of global beef processing infrastructure, creating bottleneck risk during trade disruption.
- Antibiotic reduction mandates:EU and emerging market regulatory convergence on growth-promoter bans forces herd health management transitions that elevate mortality rates during adaptation periods.
Strategic Opportunities
- Carbon credit monetization:Australia's Emissions Reduction Fund and similar mechanisms in New Zealand reward methane-capture investments with tradeable offset revenue streams.
- Cold-chain bypass formats:Shelf-stable cured and processed segments reduce logistics dependency and extend geographic reach into infrastructure-constrained markets.
- Precision livestock monitoring:Sensor-based health tracking converging with AI-driven feed optimization is opening margin recovery pathways for mid-scale operators.
Industry Challenges
- Veterinary epidemiology expertise scarcity:African swine fever and avian influenza surveillance demands outpace trained field diagnostician availability in major production zones.
- Facility retrofit capex burdens:EU-aligned environmental compliance requires anaerobic digester installation and manure management system overhauls that strain balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Livestock and Meat Market |
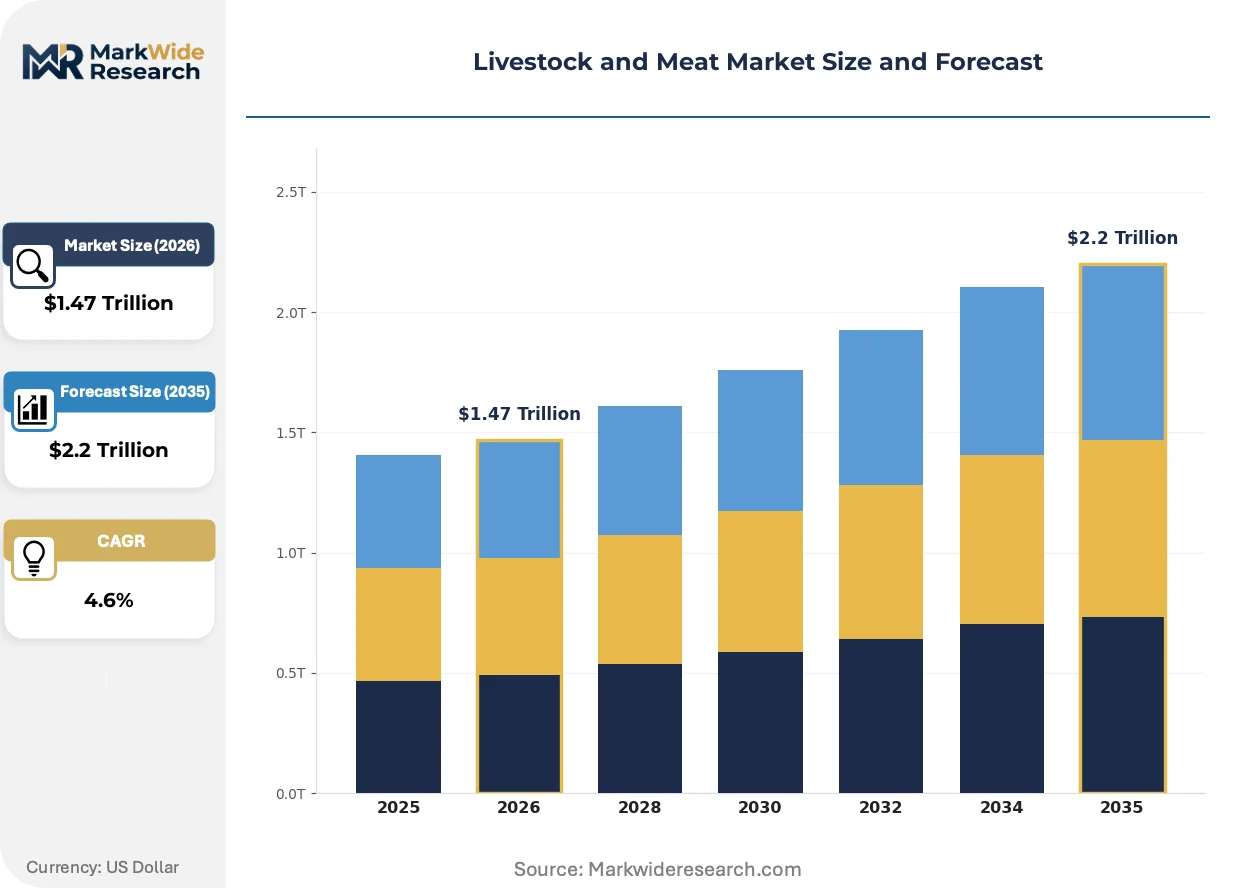
| Market Size in 2026 | $1.47 Trillion |
| Market Size in 2035 | $2.2 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cattle, Poultry, Swine, Sheep Distribution Channel: Wholesale, Retail, Online, Direct Sales End User: Food Service, Retailers, Exporters, Processors Processing Method: Fresh, Frozen, Cured, Processed |
| Companies Covered | Tyson Foods, JBS, Cargill, Smithfield Foods, Hormel Foods, Marfrig, Danish Crown, BRF, Minerva Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Livestock and Meat Market Shifts & Advancements
Digital traceability infrastructure and alternative protein manufacturing are compressing traditional livestock value chains while regulatory sustainability mandates force operational recalibration. These forces operate on different timelines but converge on the same capital allocation decisions facing incumbents.
Blockchain-enabled provenance tracking is decentralizing supply chain verification away from centralized certifying bodies toward distributed ledger architectures. Major European retailers and Asian e-commerce platforms are piloting farm-to-fork transparency systems that bypass legacy paper-based documentation. This shift is decentralizing audit authority and compressing the value capture historically held by third-party certification agencies.
REACH and the EU Green Deal's methane reporting requirements are forcing real-time emissions monitoring into standard operating practice. Slaughter facilities must now install continuous measurement equipment and submit verified data to national environmental regulators. Beef feedlot operators in Ireland and Denmark face the steepest compliance curves due to concentrated herd densities and proximity to urban monitoring networks.
Food service procurement teams are consolidating supplier relationships around vertically integrated protein providers capable of certifying full chain-of-custody documentation. This buyer concentration is displacing fragmented spot-market purchasing that historically characterized restaurant and hospitality sourcing. The shift is most visible across Asia-Pacific markets where cloud kitchen expansion demands predictable volume commitments and standardized quality specifications.
Livestock and Meat Market Segmentation
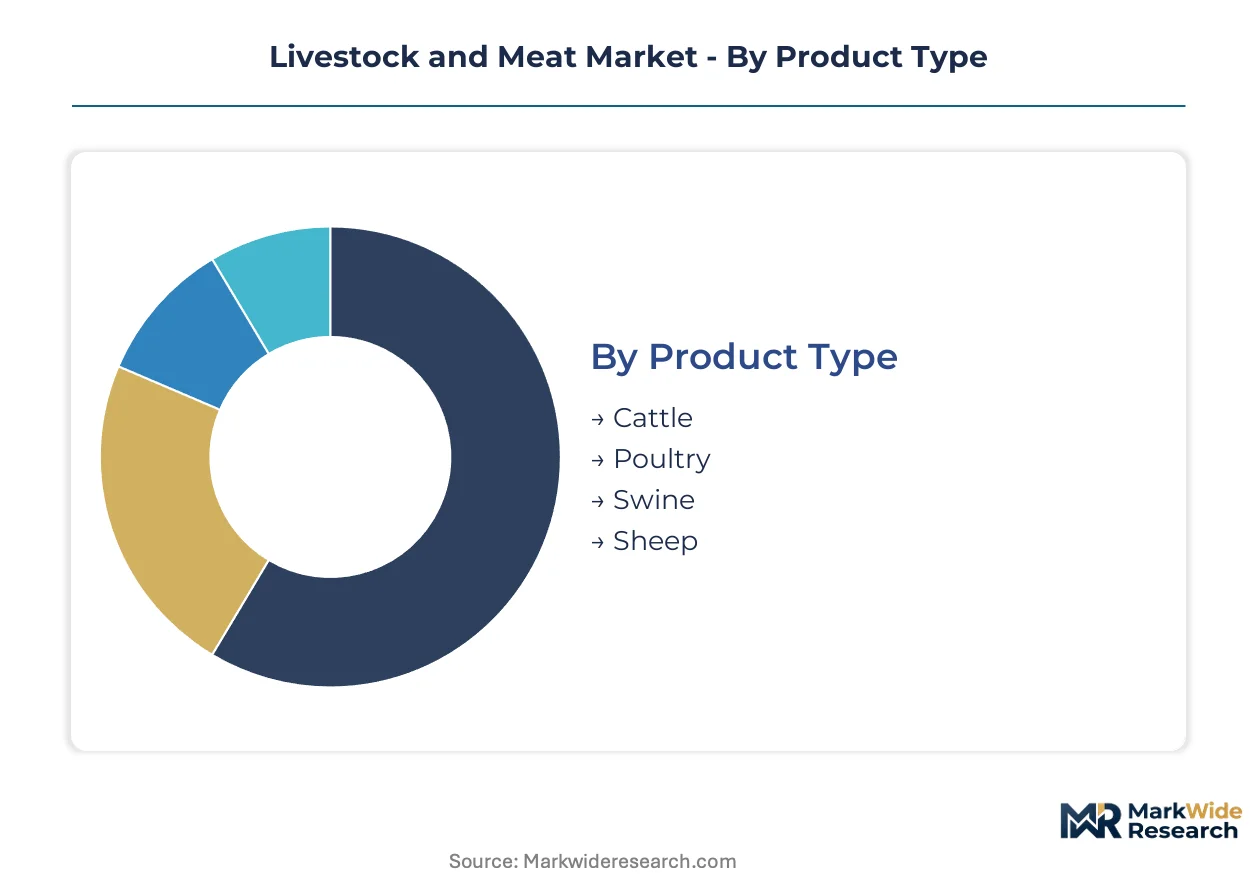
Livestock and meat segmentation reflects divergent feed conversion economics, cold-chain infrastructure maturity, and buyer procurement sophistication across protein categories. Channel and processing distinctions determine margin capture, shelf-life extension, and geographic reach for operators navigating regulatory compliance and input cost volatility.
Product Type:
Buyers prioritize feed efficiency ratios and production cycle duration when allocating procurement budgets across protein categories.
- Cattle:Grass-fed and grain-finished beef grades command premium positioning in food service channels, with Australian and Brazilian export certification regimes determining Asian market access eligibility. Herd management economics face compression from methane abatement mandates under the EU Green Deal's Farm to Fork Strategy.
- Poultry:Broiler operations achieve the shortest feed-to-protein conversion cycles in commercial livestock, driving volume concentration in vertically integrated operations from feed milling through retail distribution. Tyson Foods leverages this efficiency to sustain margin control across North American supply chains.
- Swine:Pork production clusters in grain-proximate regions with access to soybean-meal supply chains; African swine fever surveillance demands strain veterinary field capacity in major Asian production zones.
- Sheep:Lamb and mutton serve niche protein demand in Middle Eastern and Mediterranean culinary traditions, with New Zealand's Emissions Reduction Fund creating carbon credit revenue streams for methane-capture investments.
Volume sits with Poultry; growth tilts toward Cattle.
Distribution Channel:
Cold-chain reliability and buyer consolidation patterns reshape channel economics for protein suppliers.
- Wholesale:Consolidated procurement by food service operators and processors demands standardized carcass grading and predictable volume commitments, displacing fragmented spot-market purchasing across Asia-Pacific cloud kitchen expansion.
- Retail:Supermarket chains and hypermarkets require blockchain-enabled provenance documentation to satisfy ECHA-aligned residue threshold compliance and consumer transparency expectations.
- Online:E-commerce platforms pilot farm-to-fork traceability systems that bypass legacy paper-based certification, decentralizing audit authority toward distributed ledger architectures.
- Direct Sales:Producer-to-consumer relationships concentrate in premium grass-fed and organic segments where certification premiums offset logistics complexity.
Wholesale dominates throughput; Online expands most quickly.
End User:
Procurement sophistication and documentation requirements differentiate buyer segments.
- Food Service:Restaurant and hospitality operators consolidate supplier relationships around vertically integrated providers capable of certifying full chain-of-custody documentation, with Asia-Pacific markets leading this concentration shift.
- Retailers:European supermarket chains enforce REACH-aligned veterinary residue protocols that accelerate compliance investments among third-country exporters seeking shelf access.
- Exporters:Brazil's MAPA and Australia's DAWE administer certification regimes that determine market eligibility for grass-fed and grain-finished beef entering Asian trade corridors.
- Processors:Slaughter and further-processing facilities face capital-intensive retrofit requirements for anaerobic digester installation and continuous methane monitoring equipment under EU environmental mandates.
Food Service commands volume share; Processors face steepest compliance investment curves.
Processing Method:
Shelf-life extension and logistics dependency determine processing method selection.
- Fresh:Chilled carcass and primal cuts command premium positioning in retail and food service channels where culinary quality specifications justify cold-chain expenditure.
- Frozen:Blast-frozen protein extends geographic reach into infrastructure-constrained markets, with Brazilian and U.S. beef processing infrastructure supporting intercontinental trade flows.
- Cured:Shelf-stable formats reduce logistics dependency and cold-chain capital requirements, opening margin pools in emerging markets with limited refrigeration penetration.
- Processed:Value-added segments concentrate margin pools where formulation expertise and brand positioning offset commodity protein price exposure.
Fresh captures value concentration; Cured gains share fastest in infrastructure-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export processing zones in Brazil's Paraná and São Paulo states concentrate beef and poultry slaughter capacity, attracting capital from multinational traders seeking duty-advantaged access to Asian markets.
Brazil
Asian food service procurement teams source disproportionate volumes of grass-fed and grain-finished beef from Brazilian facilities. MAPA's export certification regimes determine eligibility for third-country trade corridors. São Paulo's industrial belt anchors JBS and Marfrig processing complexes that channel protein through Santos port infrastructure.
United States
Vertically integrated poultry operations sustain margin control from feed milling through retail distribution. USDA enforces pathogen reduction and HACCP standards governing slaughter facility design and microbial testing protocols. Arkansas and Georgia processing clusters concentrate Tyson Foods capacity serving domestic and export channels.
Australia
Grass-fed beef demand from East Asian markets pulls volume through Queensland and New South Wales production zones. DAWE administers export certification determining market access eligibility. The Emissions Reduction Fund creates carbon credit revenue streams for methane-capture investments in feedlot operations near Brisbane.
China
Domestic pork production clusters in Sichuan and Henan provinces face African swine fever surveillance demands that strain veterinary field capacity. SAMR oversees food safety standards for imported protein entering coastal consumption centers. Yangtze River Delta cold-chain infrastructure supports premium fresh meat distribution into Shanghai food service networks.
Germany
EU Green Deal methane abatement mandates force capital-intensive retrofit investments across Lower Saxony pork operations. ECHA's REACH protocols tighten veterinary residue thresholds for imported meat. North Rhine-Westphalia processing facilities face steepest compliance curves due to concentrated herd densities and proximity to urban monitoring networks.
Livestock and Meat Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across protein categories, creating tiered competitive dynamics. The vendor base organizes around three strategic archetypes: grain-trading integrated livestock finishers, vertically controlled poultry operators, and export-certified beef processors. Scale concentration in Brazil and the United States creates bottleneck risk during trade disruption. Competitive moves center on backward integration into feedstock supply and cold-chain infrastructure expansion.
Within the diversified conglomerate tier, Cargill exemplifies grain-trading integration that secures captive feedstock for livestock finishing operations. Tyson Foods occupies a position representing vertically controlled poultry operations sustaining margin control from feed milling through retail distribution. JBS anchors the export-certified beef processor archetype through processing scale across North and South American facilities. These three players represent distinct strategic postures rather than interchangeable competitive positioning.
| Leading Market Players |
|---|
| Tyson Foods |
| JBS |
| Cargill |
| Smithfield Foods |
| Hormel Foods |
| Marfrig |
| Danish Crown |
| BRF |
| Minerva Foods |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between EU Green Deal-compliant operations and conventional export facilities creates divergent margin structures across Brazilian, Australian, and U.S. supply corridors. Premium positioning accrues to operators capturing methane-abatement documentation and REACH-aligned residue protocols, while spot-market participants absorb feed-cost volatility without price-recovery mechanisms.
Pricing Analysis
Short-lead-time premiums attach to chilled carcass deliveries into Asia-Pacific food service networks, while frozen inventory trades at discounts reflecting cold-chain capital costs and inventory carry. Three-tier pricing structure across premium grass-fed, standard grain-finished, and economy frozen tiers tracks certification grade and volume commitment scale. Pricing pressure stems from soybean-meal input cost swings compressing poultry and pork finishing margins. Food service operators demonstrate lowest price sensitivity due to menu-price pass-through capacity; spot-market traders exhibit highest sensitivity to carcass-grade arbitrage opportunities.
Supply Chain Analysis
Export certification gating through Brazil's MAPA, Australia's DAWE, and USDA protocols concentrates supply authority among accredited slaughter facilities in São Paulo, Queensland, and Nebraska-Iowa corridors. Raw material dependencies center on South American soybean-meal supply, North American corn feedstock, and Australian pasture grazing capacity. Single-source vulnerability runs through Brazil-U.S. beef processing infrastructure concentration, creating bottleneck exposure during trade corridor disruption. Distribution runs through vertically integrated cold-chain networks serving retail and food service channels, with e-commerce platforms piloting direct-farm traceability bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slaughter capacity concentration across Brazilian and U.S. processing zones props pricing power for accredited exporters, constraining volume availability for non-integrated buyers.
For Market Incumbents: Lock in feedstock supply through backward integration into grain-trading operations or long-term offtake agreements with South American crop processors. Secure EU Green Deal compliance certification ahead of Farm to Fork Strategy enforcement timelines to capture premium positioning in European retail channels. Threat exposure from cultivated protein R&D venture capital flows demands defensive patent positioning around hybrid product formulation.
For New Entrants and Emerging Players: Mid-scale cloud kitchen operators in Southeast Asian urban corridors represent an underserved buyer archetype seeking predictable volume commitments with standardized quality documentation. White-space targets include precision livestock monitoring technology deployment and carbon credit monetization services for Australian feedlot operations. Go-to-market execution should anchor on sensor-based health tracking bundled with AI-driven feed optimization subscriptions.
For Investors and Strategic Acquirers: Re-rating potential sits with export-certified beef processors given Asian food service procurement consolidation and disproportionate demand pull through Brazil-Argentina-Australia corridors. Acquisition target archetypes include mid-scale operators with MAPA or DAWE certification pending facility retrofit completion. Signal to watch: methane-abatement retrofit capex deployment rates across European pork operations as inflection indicator for compliance-aligned asset scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Anaerobic Digester Installation | EU Green Deal methane mandates force capital deployment into manure management systems across German and Danish pork operations. |
| Blockchain Provenance Tracking | Distributed ledger architectures decentralize audit authority away from legacy certification agencies toward retailer-controlled transparency systems. |
| Carbon Credit Monetization | Australia's Emissions Reduction Fund creates tradeable offset revenue streams for methane-capture investments in Queensland feedlots. |
| Cold-Chain Bypass Formats | Shelf-stable cured segments reduce logistics dependency and extend geographic reach into infrastructure-constrained emerging markets. |
| Precision Livestock Monitoring | Sensor-based health tracking converging with AI-driven feed optimization opens margin recovery pathways for mid-scale operators. |
Research Methodology
Multi-period observation of feed conversion ratios, carcass grading premiums, and certification compliance rates anchored the trend analysis, supplemented by interviews with livestock procurement directors, veterinary epidemiologists, cold-chain logistics operators, and grain-trading risk managers. Secondary validation drew from USDA production reports, ECHA REACH substance registrations, Brazilian MAPA export certification databases, and Australian DAWE trade statistics. Bottom-up facility capacity modeling triangulated against top-down protein consumption forecasts across the analysis window.
Input-output matrices mapped feedstock supply elasticity, slaughter capacity utilization, and channel margin allocation across protein categories and processing methods. Segmentation dimensions modeled include product type, distribution channel, end-user procurement sophistication, and processing method shelf-life characteristics. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for regulatory compliance cost absorption and feed cost volatility assumptions.
Revisions become necessary when African swine fever or avian influenza outbreaks trigger veterinary quarantine protocols, when EU methane-abatement mandates accelerate beyond modeled facility retrofit timelines, or when Asian food service procurement consolidation shifts volume commitment structures. Forecasts reflect documented assumptions regarding feed input cost stability and certification regime enforcement intensity. A model refresh is warranted upon material change in South American crop cycle yields or Brazilian export corridor infrastructure investment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Middle East and Africa Bonsai Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Pure Plant Oil Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Africa Orange Market