
 South America Swine Feed Premix Market | 2026-2036
South America Swine Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
South America Swine Feed Premix Market Analytics
Buyer concentration among large-scale integrated operations is decoupling from traditional fragmented family farm procurement across southern Brazil and Argentina. Nutreco N.V. leverages its premix formulation expertise to serve contract growers seeking precision nutrition programs. Cargill, Incorporated anchors regional supply through its Brazilian compound feed network and direct-to-farm distribution infrastructure. De Heus Animal Nutrition competes by specializing in customized vitamin-mineral blends tailored to tropical climate stressors affecting swine metabolism.
South America swine feed premix denotes a micro-ingredient blend containing vitamins, minerals, amino acids, and additives dosed at 0.5–3.0% of finished feed weight, manufactured via multi-stage batching and cold-pelleting to preserve thermolabile compounds, serving to standardize nutritional intake across variable basal feedstuffs. Medicated premix retains dominant volume share where therapeutic use persists under veterinary prescription frameworks, though non-medicated premix captures accelerating growth as Brazil's antibiotic reduction mandates tighten. Vitamin premix commands premium positioning due to stability requirements and import dependency for certain fat-soluble compounds.
Brazil's MAPA enforces residue monitoring and withdrawal period protocols that reshape premix ingredient approvals, while Argentina's SENASA regulates import pathways for synthetic additives and vitamin concentrates. ANVISA in Brazil coordinates with MAPA on feed-grade pharmaceutical classifications, creating compliance complexity for medicated premix suppliers. Stakeholders must monitor regulatory divergence between Mercosur harmonization efforts and national implementation timelines to anticipate formulation reformulation cycles and sourcing reconfigurations.
Market Dynamics
Brazil's MAPA antibiotic reduction mandates are compressing formulation cycles across the premix supply base, forcing rapid reconfiguration of vitamin-mineral matrices and additive sourcing patterns before compliance deadlines take full effect.
Growth Catalysts
- Integrated farm consolidation:Large-scale operations in Santa Catarina and Rio Grande do Sul are standardizing premix procurement through volume contracts, creating predictable demand baselines for suppliers.
- MAPA regulatory pressure:Brazil's veterinary prescription frameworks for medicated feeds are accelerating non-medicated premix adoption as producers pre-position for stricter enforcement timelines.
- Precision nutrition technology:Real-time feed formulation software is enabling dynamic premix dosing adjustments based on herd growth-stage requirements and environmental stress factors.
Market Restraints
- Vitamin concentrate import dependency:Fat-soluble vitamin stability requirements force reliance on concentrated imports from European and Asian suppliers, exposing margins to currency volatility and shipping disruptions.
- Feed mill capacity concentration:Brazil's southern states host disproportionate compound feed production, creating geographic supply bottlenecks when logistics constraints emerge.
- Thermolabile compound degradation:Cold-pelleting infrastructure gaps in mid-sized facilities limit adoption of premium vitamin premix formulations requiring precise temperature control.
Strategic Opportunities
- Argentina's underpenetrated cordoba corridor:Swine production expansion in Argentina's central provinces lacks equivalent premix supplier density, creating first-mover positioning for formulation specialists.
- Enzyme-additive convergence:Phytase and carbohydrase integration with mineral matrices is opening new performance-tier premix categories commanding formulation premiums.
- Direct-to-farm digital channels:E-procurement platforms are bypassing traditional distributor layers, enabling premix suppliers to capture margin compression and build grower data relationships.
Industry Challenges
- Formulation chemist scarcity:Brazil's veterinary and animal science programs produce insufficient specialists in tropical stress nutrition, constraining supplier R&D expansion.
- Multi-regulator compliance synchronization:ANVISA pharmaceutical classifications frequently misalign with MAPA feed-grade approvals, creating product registration delays and inventory stranding risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Swine Feed Premix Market |
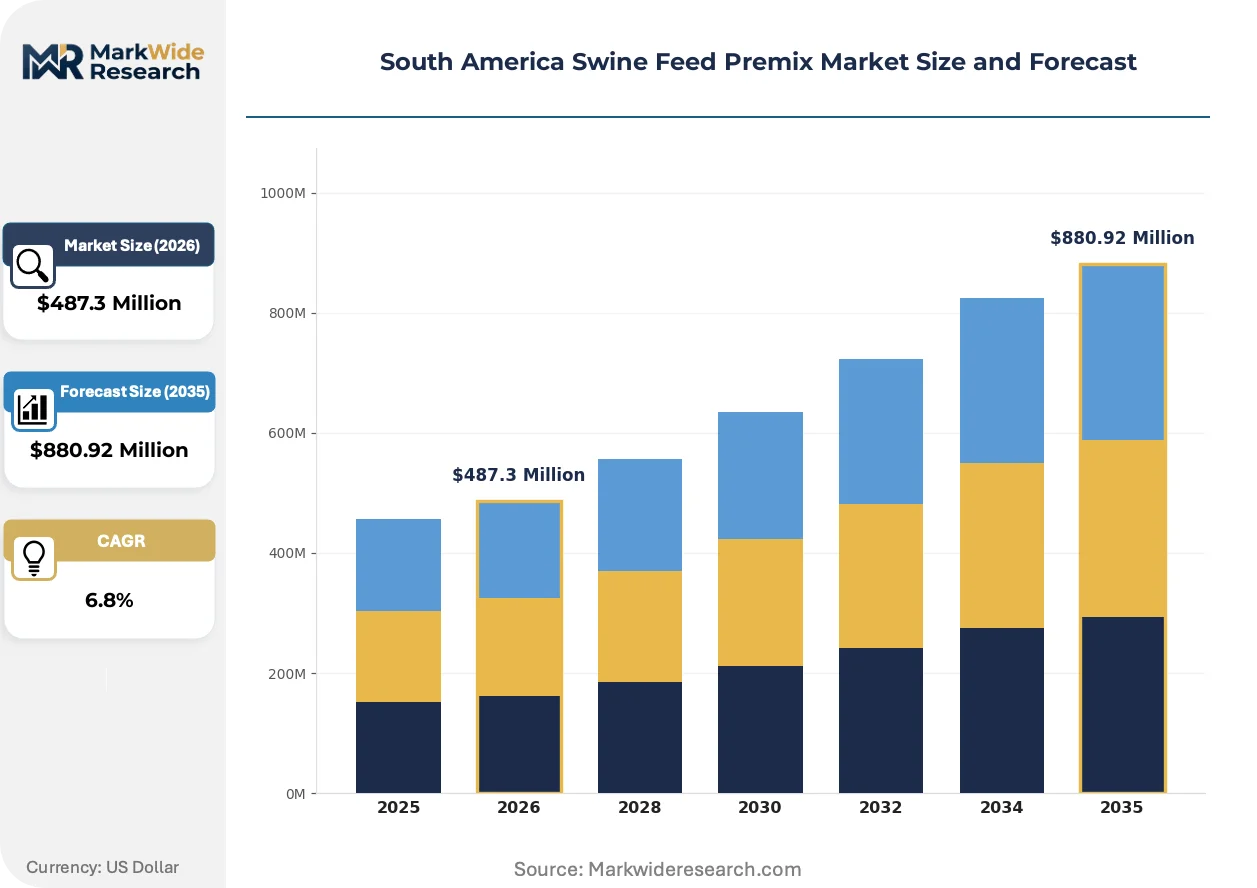
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medicated Premix, Non-Medicated Premix, Vitamin Premix, Mineral Premix Ingredient Source: Animal By-Products, Plant-Based Ingredients, Synthetic Additives, Fermented Products End User: Commercial Farms, Family Farms, Integrated Operations, Feed Manufacturers Distribution Channel: Online Sales, Retail Stores, Direct Sales, Distributors |
| Companies Covered | BRF Global, Nutreco N.V., Cargill, Incorporated, JBS S.A., Koninklijke DSM N.V., Archer Daniels Midland Company, De Heus Animal Nutrition, Agrosuper Group, SHV Holdings, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Swine Feed Premix Market Evolving Landscape
Formulation science is pivoting toward bioactive preservation and climate-adaptive nutrition matrices, with technology deployment patterns diverging sharply between integrated operators and fragmented family farm segments.
Encapsulated fat-soluble vitamin technologies are overtaking conventional spray-dried formulations in Brazil's premium premix tier. Large integrated operations in Paraná and Santa Catarina are adopting these stabilized compounds at accelerated procurement cycles. This shift is compressing shelf-life risk premiums and enabling longer supply chain reach into Argentina's interior production zones.
MAPA's residue monitoring protocols are reshaping additive approval pathways for Brazilian premix manufacturers. The framework's withdrawal period documentation requirements are extending product development timelines by forcing parallel toxicology studies. Medicated premix suppliers face the steepest compliance burden, with many accelerating non-medicated line extensions to maintain revenue continuity.
Contract nutrition advisory services are displacing transactional premix sales in southern Brazil's integrated sector. Large-scale operators in Rio Grande do Sul are bundling formulation expertise with volume supply agreements, unbundling traditional distributor technical support functions. This pattern is most visible among operations exceeding ten-thousand-sow capacity, where precision feeding economics justify dedicated nutritionist retention.
South America Swine Feed Premix Market Segmentation
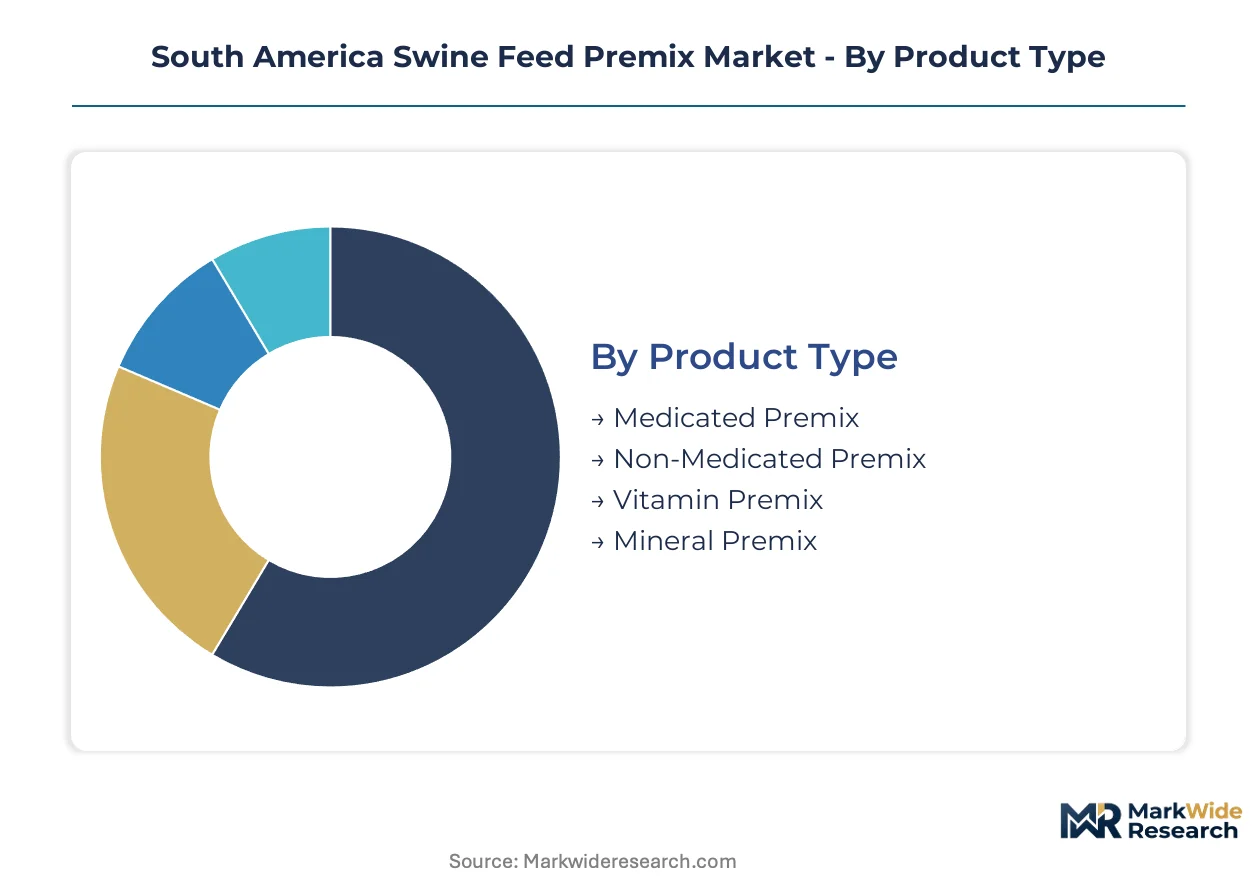
Premix segmentation in South America reflects divergent procurement patterns between Brazil's antibiotic transition mandates and Argentina's production expansion zones. Formulation complexity varies sharply across customer scale, with integrated operations demanding precision matrices that family farms cannot justify operationally.
Product Type:
Upgrade cycles from medicated to non-medicated formulations are compressing as MAPA enforcement timelines approach, forcing rapid re-equipment of feed mill dosing systems and cold-pelleting infrastructure.
- Medicated Premix:Therapeutic-grade blends containing regulated pharmaceuticals dosed under veterinary prescription frameworks. Procurement volumes remain concentrated in Santa Catarina's large sow operations where disease pressure justifies continued therapeutic use despite tightening withdrawal documentation.
- Non-Medicated Premix:Antibiotic-free vitamin-mineral matrices incorporating organic acids, botanical extracts, and enzyme systems as performance substitutes. Rio Grande do Sul's integrated operators are pre-positioning procurement contracts ahead of MAPA's full compliance deadlines.
- Vitamin Premix:Thermolabile fat-soluble compound blends requiring stabilized encapsulation and precision cold-pelleting.
- Mineral Premix:Trace element and macromineral concentrates calibrated to regional soil deficiency profiles in southern Brazil's corn-soy basal feedstuffs.
Volume placements concentrate in Medicated Premix; the faster expansion belongs to Non-Medicated Premix.
Ingredient Source:
Cost tier differentiation separates premium synthetic formulations from commodity plant-based alternatives, with price spreads widening as currency volatility affects import-dependent concentrate sourcing.
- Synthetic Additives:Laboratory-synthesized amino acids, vitamins, and performance compounds offering precise potency standardization. Brazil's premix manufacturers depend on European and Asian concentrate suppliers for fat-soluble vitamin stability, exposing formulation costs to exchange rate fluctuations.
- Plant-Based Ingredients:Soy-derived protein concentrates, corn gluten meals, and oilseed processing by-products forming basal matrix carriers. Argentina's expanding Cordoba corridor production favors these domestically sourced inputs for cost containment.
- Animal By-Products:Processed protein meals and rendered fats subject to SENASA traceability protocols.
- Fermented Products:Probiotic cultures and enzyme-active substrates produced through controlled fermentation.
Procurement economics favor Plant-Based Ingredients in Argentina; Synthetic Additives retain premium positioning in Brazil's precision nutrition tier.
End User:
Customer type segmentation tracks the operational divergence between Brazil's southern state consolidation and Argentina's fragmented production base.
- Integrated Operations:Vertically coordinated sow-to-finish systems exceeding ten-thousand-sow capacity with in-house nutritionist staffing. These operators in Paraná and Santa Catarina are bundling premix procurement with contract advisory services, bypassing traditional distributor technical support.
- Commercial Farms:Mid-scale independent producers with professional management but without captive feed milling. Southern Brazil's commercial farm segment is standardizing on volume premix contracts as feed conversion ratio optimization becomes competitive necessity.
- Feed Manufacturers:Independent compound feed mills producing finished rations for third-party farms.
- Family Farms:Smallholder operations under two-hundred-sow capacity with limited formulation sophistication.
Revenue concentration sits with Integrated Operations; Commercial Farms represent the steepest expansion trajectory as professionalization spreads.
Distribution Channel:
Supply concentration in Brazil's southern states creates geographic bottlenecks that channel strategy must address through direct-to-farm bypass or distributor density.
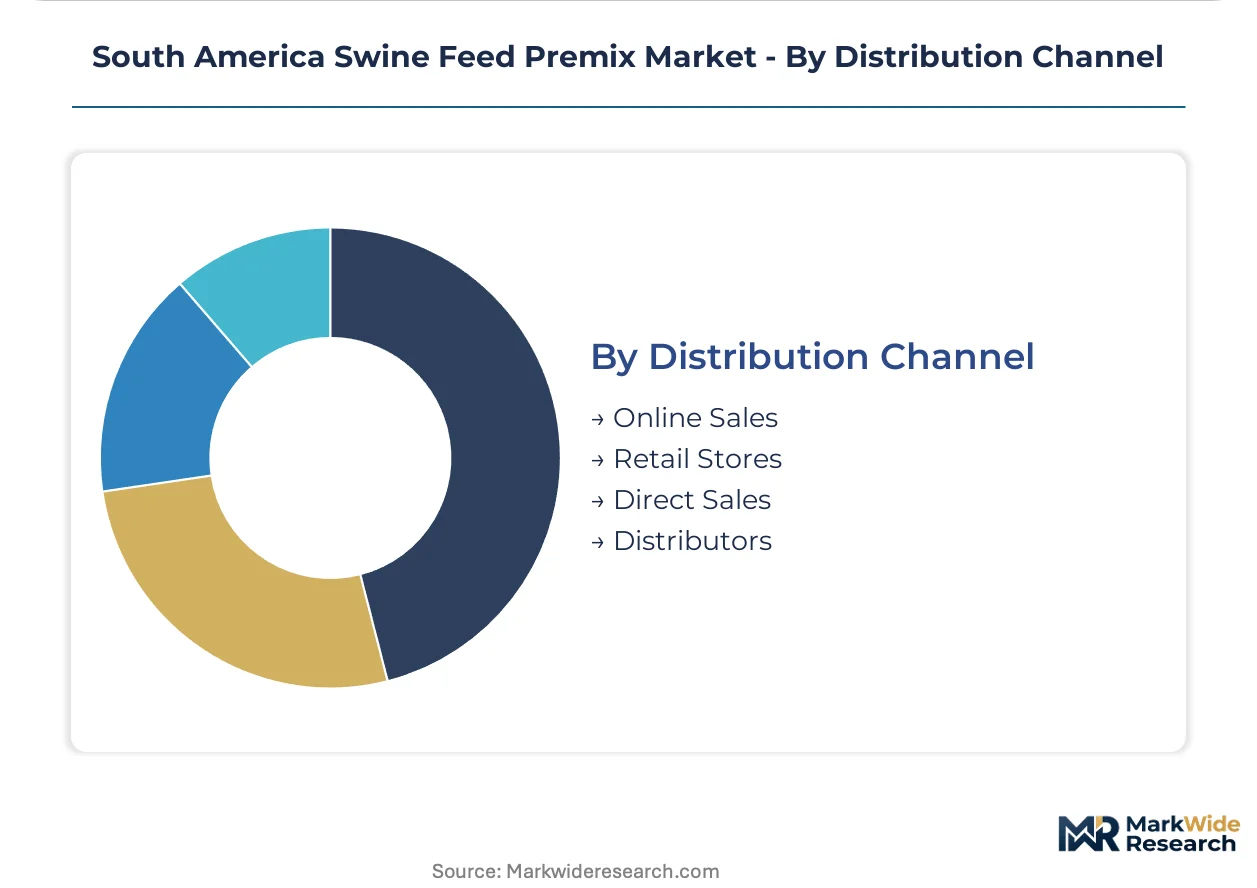
- Direct Sales:Manufacturer-to-farm relationships with dedicated technical representatives and volume pricing schedules. Large integrated operators in Rio Grande do Sul are consolidating procurement through direct channels to capture margin compression and build grower data relationships.
- Distributors:Regional feed supply cooperatives and agricultural input retailers with local logistics infrastructure. These intermediaries retain relevance in Argentina's underpenetrated interior provinces where supplier density remains thin.
- Online Sales:E-procurement platforms enabling price transparency and order automation.
- Retail Stores:Agricultural supply outlets serving smallholder and family farm segments.
Channel share is consolidating toward Direct Sales; Online Sales are climbing the fastest as digital infrastructure penetrates mid-scale farm management systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's southern pork belt, where integrated operations drive volume procurement and regulatory pressure accelerates formulation shifts. Argentina's central provinces emerge as secondary expansion zones with underdeveloped supplier density. Chile and Colombia host smaller but specialized production clusters responding to distinct regulatory frameworks.
Brazil
Santa Catarina and Rio Grande do Sul dominate regional premix consumption through vertically integrated sow-to-finish systems exceeding ten-thousand-head capacity. MAPA's antibiotic reduction mandates force rapid reconfiguration of vitamin-mineral matrices ahead of enforcement deadlines. Paraná's commercial farm segment is standardizing on volume contracts as feed conversion optimization becomes competitive necessity.
Argentina
Cordoba Province's expanding swine production corridor lacks equivalent premix supplier density, creating first-mover positioning for formulation specialists. SENASA regulates import pathways for synthetic additives and vitamin concentrates, extending product registration timelines. Buenos Aires Province maintains traditional procurement through distributor networks serving mid-scale independent producers.
Chile
Metropolitan Region and O'Higgins Province concentrate Chilean pork production under strict residue monitoring protocols. The country's national agricultural regulator enforces withdrawal period documentation that parallels Brazil's MAPA framework. Southern Bio Bio Region hosts emerging commercial farms adopting precision nutrition technology from Brazilian suppliers.
Colombia
Antioquia Department's pork sector imports premix formulations primarily through Colombian compound feed manufacturers. The national food and drug regulator coordinates with agricultural authorities on feed-grade additive classifications. Cundinamarca's high-altitude production zones demand customized mineral matrices addressing metabolic stress factors.
Uruguay
Paysandú and Canelones departments sustain modest but professionalized swine operations with premix procurement through Argentine distributor channels. The national livestock services administration maintains traceability protocols for imported vitamin concentrates. Montevideo's feed manufacturing cluster serves regional demand with limited local formulation capability.
South America Swine Feed Premix Market Competitive Landscape
Brazilian producers anchor one tier; Dutch and U.S. specialists hold formulation technology positions. The market structure reflects consolidated procurement power among integrated operators confronting fragmented mid-scale farm segments. Three archetypes dominate: multinational nutrition platforms with regional compound feed networks, dedicated premix formulators with tropical climate expertise, and protein-integrated conglomerates with captive feed demand. Capacity expansion and direct-to-farm channel development represent the dominant competitive moves as distributors face margin compression.
Within the multinational platform tier, Nutreco N.V. and Cargill, Incorporated occupy positions defined by regional infrastructure scale and distribution reach. De Heus Animal Nutrition exemplifies the specialized formulator archetype with tropical stress nutrition positioning. These three entities represent distinct strategic approaches to procurement consolidation in southern Brazil and expansion positioning in Argentina's underpenetrated interior.
| Leading Market Players |
|---|
| BRF Global |
| Nutreco N.V. |
| Cargill, Incorporated |
| JBS S.A. |
| Koninklijke DSM N.V. |
| Archer Daniels Midland Company |
| De Heus Animal Nutrition |
| Agrosuper Group |
| SHV Holdings |
| Others |
Value Network & Pricing Analysis
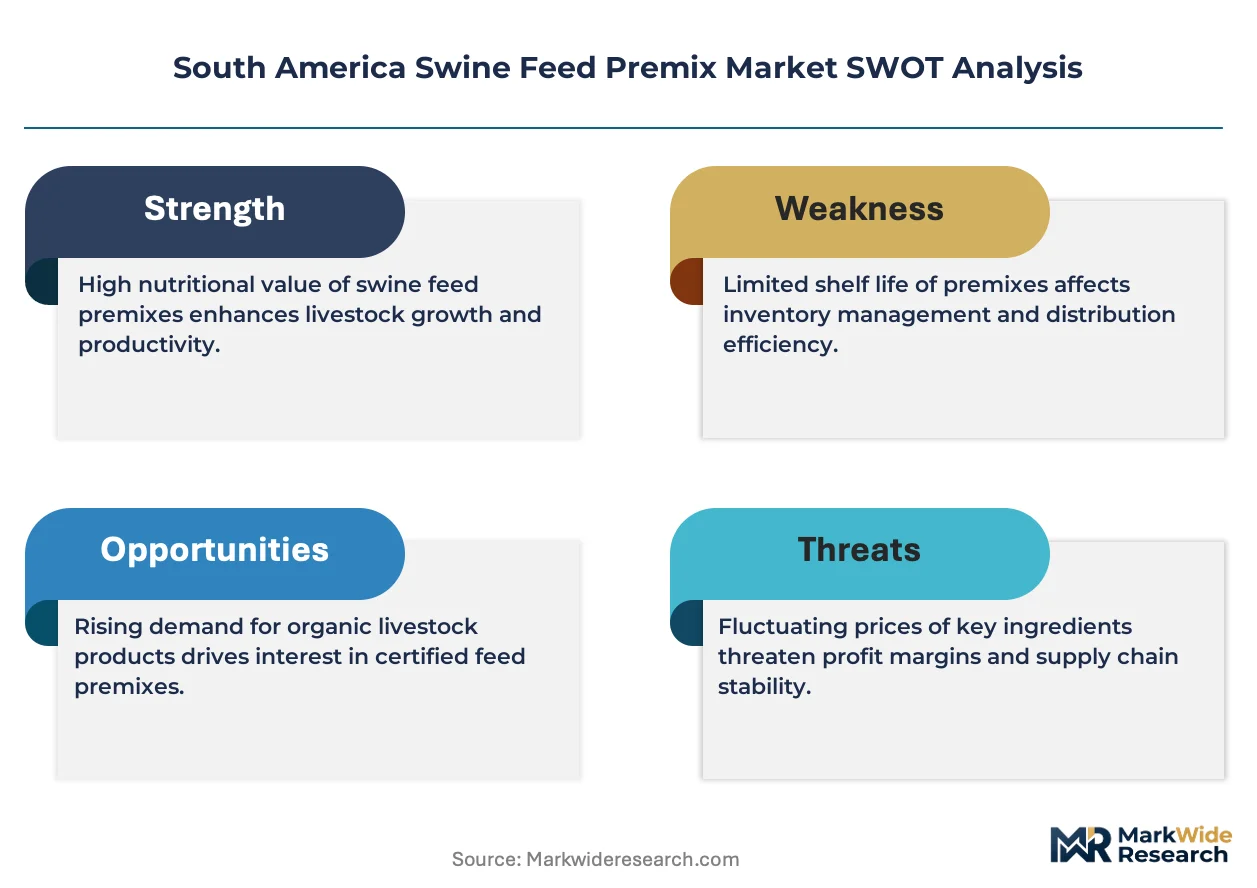
Brazil's MAPA antibiotic reduction mandates are forcing rapid reformulation investments across premix portfolios, compelling suppliers to absorb cold-pelleting infrastructure costs and pass through select premiums to integrated operators while compressing margins on legacy medicated lines.
Pricing Analysis
Volume contracts anchor the lower tier where Rio Grande do Sul's integrated operators extract scale discounts through multi-year procurement commitments; premium pricing stratifies across encapsulated vitamin formulations serving Santa Catarina's precision nutrition tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales advisory bundling. Cost compression in standard medicated premix is intensifying because MAPA compliance deadlines are accelerating product line transitions. Family farms under two-hundred-sow capacity exhibit acute price sensitivity, while ten-thousand-sow operations prioritize feed conversion performance over unit cost.
Supply Chain Analysis
Argentina's SENASA domestic-content traceability requirements are reshaping sourcing patterns for Cordoba corridor producers, pushing formulators toward regional oilseed processing by-products and away from concentrated European vitamin imports. Supply concentrates in Brazil's southern states, with secondary sourcing corridors drawing from Argentina's expanding domestic basal feedstuff production. Raw material dependencies center on European fat-soluble vitamin concentrates, Asian synthetic amino acid precursors, and regional corn-soy matrices. Single-source vulnerability runs through vitamin concentrate import channels exposed to currency volatility. Distribution runs through direct-to-farm manufacturer relationships in southern Brazil and agricultural cooperative networks in Argentina's interior provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around formulation chemistry capabilities and cold-pelleting infrastructure, with MAPA compliance deadlines eliminating undercapitalized regional blenders unable to fund rapid product line transitions.
For Market Incumbents: Deepen captive supply relationships with Rio Grande do Sul's largest integrated operators through bundled nutrition advisory contracts that lock out competitor access. Expand cold-pelleting capacity in Paraná to capture commercial farm segment procurement standardization. The threat of Argentine formulators exploiting Cordoba corridor underpenetration demands preemptive distributor acquisition or joint venture positioning. For New Entrants and Emerging Players: Capture Argentina's Cordoba corridor through SENASA-registered mineral premix offerings calibrated to regional soil deficiency profiles absent incumbent density. Target commercial farms in Paraná with precision dosing technology partnerships that bypass established distributor technical support relationships. A direct-to-farm digital procurement platform with embedded feed formulation software offers the cleanest go-to-market angle against legacy supply chains. For Investors and Strategic Acquirers: The window for entry favors specialized tropical stress nutrition formulators with established MAPA regulatory navigation capabilities and existing cold-pelleting assets. Acquisition targets should demonstrate proven reformulation agility under Brazil's antibiotic reduction mandates. Watch for MAPA enforcement timeline acceleration as the inflection signal that compresses valuation multiples for medicated-premix-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Concentrate Sourcing | Reduces exposure to European supplier currency volatility and shipping disruption risks. |
| Cold-Pelleting Capacity Expansion | Enables encapsulated fat-soluble vitamin preservation required for MAPA-compliant premium formulations. |
| Direct-to-Farm Digital Platform Launch | Bypasses distributor margin capture while building grower data relationships for precision nutrition services. |
| SENASA Registration Acceleration in Argentina | Secures first-mover positioning in Cordoba corridor expansion ahead of incumbent supply base reconfiguration. |
| Contract Nutrition Advisory Bundling | Locks in multi-year procurement commitments from integrated operators through embedded technical support. |
Research Methodology
Independent corroboration across feed mill operations directors, integrated farm nutritionists, and SENASA regulatory affairs specialists underwrites the qualitative findings, validated against MAPA regulatory filings, Brazilian compound feed production statistics, and Argentine agricultural export customs records. Bottom-up volume estimates from state-level sow inventory data triangulate against top-down premix manufacturer shipment disclosures. Primary fieldwork encompassed formulation chemists at Brazilian premix facilities, procurement leads at Rio Grande do Sul integrated operations, and distributor principals serving Argentina's interior provinces.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon, with segmentation modeling spanning product type, ingredient source, end user scale, and distribution channel. CAGRs derive from logistic curve fitting to historical adoption patterns adjusted for regulatory inflection timing. Industry-specific forecast inputs include MAPA enforcement timeline probability distributions and Argentine swine herd expansion projections from provincial agricultural ministry data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mercosur regulatory harmonization delays and vitamin concentrate import tariff volatility. Forecasts reflect documented assumptions regarding MAPA compliance adherence rates and integrated farm consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Genetically Modified Feed Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Mexico Compound Feed Market