
 Australia Organic Farming Market | 2026-2036
Australia Organic Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Organic Farming Market Intelligence
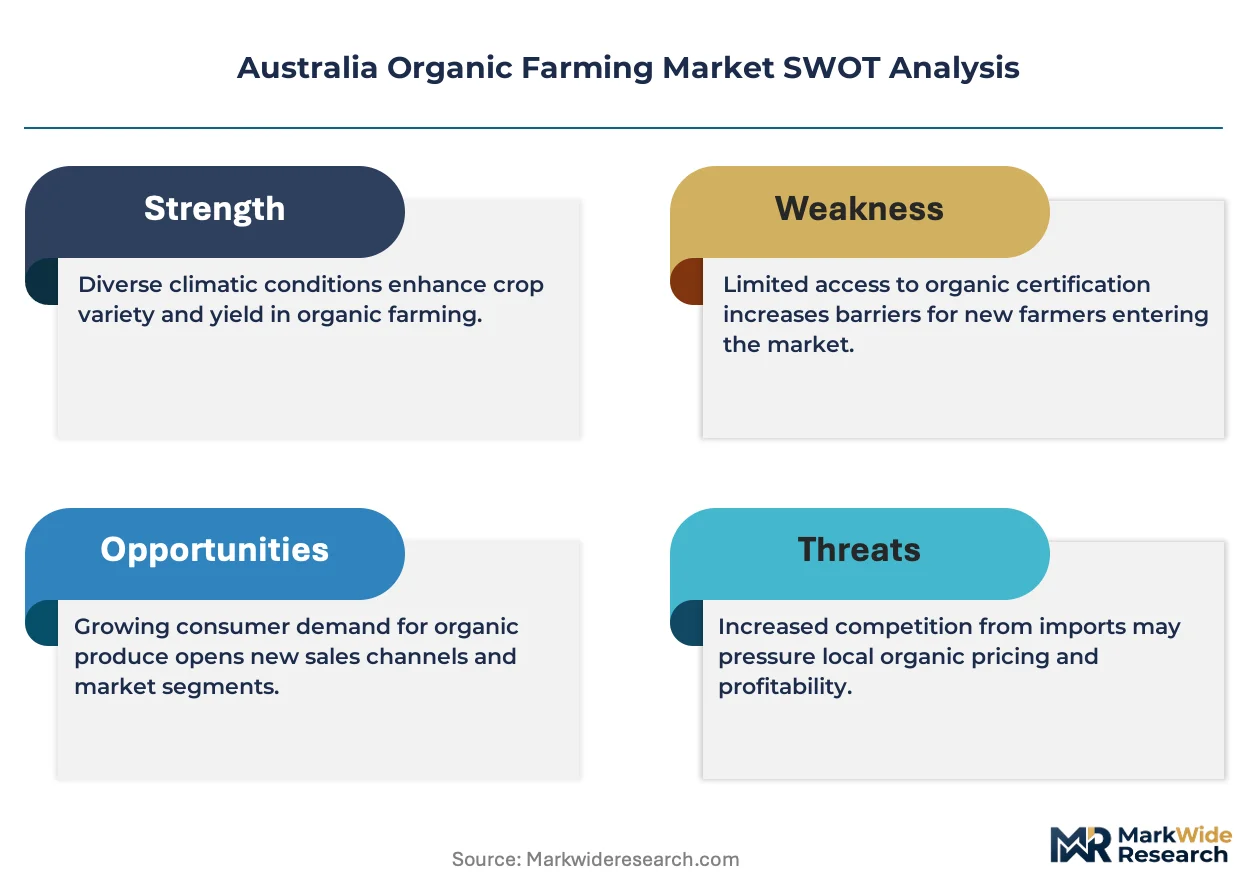
Australian Certified Organic certification is collapsing the pool of qualified producers as compliance timelines tighten and audit costs escalate. Enviroganic Farm leverages its long-standing certification pedigree to command shelf space in premium retail channels. Costa Group dominates protected-crop organic vegetable output through scale-controlled glasshouse operations. Elders sustains broad geographic coverage by embedding organic advisory services within its legacy rural supply network.
Organic farming denotes agricultural production that excludes synthetic pesticides, genetically modified organisms, and artificial fertilizers while maintaining soil ecological balance through crop rotation, composting, and biological pest management; certification mandates multi-year transition periods and residue testing protocols. The primary purpose is to produce food and fiber for human and animal consumption under verified environmental stewardship standards. Vegetables and dairy command the deepest margin pools due to perishability-driven price premiums and concentrated processing infrastructure. Grains occupy the most mature segment with established export corridors to Asian markets. Online retail represents the fastest-growing distribution channel as direct-to-consumer platforms reduce intermediary capture.
The National Association for Sustainable Agriculture Australia administers the dominant domestic certification scheme, while the Department of Agriculture, Fisheries and Forestry oversees export integrity and biosecurity alignment. These frameworks shape demand by determining which producers can access premium domestic shelf space and which consignments clear border protocols for EU and Asian buyers. Stakeholders must monitor pending revisions to the Australian Organic Standard and assess whether on-farm digital traceability investments will become de facto market access requirements.
Market Dynamics
Soil carbon measurement technologies are tightening compliance timelines across Australian organic operations, forcing producers to adopt precision monitoring systems or face certification disqualification. This technological imperative is compressing operational margins while simultaneously creating competitive separation between digitally equipped farms and legacy operators.
Growth Catalysts
- Premium retail channel expansion:Major grocery chains in New South Wales and Victoria are dedicating expanded shelf space to certified organic produce, creating guaranteed offtake for compliant suppliers.
- Export corridor maturation:The Department of Agriculture, Fisheries and Forestry has streamlined biosecurity protocols for organic grain shipments to Asian markets, reducing border clearance friction.
- Soil health monetization:Carbon credit frameworks are rewarding verified soil carbon sequestration practices, adding revenue streams beyond commodity sales for certified operators.
Market Restraints
- Audit cost escalation:Australian Certified Organic certification requires annual third-party inspections with fees rising faster than commodity price indices, squeezing smallholder participation.
- Input supply concentration:Organic seed and biological pest control suppliers cluster in southeastern Australia, exposing interstate producers to freight cost volatility and supply delays.
- Transition period rigidity:The mandatory multi-year conversion timeline from conventional to organic status locks land in revenue-suppressed status without interim certification flexibility.
Strategic Opportunities
- Queensland underpenetration:Northern production zones hold significant organic conversion potential with established irrigation infrastructure and proximity to Asian export ports.
- Direct-to-consumer platform growth:Online retail channels are capturing margin previously absorbed by wholesale intermediaries, enabling producer price control and customer relationship ownership.
- Regenerative agriculture convergence:Integration of organic certification with emerging soil health standards is creating dual-credential products commanding premium positioning in domestic and export markets.
Industry Challenges
- Skilled labor scarcity:Biological pest management and composting system operation require specialized expertise that agricultural training institutions have not scaled to meet demand.
- Glasshouse capital intensity:Protected-crop organic vegetable production demands substantial infrastructure investment that mid-scale operators struggle to finance without equity dilution.
- Residue testing complexity:Cross-contamination risk from neighboring conventional operations necessitates buffer zone management and ongoing surveillance testing that complicates land use planning.
Report Scope
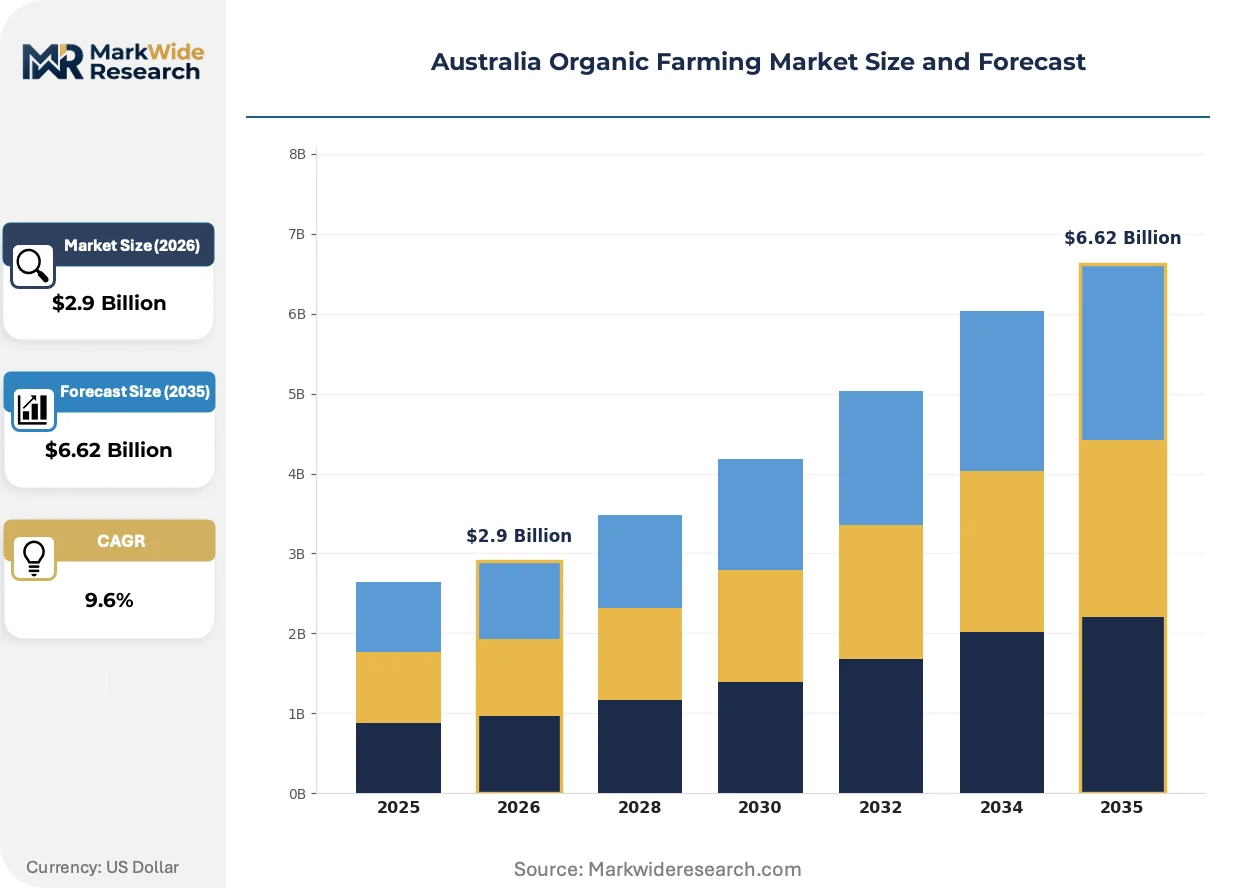
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Organic Farming Market |
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $6.62 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Certification Type: USDA Organic, Australian Certified Organic, Bio-Dynamic, EU Organic Distribution Channel: Supermarkets, Farmers Markets, Online Retail, Specialty Stores End User: Households, Restaurants, Food Manufacturers, Exporters |
| Companies Covered | Consolidated Pastoral Company Pty Ltd, Enviroganic Farm, Costa Group Ltd, The Leaf Protein Co., NewWave Biotechnology, Elders, Southern Cross Farms, Farmbot Monitoring Solutions, Rural Funds Management Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Organic Farming Market Strategic Shifts & Innovations
Digital traceability infrastructure is penetrating Australian organic supply chains, replacing paper-based audit trails with immutable verification systems that satisfy both domestic retailers and export regulators.
Remote sensing platforms combining satellite imagery with ground-truthed soil sensors are displacing manual field inspection regimes for compliance verification. Major retail buyers in Sydney and Melbourne are mandating real-time data feeds from supplier farms. This technological shift is compressing the competitive position of operators unable to demonstrate continuous monitoring capabilities.
The Australian Organic Standard revision process is accelerating alignment with EU organic regulations, driven by the Department of Agriculture, Fisheries and Forestry's export integrity mandate. This harmonization reduces dual-certification burdens for grain exporters targeting European markets. Dairy and processed food segments are investing in laboratory capacity upgrades to meet the tightened residue thresholds anticipated in the forthcoming standard release.
Subscription-based produce box models are capturing urban household procurement patterns across Melbourne and Sydney, disintermediating traditional wholesale channels. Premium retail chains are responding with private-label organic lines and direct farmer partnerships. This channel evolution concentrates demand visibility with end consumers while pressuring conventional distributor margins.
Australia Organic Farming Market Segmentation
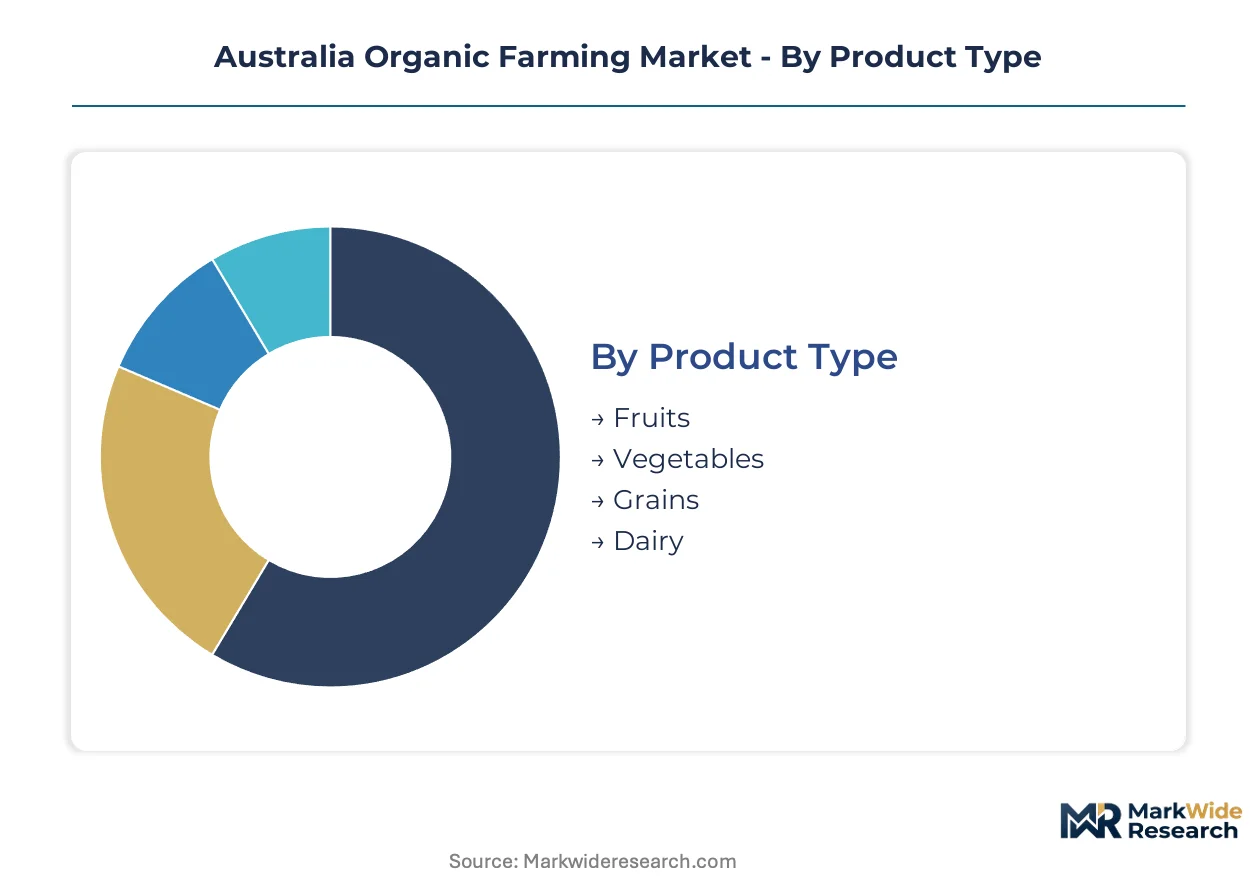
Segmentation in Australian organic farming reveals how certification tiers, channel strategies, and end-user specifications fragment revenue capture across the value chain. Producers must align product portfolios with the distinct compliance, pricing, and logistics requirements of each segment to secure sustainable offtake.
Product Type:
Channel-mix patterns diverge sharply across product categories, with perishability dictating whether segments flow through premium retail, direct-to-consumer platforms, or bulk export corridors.
- Vegetables:Protected-crop glasshouse operations dominate output, with harvest cycles optimized for Coles and Woolworths procurement calendars in Sydney and Melbourne. New South Wales and Victoria absorb the majority of domestic volume, though residue testing complexity from neighboring conventional farms constrains expansion into peri-urban zones.
- Dairy:Pasteurized milk and value-added products command shelf space through supermarket private-label programs and specialty cheese distribution. Processing infrastructure concentration in Victoria creates margin compression for interstate suppliers facing freight cost volatility.
- Fruits:Orchard-based production targets both domestic retail and Asian export markets, with biosecurity alignment through the Department of Agriculture, Fisheries and Forestry determining market access.
- Grains:Mature export corridors serve Asian buyers, with bulk handling infrastructure in South Australia and Western Australia supporting containerized shipments.
By volume, grains lead. By growth pace, vegetables are ahead.
Certification Type:
Cost-tier stratification separates producers by audit burden and market access eligibility, with premium domestic and export channels gating entry behind specific credential requirements.
- Australian Certified Organic:The dominant domestic scheme administered by the National Association for Sustainable Agriculture Australia governs supermarket shelf access and underpins most premium retail contracts. Annual third-party inspections with escalating fee structures squeeze smallholder participation while creating competitive separation for established operators.
- USDA Organic:Dual-certification burden for exporters targeting North American markets, with equivalence agreements reducing redundant testing but maintaining separate documentation trails. Grain handlers in South Australia prioritize this credential for bulk shipments.
- EU Organic:Alignment with Australian Organic Standard revisions is accelerating, reducing compliance friction for grain and processed food exporters targeting European buyers. Dairy processors are upgrading laboratory capacity to meet tightened residue thresholds.
- Bio-Dynamic:Niche positioning through Demeter certification captures specialty retail and farmers market channels, with premium pricing offsetting lower production volumes and limited export recognition.
By producer count, Australian Certified Organic dominates. By margin expansion potential, EU Organic is climbing fastest.
Distribution Channel:
Customer-type concentration shapes channel selection, with household procurement patterns fragmenting across convenience-driven supermarket visits and relationship-based direct purchasing.
- Supermarkets:Coles and Woolworths control the majority of certified organic volume through dedicated shelf space expansion in New South Wales and Victoria. Real-time data feed mandates from major retail buyers in Sydney and Melbourne are compressing the competitive position of non-digitized suppliers.
- Online Retail:Subscription-based produce box models across Melbourne and Sydney are disintermediating wholesale channels, capturing margin previously absorbed by intermediaries. This channel is expanding most quickly as direct-to-consumer platforms enable producer price control.
- Farmers Markets:Relationship-driven transactions support smaller producers lacking scale for retail supply contracts, with Saturday trading patterns in capital cities concentrating demand visibility.
- Specialty Stores:Independent grocers and organic retailers serve niche consumer segments seeking product provenance transparency, though shelf space constraints limit volume growth.
By revenue concentration, supermarkets lead. By margin capture per unit, online retail is gaining share fastest.
End User:
Application requirements fragment demand specifications, with processing intensity and export documentation burden determining which producer segments serve each category.
- Households:Urban consumers in Sydney and Melbourne drive procurement through supermarket and online channels, with subscription models capturing recurring purchase patterns. Price sensitivity varies by income bracket and certification awareness.
- Restaurants:Chef-driven demand for specific varietals and harvest timing creates contract growing opportunities, though volume volatility and payment term pressure constrain producer participation.
- Food Manufacturers:Ingredient sourcing for processed organic products requires consistent supply contracts and laboratory-verified residue documentation, favoring larger-scale certified operations.
- Exporters:Asian and European buyers impose distinct biosecurity and certification requirements, with the Department of Agriculture, Fisheries and Forestry oversight determining border clearance outcomes.
By transaction frequency, households lead. By contract value per shipment, exporters show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium grocery buyers in Sydney and Melbourne concentrate procurement power, dictating certification requirements and shelf-space allocation across eastern seaboard production zones. This buyer-archetype concentration shapes where conversion capital flows and which regions capture organic price premiums.
New South Wales
Coles and Woolworths headquarters procurement teams dominate vegetable offtake from the Sydney Basin and Hunter Valley glasshouse clusters. The Department of Agriculture, Fisheries and Forestry administers export integrity protocols from Port Botany. Biological pest management expertise concentrates around Richmond and the Central Coast, where advisory services from legacy rural supply networks support producer transitions.
Victoria
Dairy processing infrastructure in Gippsland and the Murray Valley creates margin pools for pasture-based organic milk suppliers. The Australian Organic Standard revision process engages Victorian laboratories for residue threshold testing. Melbourne's subscription produce box models disintermediate wholesale channels, capturing recurring urban household procurement patterns.
Queensland
Established irrigation infrastructure in the Lockyer Valley and Darling Downs holds conversion potential for grain and vegetable operations. The National Association for Sustainable Agriculture Australia extends certification administration into northern production zones. Proximity to Brisbane Port and Asian export corridors positions the state for expansion as compliance timelines tighten elsewhere.
Western Australia
Bulk grain handling infrastructure in the Wheatbelt supports containerized organic shipments to Asian buyers. The Department of Agriculture, Fisheries and Forestry oversees biosecurity alignment for export consignments from Fremantle. Soil carbon measurement technology adoption lags eastern states, creating competitive pressure on producers seeking dual-credential positioning.
South Australia
Established organic grain export corridors through Port Adelaide serve mature Asian market relationships. The Australian Certified Organic audit burden escalates faster here than commodity price indices, squeezing smallholder participation. Adelaide Hills orchard production targets domestic retail and specialty cheese distribution channels.
Australia Organic Farming Market Key Industry Players
Player mix skews toward diversified agribusiness conglomerates with legacy rural supply networks and specialized organic operators with multi-decade certification pedigrees. Market structure exhibits tiered concentration: scale-controlled glasshouse vegetable producers command premium retail shelf space, while mid-scale mixed farms compete for farmers market and direct-to-consumer channels. Two strategic archetypes dominate—vertically integrated protected-crop specialists and advisory-embedded rural service platforms. Competitive moves center on certification pedigree accumulation and digital traceability infrastructure deployment.
Among certification-pedigreed operators, Enviroganic Farm exemplifies long-standing Australian Certified Organic credential holders commanding supermarket shelf access, while Costa Group occupies the scale-driven protected-crop tier with glasshouse infrastructure concentration. Elders represents the advisory-embedded archetype, leveraging legacy rural supply networks to sustain broad geographic coverage. These three anchors illustrate how competitive positioning separates digitally equipped, certification-advantaged operations from legacy producers facing compliance disqualification risk.
| Leading Market Players |
|---|
| Consolidated Pastoral Company Pty Ltd |
| Enviroganic Farm |
| Costa Group Ltd |
| The Leaf Protein Co. |
| NewWave Biotechnology |
| Elders |
| Southern Cross Farms |
| Farmbot Monitoring Solutions |
| Rural Funds Management Limited |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for biological pest control inputs compress working capital flexibility while amplifying the pricing leverage of southeastern Australian suppliers over interstate producers. This lead-time rigidity concentrates margin capture with certified seed and biological input vendors in New South Wales and Victoria, forcing Queensland and Western Australia operations to absorb freight volatility or face certification disqualification.
Pricing Analysis
Cost-plus contracts indexed to Australian Certified Organic audit fee escalations dominate procurement agreements between premium retail chains and established vegetable producers. Three-tier pricing structure across Australian Certified Organic, EU Organic, and Bio-Dynamic certification levels separates shelf-access eligibility, with Coles and Woolworths procurement teams commanding steepest discounts from large-scale glasshouse operators. Cost compression in the Bio-Dynamic tier is intensifying because Demeter-certified volumes lack export corridor recognition. Households in Sydney and Melbourne show highest price sensitivity, while Asian export buyers demonstrate inelastic demand for residue-verified grain shipments.
Supply Chain Analysis
Inventory concentration in New South Wales and Victoria for organic seed stock and biological pest control formulations exposes Queensland and Western Australia producers to supply delays during certification audit windows. Raw material dependencies center on heritage seed varieties, composted manure inputs, and microbial inoculants sourced from established southeastern suppliers. Single-source vulnerability pervades the biological input segment, where two dominant vendors control mycorrhizal fungi and beneficial nematode formulations. Distribution runs through Coles and Woolworths centralized distribution centers for domestic retail, while bulk grain shipments containerize through Port Botany, Fremantle, and Brisbane for Asian export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from regenerative agriculture operators capturing dual-credential premiums without full organic certification burdens. Defensive positioning requires preemptive moves before soil carbon measurement mandates reshape compliance economics.
For Market Incumbents: Shield certification pedigree through accelerated Australian Certified Organic renewal investments ahead of anticipated audit cost spikes. Backward integration into biological pest control propagation reduces exposure to southeastern supplier concentration. Lock long-term offtake agreements with Coles and Woolworths procurement teams before regenerative agriculture alternatives erode shelf-space guarantees.
For New Entrants and Emerging Players: Anchor in Queensland irrigation infrastructure where established water rights and Asian export port proximity offset compliance timeline disadvantages. Target Lockyer Valley vegetable production and Darling Downs grain conversion as underpenetrated zones with lower land cost bases than New South Wales competitors. Deploy subscription produce box models capturing Melbourne and Sydney household procurement patterns with direct-to-consumer margin retention.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because audit cost escalation will force smallholder exits while rewarding scaled, digitally traceable operations. Acquisition targets cluster around mid-scale mixed farms with multi-decade certification pedigrees and existing Coles or Woolworths supply contracts. Watch for Australian Organic Standard revision announcements as the signal indicating when residue threshold investments become mandatory for market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Traceability Infrastructure Deployment | Real-time data feeds from supplier farms satisfy Coles and Woolworths procurement mandates while compressing non-digitized competitors. |
| Backward Integration into Biological Input Production | In-house propagation of beneficial nematodes and microbial inoculants reduces freight cost volatility from southeastern supplier concentration. |
| Dual-Credential Certification Pursuit | Simultaneous Australian Certified Organic and EU Organic alignment captures premium shelf space in Sydney and Melbourne while clearing European export protocols. |
| Direct-to-Consumer Platform Launch | Subscription produce box models disintermediate wholesale channels and capture margin previously absorbed by distributors in Melbourne and Sydney. |
| Queensland Production Footprint Expansion | Lockyer Valley and Darling Downs conversion leverages established irrigation infrastructure and Brisbane Port proximity to Asian buyers. |
Research Approach
Initial hypotheses were tested against primary input from organic certification auditors, Coles and Woolworths category buyers, biological pest control suppliers, and Department of Agriculture, Fisheries and Forestry export integrity officers and refined through secondary validation against National Association for Sustainable Agriculture Australia certification records, Australian Organic Standard revision drafts, customs export documentation, and agricultural trade flow databases. Bottom-up volume estimates from individual farm operations were triangulated against top-down market sizing from retail channel revenue flows.
Variance decomposition across product type, certification tier, distribution channel, and end-user application segments structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assumptions weighted by revenue concentration. Forecast inputs incorporated Australian Certified Organic audit fee trajectories, soil carbon measurement technology adoption curves, and premium retail shelf space expansion commitments from major grocery chains.
Decision-makers should treat outputs as directional under assumptions of continued Australian Organic Standard alignment with EU regulations and stable biosecurity protocol enforcement from the Department of Agriculture, Fisheries and Forestry; material deviation in certification harmonization timelines or export corridor access would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Global Guayusa Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Singapore Floriculture Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Specialty Egg Market