
 Fish Feed Market | 2026-2036
Fish Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Feed Market Analysis
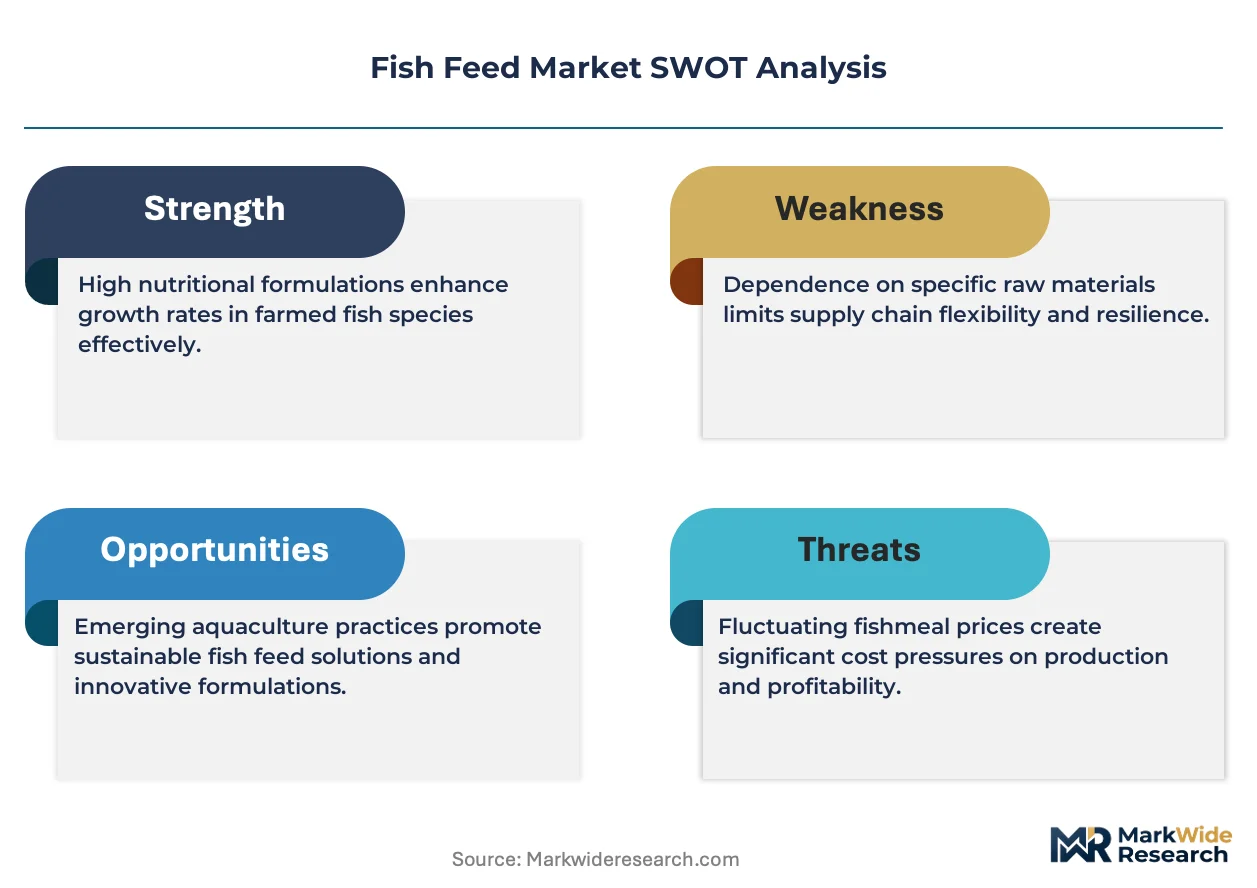
Modular feed formulation—where base nutrient premixes separate from species-specific additive packs—is realigning how aquaculture farms configure procurement contracts. Cargill Incorporated leverages its integrated soy processing network to secure cost-advantaged raw material positions across South American supply basins. BioMar Group anchors its competitive stance through specialized marine hatchery diets that command premium positioning in Atlantic salmon value chains. Nutreco N.V. differentiates via sustained R&D intensity in functional feed additives targeting gut health optimization.
Fish feed constitutes nutritionally complete formulated diets manufactured through extrusion, pelleting, or liquid suspension processes, typically containing 25-55% crude protein, 6-18% lipid content, and micronutrient premixes tailored to species-specific metabolic requirements; its primary commercial purpose is to replace wild forage fish dependency in intensive aquaculture production systems. Extruded feed dominates value pools due to superior water stability and digestibility coefficients that reduce feed conversion ratios in high-density cage operations. Soybean meal displaces fish meal across growth-stage formulations as price volatility in marine ingredients drives reformulation investments. Aquaculture farms represent the concentrated demand node, though fish hatcheries command specialized premium formulations with exacting larval nutrition protocols.
The EU Green Deal's Farm to Fork Strategy and REACH chemical registration frameworks constrain marine ingredient sourcing flexibility for European compounders, while Norway's national seafood regulator enforces strict maximum residue limits that cascade into feed raw material certification requirements. The US FDA exercises oversight through the Animal Food Safety Modernization Act, imposing hazard analysis protocols on imported feed additives that affect cross-border supply reliability. Stakeholders must monitor how emerging microbiome-targeted feed regulations in multiple jurisdictions reshape additive approval pathways and reformulation timelines.
Market Dynamics
Marine ingredient traceability mandates under the EU Green Deal's Farm to Fork Strategy are forcing compounders to restructure raw material sourcing networks and accelerate alternative protein validation timelines.
Growth Catalysts
- EU Green Deal traceability mandates:European aquaculture farms must document marine ingredient origins, creating pull for certified sustainable feed formulations across Norwegian salmon operations.
- Pangasius conversion in Vietnam:Mekong Delta producers are abandoning farm-made feeds for commercial extruded diets, expanding addressable market for compounders with localized production.
- Single-cell protein fermentation:Industrial biotechnology platforms are achieving commercial scale for bacterial and algal biomass that substitutes fish meal in grower diets.
Market Restraints
- Fish meal price volatility:Peruvian anchovy catch fluctuations and El Niño events transmit directly into formulation cost instability for marine protein-dependent diets.
- Soy supply concentration:Brazilian and Argentinian crushing capacity dominates global soybean meal trade, exposing compounders to South American logistics bottlenecks and currency exposure.
- Digestibility ceilings in plant proteins:Anti-nutritional factors in legume meals constrain inclusion rates below theoretical amino acid equivalence, preserving marine ingredient dependency.
Strategic Opportunities
- Indonesia's untapped marine finfish sector:Grouper and barramundi cage farming expansion outpaces local compounding capacity, creating import substitution potential for extruded feed suppliers.
- Carbon intensity labeling:EU CSRD scope 3 disclosure requirements position low-carbon feed formulations as procurement differentiators for integrated seafood groups.
- Insect meal regulatory clearance:EFSA novel food approvals for black soldier fly protein open formulation pathways previously blocked by regulatory uncertainty.
Industry Challenges
- Aquaculture nutritionist scarcity:Specialized expertise in larval stage micronutrient balancing remains concentrated among senior formulators at established compounders, constraining new entrant R&D velocity.
- Extrusion line retrofit costs:Transitioning from steam-pelleted to twin-screw extruded output demands seven-figure capital commitments for water stability and oil encapsulation performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Feed Market |
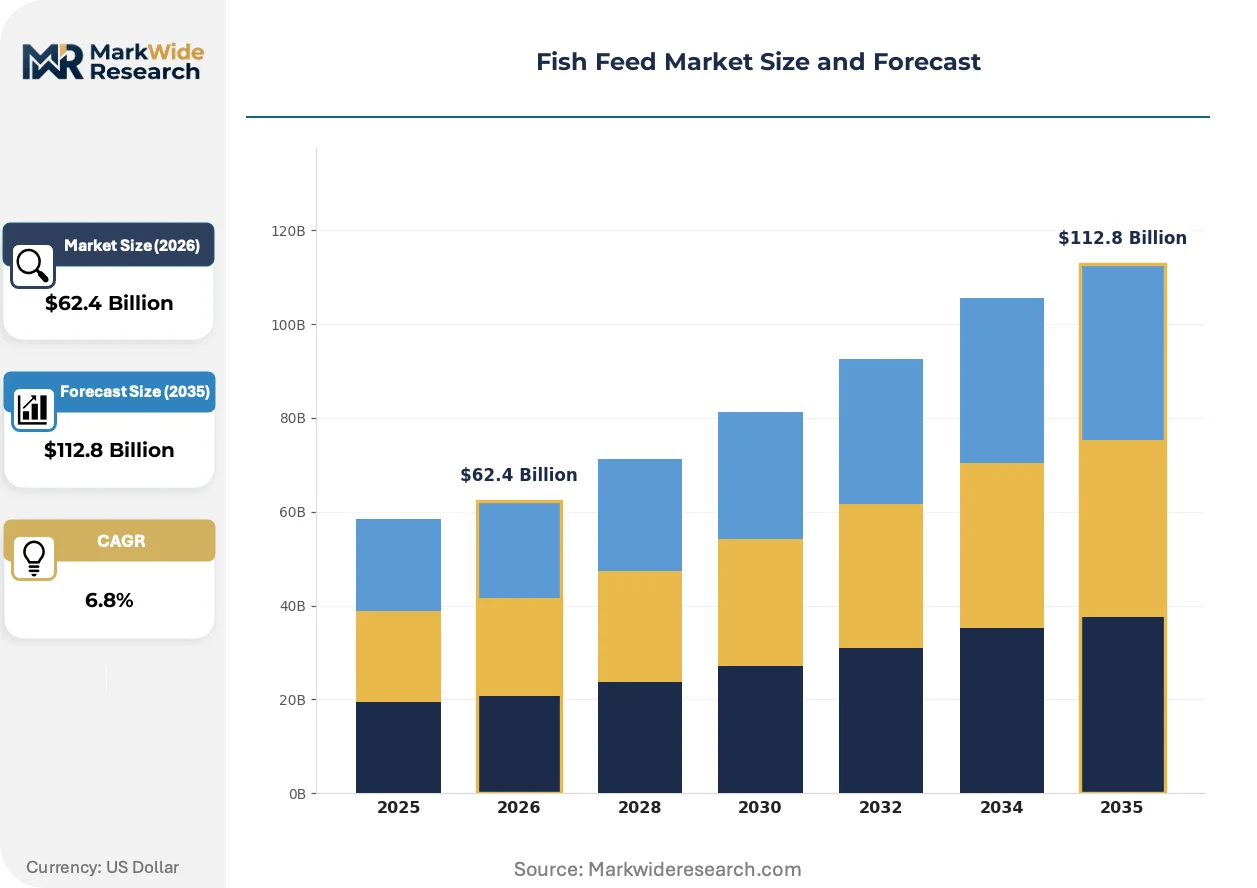
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Feed, Pelleted Feed, Liquid Feed, Powdered Feed Raw Material: Fish Meal, Soybean Meal, Wheat, Corn End User: Aquaculture Farms, Pet Stores, Research Institutions, Fish Hatcheries Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Cargill Incorporated, Nutreco N.V., Archer Daniels Midland Company, BioMar Group, Alltech Inc., Aller Aqua A/S, Ridley Corporation Limited, Koninklijke DSM N.V., Charoen Pokphand Foods PCL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Feed Market Emerging Trajectories
Precision formulation technologies and alternative protein platforms are compressing traditional raw material hierarchies while regulatory chemistry is rewriting approval pathways for novel ingredients.
Single-cell protein from methanotrophic bacteria is absorbing capital allocation from major compounders seeking supply security beyond agricultural commodity markets. Atlantic salmon integrators in Norway are running parallel validation trials at commercial scale. This biotechnology is absorbing risk exposure that previously concentrated in marine ingredient price cycles.
REACH chemical registration frameworks in Europe are extending evaluation timelines for novel feed additives, particularly those targeting gut microbiome modulation. The industrial consequence is delayed market entry for innovation pipelines and extended reliance on legacy additive portfolios. Functional feed specialists are responding by front-loading toxicology dossiers earlier in development cycles.
Integrated seafood groups are consolidating procurement decisions at headquarters level, displacing decentralized farm-level purchasing that historically favored local compounders. Vietnamese pangasius cooperatives and Chilean salmon farmers now negotiate annual volume contracts directly with multinational suppliers. This concentration is most visible in contract structures that bundle feed supply with technical advisory services.
Fish Feed Market Segmentation
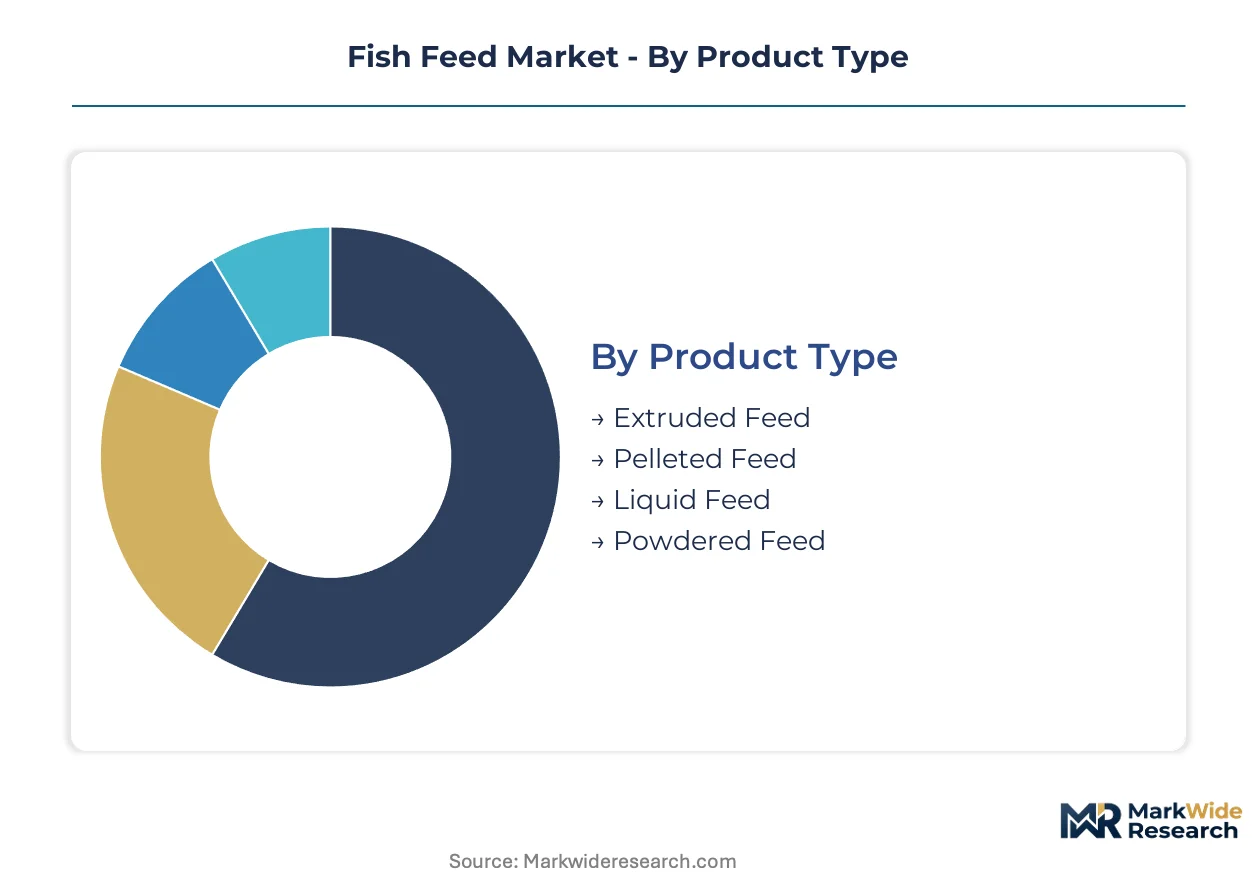
Segmentation in fish feed determines formulation complexity, procurement contracting structures, and margin architecture. Product format choices cascade into extrusion capital requirements, while raw material sourcing strategies expose compounders to distinct commodity volatility profiles across marine and agricultural supply basins.
Product Type:
Standalone feed formats operate independently of delivery systems, whereas embedded applications require compatibility with automated feeding infrastructure.
- Extruded Feed:High-temperature twin-screw processing creates porous matrices that encapsulate lipids and sustain water stability beyond 24 hours in cage operations. Norwegian salmon integrators specify extruded diets exclusively for their documented feed conversion ratio advantages in high-density marine sites.
- Pelleted Feed:Steam-conditioned compression produces denser, lower-cost diets suited to pond-based tilapia and carp systems where mechanical durability requirements moderate. Vietnamese pangasius cooperatives are converting from on-farm mixing to commercial pelleted diets as traceability mandates tighten.
- Liquid Feed:Emulsified suspensions for larval stages and recirculating aquaculture systems requiring precise nutrient dosing protocols.
- Powdered Feed:Micronized formulations for early-stage larvae and specialized research applications demanding exact particle size distribution.
Volume placements concentrate in extruded feed; the faster expansion belongs to liquid feed as marine hatchery intensification accelerates.
Raw Material:
Cost tier stratification separates premium marine-dependent formulations from commodity-anchored alternatives competing on price per kilogram delivered.
- Fish Meal:Peruvian anchovy reduction fisheries supply the benchmark marine protein with 60-72% crude protein content and superior amino acid digestibility coefficients. El Niño-driven catch volatility transmits directly into formulation cost instability for Atlantic salmon diets.
- Soybean Meal:Solvent-extracted defatted flakes from Brazilian crushing capacity anchor grower-stage formulations at 44-48% protein inclusion rates. Anti-nutritional factors in untreated meal constrain inclusion ceilings below theoretical amino acid equivalence.
- Wheat:Starch-rich binding agent improving pellet durability and water stability in temperate-zone carp and trout diets.
- Corn:Energy-dense carbohydrate source displacing wheat in price-sensitive tropical aquaculture markets.
Procurement volumes concentrate in soybean meal; fish meal retains premium positioning despite reformulation pressure.
End User:
Customer type determines order frequency, technical service intensity, and contract bundling structures across the value chain.
- Aquaculture Farms:Commercial grow-out operations purchasing bulk volumes on annual contracts with embedded technical advisory services. Integrated seafood groups in Chile and Norway now centralize procurement decisions at headquarters level.
- Fish Hatcheries:Larval-stage specialists demanding micronutrient-balanced live feed substitutes and precision-formulated weaning diets at premium pricing multiples.
- Pet Stores:Small-format ornamental fish retailers sourcing packaged specialty diets through wholesale distributors.
- Research Institutions:Low-volume, high-specification buyers requiring certified contaminant-free formulations for controlled studies.
Revenue concentration sits with aquaculture farms; hatchery diets command the steepest margin expansion trajectory.
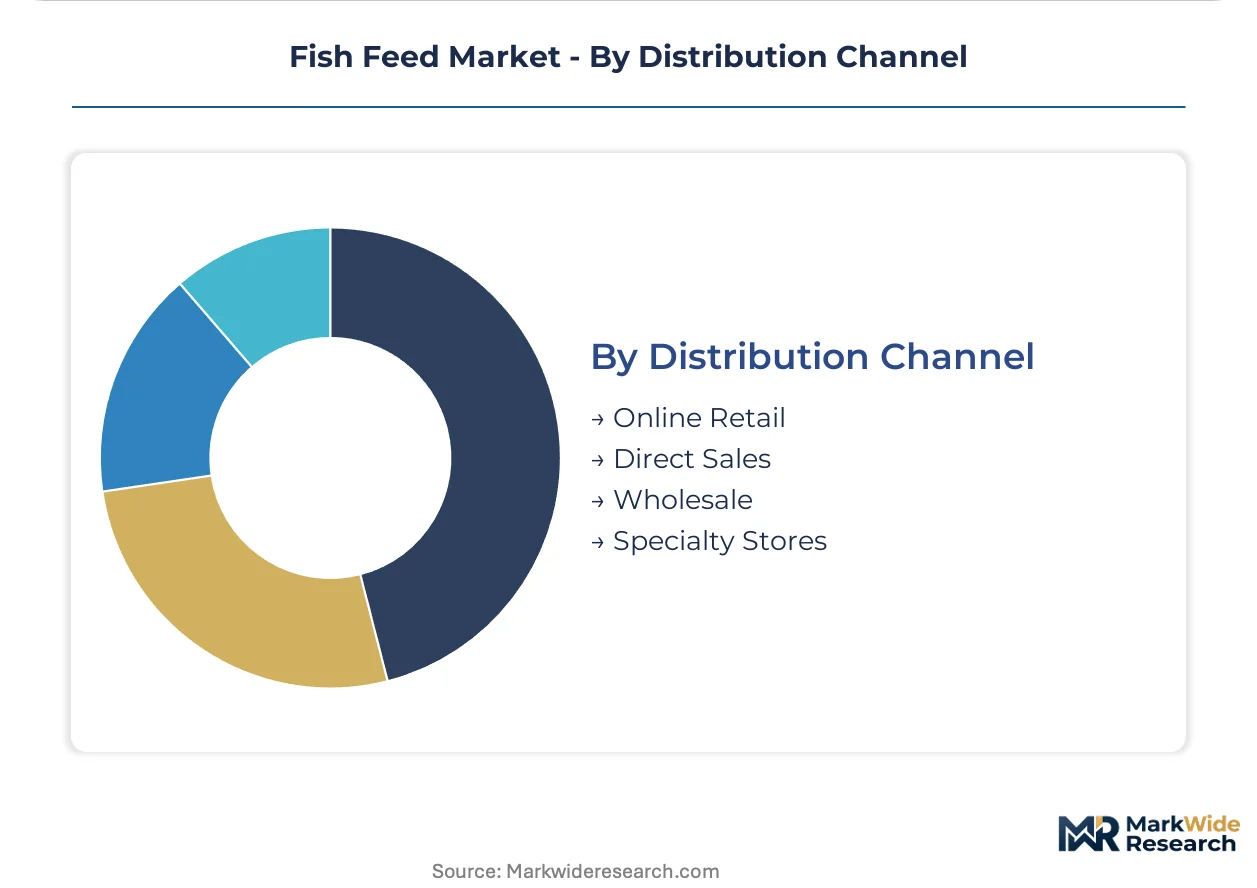
Distribution Channel:
Channel selection reflects order scale, geographic remoteness, and the value placed on technical support proximity.
- Direct Sales:Multinational compounders negotiate annual volume contracts directly with Vietnamese pangasius cooperatives and Chilean salmon integrators, bundling feed supply with on-site nutritionist advisory.
- Wholesale:Regional distributors aggregate fragmented demand from smallholder pond farmers across Indonesia's grouper cage farming zones.
- Online Retail:E-commerce platforms penetrating ornamental and small-scale aquaculture segments with packaged specialty formulations.
- Specialty Stores:Localized agricultural supply retailers serving remote farming communities with limited cold-chain logistics reach.
Transaction volumes flow through direct sales; online retail is gaining share fastest among non-commercial buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in coastal zones with cold-water cage infrastructure, while consumption pulls toward tropical aquaculture belts converting from farm-made to commercial diets. This geographic split shapes procurement contracting and raw material sourcing networks across distinct regulatory environments.
Norway
Atlantic salmon integrators in the fjord regions drive formulated feed volumes as the national seafood regulator enforces strict maximum residue limits cascading into raw material certification requirements. The EU Green Deal's Farm to Fork Strategy tightens marine ingredient traceability, compelling compounders to restructure sourcing networks. Bergen and Trondheim harbor clusters where extruded feed production scales to service high-density marine sites.
Vietnam
Pangasius producers across the Mekong Delta are abandoning farm-made feeds for commercial extruded diets, expanding addressable market for compounders with localized production. The country's fisheries ministry implements aquaculture development programs accelerating conversion timelines. Can Tho and An Giang provinces concentrate cage farming operations where feed procurement is shifting to annual volume contracts with multinational suppliers.
Indonesia
Grouper and barramundi cage farming expansion in the archipelago outpaces local compounding capacity, creating import substitution potential for extruded feed suppliers. The national aquaculture agency promotes marine finfish sector development through infrastructure investment schemes. Batam and Sulawesi coastal zones concentrate hatchery intensification demanding specialized larval nutrition formulations.
Chile
Salmon farming operations in the Los Lagos and Aysén regions centralize procurement decisions at headquarters level, displacing decentralized farm-level purchasing. The national fisheries service enforces sanitary regulations affecting feed additive approval pathways. Puerto Montt anchors processing infrastructure where integrated seafood groups negotiate bundled feed supply with technical advisory services.
United States
Catfish producers in the Mississippi Delta and emerging recirculating aquaculture systems in landlocked states pull diversified feed formats. The FDA exercises oversight through the Animal Food Safety Modernization Act, imposing hazard analysis protocols on imported feed additives. Auburn, Alabama and Davis, California host university research clusters advancing precision formulation technologies for domestic species.
Fish Feed Market Vendor Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive soy processing networks and specialized marine nutrition specialists commanding premium hatchery segments. Three archetypes dominate: diversified agricultural processors leveraging commodity scale, dedicated aquaculture compounders with species-specific formulation depth, and biotechnology platforms commercializing single-cell proteins. Consolidation proceeds through acquisition of regional feed mills and strategic partnerships for alternative protein validation.
Within the integrated processor tier, Cargill Incorporated and Archer Daniels Midland Company exemplify commodity-scale players with South American supply basin exposure. BioMar Group and Nutreco N.V. occupy positions among dedicated aquaculture specialists, with the former anchoring marine hatchery diet capabilities and the latter representing sustained R&D intensity in functional additives. Charoen Pokphand Foods PCL sits within the Asia-Pacific regional champion archetype, reflecting Thai agribusiness conglomerate structure with integrated seafood value chain participation.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Nutreco N.V. |
| Archer Daniels Midland Company |
| BioMar Group |
| Alltech Inc. |
| Aller Aqua A/S |
| Ridley Corporation Limited |
| Koninklijke DSM N.V. |
| Charoen Pokphand Foods PCL |
| Others |
Supply Flow & Price Mechanics
EU Green Deal traceability mandates gate qualified supply access and premium-tier pricing power, compelling compounders to invest in certified marine ingredient sourcing networks that Atlantic salmon integrators in Norway now require for contract eligibility.
Pricing Analysis
Margin tightening in standard-grade formulations reflects Brazilian soybean meal price volatility and anti-nutritional factor processing costs. Three-tier pricing structure across premium, standard, and economy levels separates marine-dependent hatchery diets from grower-stage plant-protein formulations. Cost-down pressure on economy tiers accelerates because Vietnamese pangasius cooperatives negotiate annual volume contracts with embedded technical advisory bundles. Smallholder pond farmers in Indonesia exhibit highest price sensitivity; Norwegian salmon integrators demonstrate lowest sensitivity due to feed conversion ratio performance premiums.
Supply Chain Analysis
Certification requirements for marine ingredient traceability concentrate qualified supply among Peruvian anchovy reduction fisheries, Brazilian soy crushing complexes, and Norwegian extrusion facilities. Raw material sourcing draws from fish meal, soybean meal, and single-cell protein fermentation platforms. Commodity price volatility in marine ingredients constitutes the dominant structural risk, transmitting El Niño-driven catch fluctuations directly into formulation costs. Distribution runs through direct annual contracts with integrated seafood groups, displacing fragmented farm-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compounders face a vertical-integration race where captive soy processing networks and alternative protein fermentation capacity determine cost position and supply security.
For Market Incumbents: Anticipate regulatory chemistry extending additive approval timelines by front-loading toxicology dossiers for microbiome-targeted formulations. Secure backward integration into South American soy supply basins to defend margin position against currency exposure and logistics bottlenecks. Counter single-cell protein entrants by accelerating commercial-scale validation trials with Atlantic salmon integrators in Norway. For New Entrants and Emerging Players: Regional distributors serving Indonesia's grouper cage farming zones represent the most penetrable channel partner type for localized extruded feed supply. Target marine hatchery diet segments where specialized larval nutrition expertise commands premium pricing multiples. Pursue import substitution in Batam and Sulawesi coastal zones where domestic compounding capacity lags cage farming expansion. For Investors and Strategic Acquirers: EFSA novel food approvals for insect meal are the leading indicator that regulatory clearance pathways for alternative proteins are stabilizing. Long-term viability hinges on biotechnology platforms achieving commercial scale beyond agricultural commodity markets. Monitor parallel validation trial announcements from major compounders as the primary inflection signal for single-cell protein adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soy Processing | Cargill's South American supply basin control insulates compounders from Brazilian logistics bottlenecks and currency volatility. |
| Single-Cell Protein Scale-Up | Methanotrophic bacterial biomass fermentation absorbs marine ingredient price cycle exposure for Atlantic salmon diets. |
| Marine Hatchery Diet Specialization | BioMar's larval nutrition protocols command premium positioning in intensifying barramundi and grouper hatchery sectors. |
| Direct Sales Channel Consolidation | Annual volume contracts with Vietnamese pangasius cooperatives displace fragmented local compounder relationships. |
| Alternative Protein Regulatory Clearance | EFSA novel food approvals for black soldier fly protein unlock formulation pathways previously blocked by uncertainty. |
Methodological Framework
Trade databases, regulatory filings, and aquaculture production statistics formed the secondary backbone, supplemented by primary interviews with compounder procurement directors, marine hatchery nutritionists, and integrated seafood group supply chain managers. Bottom-up volume estimates derived from species-specific feed conversion ratios and cage farming intensity metrics were cross-validated against top-down market sizing from customs records and industry association disclosures.
Bottom-up modeling segmented the market by product format, raw material composition, end-user type, and distribution channel across the projection horizon. CAGRs were derived from trend extrapolation of extrusion capacity expansion, pangasius diet conversion rates, and single-cell protein commercialization timelines. Industry-specific forecast inputs included Peruvian anchovy catch variability, EU Green Deal implementation pacing, and Indonesian marine finfish sector infrastructure investment flows.
Caveats apply where El Niño frequency intensification, REACH chemical registration timeline extensions, or microbiome-targeted feed regulatory shifts could materially shift the outlook. A model refresh is warranted upon material change in marine ingredient traceability mandate enforcement stringency or alternative protein platform commercial scale achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Rice-Based Products Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market