
 India Acetic Acid Market | 2026-2036
India Acetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
India Acetic Acid Market Insights
Membrane-based methanol carbonylation is reconfiguring production economics for Indian acetic acid manufacturers. Gujarat Narmada Valley Fertilizers & Chemicals Limited leverages its integrated ammonia-methanol complex to sustain captive feedstock supply for acetic acid output. Jubilant Ingrevia Limited anchors its position through specialized acetate ester derivatives serving pharmaceutical solvent demand. GODAVARI BIOREFINERIES LTD competes via ethanol-based fermentation routes that differentiate its product for food-grade and specialty chemical segments.
Acetic acid (CH₃COOH) is a carboxylic acid with a minimum purity of 99.5% in glacial form, produced industrially through methanol carbonylation or ethanol oxidation, serving primarily as a chemical intermediate and solvent across polymer, pharmaceutical, and food processing industries. Glacial acetic acid dominates volume flows into vinyl acetate monomer and purified terephthalic acid chains where margin pools concentrate with integrated petrochemical players. Acetate esters represent the fastest-growing product category as coatings and adhesives manufacturers in Maharashtra and Gujarat shift toward low-VOC solvent systems. The food preservative application maintains steady offtake from pickling and condiment processors operating under FSSAI-mandated additive limits.
Bureau of Indian Standards specifications for glacial acetic acid purity and Food Safety and Standards Authority of India additive codes shape product certification requirements and market access for domestic producers and importers. Central Pollution Control Board effluent norms for acetic acid manufacturing units are forcing coastal Gujarat facilities to adopt zero-liquid-discharge systems that raise capital intensity but reduce regulatory risk. Stakeholders must monitor how Petroleum, Chemicals and Petrochemicals Investment Region incentives and proposed green hydrogen mandates alter feedstock cost structures for methanol-based acetic acid routes.
Market Dynamics
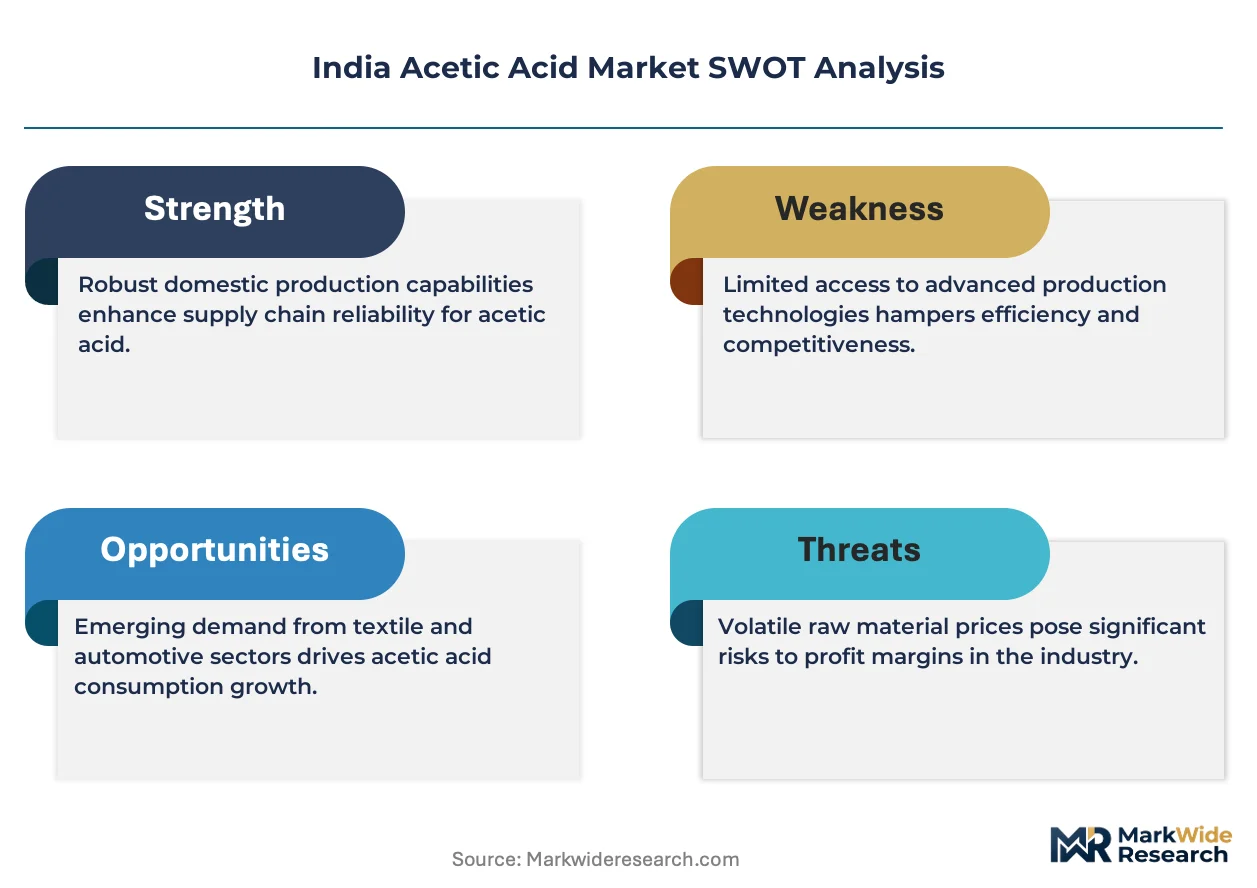
Membrane-based methanol carbonylation is compressing production costs for Indian acetic acid manufacturers while BIS purity mandates force technology upgrades across Gujarat and Maharashtra facilities. This dual pressure of cost optimization and regulatory compliance is restructuring competitive positioning in the sector.
Growth Catalysts
- Vinyl Acetate Monomer Expansion:Petrochemical clusters near Vadodara and Mumbai are scaling VAM output for adhesives and coatings, pulling glacial acetic acid volumes upward through captive offtake arrangements.
- FSSAI Additive Codes:Food Safety and Standards Authority of India regulations for pickling and condiment preservatives sustain steady demand from processed food manufacturers seeking compliant acid grades.
- Low-VOC Solvent Transition:Coatings formulators in western India are substituting traditional solvents with acetate esters, accelerating consumption of acetic acid derivatives in environmentally compliant formulations.
Market Restraints
- Methanol Price Volatility:Feedstock costs fluctuate with imported natural gas-linked methanol pricing, squeezing margin stability for carbonylation-based producers lacking captive ammonia-methanol integration.
- Coastal Gujarat Supply Concentration:Bulk production capacity clusters along the Gulf of Khambhat, exposing buyers to single-region disruption risks from cyclonic events or port logistics constraints.
- Ethanol Oxidation Yield Limits:Fermentation-route manufacturers face inherent conversion efficiency ceilings that cap output scale relative to petrochemical-based competitors.
Strategic Opportunities
- Petroleum, Chemicals and Petrochemicals Investment Region Incentives:PCPIR tax holidays and infrastructure subsidies for greenfield acetic acid units in Dahej and Mundra reduce breakeven thresholds for new entrants.
- Pharmaceutical Solvent Specialization:Acetate ester derivatives for active pharmaceutical ingredient synthesis remain underpenetrated versus commodity VAM offtake, offering premium pricing capture.
- Zero-Liquid-Discharge Technology Adoption:Central Pollution Control Board effluent norms are creating first-mover advantages for coastal facilities that retrofit membrane bioreactor systems ahead of enforcement deadlines.
Industry Challenges
- Membrane Cell Technician Scarcity:Specialized operations and maintenance expertise for Monsanto/BP process technology remains concentrated among a limited pool of trained engineers in Gujarat.
- BIS Certification Timelines:Bureau of Indian Standards testing protocols for food-grade purity specifications extend product approval cycles, delaying market access for new fermentation-route entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Acetic Acid Market |
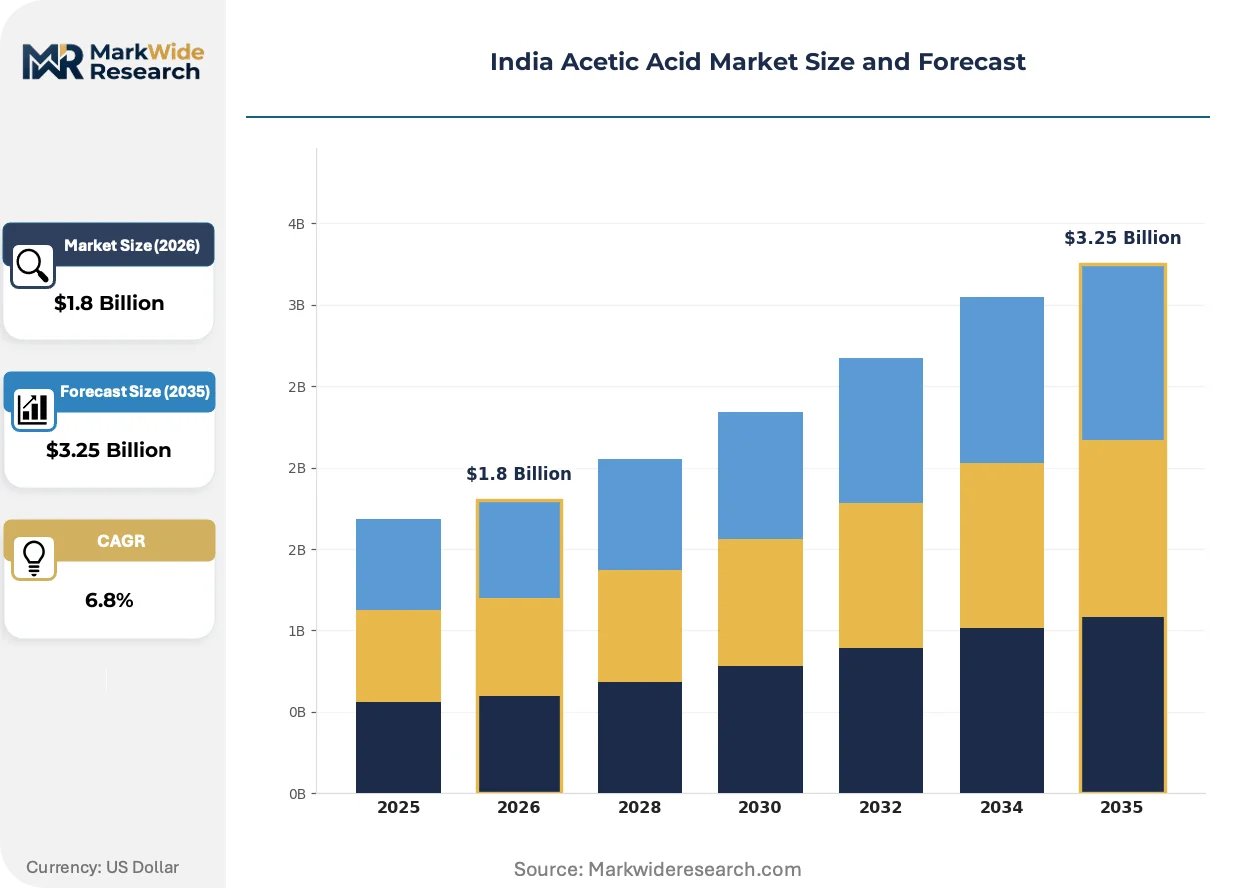
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glacial Acetic Acid, Diluted Acetic Acid, Acetic Anhydride, Acetate Esters End User: Food & Beverage, Textile, Chemicals, Plastics Application: Food Preservative, Solvent, Varnish, Adhesive Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | Gujarat Narmada Valley Fertilizers & Chemicals Limited, Celanese Corporation, Jubilant Ingrevia Limited, GODAVARI BIOREFINERIES LTD, Assam Bio-Refinery Private Limited, Anupam Rasayan India Ltd, Tanfac Industries Ltd, Indian Oil Corporation Limited, Reliance Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Acetic Acid Market Trends and Innovations
Process intensification and regulatory tightening are converging to reshape how Indian acetic acid manufacturers configure production assets and qualify product grades for end-use markets.
Catalytic methanol carbonylation systems is hybridizing with advanced membrane separation units to boost carbon monoxide conversion efficiency while reducing catalyst consumption rates. Integrated petrochemical complexes in Dahej are deploying these hybrid configurations to defend margin positions against standalone fermentation competitors. The technology is hybridizing operational economics by enabling smaller-scale units to achieve parity with world-scale carbonylation plants.
FSSAI's tightened additive purity specifications for food-grade acetic acid are forcing fermentation-route producers to retrofit distillation columns and install additional filtration stages. Bureau of Indian Standards has synchronized its glacial acetic acid standards with Codex Alimentarius benchmarks, raising import compliance barriers for non-certified suppliers. Maharashtra-based pickling processors are now demanding batch-specific certificates of analysis, shifting supplier qualification from price-based to documentation-intensive selection.
Direct procurement contracts between VAM manufacturers and acetic acid producers are displacing traditional distributor-mediated supply chains in western India. Large coatings formulators in Mumbai-Pune industrial corridor are negotiating quarterly volume commitments with membrane-cell operators to secure priority allocation during feedstock shortage periods. This concentration of buying power is most visible in Gujarat, where three petrochemical clusters now account for the majority of glacial acid offtake through bilateral agreements rather than spot market transactions.
India Acetic Acid Market Segmentation
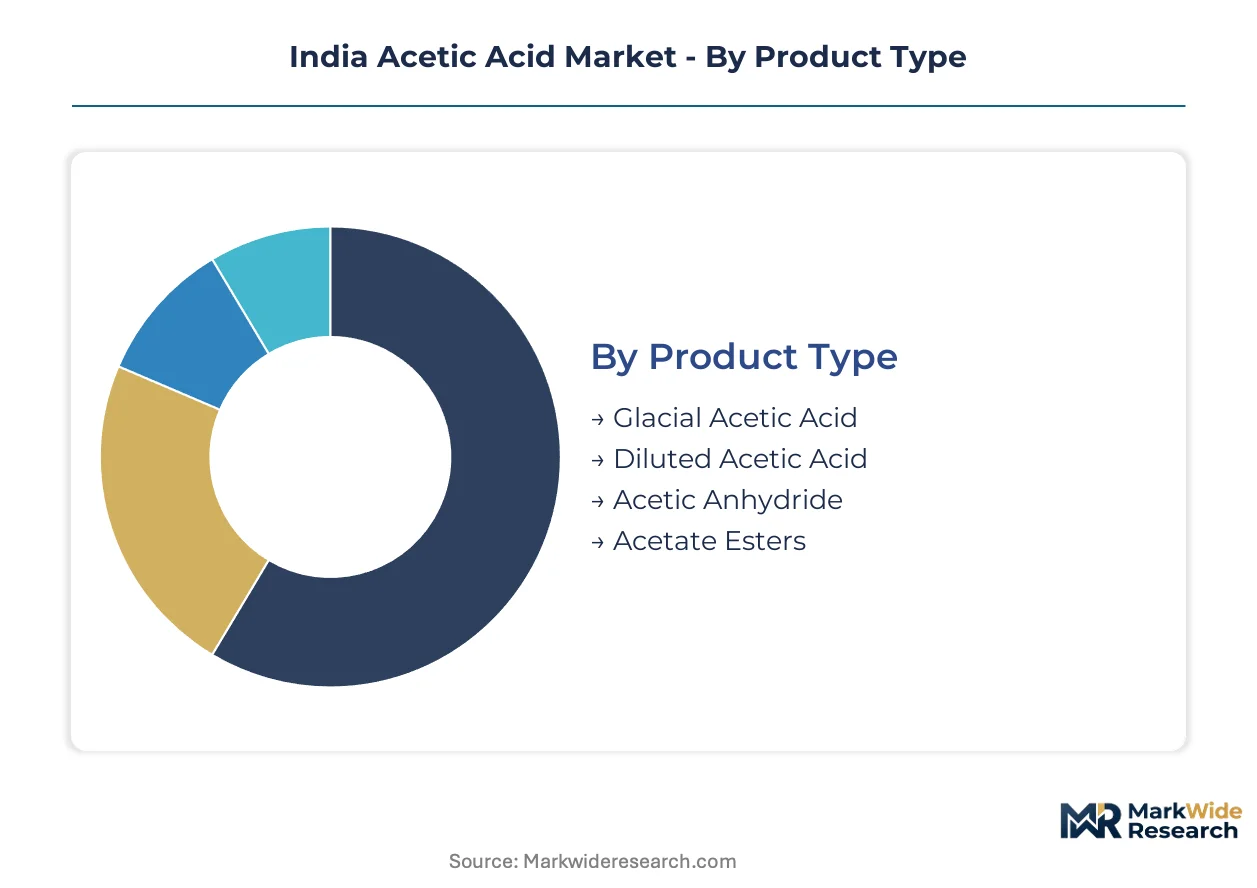
Acetic acid consumption patterns in India diverge sharply across purity grades and end-use specifications. BIS certification requirements and feedstock route economics create distinct competitive arenas within each segment category.
Product Type:
The use-case spectrum spans commodity chemical intermediates through specialized reagent grades, with production technology determining margin capture.
- Glacial Acetic Acid:Minimum 99.5% purity specification serves vinyl acetate monomer synthesis and purified terephthalic acid production. Petrochemical clusters in Vadodara and Mumbai absorb bulk volumes through captive offtake arrangements with integrated methanol carbonylation operators.
- Acetate Esters:Derivative solvents including ethyl acetate and butyl acetate target low-VOC coating formulations. Maharashtra-based coatings manufacturers are substituting traditional aromatic solvents, pulling demand growth fastest in western India industrial corridors.
- Diluted Acetic Acid:10-80% concentration grades serve food processing and textile neutralization applications under FSSAI-mandated additive limits.
- Acetic Anhydride:Dehydrated derivative for cellulose acetate and pharmaceutical acetylation reactions, produced through controlled pyrolysis of acetic acid.
The dominant share belongs to Glacial Acetic Acid, while Acetate Esters is closing the gap fastest.
End User:
Cost tier stratification separates bulk commodity offtake from premium-certified specialty grades.
- Chemicals:Intermediate consumption for vinyl acetate monomer, acetic anhydride, and acetate ester manufacturing anchors volume demand. Dahej and Mundra petrochemical complexes source directly through pipeline-linked supply contracts.
- Food & Beverage:Pickling, condiment, and preservative applications require FSSAI-compliant food-grade certification with batch-specific purity documentation. Gujarat fermentation-route producers compete on documentation intensity rather than scale.
- Plastics:Purified terephthalic acid chain feedstock for polyester resin production, concentrated with integrated PTA manufacturers.
- Textile:Neutralization agent in dyeing processes and cellulose acetate fiber production, with demand concentrated in Surat and Tirupur processing hubs.
Chemicals commands the largest volume share, though Food & Beverage is expanding most quickly as processed food certification requirements tighten.
Application:
Volume concentration tracks the geographic clustering of downstream manufacturing capacity.
- Solvent:Acetate ester formulations for coatings, adhesives, and pharmaceutical extraction processes. Mumbai-Pune industrial corridor formulators are negotiating quarterly volume commitments to secure allocation priority.
- Food Preservative:Acidulant and antimicrobial agent in pickling brines and condiment formulations, governed by FSSAI additive code limits on residual concentrations.
- Adhesive:Vinyl acetate monomer-derived emulsion binders for wood glue and packaging applications.
- Varnish:Cellulose acetate lacquer formulations for automotive and furniture finishing.
Solvent dominates current offtake, while Food Preservative is gaining share fastest as packaged food penetration deepens in tier-2 cities.
Distribution Channel:
Customer type and procurement scale determine channel selection, with bulk consumers bypassing intermediaries entirely.
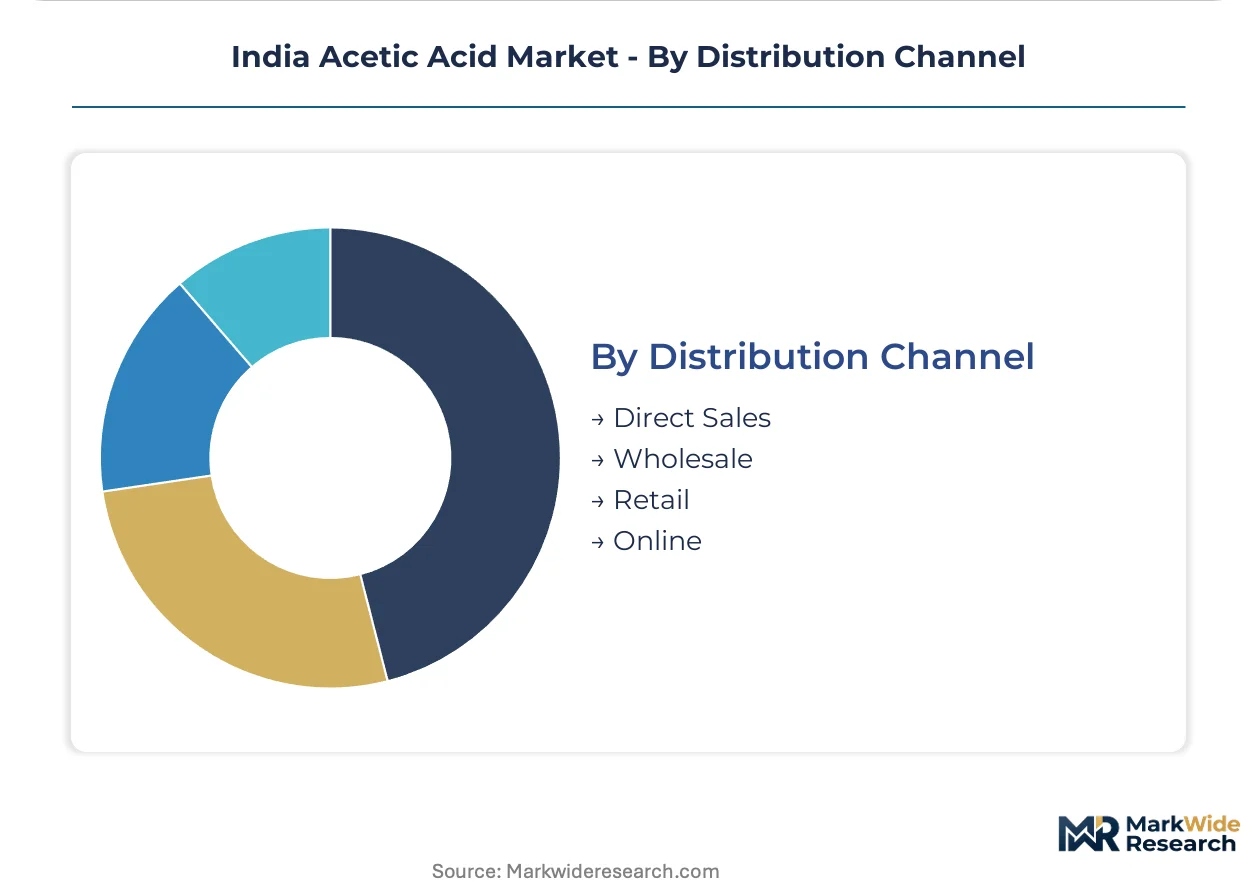
- Direct Sales:Bilateral contracts between acetic acid producers and VAM or PTA manufacturers displace traditional distributor relationships. Three Gujarat petrochemical clusters now execute the majority of glacial acid procurement through direct agreements.
- Wholesale:Regional distributors serve mid-scale coatings and textile processors with standardized grade availability and credit terms.
- Retail:Small-volume packaging for laboratory reagent and specialty food-grade applications.
- Online:Emerging platform-based procurement for standardized industrial grades with documented certificates of analysis.
Direct Sales holds the dominant position, though Wholesale maintains relevance for geographically dispersed processors outside pipeline-connected zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's acetic acid trade balance tilts toward import dependency for food-grade and specialty grades, while western states generate surplus glacial acid for domestic chemical offtake. Regional production capacity clusters along the Gulf of Khambhat and Mumbai industrial corridor, creating distinct supply-demand dynamics across state boundaries.
Gujarat
Dahej and Mundra petrochemical complexes anchor bulk carbonylation capacity serving vinyl acetate monomer and purified terephthalic acid manufacturers. PCPIR tax incentives and infrastructure subsidies reduce breakeven thresholds for greenfield membrane-cell units. Coastal facilities face Central Pollution Control Board zero-liquid-discharge mandates that raise capital intensity but lower regulatory risk for early adopters.
Maharashtra
Mumbai-Pune industrial corridor absorbs glacial acetic acid volumes through pipeline-linked supply contracts with integrated petrochemical players. Coatings formulators in Thane and Pune districts negotiate quarterly volume commitments to secure priority allocation during methanol feedstock shortages. FSSAI additive codes for pickling processors in Nashik and Sangli sustain steady demand for certified food-grade acid with batch-specific documentation.
Tamil Nadu
Tirupur textile processing hubs consume diluted acetic acid grades for dye neutralization and cellulose acetate fiber production. Surat-Mumbai supply chains extend southward through distributor networks serving mid-scale processors outside pipeline-connected zones. State industrial policy incentives for chemical manufacturing remain underutilized relative to western India clusters.
Andhra Pradesh
Visakhapatnam port infrastructure enables methanol import flows for potential carbonylation capacity expansion. Petroleum, Chemicals and Petrochemicals Investment Region designation for Kakinada offers tax holidays comparable to Gujarat facilities. Current acetic acid consumption concentrates in pharmaceutical solvent demand from Hyderabad-based active pharmaceutical ingredient manufacturers.
Assam
Bamboo-based ethanol feedstock availability supports fermentation-route acetic acid production targeting food-grade and specialty chemical segments. Northeast industrial corridor development programs aim to reduce dependency on western India supply chains. Guwahati-based processors currently source diluted grades through wholesale distributor networks with extended lead times.
India Acetic Acid Market Competitive Landscape
On the supply side, the industry is consolidating around integrated petrochemical complexes with captive methanol-ammonia integration, while fermentation-route specialists occupy niche food-grade segments. Three archetypes dominate: state-linked fertilizer-chemical conglomerates with backward integration into feedstock, diversified industrial groups with petrochemical scale advantages, and regional biorefinery operators with ethanol oxidation capabilities. Capacity expansion through membrane technology upgrades and strategic partnerships for pharmaceutical solvent specialization represent the primary competitive vectors.
Among domestic producers, Gujarat Narmada Valley Fertilizers & Chemicals Limited exemplifies the integrated petrochemical archetype through its captive ammonia-methanol complex position. Jubilant Ingrevia Limited occupies a specialist role in acetate ester derivatives serving pharmaceutical applications. GODAVARI BIOREFINERIES LTD represents the fermentation-route differentiation strategy for food-grade certification compliance.
| Leading Market Players |
|---|
| Gujarat Narmada Valley Fertilizers & Chemicals Limited |
| Celanese Corporation |
| Jubilant Ingrevia Limited |
| GODAVARI BIOREFINERIES LTD |
| Assam Bio-Refinery Private Limited |
| Anupam Rasayan India Ltd |
| Tanfac Industries Ltd |
| Indian Oil Corporation Limited |
| Reliance Industries Limited |
| Others |
Pricing and Supply Chain Analysis
Methanol price volatility tied to imported natural gas benchmarks determines both the spread between carbonylation and fermentation-route pricing tiers and the geographic clustering of production capacity along coastal Gujarat. Buyers face divergent cost structures depending on whether suppliers maintain captive ammonia-methanol integration or rely on spot feedstock procurement.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for glacial acetic acid, with pricing stratifying across food-grade certified, industrial-grade, and commodity VAM-feedstock tiers. Price differentiation rests on BIS certification intensity and volume scale, with pharmaceutical solvent buyers showing least price sensitivity due to documentation requirements. Cost compression in commodity grades is intensifying because membrane technology upgrades are compressing production economics for carbonylation operators. Spot market participants in Maharashtra coatings clusters exhibit highest price sensitivity, shifting procurement timing with methanol futures movements.
Supply Chain Analysis
Export-control regimes on Monsanto/BP membrane cell technology limit technology transfer to Indian engineering procurement, constraining capacity expansion outside established Gujarat facilities. Manufacturing concentrates in India, with methanol feedstock drawing from Oman, Qatar, and domestic coal-gasification pilots. Supply chain risk centers on single-source vulnerability for specialized membrane maintenance technicians concentrated in Vadodara. Distribution runs through pipeline-linked direct sales to petrochemical clusters, supplemented by wholesale networks serving textile processors in Tamil Nadu and Assam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India acetic acid market sits in a cyclical recovery phase as petrochemical capacity expansion in Dahej and Mundra drives VAM demand upward. Methanol feedstock cost normalization following energy price volatility supports margin restoration for integrated producers.
For Market Incumbents: Pre-empt fermentation-route competition by accelerating BIS certification timelines for food-grade output and securing pipeline exclusivity with Mumbai-Pune coatings formulators. Membrane cell technician scarcity threatens operational uptime; captive training programs at Gujarat Narmada Valley Fertilizers & Chemicals Limited and Jubilant Ingrevia Limited facilities create defensive moats. Backward integration into methanol-ammonia complexes remains the priority lever against feedstock volatility.
For New Entrants and Emerging Players: Build out pharmaceutical solvent specialization capacity in Andhra Pradesh, where Hyderabad-based API manufacturers remain underserved versus commodity VAM offtake. Assam's bamboo-ethanol feedstock availability supports fermentation-route differentiation for FSSAI-certified food-grade acid with premium documentation intensity. Direct procurement relationships with Nashik and Sangli pickling processors offer the most penetrable entry path outside western India petrochemical clusters.
For Investors and Strategic Acquirers: BIS purity specification tightening reshapes the acquisition landscape toward fermentation-route assets with existing food-grade certification infrastructure. Five-to-ten-year viability favors biorefinery operators with ethanol oxidation capabilities and established FSSAI compliance documentation. The signal to watch is PCPIR incentive utilization rates in Dahej and Mundra, which indicate greenfield membrane-cell deployment appetite.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Upgrade | BP/Monsanto process retrofits compress catalyst consumption rates for Gujarat carbonylation operators. |
| Backward Integration into Methanol | Captive ammonia-methanol complexes at GNFC insulate margin stability from imported feedstock volatility. |
| Pharmaceutical Solvent Specialization | Acetate ester derivatives for API synthesis command premium pricing from Hyderabad manufacturers. |
| Zero-Liquid-Discharge Retrofit | CPCB effluent compliance at coastal facilities reduces regulatory enforcement risk ahead of deadlines. |
| Food-Grade Certification Investment | FSSAI additive code synchronization with Codex Alimentarius opens export pathways for fermentation-route producers. |
Research Methodology
The analysis maps methanol carbonylation, ethanol oxidation, and acetate ester derivative sub-sectors, each validated through plant managers at Gujarat and Maharashtra facilities, procurement leads at VAM and PTA manufacturers, distribution channel partners serving Tamil Nadu textile hubs, and technical R&D directors overseeing membrane cell operations. Primary interview findings triangulated against BIS certification records, Central Pollution Control Board effluent compliance filings, FSSAI additive code registrations, and customs trade data for methanol import flows. Bottom-up capacity utilization estimates and top-down end-use consumption models were reconciled across verification rounds.
Assumptions held fixed include BIS purity specification enforcement timelines, PCPIR tax incentive availability, and FSSAI additive code alignment with Codex Alimentarius benchmarks. Variables stress-tested encompass methanol price volatility bands, membrane cell technology transfer licensing conditions, and cyclonic disruption frequency for Gulf of Khambhat facilities. The forecast framework models grade tier, end-use industry, and regional production hub segmentation dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections tied to VAM and PTA capacity expansion schedules, with pharmaceutical solvent demand growth calibrated against API manufacturing output trends.
Stress conditions across methanol feedstock pricing, membrane technician availability, and coastal logistics disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions that PCPIR infrastructure subsidies sustain greenfield project economics and that BIS certification timelines do not extend beyond current procedural benchmarks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Industrial Phosphate Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
2,3-Butanediol Market