
 Profenofos Market | 2026-2036
Profenofos Market Size, Share, and Industry Trends Forecast 2026-2036
Profenofos Market Analytics
Precision formulation technologies are reshaping how agrochemical active ingredients reach target pests with reduced off-target drift. Syngenta Group leverages micro-encapsulation platforms to extend residual control in tropical cotton systems. UPL Ltd anchors its position through backward integration into technical-grade manufacturing in India. BASF SE differentiates via co-formulation partnerships that combine profenofos with synergists.
Profenofos is an organophosphate insecticide and acaricide with the chemical formula C11H15BrClO3PS, functioning as a cholinesterase inhibitor that disrupts nervous system function in lepidopteran and hemipteran pests. Manufacturers synthesize the compound through phosphorus tribromide-mediated chlorination of hydroxyl precursors, yielding emulsifiable concentrate formulations for foliar spray deployment against bollworm and whitefly infestations. Emulsifiable concentrate formulations dominate volume shipments due to established farmer familiarity and compatibility with existing spray equipment across South Asian cotton belts. Wettable powder grades capture premium positioning in greenhouse applications where residue limits drive formulation selection.
India's Central Insecticides Board mandates registration under the Insecticides Act for all profenofos formulations sold domestically. The European Food Safety Authority evaluates maximum residue limits under Regulation (EC) No 396/2005, restricting import tolerance for treated commodities. The United States Environmental Protection Agency maintains reregistration eligibility decisions under FIFRA that govern export-oriented production from Indian and Chinese technical manufacturers. Stakeholders must monitor evolving residue thresholds in destination markets to sustain product registrations and protect trade corridors.
Market Dynamics
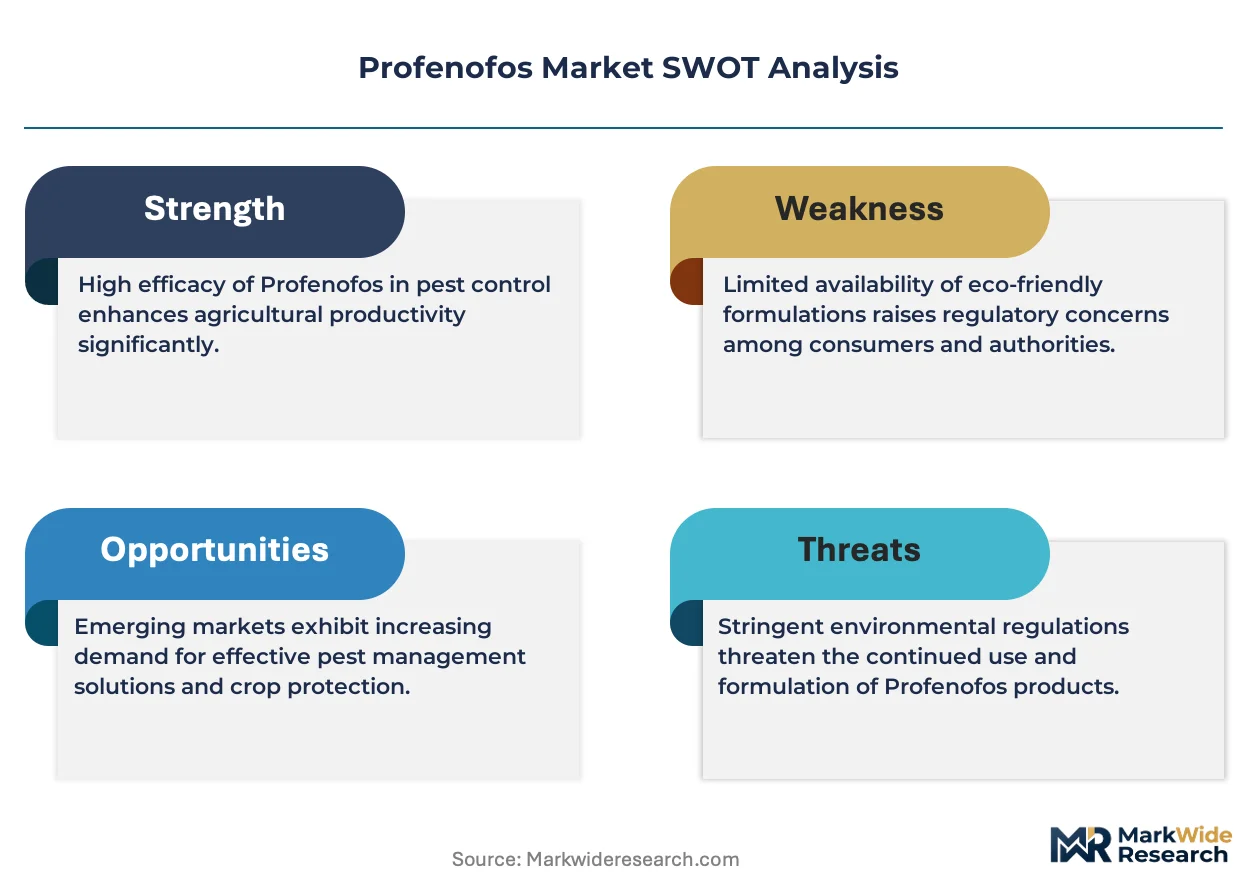
The profenofos market pivots on tightening maximum residue limits in export destination markets, forcing reformulation investments and technical-grade purification upgrades across Indian and Chinese supply bases.
Growth Catalysts
- Integrated pest management expansion:Maharashtra and Gujarat state agriculture departments mandate IPM protocols in cotton belts, creating structured demand for organophosphate rotation partners.
- REACH registration pathways:ECHA's updated data requirements for existing active ingredients create first-mover advantages for technical manufacturers with complete toxicology dossiers.
- Emulsifiable concentrate durability:Tropical humidity and monsoon spray windows favor EC formulations with extended field stability over wettable powder alternatives.
Market Restraints
- Phosphorus tribromide feedstock volatility:Bromine extraction costs from Dead Sea and Arkansas brine operations transmit directly to technical synthesis economics.
- EU import tolerance compression:EFSA's cumulative dietary exposure assessments under Regulation (EC) No 396/2005 narrow residue headroom for cottonseed and vegetable commodities.
- Neonicotinoid substitution in seed treatment:Imidacloprid and thiamethoxam soil applications displace early-season foliar organophosphate sprays in Gujarat's Bt cotton zones.
Strategic Opportunities
- Telangana state penetration:The Khammam and Warangal cotton corridors remain underdeveloped for profenofos distribution relative to Maharashtra and Gujarat saturation.
- Synergist co-formulation development:Piperonyl butoxide combinations restore efficacy against pyrethroid-resistant Helicoverpa armigera populations in Andhra Pradesh.
- Drone spray compatibility:Ultra-low volume formulations calibrated for agricultural UAV deployment open channel access through agritech service providers.
Industry Challenges
- Analytical chemist scarcity:GLP-compliant residue testing facilities face recruitment gaps for chromatography specialists capable of generating EFSA-acceptable data packages.
- Registration dossier timelines:India's Central Insecticides Board review queues extend submission-to-approval intervals beyond two cotton growing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Profenofos Market |
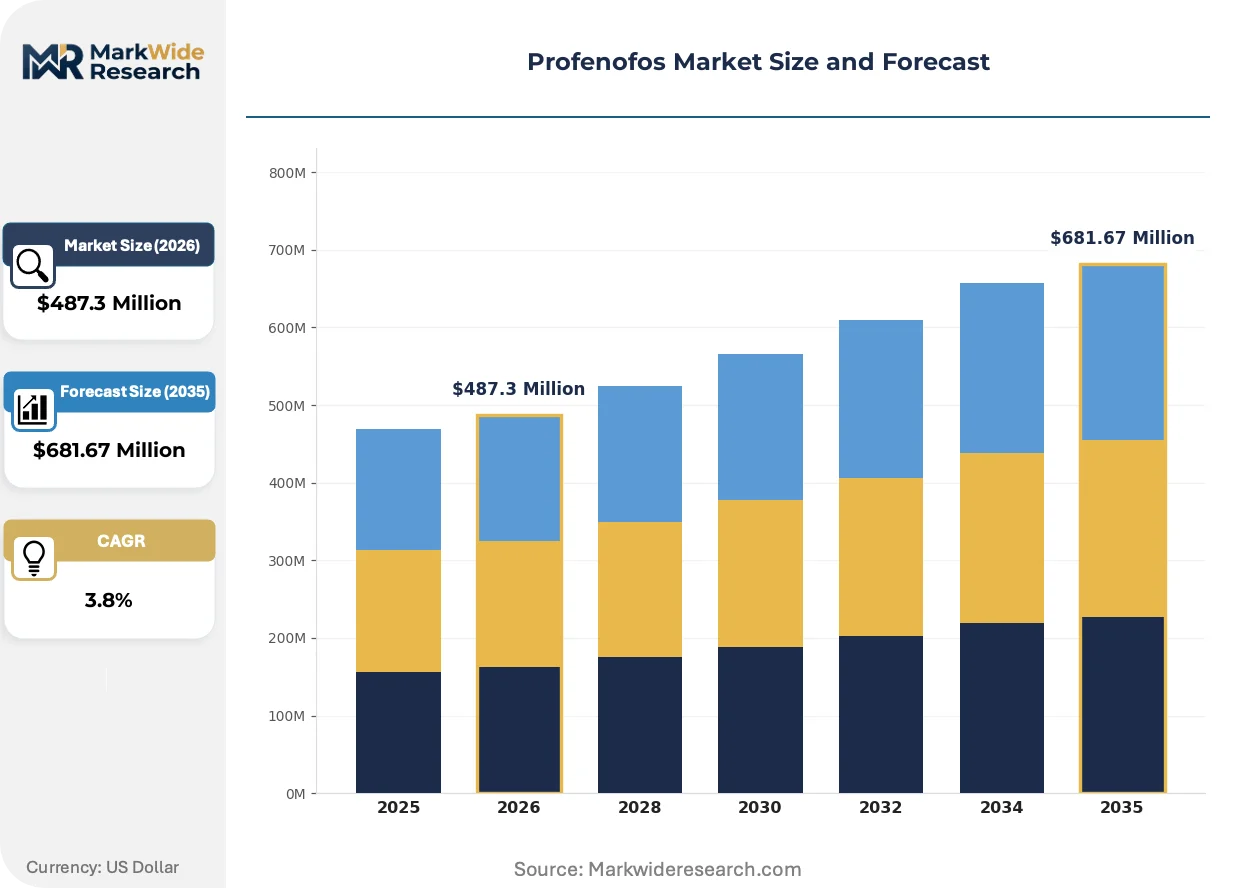
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticide, Pest Control Agent, Herbicide, Fungicide Application: Agriculture, Horticulture, Forestry, Greenhouse Formulation: Emulsifiable Concentrate, Granule, Wettable Powder, Suspension Concentrate Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Syngenta Group, UPL Ltd, ADAMA Agricultural Solutions, BASF SE, Bayer CropScience, Gharda Chemicals Ltd, Coromandel International Ltd, Mitsui & Co., Ltd, Nufarm Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Profenofos Market Evolving Landscape
Formulation science and application machinery are converging to reduce active ingredient load rates while preserving lethality against resistant pest biotypes.
Micro-encapsulation technology is virtualizing release kinetics in tropical field conditions. Syngenta's polymer shell systems delay profenofos availability until cuticle contact occurs. Cotton growers in Maharashtra's Jalgaon district adopt these formulations at 40% price premiums over standard EC grades. The technology is virtualizing competitive positioning around residual duration rather than acute toxicity metrics.
EFSA's 2023 guidance on cumulative risk assessment revises hazard index calculations for organophosphate clusters. The framework aggregates cholinesterase inhibition across multiple actives, compressing acceptable exposure thresholds for individual compounds. Cottonseed oil processors and export-oriented ginners in India face reformulation pressure to maintain EU market access.
Farmer purchasing through input dealer credit networks is fragmenting toward cash-based digital platforms. Agritech aggregators in Gujarat's Rajkot and Ahmedabad districts now bundle profenofos with weather-indexed insurance and drone services. This shift concentrates procurement decision-making with younger farm operators managing larger consolidated landholdings.
Profenofos Market Segmentation
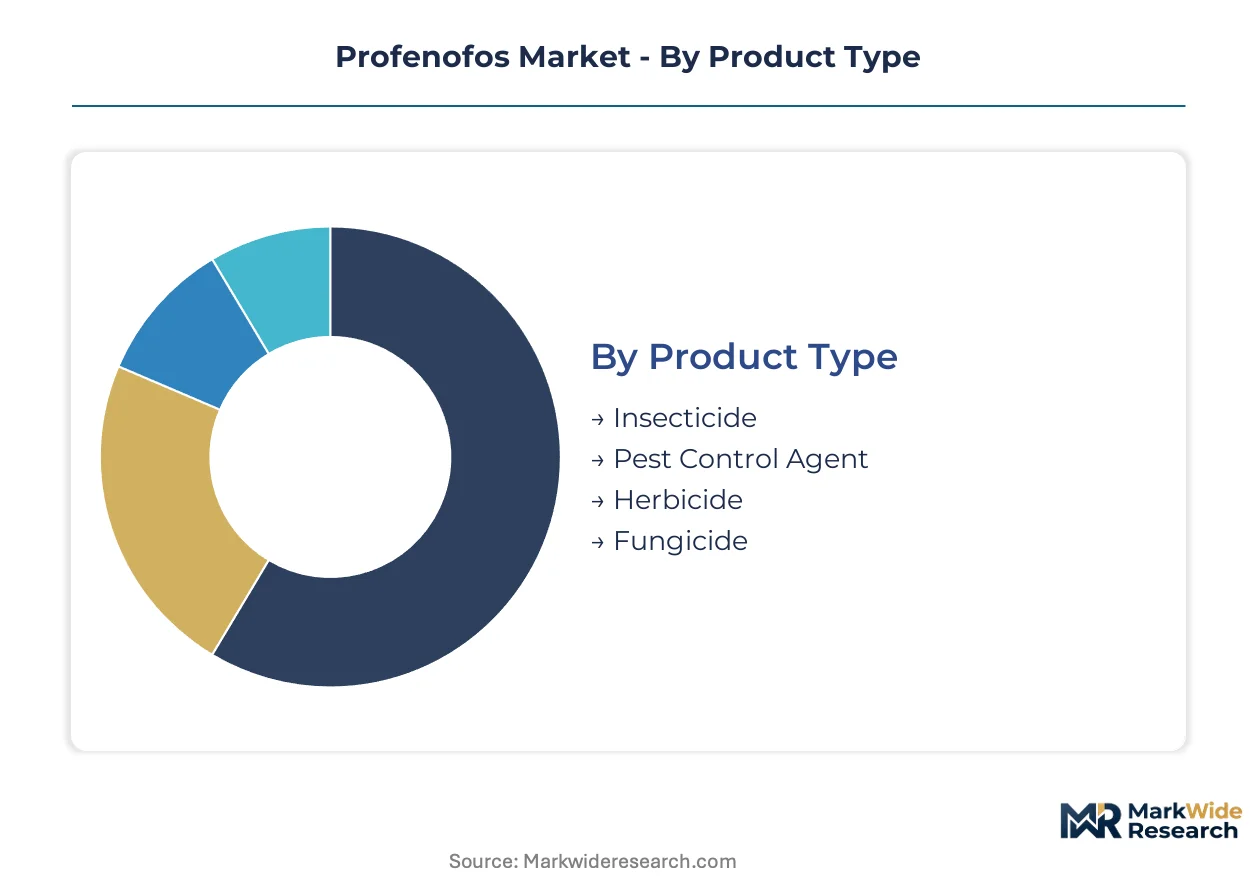
Segmentation in profenofos markets reveals how formulation chemistry, crop application, and procurement channels create distinct value pools. Technical-grade manufacturers align production assets to these divisions while navigating residue regulations that vary by end-use destination.
Product Type:
Cost tier positioning determines which active ingredient categories absorb technical manufacturing investment and regulatory compliance overhead.
- Insecticide:Cholinesterase-inhibiting chemistry targets lepidopteran and hemipteran nervous systems in cotton and vegetable systems. Maharashtra and Gujarat agriculture departments specify this category in state-mandated IPM protocols for bollworm management.
- Pest Control Agent:Broader-spectrum positioning encompasses mite and secondary pest suppression beyond primary lepidopteran targets. Greenhouse operators in the Netherlands specify this grade for integrated resistance management programs under EFSA residue frameworks.
- Herbicide:Profenofos lacks significant herbicidal activity; this segment captures minimal commercial volume.
- Fungicide:No established fungicidal mode of action limits this classification to nominal regulatory categorization.
Insecticide commands the established base. The steepest expansion runs through pest control agent positioning in specialty horticulture channels.
Application:
Volume concentration across crop systems shapes technical manufacturing batch sizing and seasonal inventory cycles.
- Agriculture:Field-scale cotton cultivation in India absorbs emulsifiable concentrate formulations through monsoon spray windows. Bt cotton adoption patterns in Gujarat's Kutch district sustain foliar application demand against secondary pest resurgence.
- Horticulture:Vegetable and fruit systems in Andhra Pradesh and Karnataka require tighter residue management. Export-oriented chilli and tomato growers face EU import tolerance thresholds under Regulation (EC) No 396/2005.
- Forestry:Plantation timber applications remain limited by aerial spray restrictions and environmental fate concerns in watershed zones.
- Greenhouse:Controlled-environment agriculture in Almeria, Spain and the Netherlands favors wettable powder grades for precision dosing and worker exposure mitigation.
Agriculture anchors volume throughput. Greenhouse applications gain share fastest on residue-sensitive export crop premiums.
Formulation:
Margin structure diverges sharply between established emulsifiable concentrate production and advanced delivery systems requiring polymer chemistry investment.
- Emulsifiable Concentrate:Petroleum-based solvent systems with surfactant packages enable rapid cuticle penetration in tropical humidity. Indian technical manufacturers in Gujarat and Maharashtra maintain EC-dedicated production lines for domestic cotton belt supply.
- Wettable Powder:Solid carrier formulations with dispersing agents suit greenhouse and high-value horticulture where residue limits constrain liquid application rates. Premium positioning reflects analytical certification costs for EU export compliance.
- Granule:Clay-based carriers enable soil incorporation for root zone pest suppression in limited specialty applications.
- Suspension Concentrate:Aqueous dispersed systems reduce solvent exposure and enable drone spray compatibility. Agritech service providers in Telangana pilot SC formulations for UAV deployment in cotton corridors.
Emulsifiable concentrate retains the volume base. Suspension concentrate climbs fastest on precision agriculture equipment integration.
Distribution Channel:
Customer type fragmentation between smallholder credit dependence and consolidated farm digital procurement reshapes channel economics.
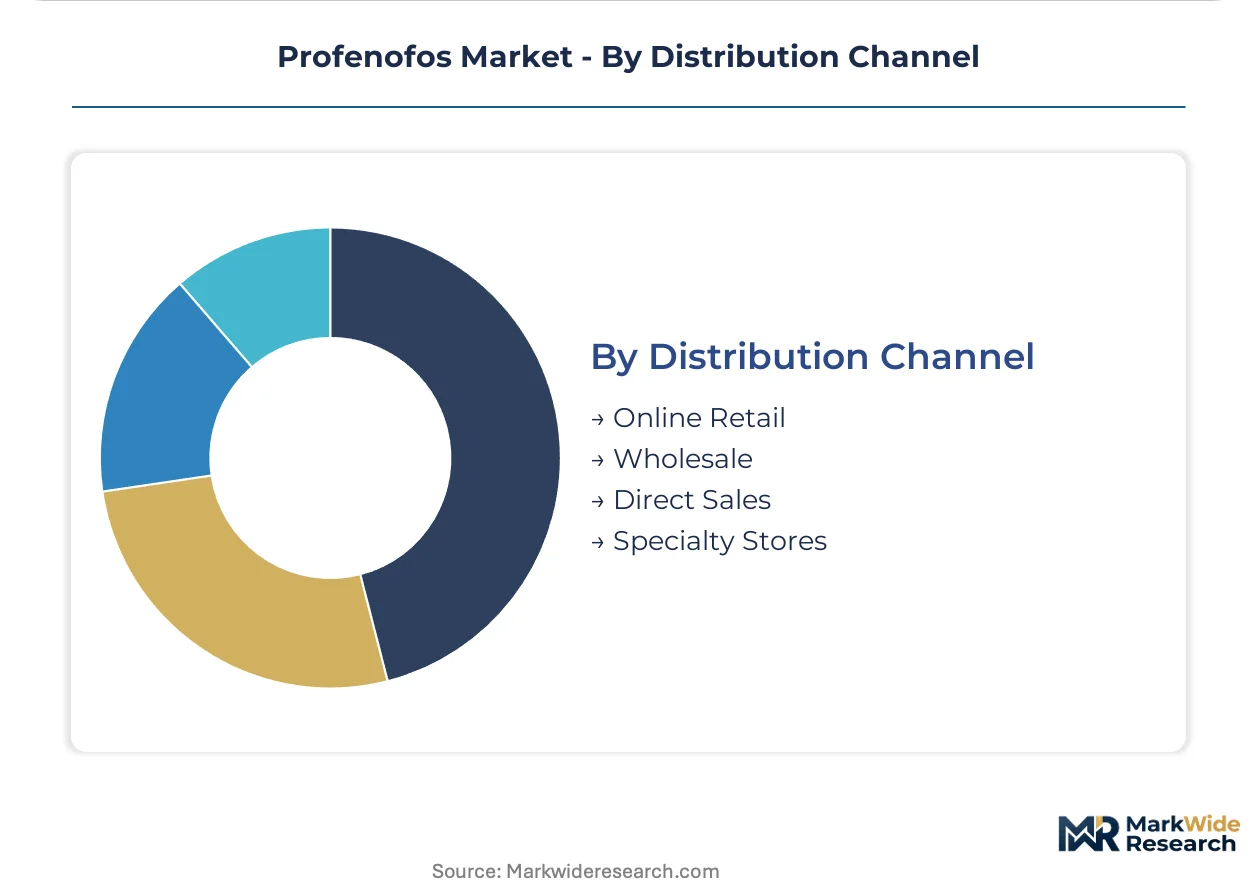
- Wholesale:Input dealer networks in Rajkot and Ahmedabad districts extend credit-linked seasonal procurement to cotton growers. Inventory financing structures align with monsoon planting calendars and harvest cash flows.
- Direct Sales:Large-scale farming enterprises and cooperative aggregators in Maharashtra's Jalgaon district negotiate technical-grade pricing through manufacturer relationships. Volume commitments secure batch prioritization during seasonal demand surges.
- Online Retail:Agritech platforms bundle profenofos with weather-indexed insurance and drone services. Younger farm operators managing consolidated holdings drive adoption in Gujarat's emerging digital procurement zones.
- Specialty Stores:Greenhouse supply outlets in the Netherlands and Spain serve protected agriculture operators with certified residue-compliant formulations.
Wholesale channels command the established base. Online retail gains share fastest on agritech platform consolidation and credit digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Input dealer credit networks in Maharashtra and Gujarat concentrate procurement decision-making among cotton growers managing monsoon spray calendars. Technical manufacturers align batch production to these buyer archetypes while navigating residue thresholds in EU and US export corridors.
India
Maharashtra and Gujarat absorb emulsifiable concentrate volumes through state-mandated IPM protocols for bollworm management. The Central Insecticides Board extends registration review timelines beyond two growing cycles. Jalgaon district cotton growers adopt micro-encapsulated formulations at price premiums over standard grades.
China
Technical-grade manufacturers supply phosphorus tribromide-derived actives to Indian formulators and Southeast Asian distributors. NMPA registration pathways for organophosphate exports require toxicology dossier completeness. Jiangsu and Zhejiang province chemical clusters concentrate bromine-chlorination synthesis capacity.
United States
EPA reregistration eligibility decisions under FIFRA govern import tolerance for cottonseed and vegetable commodities. The agency's cumulative risk assessments for cholinesterase-inhibiting compounds compress residue headroom. California's Central Valley processing facilities enforce analytical certification for export-bound produce.
Spain
Almeria greenhouse operators specify wettable powder grades for precision dosing in protected agriculture systems. EFSA's cumulative dietary exposure assessments under Regulation (EC) No 396/2005 narrow acceptable thresholds. Andalusian export cooperatives face reformulation pressure to maintain EU market access for treated vegetables.
Netherlands
Specialty supply outlets serve protected horticulture operators with certified residue-compliant formulations. ECHA's REACH data requirements for existing actives create registration barriers for incomplete dossiers. Rotterdam distribution hubs channel technical-grade imports to European formulators.
Profenofos Market Competitive Landscape
Channel-controlling players compete with product-specialist players across credit-linked dealer networks and direct procurement platforms. The structure consolidates around technical manufacturers with backward integration into phosphorus tribromide supply and formulators with distribution reach into monsoon-dependent cotton belts. Three archetypes dominate: integrated agrochemical conglomerates with multi-active portfolios, regional technical specialists serving export-oriented formulators, and agritech-enabled service providers bundling inputs with precision application equipment. Competitive moves concentrate on co-formulation partnerships for resistance management and drone-compatible formulation development.
Among the integrated agrochemical conglomerates, Syngenta Group and BASF SE exemplify archetypes combining micro-encapsulation technology with established distribution infrastructure. UPL Ltd occupies a position representing regional technical specialists with captive manufacturing in Indian chemical clusters. These three companies anchor the competitive spectrum from premium formulation innovation to volume-driven technical supply.
| Leading Market Players |
|---|
| Syngenta Group |
| UPL Ltd |
| ADAMA Agricultural Solutions |
| BASF SE |
| Bayer CropScience |
| Gharda Chemicals Ltd |
| Coromandel International Ltd |
| Mitsui & Co., Ltd |
| Nufarm Limited |
| Others |
Value Network & Pricing Analysis
Phosphorus tribromide feedstock volatility from Dead Sea and Arkansas brine operations compresses margin headroom across technical-grade manufacturers while simultaneously widening spreads between economy EC formulations and micro-encapsulated premium grades. This single-input dependency reshapes both procurement contract structures and geographic production footprints as Indian and Chinese synthesis facilities absorb bromine cost transmission differently.
Pricing Analysis
Cost-plus contracts indexed to bromine spot quotations dominate technical-grade transactions between Chinese manufacturers and Indian formulators. Three-tier pricing structure across premium, standard, and economy levels separates micro-encapsulated formulations with extended residual claims from commodity EC grades and wettable powder certifications for EU export compliance. Cost compression in standard EC tiers is intensifying because phosphorus tribromide volatility transmits directly to batch economics without formulation differentiation to absorb shocks. Smallholder cotton growers in Maharashtra's dealer credit networks exhibit highest price sensitivity, while export-oriented greenhouse operators in Almeria and the Netherlands accept certification-driven premiums.
Supply Chain Analysis
Supply-chain finance facilities extended by Gujarat-based technical manufacturers to Rajkot and Ahmedabad input dealers anchor working capital flows through monsoon planting cycles. Production gravity centers on India, China, and the Netherlands, with Jiangsu and Zhejiang province chemical clusters feeding phosphorus tribromide-derived actives to Indian formulators and European distributors. Raw material dependencies rest on Dead Sea bromine extraction, chlorinated solvent carriers, and polymer encapsulation resins. Single-source vulnerability concentrates in bromine supply from ICL Group and Albemarle operations. Distribution runs through credit-linked dealer networks for domestic cotton belts and direct technical-grade contracting for export-oriented formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Profenofos demand fragments across precision agriculture adoption curves, creating specialty formulation niches distinct from commodity EC volume plays. This demand-side shift rewards players who can bridge agritech service bundling with residue-compliant certification tiers.
For Market Incumbents: Build regulatory dossier depth as the primary moat against REACH re-registration barriers and EFSA cumulative risk compression. Invest in backward integration into phosphorus tribromide supply through offtake agreements with Dead Sea and Arkansas producers to dampen feedstock volatility exposure. Expand micro-encapsulation capacity in Maharashtra chemical clusters to capture premium pricing from Jalgaon district cotton growers adopting extended residual formulations. For New Entrants and Emerging Players: Build out drone-compatible suspension concentrate formulations targeting Telangana's Khammam and Warangal cotton corridors where agritech service providers consolidate procurement decisions. The underpenetrated Telangana state distribution infrastructure offers the most penetrable geography relative to saturated Maharashtra and Gujarat dealer networks. Partner with UAV operators to bundle ultra-low volume formulations with precision application services rather than competing through standalone input sales. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technical manufacturers with complete ECHA toxicology dossiers and captive bromine supply arrangements. Long-term viability hinges on residue compliance capabilities across shrinking EU import tolerance thresholds rather than volume scale alone. Watch EFSA cumulative dietary exposure reassessments as the signal indicating accelerated reformulation investment requirements or registration withdrawal cascades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Tribromide | Captive bromine supply dampens Dead Sea extraction cost volatility for Indian technical manufacturers. |
| Micro-Encapsulation Capacity Expansion | Polymer shell technology extends residual control claims in Maharashtra tropical cotton systems. |
| Drone-Compatible Formulation Development | Ultra-low volume SC grades align with Telangana agritech service provider procurement consolidation. |
| EFSA-Compliant Residue Certification | Complete toxicology dossiers secure REACH re-registration pathways against cumulative risk compression. |
| Synergist Co-Formulation Partnerships | Piperonyl butoxide combinations restore efficacy against pyrethroid-resistant Helicoverpa armigera in Andhra Pradesh. |
Research Methodology
Desk research of customs trade databases, EFSA residue limit registers, and Central Insecticides Board registration filings preceded structured interviews with technical manufacturing plant managers, Gujarat input dealer network operators, Maharashtra cotton cooperative procurement leads, and ECHA regulatory affairs specialists. Primary fieldwork validated batch production economics and monsoon seasonal demand patterns against secondary trade flow analysis. Bottom-up technical-grade production estimates triangulated with top-down cotton cultivation hectarage projections across Indian state agriculture department data.
Assumptions held fixed include EFSA maximum residue limit trajectories under Regulation (EC) No 396/2005, REACH re-registration timelines for existing actives, and Bt cotton adoption saturation levels in Gujarat and Maharashtra. The analytical framework modeled volume and value across formulation chemistry, crop application, and procurement channel dimensions throughout the forecast period. CAGRs derived from segmented growth rate blending weighted by cotton cultivation expansion in Telangana and residue-driven formulation premium capture in greenhouse horticulture. Modeled inputs included phosphorus tribromide cost transmission elasticities and drone spray adoption curves in Indian cotton belts.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese technical manufacturers or accelerated EFSA registration withdrawals would shift outcomes. Macroeconomic deviation in cotton commodity pricing, regulatory revision to EU cumulative risk assessment methodologies, or technological disruption through RNA interference pest control alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Isononanol (INA) Market