
 Middle East Refrigerants Market | 2026-2036
Middle East Refrigerants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Refrigerants Market Analysis
The F-Gas Regulation alignment push across Gulf Cooperation Council member states is consolidating demand toward lower-GWP refrigerant portfolios. Honeywell International leverages its fluorochemical R&D infrastructure to supply next-generation hydrofluoroolefin formulations to regional HVAC OEMs. Gulf Cryo anchors industrial gas distribution across Saudi Arabia and the UAE through captive production of ammonia and carbon dioxide refrigerants. Harp Middle East LLC specializes in reclaimed and reclaimed-blend refrigerant supply, competing on circularity credentials against virgin material imports.
Refrigerants comprise thermodynamic working fluids—typically pure compounds or zeotropic azeotropic blends with specified critical temperatures and glide characteristics—that transfer heat through phase-change cycles in mechanical compression systems. Their primary commercial purpose centers on enabling temperature control across food preservation, human comfort, and industrial process cooling applications. Natural refrigerants, particularly ammonia and carbon dioxide, occupy the industrial refrigeration segment where toxicity and pressure handling capabilities are manageable through engineered containment. HFCs still dominate residential AC and commercial cooling retrofit channels where equipment compatibility constraints slow transition timelines. Blends represent the fastest-growing type category as contractors navigate retrofit economics in existing R-22 and R-410A installed bases.
Saudi Arabia's SFDA and the UAE's MOHAP enforce product registration and import conformity requirements that filter uncertified refrigerant formulations from regional supply channels. The EU F-Gas Regulation's extraterritorial influence on Gulf-based exporters shapes OEM sourcing decisions toward MEE-aligned low-GWP specifications. ISO 817 and IEC 60335-2-89 safety standards govern equipment redesign cycles that determine refrigerant eligibility by application class. Stakeholders must monitor how Saudi dual carbon goals and UAE net-zero commitments translate into building code amendments that mandate refrigerant GWP thresholds in new construction permits.
Market Dynamics
The F-Gas Regulation's extraterritorial pull on Gulf-based exporters is compressing refrigerant procurement timelines and forcing HVAC OEMs to qualify lower-GWP formulations before equipment redesign cycles complete.
Growth Catalysts
- District Cooling Infrastructure:Dubai's district cooling networks and Abu Dhabi's data center construction are generating concentrated offtake for low-GWP alternatives across the UAE.
- SFDA Product Registration:Saudi Arabia's enforcement of import conformity requirements is redirecting procurement toward certified domestic distributors with compliant refrigerant blends.
- Hydrofluoroolefin R&D:Next-generation HFO formulations are penetrating regional HVAC OEM supply chains as fluorochemical innovation accelerates equipment compatibility testing.
Market Restraints
- Retrofit Economics:Existing R-22 and R-410A installed bases create equipment compatibility constraints that slow transition timelines in residential AC channels.
- Supply Concentration:Industrial gas distribution concentrates among captive ammonia and carbon dioxide producers across Saudi Arabia and the UAE.
- Toxicity Handling Requirements:Natural refrigerant adoption in industrial segments faces containment engineering costs that limit contractor participation.
Strategic Opportunities
- Reclaimed Refrigerant Circularity:Reclaimed and reclaimed-blend supply channels are competing against virgin material imports on sustainability credentials.
- Building Code Amendments:Saudi dual carbon goals and UAE net-zero commitments are translating into permit mandates for GWP thresholds in new construction.
- Data Center Thermal Management:Hyperscale facility construction is creating specialized demand for precision cooling fluids with ultra-low GWP specifications.
Industry Challenges
- Certification Timeline Compression:ISO 817 and IEC 60335-2-89 safety standards are governing equipment redesign cycles that determine refrigerant eligibility by application class.
- Contractor Skill Gaps:Blends require handling protocols distinct from pure compounds, stretching technical training capacity across installation networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Refrigerants Market |
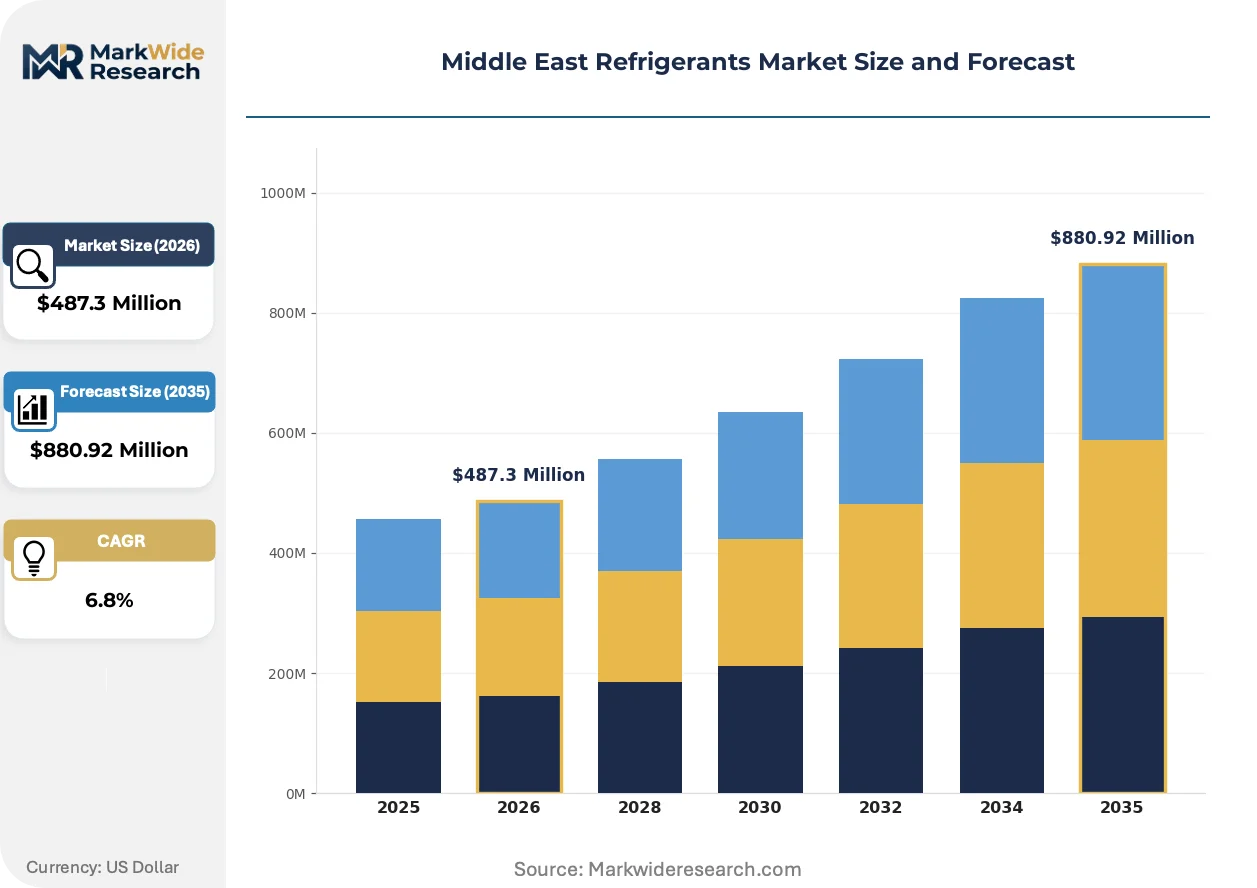
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: HFCs, HCFCs, Natural Refrigerants, Blends Application: Commercial Cooling, Residential AC, Industrial Refrigeration, Automotive AC End User: Refrigeration Industry, HVAC Contractors, Food and Beverage Industry, Automotive Sector Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Honeywell International, Harp Middle East LLC, Gulf Cryo, Abdullah Hashim Industrial Gases & Equipment, Brothers Gas Bottling, Linde, Daikin Industries, Air Liquide, Arkema, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Refrigerants Market Emerging Trajectories
Refrigerant technology trajectories across the Middle East are converging on phase-change fluids that satisfy both thermodynamic performance and emerging regulatory GWP ceilings.
Hydrofluoroolefin formulations are expanding into commercial cooling retrofit channels as HVAC OEMs accelerate equipment qualification programs. Contractors servicing Dubai's hospitality sector are adopting HFO blends to preempt permit compliance deadlines. This transition is expanding into procurement specifications that previously excluded next-generation fluorochemicals on cost grounds.
The EU F-Gas Regulation is reshaping Gulf-based exporter sourcing decisions toward MEE-aligned low-GWP specifications. OEMs supplying European markets must certify refrigerant portfolios before shipment, compressing formulation approval timelines. Industrial refrigeration segments in Saudi Arabia are responding by dual-qualifying ammonia systems alongside transitional HFC blends.
Buyer preference is tilting toward certified reclaimed material as sustainability reporting requirements penetrate corporate procurement policies. Retail and hospitality chains across the UAE are inserting circularity credentials into refrigerant supply agreements. This specification tightening is most visible in Dubai's district cooling concessions, where operators face disclosure mandates on embodied carbon in working fluids.
Middle East Refrigerants Market Segmentation
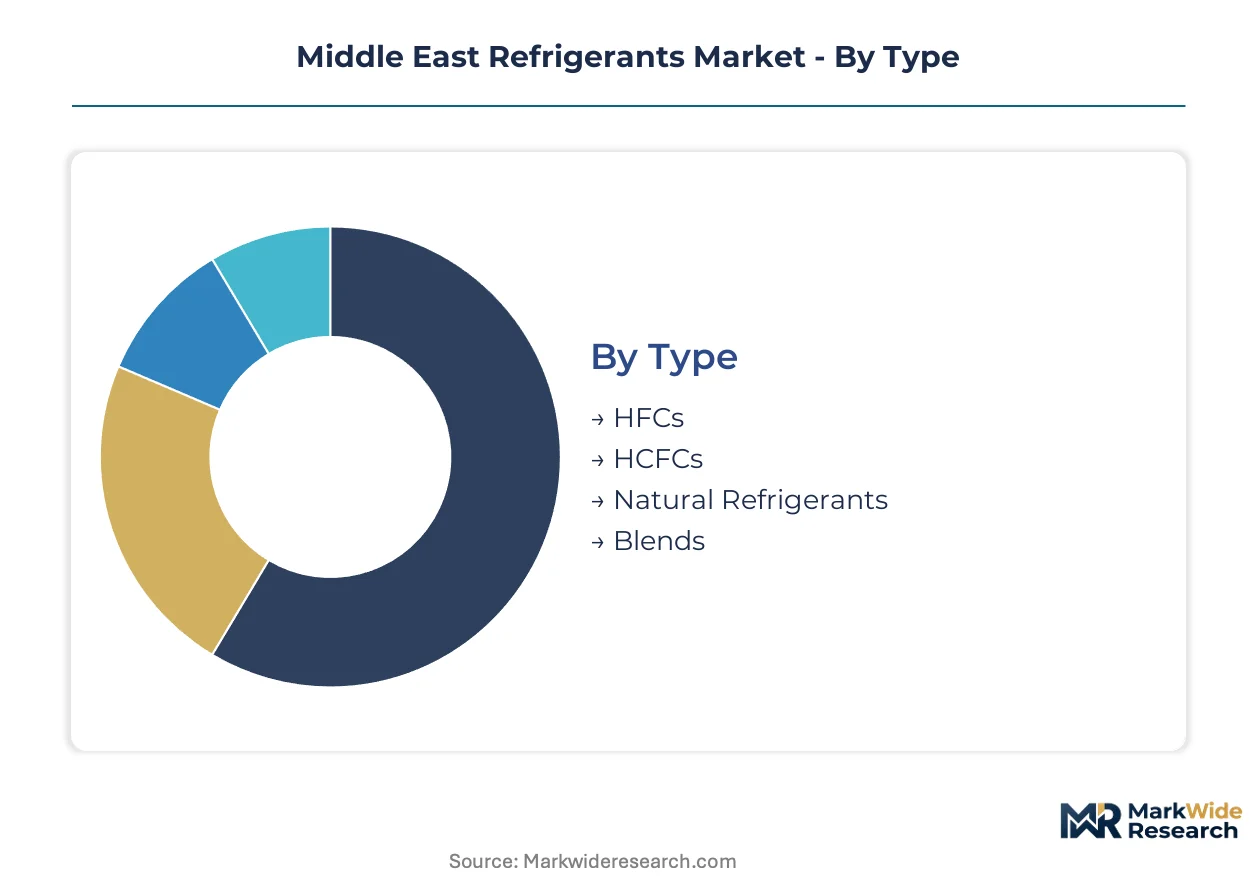
Refrigerant procurement patterns across the Middle East fragment sharply by thermal performance requirements, regulatory compliance tiers, and contractor handling capabilities. Segmentation reveals where low-GWP transitions concentrate versus where legacy formulations retain equipment lock-in.
Type:
Standardization dominates commodity HFCs and HCFCs, while natural refrigerants and precision blends require engineered customization for specific pressure and glide specifications.
- HFCs:Hydrofluorocarbon formulations including R-410A and R-134a remain entrenched in residential AC and commercial cooling retrofits across Saudi Arabia and the UAE. Equipment compatibility constraints and contractor familiarity sustain procurement volumes despite F-Gas Regulation pressure on Gulf exporters serving European markets.
- Blends:Zeotropic and azeotropic mixtures are displacing pure compounds in Dubai's district cooling networks and Abu Dhabi data center construction. Contractors specify these formulations to navigate retrofit economics while meeting tightening GWP thresholds in new building permits.
- HCFCs:R-22 phase-out schedules are compressing residual demand into equipment servicing channels.
- Natural Refrigerants:Ammonia and carbon dioxide occupy industrial refrigeration where Gulf Cryo and similar captive producers control containment-engineered supply.
Leading the category by volume: HFCs. Growing fastest: Blends.
Application:
Application segmentation tracks cooling load intensity against regulatory scrutiny intensity.
- Commercial Cooling:Hospitality and retail climate infrastructure across Dubai and Riyadh generates concentrated offtake for lower-GWP alternatives. Procurement specifications increasingly mandate reclaimed material credentials and pre-registered SFDA-compliant formulations.
- Industrial Refrigeration:Ammonia systems dominate food processing and cold chain logistics in Saudi Arabia's Eastern Province and UAE free zones. Toxicity handling requirements filter contractor participation toward specialized engineering firms.
- Residential AC:R-22 and R-410A installed bases create equipment compatibility constraints slowing transition timelines.
- Automotive AC:Service channel demand concentrates on R-134a replacement cycles with gradual HFO-1234yf penetration.
Commercial Cooling generates the steepest expansion trajectory as district cooling concessions multiply.
End User:
End user segmentation reflects technical sophistication gradients in refrigerant handling and compliance documentation.
- HVAC Contractors:Installation and service networks across the GCC require blend-specific training protocols distinct from pure compound handling. SFDA registration requirements are redirecting procurement toward certified domestic distributors with compliant documentation.
- Food and Beverage Industry:Cold chain operators in Saudi Arabia and the UAE face sustainability reporting mandates that favor reclaimed refrigerant supply agreements.
- Refrigeration Industry:OEM equipment manufacturers source formulations pre-qualified for export markets.
- Automotive Sector:Service chains manage replacement cycles with standardized R-134a volumes.
HVAC Contractors command the largest procurement volumes. Food and Beverage Industry procurement is climbing the fastest on circularity credential requirements.
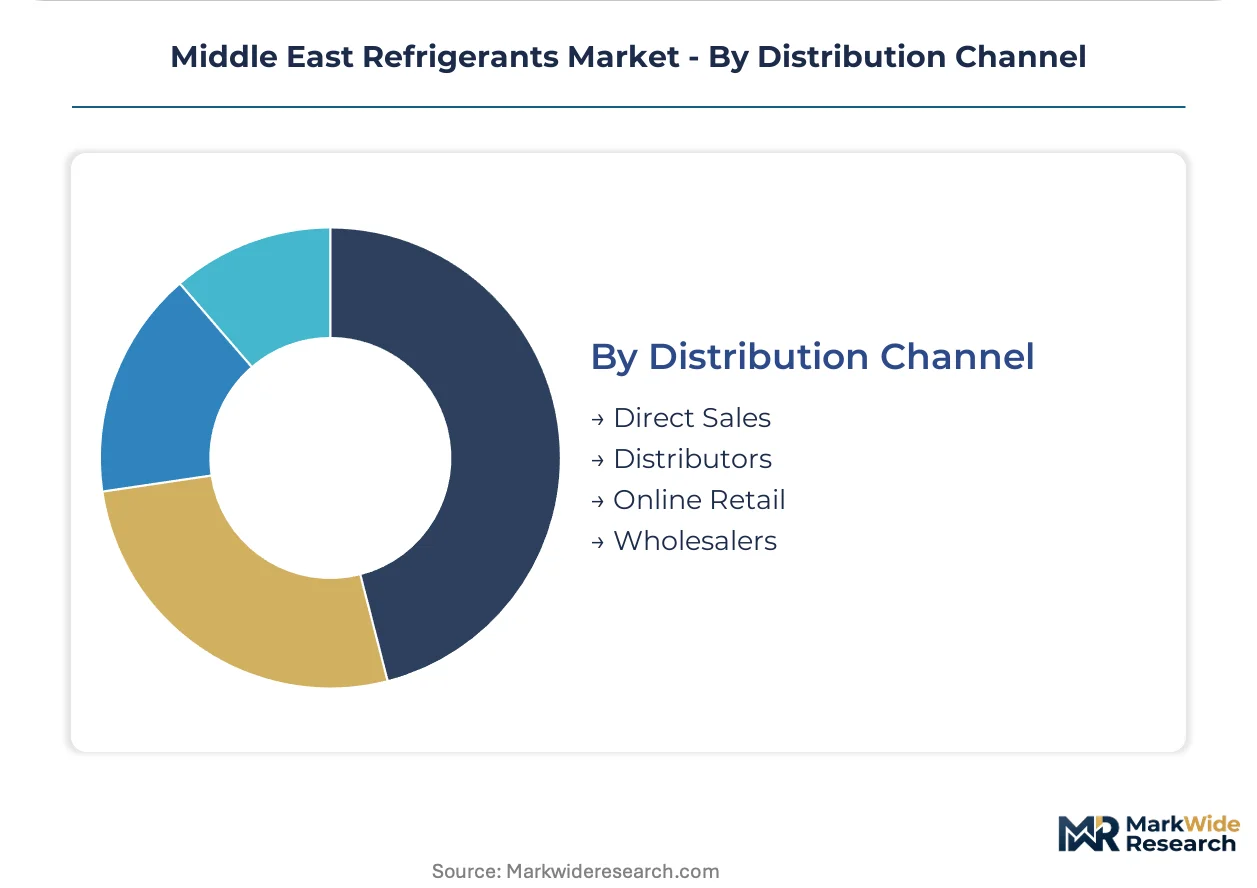
Distribution Channel:
Channel segmentation tracks certification value-add against transaction efficiency.
- Distributors:Certified domestic distributors anchor refrigerant supply across Saudi Arabia and the UAE, leveraging SFDA and MOHAP registration capabilities that filter uncertified imports. These intermediaries capture value through compliance documentation and technical support.
- Direct Sales:Industrial gas producers including captive ammonia and carbon dioxide suppliers serve large-volume accounts through dedicated account management.
- Wholesalers:Volume aggregation serves contractor networks with standardized HFC and HCFC formulations.
- Online Retail:Digital channels remain limited by hazardous material shipping restrictions and certification verification requirements.
Distributors lead channel volumes. Direct Sales channels are gaining share fastest among industrial accounts seeking supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional production concentrates among captive industrial gas facilities in Saudi Arabia and the UAE, while consumption spreads across commercial cooling installations from Riyadh to Dubai. This geographic split shapes procurement patterns and compliance requirements.
Saudi Arabia
District cooling concessions in Riyadh and Jeddah are driving specification shifts toward lower-GWP refrigerant blends. The SFDA enforces product registration requirements that filter uncertified imports from regional supply channels. Eastern Province industrial clusters anchor ammonia production for food processing and cold chain logistics.
United Arab Emirates
Dubai's hospitality sector and Abu Dhabi's data center construction generate concentrated offtake for precision cooling fluids. MOHAP import conformity requirements redirect procurement toward certified domestic distributors. Dubai's district cooling networks are mandating reclaimed material credentials in concession agreements.
Qatar
World Cup legacy infrastructure and LNG facility expansion sustain commercial cooling demand in Doha and Ras Laffan. The country's national environmental regulator is aligning building codes with Gulf Cooperation Council sustainability frameworks. Education City and Lusail development zones are specifying ultra-low GWP alternatives in new construction permits.
Kuwait
Retail and hospitality climate infrastructure in Kuwait City generates steady demand for HFC replacement cycles. The Ministry of Commerce and Industry enforces import standards that parallel Saudi and UAE registration regimes. Shuwaikh industrial area hosts contractor networks transitioning to blend-specific handling protocols.
Oman
Port and logistics infrastructure in Sohar and Salalah are expanding cold chain capacity with ammonia-based industrial systems. The Directorate General of Specifications and Measurements governs product conformity for imported refrigerant formulations. Duqm Special Economic Zone construction is creating new demand for commercial cooling equipment qualification.
Middle East Refrigerants Market Vendor Landscape
The competitive structure tilts toward industrial gas incumbents with captive production assets and fluorochemical specialists with R&D infrastructure. Regional distribution concentrates among certified domestic intermediaries with regulatory documentation capabilities. Two strategic archetypes dominate: multinational chemical conglomerates supplying next-generation formulations, and regional industrial gas producers controlling ammonia and carbon dioxide supply. Competitive moves center on portfolio diversification into lower-GWP blends and geographic expansion through distributor certification partnerships.
Among multinational fluorochemical suppliers, Honeywell International represents the technology-licensing archetype with hydrofluoroolefin R&D infrastructure. Gulf Cryo anchors regional industrial gas distribution through captive ammonia and carbon dioxide production across Saudi Arabia and the UAE. Harp Middle East LLC exemplifies the circularity-focused tier, competing on reclaimed and reclaimed-blend refrigerant supply against virgin material imports.
| Leading Market Players |
|---|
| Honeywell International |
| Harp Middle East LLC |
| Gulf Cryo |
| Abdullah Hashim Industrial Gases & Equipment |
| Brothers Gas Bottling |
| Linde |
| Daikin Industries |
| Air Liquide |
| Arkema |
| Others |
Supply Flow & Price Mechanics
Fluorochemical feedstock indices cascading through Gulf-based formulation plants create pricing tiers that separate certified reclaimed material from virgin HFC imports. Saudi Arabia's SFDA registration requirements add compliance premiums that domestic distributors capture through documentation value-add, while Dubai's district cooling concessions impose circularity credentials that widen spreads between sustainable and conventional supply.
Pricing Analysis
Outcome-based pricing anchored to cooling system uptime and energy efficiency gains commands premiums in Abu Dhabi's data center thermal management contracts. Certification grade under SFDA and MOHAP registration tiers differentiates compliant domestic distributors from uncertified import channels, with brand premiums attaching to Honeywell's HFO formulations. Cost compression in commodity HFC tiers intensifies as Gulf exporters face EU F-Gas Regulation qualification deadlines, squeezing margins on R-410A and R-134a volumes. Residential AC contractors exhibit highest price sensitivity, while industrial refrigeration operators prioritize supply security over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese fluorochemical precursors feeding Saudi Arabia and UAE formulation plants. Geographic supply concentration centers on Saudi Arabia's Eastern Province ammonia production, UAE's Jebel Ali industrial gas hubs, and Chinese HFC/HFO intermediate manufacturing. Raw material dependencies span hydrofluoric acid, chlorinated organics, and specialized catalysts for olefin synthesis. Tariff exposure on Chinese feedstock imports presents structural risk as regional trade policy shifts. Distribution runs through certified domestic distributors with SFDA documentation capabilities, bypassing direct manufacturer-to-contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East refrigerants market sits in a technology-transition phase as hydrofluoroolefin formulations displace legacy HFCs across commercial cooling and district cooling infrastructure. This substitution wave compresses equipment redesign cycles and redirects procurement specifications toward lower-GWP portfolios.
For Market Incumbents: Acquire reclaimed refrigerant processing capacity to preempt circularity credential requirements in Dubai's district cooling concessions. Gulf Cryo's captive ammonia production model demonstrates how backward integration into industrial gas feedstock insulates margin pressure from fluorochemical volatility. SFDA registration compliance investments create switching costs that lock contractor relationships against emerging reclaimed-blend competitors. For New Entrants and Emerging Players: Certified domestic distributors with MOHAP documentation capabilities represent the most penetrable channel archetype for HFO formulation market entry. White-space concentrates in Abu Dhabi's data center precision cooling segment, where ultra-low GWP specifications outpace incumbent qualification timelines. Technical training partnerships with HVAC contractor networks offer go-to-market leverage distinct from price-competing on commodity HFC volumes. For Investors and Strategic Acquirers: Distressed-cycle entries favor reclaimed refrigerant processors in Saudi Arabia's Eastern Province industrial corridor, where R-22 phase-out compression creates feedstock abundance. Long-term viability over a multi-year horizon hinges on dual-qualification capabilities across natural refrigerants and transitional fluorochemicals. The signal to watch is MOHAP and SFDA harmonization on GWP permit thresholds, which would accelerate formulation switching costs and consolidate distributor tier positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorochemical Precursors | Saudi producers reduce Chinese feedstock dependency through captive HF acid manufacturing. |
| Reclaimed Material Processing Scale-Up | Dubai district cooling operators meet concession disclosure mandates on embodied carbon. |
| HFO Formulation Equipment Qualification | HVAC OEMs secure EU export certification before F-Gas Regulation deadlines compress. |
| Certified Distributor Network Expansion | Domestic intermediaries capture SFDA registration value-add in Riyadh and Jeddah procurement. |
| Natural Refrigerant Containment Engineering | Industrial gas producers extend ammonia service capabilities into food processing cold chains. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with HVAC contractor network managers, industrial refrigeration plant engineers, SFDA compliance officers, and fluorochemical procurement leads at regional OEMs. Secondary validation drew from SFDA product registration databases, UAE MOHAP import conformity records, GCC customs harmonization reports, and SEC disclosures from multinational chemical suppliers. Bottom-up volume estimates from distributor channel checks reconciled against top-down demand projections from construction permit data and district cooling concession awards.
Data-stream reconciliation across the modeling period applied multi-dimensional segmentation by refrigerant type, application intensity, and regulatory compliance tier. The analytical framework modeled thermal performance specifications, equipment compatibility constraints, and contractor handling capability gradients as independent demand drivers. CAGRs were derived from equipment replacement cycle analysis and building code amendment timelines rather than extrapolated trend fitting. Industry-specific forecast inputs included Dubai Electricity and Water Authority district cooling expansion plans and Saudi Vision 2030 industrial zone development schedules.
Caveats apply where SFDA-MOHAP regulatory harmonization delays or EU F-Gas Regulation extraterritorial enforcement shifts could materially shift the outlook. Forecasts embed assumptions on HFO equipment qualification timelines and reclaimed material supply scaling that remain sensitive to contractor training capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market