
 India Adhesives Market | 2026-2036
India Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
India Adhesives Market Foresight
Asset-light leasing models for specialty adhesive formulation equipment is reshaping competitive entry in India, allowing mid-tier firms to scale without heavy capex. Pidilite Industries leverages its deep distribution network across tier-2 and tier-3 cities to sustain brand loyalty in consumer adhesives. Henkel AG anchors its position through technology leadership in automotive structural bonding solutions for electric vehicle platforms. Astral Adhesives competes aggressively in construction-grade segments with localized product portfolios tailored to tropical humidity conditions.
Adhesives are polymeric substances formulated from resins, elastomers, tackifiers, and curing agents that develop structural or semi-structural bonds through mechanical interlocking, chemical reaction, or physical solidification processes. Water-based formulations dominate India's decorative and paper-bonding applications due to low volatile organic compound emissions and compatibility with BIS environmental guidelines. Solvent-based adhesives still occupy significant share in footwear and leather goods manufacturing where rapid tack strength and water resistance remain critical performance parameters. Pressure-sensitive adhesives represent the fastest-growing product category, driven by e-commerce packaging expansion and label-stock demand from FMCG distributors in Mumbai and Delhi-NCR.
BIS mandates adhesive performance testing for load-bearing construction applications, compelling manufacturers to reformulate products for shear strength and thermal aging compliance. The Central Pollution Control Board enforces solvent emission thresholds that push industrial users toward compliant water-based and hot-melt systems. OEM procurement teams must monitor PLI scheme extensions for domestic chemical manufacturing, as these incentives determine whether local formulation capacity can offset imported resin dependencies.
Market Dynamics
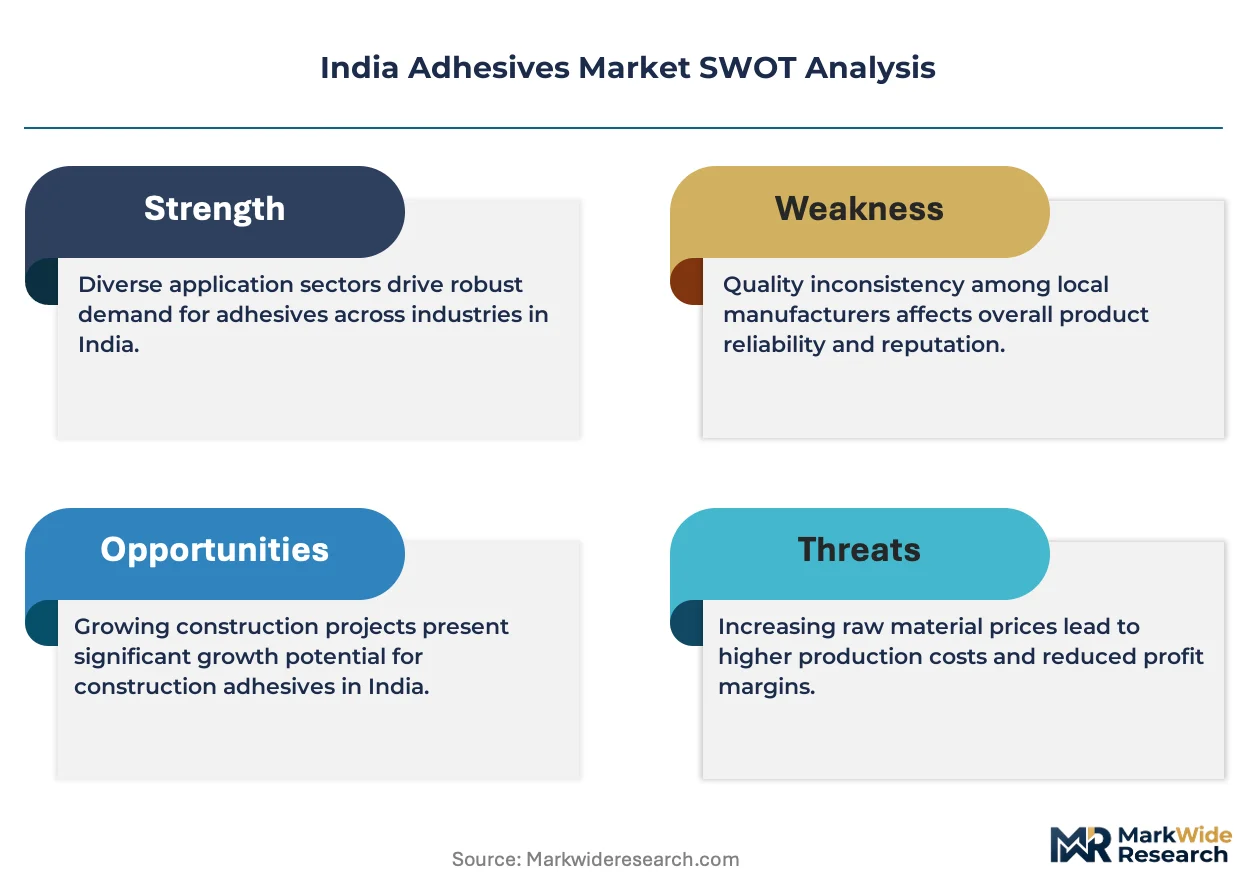
PLI scheme extensions for domestic chemical manufacturing are restructuring competitive entry economics, allowing mid-tier firms to scale formulation capacity without full capital ownership of resin synthesis infrastructure.
Growth Catalysts
- Electric vehicle platform expansion:Automotive OEMs in Chennai and Pune are expanding bonded assembly lines to reduce vehicle weight and eliminate mechanical fasteners from battery enclosure designs.
- BIS certification tightening:Mandatory adhesive performance testing for load-bearing construction applications is compelling manufacturers to reformulate products for shear strength and thermal aging compliance.
- E-commerce packaging surge:Pressure-sensitive adhesives are capturing expanded label-stock demand from FMCG distributors in Mumbai and Delhi-NCR as fulfillment center throughput rises.
Market Restraints
- Imported resin dependency:Domestic formulation capacity remains constrained by feedstock supply chains concentrated in Southeast Asian petrochemical hubs.
- Solvent emission thresholds:Central Pollution Control Board enforcement pushes industrial users toward compliant water-based systems before cost parity is achieved.
- Humidity performance gaps:Tropical climate conditions in coastal Maharashtra and Gujarat degrade bond durability in unmodified acrylic formulations.
Strategic Opportunities
- Tier-2 and tier-3 distribution penetration:Pidilite Industries demonstrates sustained brand loyalty through deep distribution networks in underserved urban centers.
- Hot-melt system conversion:Packaging hubs are accelerating adoption of solvent-free systems to preempt regulatory compliance costs.
- Asset-light equipment leasing:Specialty adhesive formulation equipment leasing models allow mid-tier firms to scale production without heavy capex commitments.
Industry Challenges
- Reformulation timeline compression:BIS mandates require accelerated product recertification cycles that strain R&D bandwidth at mid-sized manufacturers.
- Humidity-specific product development:Construction-grade segments demand localized portfolios tailored to tropical conditions, fragmenting SKU economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Adhesives Market |
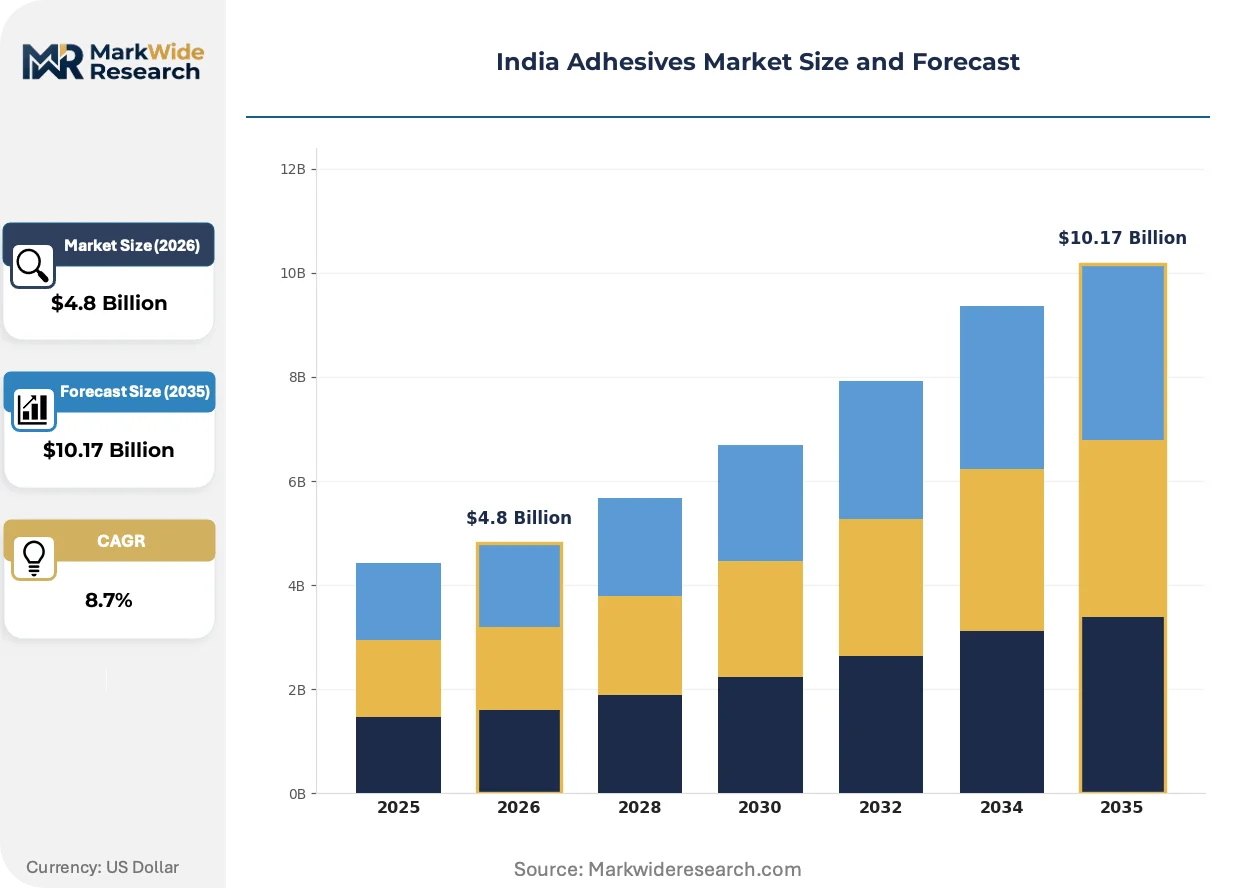
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Pressure Sensitive Application: Furniture, Automotive, Packaging, Construction End User: OEMs, Contractors, Retailers, Distributors Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Pidilite Industries, Henkel AG, 3M, H.B. Fuller, Arkema, Sika, Bostik, Astral Adhesives, Anabond, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Adhesives Market Shifts & Advancements
Water-based adhesive chemistry is collapsing performance gaps with solvent-based alternatives across industrial applications, while regulatory pressure and procurement model evolution accelerate displacement timelines.
Reactive hot-melt polyurethane technology is collapsing the durability advantage previously held by solvent-based systems in footwear and automotive interior applications. Tier-1 suppliers in Tamil Nadu are adopting these systems at pace to maintain export compliance with EU REACH thresholds. The technology is collapsing capital barriers to high-performance bonding by eliminating ventilation infrastructure requirements.
BIS mandates for construction-grade adhesive performance testing are forcing reformulation investments across load-bearing application segments. Manufacturers must now document shear strength and thermal aging compliance before product registration approval. Western India construction material distributors are responding by consolidating supplier relationships toward certified domestic producers.
Leasing arrangements for specialty formulation equipment are replacing ownership models among mid-tier manufacturers seeking production scale without balance sheet expansion. Contract manufacturers in Gujarat and Maharashtra are capturing volume from brands that previously imported finished goods. This shift concentrates most visibly among furniture manufacturing clusters seeking flexible capacity alignment with export order volatility.
India Adhesives Market Segmentation
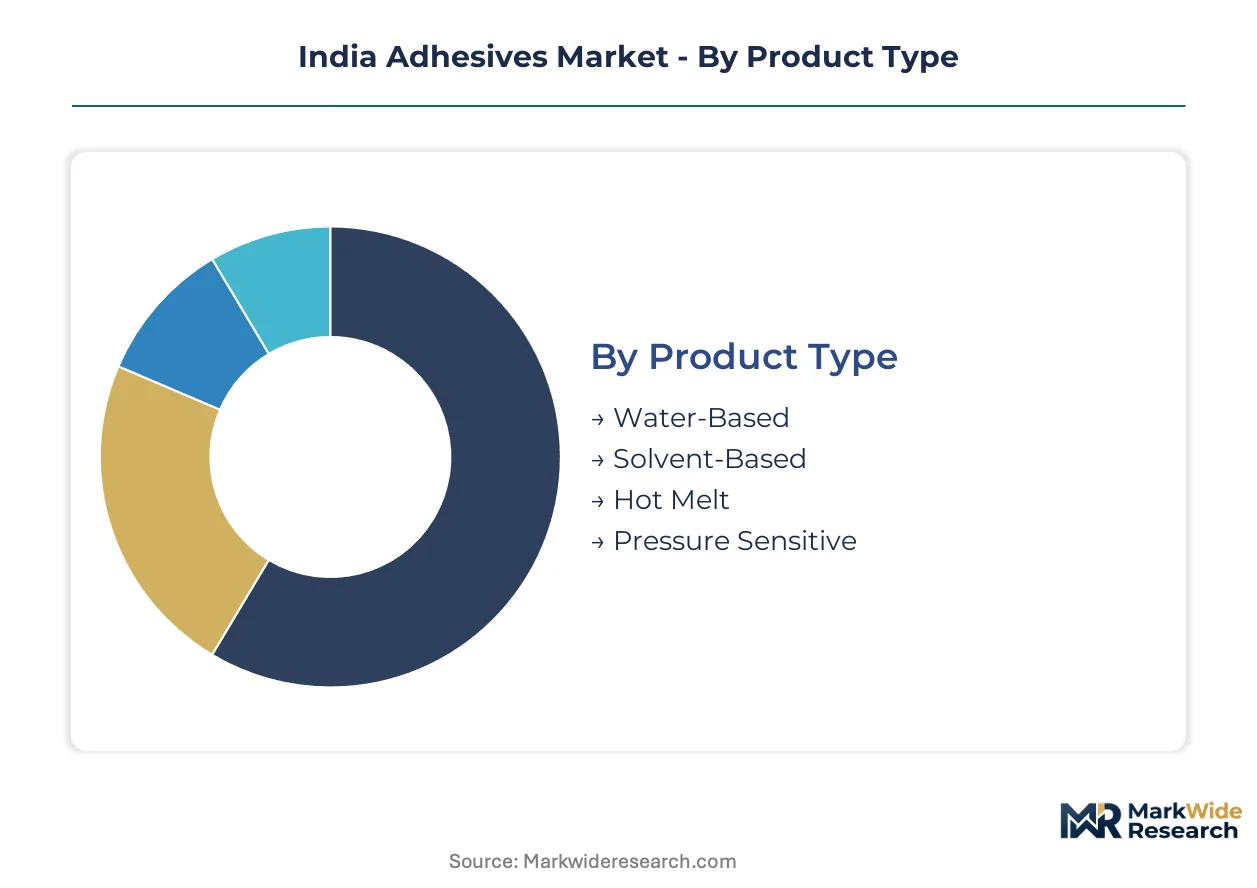
Segmentation in India's adhesives market reveals how formulation chemistry, application requirements, and procurement patterns create distinct competitive arenas. Each dimension carries regulatory, technical, and margin implications that determine where manufacturers can build defensible positions.
Product Type:
Mature formulations dominate volume, while emerging chemistries capture regulatory tailwinds and premium positioning.
- Water-Based:These emulsion systems disperse synthetic resins in aqueous carriers with minimal volatile organic compound release. Maharashtra and Gujarat furniture clusters specify water-based systems to meet BIS environmental guidelines and Central Pollution Control Board emission thresholds. The chemistry is displacing solvent alternatives in decorative bonding as cost parity improves.
- Solvent-Based:Rapid tack development and superior water resistance sustain demand in footwear manufacturing clusters across Tamil Nadu. BIS mandates and CPCB enforcement are compressing permissible applications, forcing reformulation investments at legacy producers. The segment retains pricing power in leather goods export supply chains.
- Hot Melt:Thermoplastic polymers applied in molten state eliminate solvent handling infrastructure. E-commerce packaging hubs in Mumbai and Delhi-NCR are accelerating adoption to preempt compliance costs.
- Pressure Sensitive:Permanent tack properties enable label-stock and tape applications without activation. FMCG distributors are driving specification expansion across tier-2 fulfillment networks.
Water-based formulations handle the majority of throughput; pressure sensitive adhesives are gaining share fastest on e-commerce packaging expansion.
Application:
Application segmentation tracks where bonding performance translates into end-product value and regulatory scrutiny intensity.
- Furniture:Panel lamination and veneer bonding demand formulations with tropical humidity resistance. Gujarat and Maharashtra manufacturing clusters specify certified products for export compliance with EU REACH thresholds. The segment rewards localized product portfolios.
- Automotive:Structural bonding for electric vehicle platforms eliminates mechanical fasteners from battery enclosures. Chennai and Pune OEMs are expanding bonded assembly lines to reduce vehicle weight. The application commands specification rigor and technical service intensity.
- Packaging:Corrugated box sealing and flexible film lamination prioritize throughput speed and food-contact safety. FSSAI compliance requirements filter supplier qualification.
- Construction:Load-bearing applications face mandatory BIS performance testing for shear strength and thermal aging. Western India distributors are consolidating toward certified domestic producers.
Construction-grade products carry the heaviest compliance burden; automotive applications are climbing the fastest on electric vehicle platform expansion.
End User:
End user segmentation distinguishes between specification authority, price sensitivity, and technical support requirements.
- OEMs:Original equipment manufacturers in automotive and appliance sectors dictate formulation specifications through approved vendor lists. Chennai and Pune automotive clusters require bonded assembly line validation and batch traceability.
- Contractors:Construction application specialists prioritize on-site reliability and humidity-adjusted cure schedules. Western India building material distributors serve this segment through technical field support.
- Retailers:Consumer adhesive stockists in tier-2 and tier-3 cities emphasize brand recognition and shelf turnover. Pidilite Industries maintains network density advantages here.
- Distributors:Industrial chemical distributors consolidate fragmented demand from small and mid-sized manufacturers. Gujarat and Maharashtra hubs capture volume through inventory positioning and logistics integration.
Distributors handle the majority of throughput; OEMs are expanding their specification influence fastest on platform consolidation.
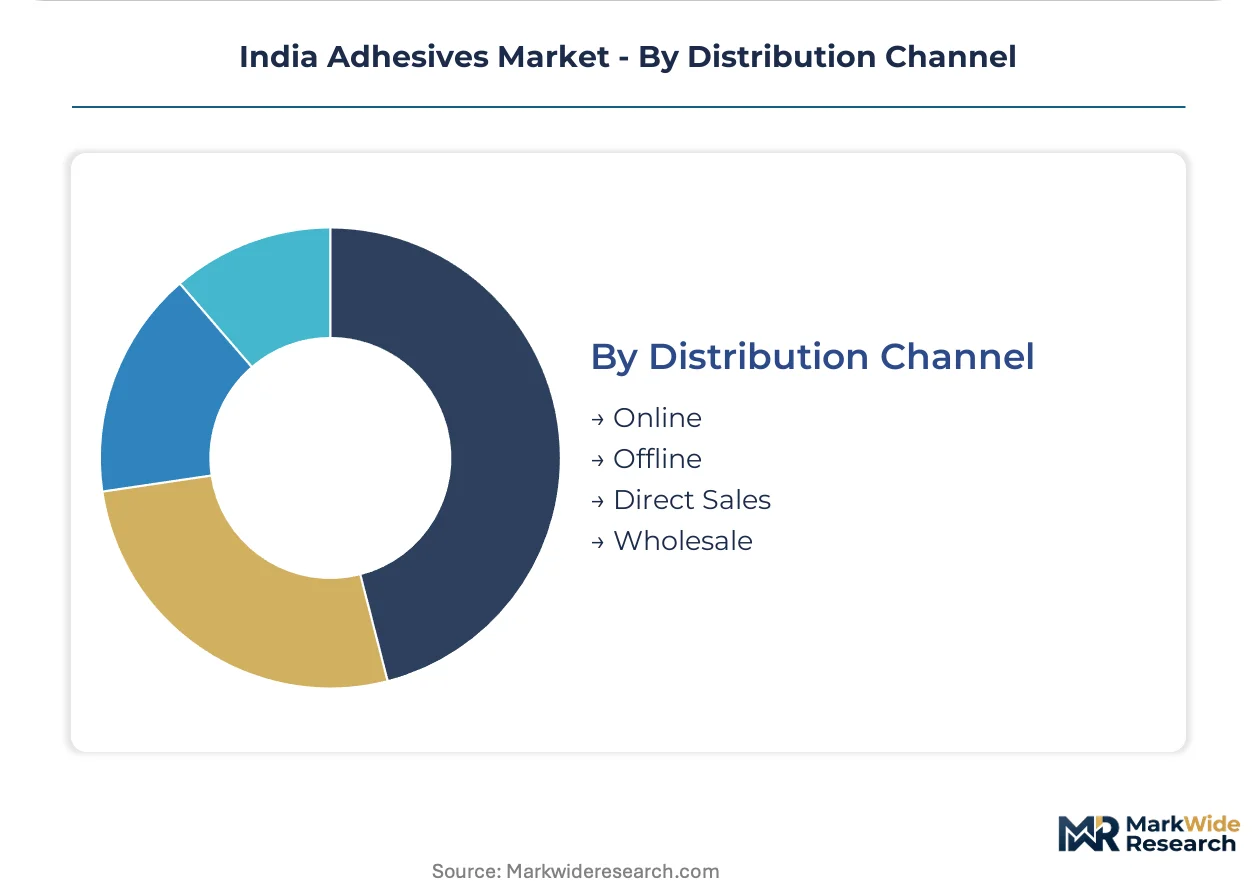
Distribution Channel:
Channel segmentation reflects how procurement convenience, technical consultation, and price transparency trade off across customer types.
- Online:E-procurement platforms serve small and mid-tier manufacturers with price transparency and consolidated logistics. Technical data sheet accessibility filters supplier qualification.
- Offline:Physical retail and trade counters dominate consumer adhesive purchases where immediate availability matters. Tier-3 city penetration requires last-mile inventory positioning.
- Direct Sales:Manufacturer field teams serve OEM accounts with application engineering and customized formulation development. Automotive and construction segments demand this channel for specification alignment.
- Wholesale:Bulk distributors aggregate demand from furniture and packaging clusters for volume-based pricing. Gujarat and Maharashtra wholesale hubs capture economies on resin procurement.
Offline channels handle the majority of throughput; online procurement is expanding most quickly among mid-tier manufacturers seeking price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Maharashtra and Gujarat dominate procurement volumes, while automotive OEMs in Tamil Nadu and construction contractors across western India shape specification trends through clustered demand concentration.
Maharashtra
Furniture manufacturing clusters and Mumbai-based packaging hubs drive formulation demand across water-based and hot-melt categories. BIS environmental guidelines filter supplier qualification for decorative bonding applications. Pune automotive suppliers are validating bonded assembly processes for electric vehicle component integration.
Gujarat
Chemical manufacturing infrastructure and export-oriented furniture production create dual demand streams for industrial adhesives. PLI scheme incentives for domestic chemical manufacturing are attracting formulation capacity investments. Ahmedabad and Surat industrial corridors host contract manufacturers capturing volume from brands previously dependent on imports.
Tamil Nadu
Chennai automotive OEMs are eliminating mechanical fasteners from battery enclosure designs through structural bonding expansion. Central Pollution Control Board emission thresholds are accelerating solvent-to-hot-melt conversions in footwear export clusters. Tier-1 suppliers around Sriperumbudur are adopting reactive polyurethane systems for EU REACH compliance.
Karnataka
Bengaluru electronics assembly and white goods manufacturing specify pressure-sensitive adhesives for component mounting and label applications. FSSAI compliance requirements filter food-contact adhesive procurement from packaging distributors. Mysuru furniture clusters are transitioning to certified water-based systems for tropical humidity performance.
Delhi-NCR
FMCG fulfillment centers and e-commerce packaging operations in Gurugram and Noida are expanding pressure-sensitive adhesive consumption for label-stock and corrugated sealing. BIS construction-grade certification mandates are consolidating supplier relationships toward tested domestic producers. Ghaziabad industrial zones host distributors aggregating fragmented demand from mid-tier manufacturers.
India Adhesives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Domestic formulation specialists leverage distribution density in tier-2 and tier-3 cities, while multinational technology leaders anchor automotive and construction specification pipelines. Three archetypes dominate: brand-loyalty sustainers through retail network control, specification anchors through OEM technical validation, and flexible contract manufacturers through asset-light capacity leasing. Competitive moves concentrate on portfolio diversification toward humidity-resistant construction grades and geographic penetration into underserved urban centers.
Among domestic market anchors, Pidilite Industries exemplifies the channel-control archetype through tier-2 and tier-3 network density, while Astral Adhesives occupies a position within construction-grade specialization. Henkel AG represents the technology-leader archetype for automotive structural bonding applications. These three companies illustrate the competitive vectors shaping procurement relationships across specification-driven and price-sensitive segments.
| Leading Market Players |
|---|
| Pidilite Industries |
| Henkel AG |
| 3M |
| H.B. Fuller |
| Arkema |
| Sika |
| Bostik |
| Astral Adhesives |
| Anabond |
| Others |
Supply & Pricing Matrix
Jawaharlal Nehru Port Trust freight corridors feed resin import costs directly into Maharashtra and Gujarat formulation hubs, compressing margins for water-based adhesive producers while amplifying price premiums on humidity-certified construction grades. This logistics chokepoint concentrates supply-side leverage among coastal contract manufacturers who can absorb landed cost volatility through volume scale.
Pricing Analysis
Cost-plus contracts with Singapore naphtha indexation dominate resin procurement agreements, spreading feedstock volatility across quarterly price adjustments. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified construction grades from uncertified industrial formulations and commodity furniture binders. Pricing pressure stems from Central Pollution Control Board compliance deadlines forcing premature solvent-to-water conversions before cost parity. Small packaging converters in tier-3 cities exhibit highest price sensitivity, while Chennai automotive OEMs prioritize technical validation over unit economics.
Supply Chain Analysis
Contract manufacturers in Gujarat and Maharashtra hold dominant formulation capacity, with Anabond and Astral Adhesives operating captive plants in Ahmedabad and Mumbai industrial corridors. Feedstock supply chains draw from Saudi petrochemical hubs, Singapore trading terminals, and domestic Reliance Industries resin streams. Single-source vulnerability concentrates in specialty tackifier imports from Southeast Asian chemical parks. Distribution runs through wholesale chemical distributors in Surat and Pune who aggregate fragmented furniture cluster demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and application engineering retainers are expanding faster than base adhesive volumes, as automotive OEMs and construction contractors outsource bonding process validation. This service-attach dynamic rewards players who bundle formulation supply with on-site technical support.
For Market Incumbents: Entrench specification control through BIS certification pre-emptiveness before mandate expansion tightens compliance windows. Deepen backward integration into acrylic emulsion production to offset Singapore naphtha price volatility. Lock in multi-year technical service agreements with Pune and Chennai automotive clusters to raise switching costs for rival suppliers.
For New Entrants and Emerging Players: Tier-3 city retail networks present the most penetrable white space, where Pidilite's distribution density thins and local stockists seek alternative brand partnerships. Target humidity-resistant furniture adhesive segments in Mysuru and Kochi manufacturing clusters where tropical performance requirements filter out uncertified imports. Lead with asset-light equipment leasing partnerships to bypass capital barriers that constrain mid-tier scale.
For Investors and Strategic Acquirers: PLI scheme extension deadlines reshape the acquisition landscape toward domestic formulation assets with residual import dependency. Five-to-ten-year viability favors contract manufacturers with established Gujarat-Maharashtra logistics integration over pure brand plays lacking captive capacity. Monitor BIS construction-grade certification approval timelines as the signal indicating which mid-tier assets will capture specification-driven margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion | Captive resin production insulates margins from Singapore naphtha index volatility. |
| BIS Pre-Certification Investment | Early compliance with load-bearing adhesive mandates locks out reformulation-lagged competitors. |
| Technical Service Contract Expansion | Application engineering retainers with Chennai OEMs raise switching costs and attach recurring revenue. |
| Tier-3 Distribution Network Buildout | Last-mile inventory positioning in underserved urban centers captures consumer adhesive volume. |
| Hot-Melt System Conversion Partnerships | Solvent-free packaging adhesive adoption preempts Central Pollution Control Board enforcement costs. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with adhesive plant managers, automotive procurement leads at Chennai and Pune OEMs, construction material distributors in western India, and technical R&D directors at formulation houses; and secondary validation through BIS certification registries, Central Pollution Control Board emission compliance filings, customs import data for acrylic resin and tackifier feedstocks, and PLI scheme beneficiary disclosures. Bottom-up volume estimates from state-level industrial consumption patterns were triangulated against top-down market sizing from chemical industry association aggregates.
Forecast inputs considered formulation chemistry migration rates, regulatory compliance timeline acceleration, and electric vehicle platform bonding content expansion across the projection horizon. Segmentation modeling captured product type, application end-use, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories at major formulation centers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Gujarat contract manufacturers or sudden PLI scheme restructuring would shift outcomes. Quarterly review of BIS certification approval backlogs, Singapore naphtha price index movements, and Chennai automotive bonded assembly line commissioning rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Heat Resistant Sealant Market