
 2,3-Butanediol Market | 2026-2036
2,3-Butanediol Market Size, Share, and Industry Trends Forecast 2026-2036
2,3-Butanediol Market Intelligence
Project finance for industrial biorefineries is fragmenting competitive entry barriers in the 2,3-Butanediol space. LanzaTech Inc. leverages gas-fermentation expertise to anchor production economics on waste carbon feedstocks. Merck KGaA sustains pharmaceutical-grade supply chains through stringent quality systems. Mitsubishi Chemical Corporation dominates chemical synthesis routes for high-purity meso-isomer output.
2,3-Butanediol (C4H10O2) is a vicinal diol existing as four stereoisomers, produced industrially via microbial fermentation of sugars or catalytic hydrogenation of precursors, and serves primarily as a chiral building block and polymer intermediate. The racemic product type occupies the largest volume share due to lower separation costs and broad solvent applicability. Polymer precursors among application segments capture expanding margin pools as polybutylene succinate manufacturers seek bio-based diol inputs. Fermentation as a production method is gaining structural prominence amid carbon accounting pressures, though chemical synthesis retains cost advantages at scale.
EPA biofuel standards under the Renewable Fuel Standard program shape domestic market access for fermentation-derived material in the United States. REACH registration requirements in Europe enforce purity and toxicity documentation that favors established producers with dossier capabilities. FDA pharmaceutical excipient guidelines further segment the market between technical-grade and GMP-compliant supply tiers. Stakeholders must monitor carbon border adjustment mechanisms and evolving lifecycle assessment protocols to determine feedstock and production technology commitments.
Market Dynamics
Fermentation-based production routes are restructuring capital allocation across the 2,3-Butanediol value chain as carbon accounting methodologies harden procurement specifications for bio-based polymer precursors.
Growth Catalysts
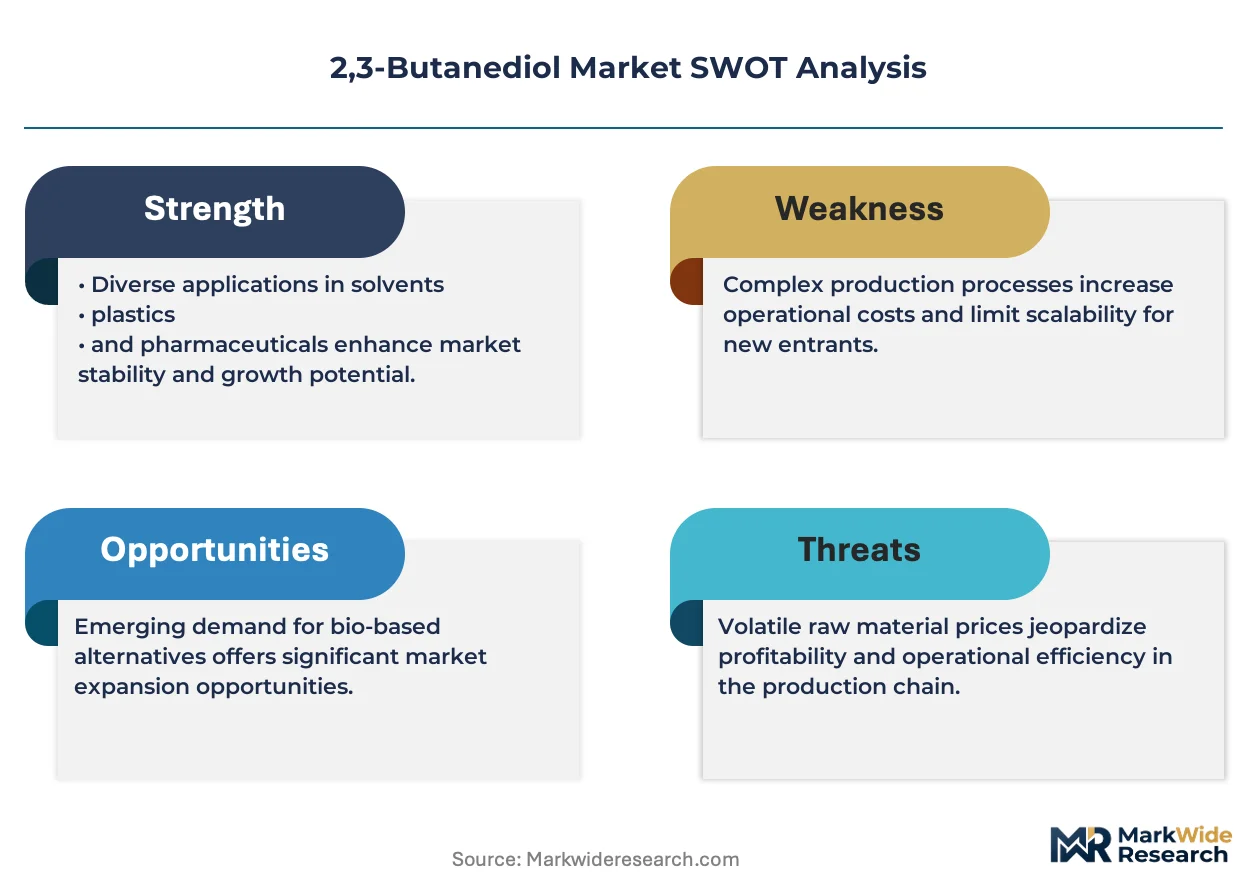
- REACH Registration Thresholds:European chemical buyers now require full substance dossiers for polymer-grade diol inputs, favoring fermentation producers with existing compliance infrastructure over import-dependent traders.
- Polybutylene Succinate Uptake:Biodegradable packaging manufacturers in Germany and the Netherlands are specifying bio-based diol content above 50% for food-contact applications.
- Gas-Fermentation Yields:Steel mill off-gas utilization is cutting feedstock costs for acetoin-reductase pathway producers, compressing the cost gap against petrochemical routes.
Market Restraints
- Sugar Feedstock Volatility:Brazilian sucrose price swings transmit directly to fermentation economics, squeezing margin stability for unhedged biorefinery operators.
- Meso-Isomer Supply Concentration:High-purity chemical synthesis capacity clusters in East Asian petrochemical complexes, creating single-source risk for pharmaceutical chiral building block buyers.
- 1,4-Butanediol Substitution:Established polybutylene terephthalate supply chains lock in incumbent diol specifications, blocking 2,3-isomer penetration in mainstream polyester applications.
Strategic Opportunities
- India PLI Scheme Alignment:Contract manufacturing for specialty chemicals qualifies for production-linked incentives, attracting fermentation technology licensors to Maharashtra and Gujarat industrial corridors.
- Aviation Fuel Precursors:C4 diol dehydration to methyl ethyl ketone opens jet fuel blendstock pathways as ASTM certification for bio-derived ketones advances.
- Carbon Border Adjustment Positioning:EU CBAM scope expansion to embedded emissions in chemicals creates first-mover advantage for producers with certified low-carbon fermentation routes.
Industry Challenges
- Industrial Microbiologist Scarcity:Strain engineering and bioprocess optimization talent concentrates in academic clusters, forcing producers to compete with pharmaceutical CDMOs for experienced fermentation scientists.
- GMP Certification Timelines:Pharmaceutical-grade 2,3-Butanediol qualification requires 18-24 month FDA validation cycles, delaying revenue recognition for new biorefinery assets targeting excipient markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2,3-Butanediol Market |
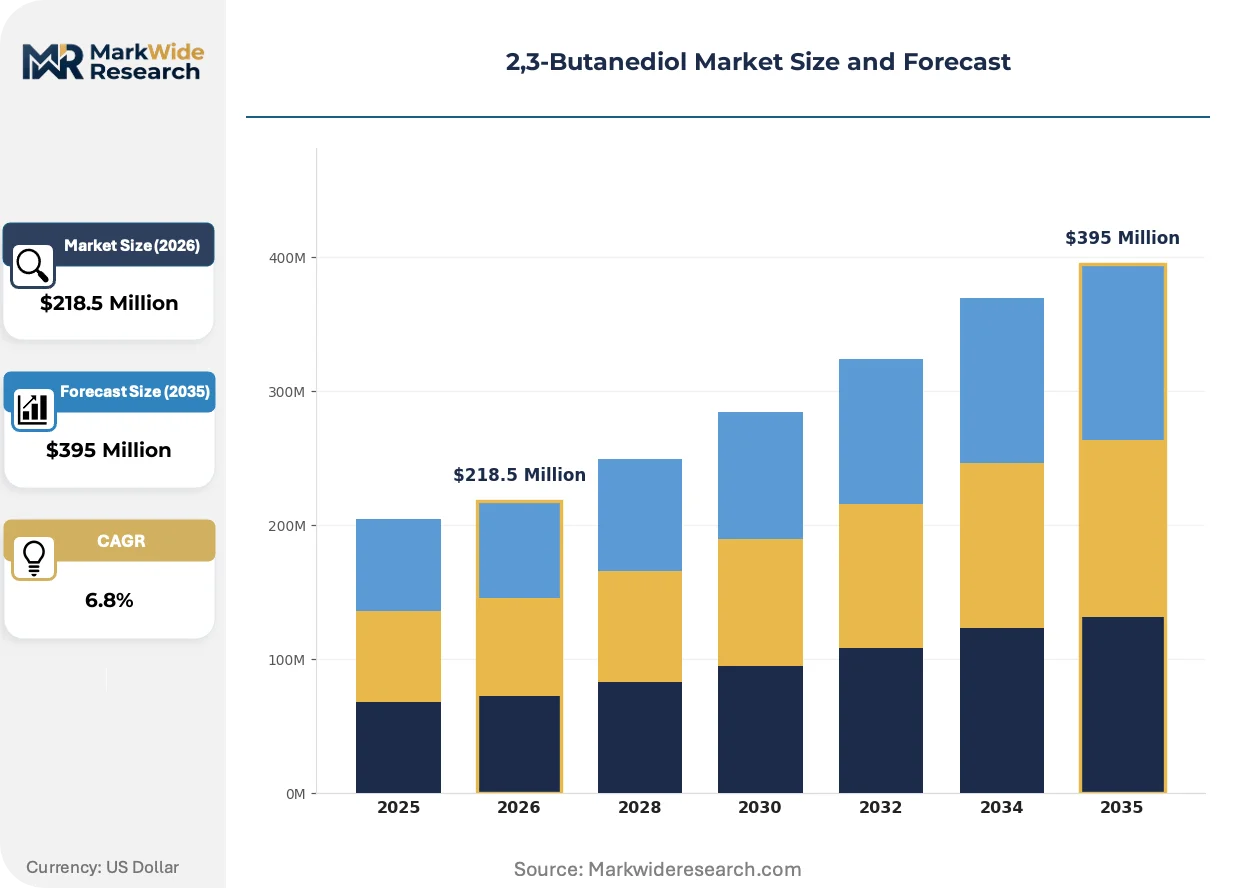
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $395 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Racemic, (2R,3R)-Butanediol, (2S,3S)-Butanediol, Mesobutanediol Application: Solvent, Fuel Additive, Polymer Precursors, Plasticizers, Coatings End Use Industry: Pharmaceutical, Cosmetics, Agrochemicals, Adhesives, Food & Beverage Production Method: Fermentation, Chemical Synthesis, Catalytic Hydrogenation, Bioconversion |
| Companies Covered | LanzaTech Inc., Merck KGaA, Mitsubishi Chemical Corporation, Orochem Technologies Inc, Nanya Plastics Corporation, Global Bio-Chem Technology Group, Tokyo Chemical Industry Co., Ltd., Shanxi Sanwei Group, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2,3-Butanediol Market Strategic Shifts & Innovations
Continuous processing architectures and machine-learning-guided strain development are compressing batch cycle times while regulatory carbon intensity metrics restructure buyer-supplier contracting terms.
CRISPR-edited Klebsiella pneumoniae strains with knocked-out byproduct pathways now achieve selectivity above 95% for the (2R,3R)-stereoisomer. Specialty polymer compounders in Japan are qualifying these outputs for optical film applications. Traditional crystallization-based separation trains are rendering obsolete as membrane-assisted pervaporation cuts energy intensity by half.
EPA's evolving Renewable Fuel Standard treatment of biogenic carbon from waste streams is redirecting project finance toward gas-fermentation platforms. Industrial biotechnology developers are restructuring offtake agreements to capture RIN value alongside chemical sales. Fermentation-derived material now commands preferential access to California LCFS credit markets versus thermochemical routes.
Long-term tolling contracts are displacing spot market purchases as polybutylene succinate producers seek supply security for capacity expansions. Compounders in northern Italy are locking in five-year fermentation diol supply agreements with fixed carbon intensity clauses. This contracting shift is most visible in automotive interior applications where OEM sustainability scorecards penalize supply chain volatility.
2,3-Butanediol Market Segmentation
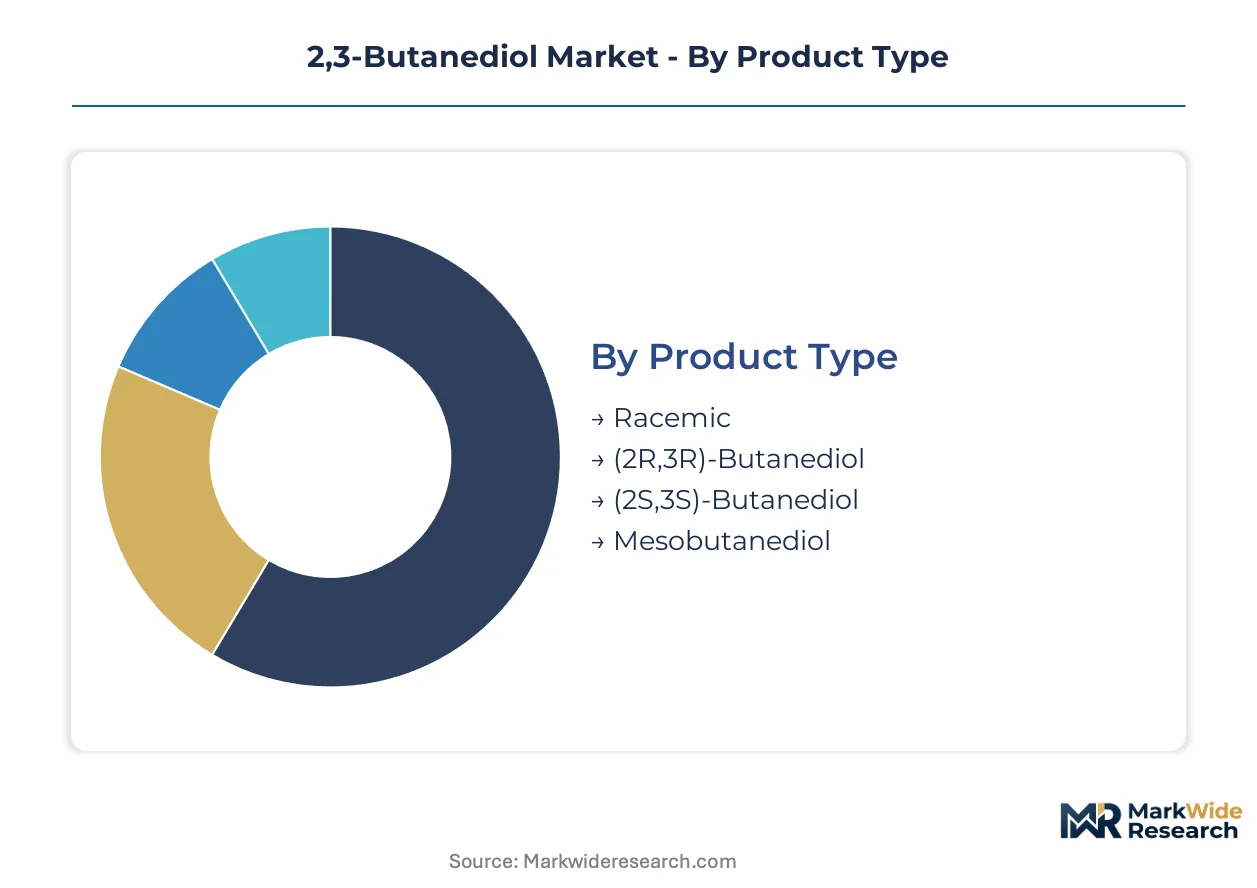
Segmentation in the 2,3-Butanediol market tracks how stereochemical purity requirements, production route carbon intensity, and end-use regulatory thresholds split procurement behavior across technical-grade and pharmaceutical-grade tiers.
Product Type:
Cost tier differentiation separates commodity solvent applications from chiral building block specifications requiring enantiomeric excess above 99%.
- Racemic:An equimolar mixture of (2R,3R) and (2S,3S) stereoisomers serves broad solvent and fuel additive applications where optical purity offers no performance advantage. Polymer compounders in Germany specify racemic grades for cost-sensitive polybutylene succinate formulations.
- (2R,3R)-Butanediol:The dextrorotatory enantiomer functions as a chiral synthon for pharmaceutical intermediates and liquid crystal precursors. Japanese optical film manufacturers are qualifying CRISPR-optimized fermentation outputs for polarizer substrate production.
- (2S,3S)-Butanediol:The levorotatory mirror enantiomer commands narrower demand pools in specialized agrochemical synthesis.
- Mesobutanediol:The achiral internal diastereomer with a plane of symmetry supplies high-purity polymer segments where crystallinity control matters.
Racemic product holds installed capacity. (2R,3R)-Butanediol is rotating up the share rankings.
Application:
Application segmentation tracks how biodegradability mandates and volatility specifications redirect volume across fuel, materials, and formulation chemistry end uses.
- Solvent:Low-toxicity polar aprotic characteristics position 2,3-butanediol as a replacement for N-methyl-2-pyrrolidone in coatings stripping and resin cleanup operations. REACH-registered fermentation grades are displacing petrochemical glycol ethers in European industrial maintenance formulations.
- Fuel Additive:C4 diol dehydration pathways to methyl ethyl ketone create blendstock opportunities for sustainable aviation fuel precursors. ASTM certification progress for bio-derived ketones is unlocking offtake interest from US renewable diesel producers.
- Polymer Precursors:Diol inputs for polybutylene succinate and copolyester elastomers anchor the fastest-expanding demand segment as food-contact biodegradable packaging specifications tighten.
- Plasticizers:Esterified derivatives soften biopolymer compounds in compostable film and sheet applications.
- Coatings:Hydroxyl functionality supports polyurethane dispersion crosslinking in automotive refinish and industrial maintenance segments.
Solvent applications hold installed capacity. Polymer precursors are rotating up the share rankings.
End Use Industry:
Customer type segmentation reflects how FDA, EMA, and ECHA dossier requirements partition supply chains between technical-grade traders and GMP-certified manufacturers.
- Pharmaceutical:Chiral building block demand for antibiotic and antiviral synthesis drives the highest purity specifications. Merck KGaA and specialized CDMOs maintain validated supply chains for excipient-grade material with full ICH Q3D elemental impurity documentation.
- Cosmetics:Humectant and emollient functions in skin care formulations require odorless, colorless grades with heavy metal limits below 10 ppm.
- Agrochemicals:Stereoselective synthesis of pyrethroid insecticides consumes (2R,3R)-enantiomer in contract manufacturing arrangements.
- Adhesives:Polyurethane reactive hot-melt formulations exploit low-temperature flexibility in automotive interior assembly.
- Food & Beverage:Flavor carrier and moisture-retention applications face FSSAI and FDA food additive petition requirements limiting supplier pools.
Pharmaceutical applications hold installed capacity. Cosmetics are rotating up the share rankings.
Production Method:
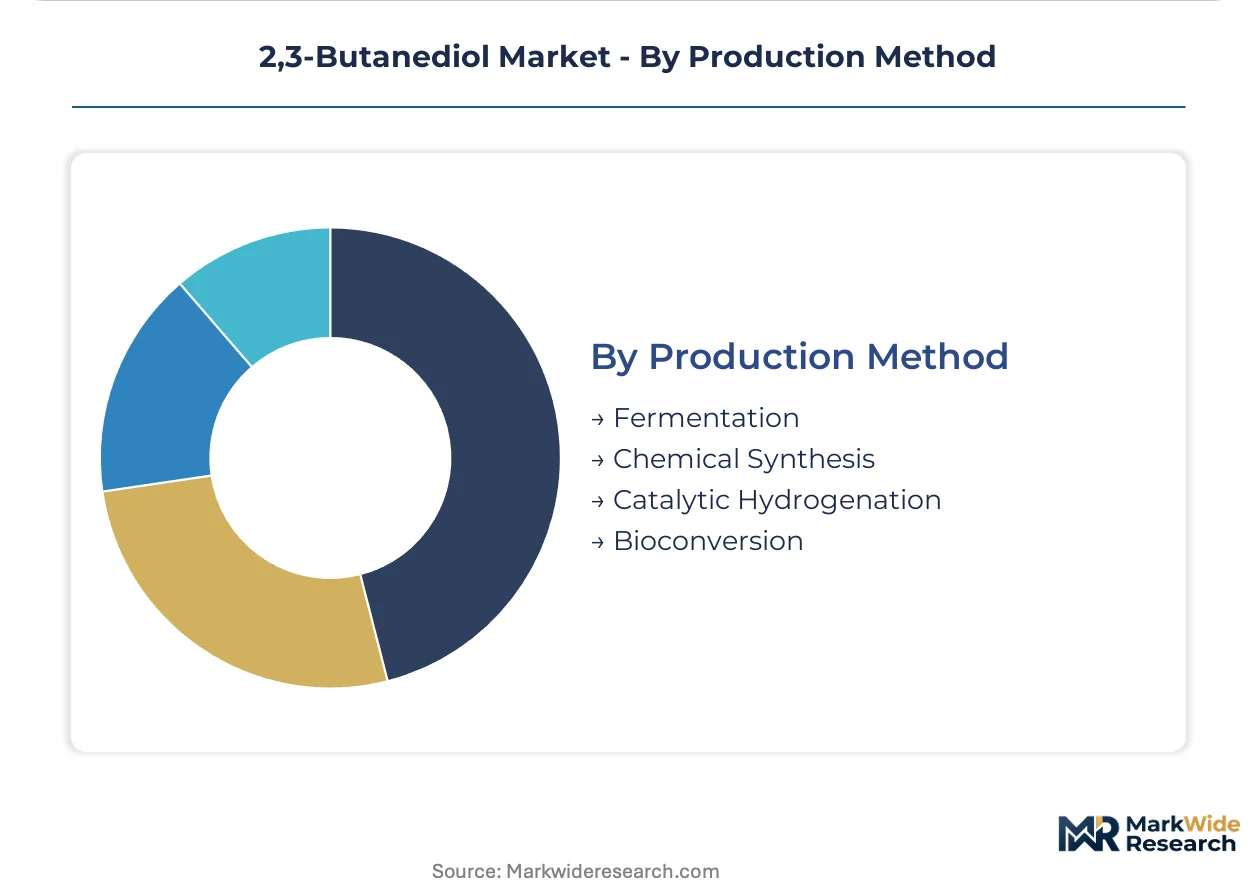
Supply concentration across fermentation versus chemical synthesis routes determines carbon intensity certification access and feedstock hedge positioning.
- Fermentation:Microbial conversion of sugars or syngas via acetoin reductase pathways delivers bio-based content certification for polymer applications. LanzaTech's gas-fermentation platform anchors steel mill off-gas valorization economics.
- Chemical Synthesis:Catalytic hydrogenation of butanedione or acetylacetone achieves meso-isomer selectivity above 99% for high-purity polymer segments. Mitsubishi Chemical Corporation maintains East Asian capacity leadership.
- Catalytic Hydrogenation:Petrochemical feedstock routes retain cost advantages at scale for racemic product where optical purity is irrelevant.
- Bioconversion:Enzymatic resolution of racemic mixtures or stereoinversion processes recovers chiral enantiomers from mixed fermentation broths.
Chemical synthesis holds installed capacity. Fermentation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in 2,3-Butanediol are tightening as regional decarbonization mandates reshape procurement geography. Countries with certified fermentation capacity now command premium access to polymer supply chains.
United States
Steel mill off-gas valorization projects in Indiana and Ohio anchor gas-fermentation economics for acetoin-reductase pathway producers. EPA Renewable Fuel Standard credit treatment for biogenic carbon streams is redirecting project finance toward waste feedstock platforms. Chicago-area industrial biotechnology clusters now host tolling agreements linking Midwest steel emissions to California LCFS markets.
Germany
Polybutylene succinate compounders in Bavaria and North Rhine-Westphalia specify bio-based diol content above 50% for food-contact packaging. REACH registration dossier requirements favor established fermentation producers with full substance documentation over import-dependent traders. The Frankfurt-Rhine-Main biotechnology corridor anchors contract manufacturing for pharmaceutical-grade chiral building blocks.
China
Catalytic hydrogenation capacity for high-purity meso-isomer concentrates in Shandong and Jiangsu petrochemical complexes. Dual carbon goals under the national climate strategy are accelerating biorefinery pilot projects in the Yangtze River Delta. Shanghai-based polymer researchers now qualify fermentation-derived racemic grades for biodegradable film applications.
India
Production-linked incentive schemes for specialty chemicals in Maharashtra and Gujarat industrial corridors attract fermentation technology licensors. CDSCO pharmaceutical excipient guidelines segment supply chains between technical-grade traders and GMP-certified manufacturers. Mumbai-Pune biotechnology clusters now host strain engineering partnerships targeting agrochemical chiral synthesis.
Japan
Optical film manufacturers in Kansai and Chubu regions qualify CRISPR-optimized (2R,3R)-enantiomer outputs for polarizer substrate production. METI circular economy roadmaps mandate bio-based content thresholds in electronics packaging materials. Osaka-based polymer compounders now lock in long-term tolling contracts with fixed carbon intensity clauses.
2,3-Butanediol Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability tiers: petrochemical synthesis incumbents with meso-isomer dominance, gas-fermentation specialists leveraging waste carbon feedstocks, and pharmaceutical-grade operators maintaining GMP-validated supply chains. Strategic archetypes include carbon-accounting-first producers, purity-premium compounders, and regional tolling intermediaries. Capacity expansion and technology licensing now outpace M&A as dominant competitive moves.
Within the carbon-accounting tier, LanzaTech Inc. exemplifies gas-fermentation platform economics. Merck KGaA occupies a position representing pharmaceutical-grade supply chain validation. Mitsubishi Chemical Corporation anchors the petrochemical synthesis archetype for high-purity stereoisomer output.
| Leading Market Players |
|---|
| LanzaTech Inc. |
| Merck KGaA |
| Mitsubishi Chemical Corporation |
| Orochem Technologies Inc |
| Nanya Plastics Corporation |
| Global Bio-Chem Technology Group |
| Tokyo Chemical Industry Co., Ltd. |
| Shanxi Sanwei Group |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Sugar feedstock volatility in Brazilian sucrose markets determines both the spread between fermentation and chemical synthesis tiers and the geographic clustering of biorefinery investments. Polybutylene succinate compounders in Germany and the Netherlands now negotiate long-term offtake contracts with fixed carbon intensity clauses to hedge against raw material swings.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across pharmaceutical-grade, polymer-grade, and technical-solvent tiers. Price differentiation centers on REACH registration status and GMP certification level, with fermentation-derived racemic product commanding premiums over petrochemical routes in European markets. Cost compression in technical-grade segments is intensifying because Brazilian ethanol price volatility transmits directly to unhedged fermentation operators. Polymer compounders in automotive interiors show least price sensitivity due to OEM sustainability scorecard requirements, while coatings formulators remain most sensitive to diol input costs.
Supply Chain Analysis
Extended payment terms from polybutylene succinate producers are restructuring working capital requirements for fermentation operators in Germany, China, and India. Raw material sourcing draws from Brazilian sucrose, Midwest US steel mill off-gas, and East Asian petrochemical naphtha streams. Single-source vulnerability concentrates in high-purity meso-isomer supply from Shandong and Jiangsu petrochemical complexes. Distribution runs through regional tolling agreements linking fermentation capacity to compounder facilities in Bavaria, North Rhine-Westphalia, and northern Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among polybutylene succinate manufacturers locking in five-year fermentation diol supply agreements, fragmenting spot market liquidity and shifting negotiation leverage toward volume-committed purchasers.
For Market Incumbents: Harden carbon intensity certification infrastructure to defend polymer-grade premiums against gas-fermentation entrants leveraging steel mill off-gas economics. Backward integration into strain engineering capabilities in the Frankfurt-Rhine-Main biotechnology corridor protects against industrial microbiologist scarcity. Anchor GMP-validated supply chains for pharmaceutical excipient tiers to maintain dossier advantages under FDA and EMA requirements. For New Entrants and Emerging Players: Build out tolling capacity in Maharashtra and Gujarat industrial corridors to capture India PLI scheme benefits for specialty chemical contract manufacturing. White-space exists in (2R,3R)-enantiomer supply for Japanese optical film manufacturers qualifying CRISPR-optimized fermentation outputs. Position gas-fermentation platforms for aviation fuel precursor pathways as ASTM certification for bio-derived ketones advances. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors fermentation technology licensors with demonstrated carbon accounting methodologies. Long-term viability hinges on EU CBAM scope expansion to embedded emissions in chemicals, creating first-mover advantage for certified low-carbon routes. Watch for CDSCO pharmaceutical excipient guideline tightening as the inflection indicator for GMP-certified supply chain valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Engineering | Captures scarce industrial microbiologist talent in Frankfurt-Rhine-Main and Mumbai-Pune clusters. |
| Long-term Supply Agreement with Fixed Carbon Clauses | Locks in polybutylene succinate demand from German automotive interior compounders. |
| Green Manufacturing Transition to Gas-Fermentation | Accesses EPA Renewable Fuel Standard credits and California LCFS markets via steel mill off-gas. |
| Capacity Expansion in Maharashtra Industrial Corridor | Qualifies for India PLI scheme production-linked incentives in specialty chemicals. |
| Joint Venture with Optical Film Manufacturers | Secures offtake for CRISPR-optimized (2R,3R)-enantiomer in Japanese polarizer substrate applications. |
Research Approach
Initial hypotheses were tested against primary input from fermentation plant managers, polymer compounder procurement leads, pharmaceutical CDMO regulatory affairs directors, and steel mill off-gas project developers and refined through secondary validation. Trade data from Eurostat and UN Comtrade, SEC filings from listed chemical producers, ECHA REACH registration dossiers, and EPA Renewable Fuel Standard compliance reports anchored supply-side quantification. Bottom-up capacity estimates triangulated against top-down demand models from polybutylene succinate and biodegradable packaging end-use segments.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by stereoisomer purity tier, production route carbon intensity, and end-use regulatory threshold. The framework captured racemic versus enantiomeric product splits, fermentation versus chemical synthesis capacity shares, and pharmaceutical-grade versus technical-grade demand pools. CAGRs were derived from production economics modeling incorporating Brazilian sucrose price scenarios and EU carbon border adjustment mechanism phase-in assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by East Asian petrochemical operators or rapid ASTM certification of bio-derived ketones would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Mass Transfer Trays Market