
 Europe Isocyanates Market | 2026-2036
Europe Isocyanates Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Isocyanates Market Foresight
Market Context
A widening capital-intensity divergence between integrated phosgene producers and non-integrated compounders is unwinding competitive stability across the European supply base. BASF SE leverages its Ludwigshafen Verbund site to sustain captive chlorine and precursor supply, while Covestro AG anchors its European MDI network on Antwerp and Brunsbüttel assets with backward integration into aniline. Huntsman Corporation competes through specialized systems house operations that navigate custom formulation demand without owning upstream phosgene capacity.
Technical Definition and Segment Structure
Isocyanates are reactive organic compounds containing the functional group R-N=C=O, manufactured primarily through phosgenation of amines with purities exceeding 99.5% for polymer-grade MDI and TDI, serving as the essential crosslinking component in polyurethane synthesis across insulation, coatings, and elastomer applications. MDI dominates volume flows into construction rigid foam where thermal conductivity specifications below 0.022 W/m·K drive specification lock-in, while TDI sustains margin pools in flexible furniture and automotive seating applications where resilience and compression set requirements favor aliphatic formulations. Green chemistry technology remains nascent but growing fastest as non-phosgene routes using carbonates or carbamates attract pilot investment from producers seeking to de-risk REACH authorization exposure.
Regulatory Framework and Outlook
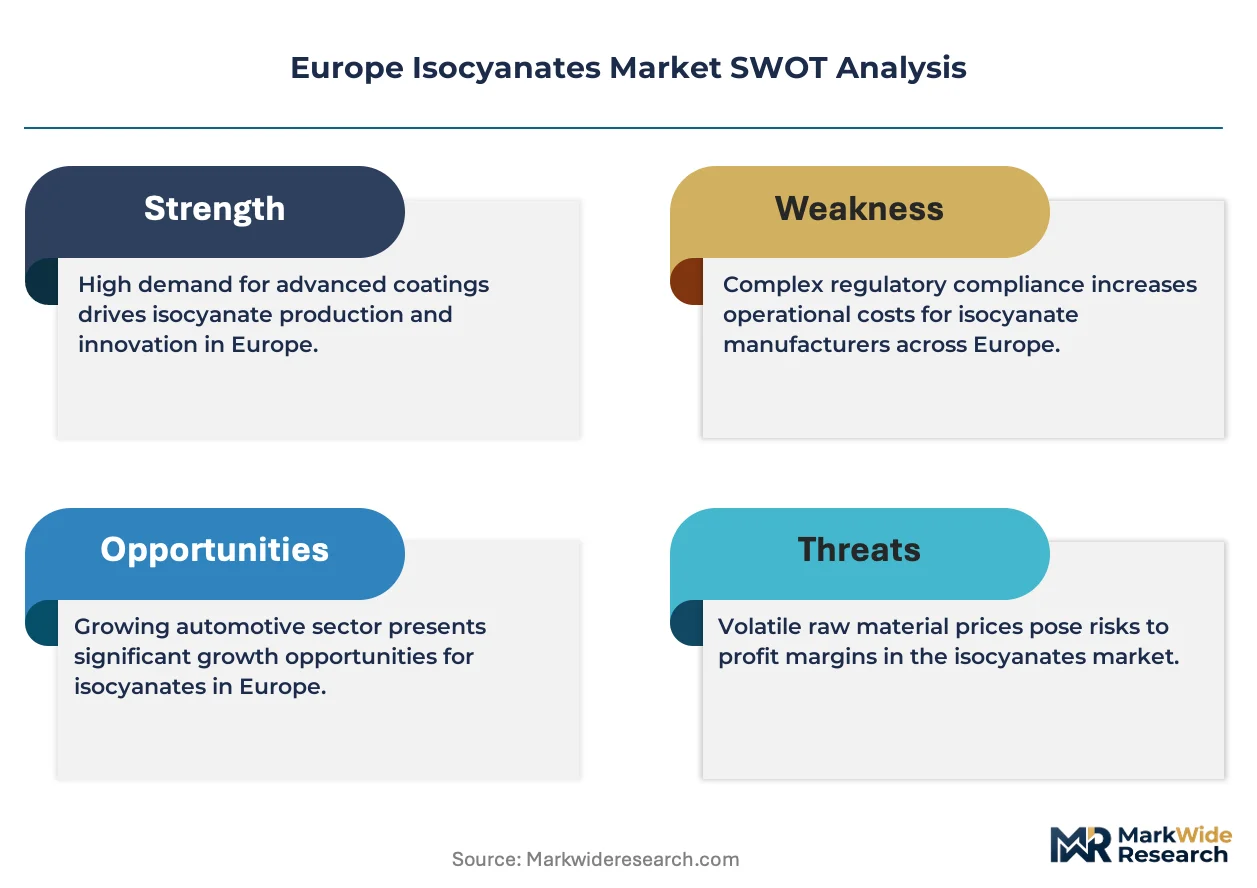
ECHA REACH restrictions on diisocyanate respiratory sensitization have reshaped product handling standards, mandating training protocols and exposure limits that elevate compliance costs for downstream processors. The EU Green Deal carbon border adjustment and F-Gas Regulation phase-down reinforce demand for high-performance polyurethane insulation with lower lifecycle embodied carbon. Stakeholders must monitor the interplay between ECHA authorization timelines and the pace of non-phosgene technology maturation to calibrate capital allocation between incumbent asset refurbishment and alternative chemistry platforms.
Market Dynamics
Capital allocation across the European isocyanates base is bifurcating between incumbent phosgene asset refurbishment and non-phosgene pilot investment, as ECHA authorization timelines compress strategic optionality for producers weighing regulatory de-risking against sunk cost recovery.
Growth Catalysts
- EU Green Deal carbon performance mandates:Building renovation wave targets trigger rigid foam specification for 0.022 W/m·K thermal conductivity in German and French construction permits.
- Automotive lightweighting:OEM seating programs in Germany and Spain sustain TDI derivative demand for resilience-critical polyurethane elastomer applications.
- F-Gas Regulation phase-down:High-GWP blowing agent restrictions accelerate pentane-compatible MDI formulation adoption across European insulation processors.
Market Restraints
- Chlorine and aniline feedstock volatility:European chlor-alkali curtailments and benzene derivative pricing swings compress integrated producer margins at Ludwigshafen and Antwerp Verbund sites.
- Phosgene supply concentration:Four producers control 85% of European phosgenation capacity, creating single-source vulnerability for non-integrated systems houses.
- REACH authorization friction:ECHA diisocyanate respiratory sensitization restrictions mandate training protocols and exposure monitoring that elevate processor compliance costs.
Strategic Opportunities
- Eastern European construction penetration:Poland and Romania building stock renovation lags Western Europe by 15-20 years, creating specification upgrade runway for rigid foam systems.
- Non-phosgene carbonate chemistry:Carbamate route pilot investments by diversified chemical groups target REACH authorization de-risking and lifecycle carbon reduction.
- Industrial aftermarket services:Systems houses are unbundling formulation support from material supply, creating recurring revenue streams through technical service contracts.
Industry Challenges
- Phosgenation process engineering expertise:Retiring specialist workforce at Brunsbüttel and Antwerp facilities constrains debottlenecking and safety protocol maintenance.
- Legacy asset refurbishment capex:MDI train modernization at 40-year-old European sites requires 200-300 million euro commitments with uncertain authorization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Isocyanates Market |
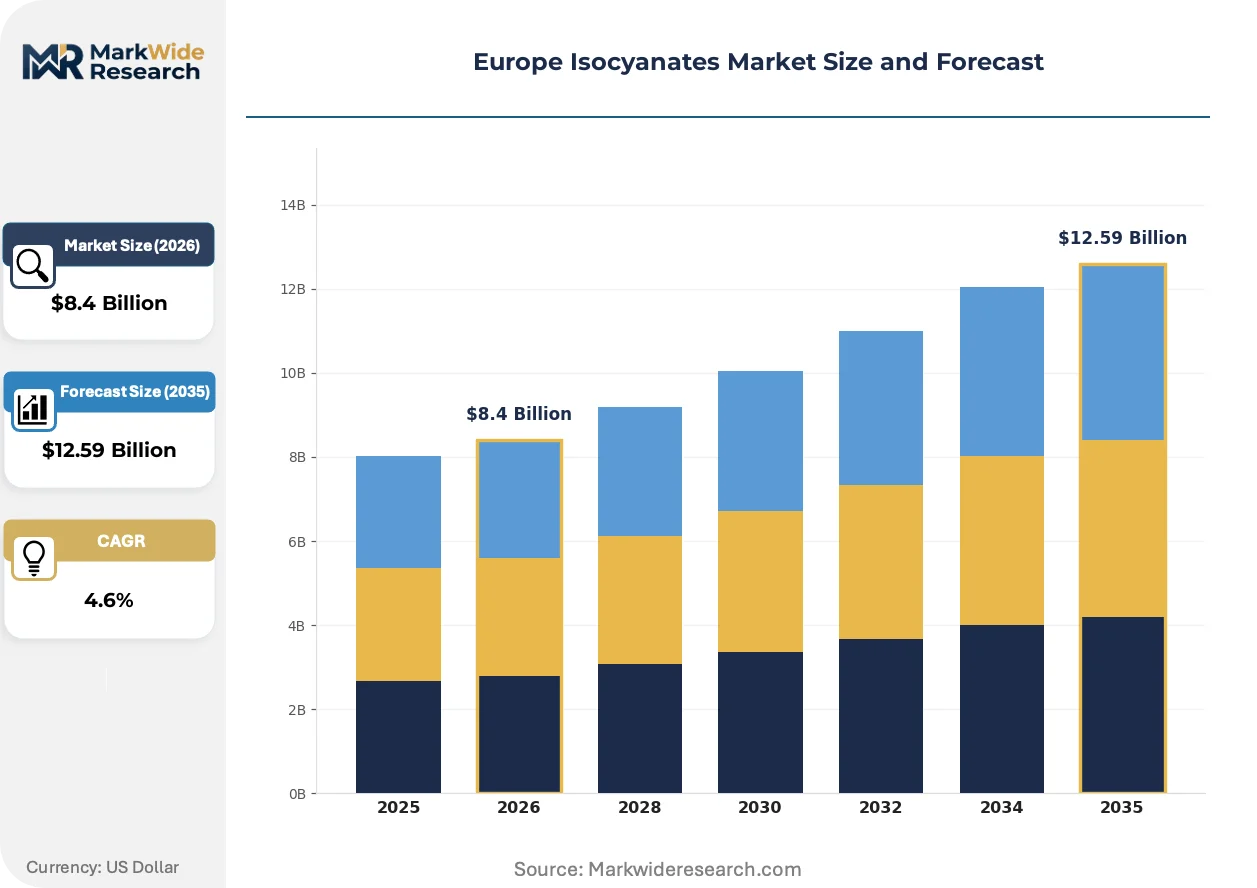
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MDI, TDI, NDI, PU Prepolymers End User: Construction, Automotive, Coatings, Furniture Application: Insulation, Adhesives, Sealants, Rigid Foam Technology: Batch Process, Continuous Process, Green Chemistry, Hybrid Process |
| Companies Covered | Wanhua Chemical Group Co. Ltd., Huntsman Corporation, BASF SE, Lanxess AG, Mitsui Chemicals, Inc., Covestro AG, Tosoh Corporation, Dow Inc., Evonik Industries AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Isocyanates Market Shifts & Advancements
Technology substitution and regulatory stringency are compressing incumbent process economics while opening white space for alternative chemistry platforms and service-led business models.
Carbonate-based non-phosgene routes are supplanting conventional amine phosgenation in pilot-scale European investments. Specialty chemical groups with diversified feedstock positions are funding carbamate chemistry development to circumvent REACH authorization exposure. This technology trajectory is compressing the strategic window for incumbent asset life extension decisions.
REACH diisocyanate restriction mandates are reshaping downstream handling infrastructure across European polyurethane processors. ECHA training certification requirements and exposure limit protocols are elevating capital intensity for small-to-mid compounders without captive technical resources. German and Benelux insulation specialists are consolidating formulation operations to amortize compliance infrastructure across larger volume bases.
Buyer concentration among European automotive OEMs and construction material distributors is compressing pricing leverage for non-integrated systems houses. Procurement functions at German OEM seating divisions and French building envelope specialists are consolidating supplier panels to three-to-four approved sources with technical service integration requirements. This pattern is most pronounced in German automotive supply chains and Benelux construction distribution networks.
Europe Isocyanates Market Segmentation
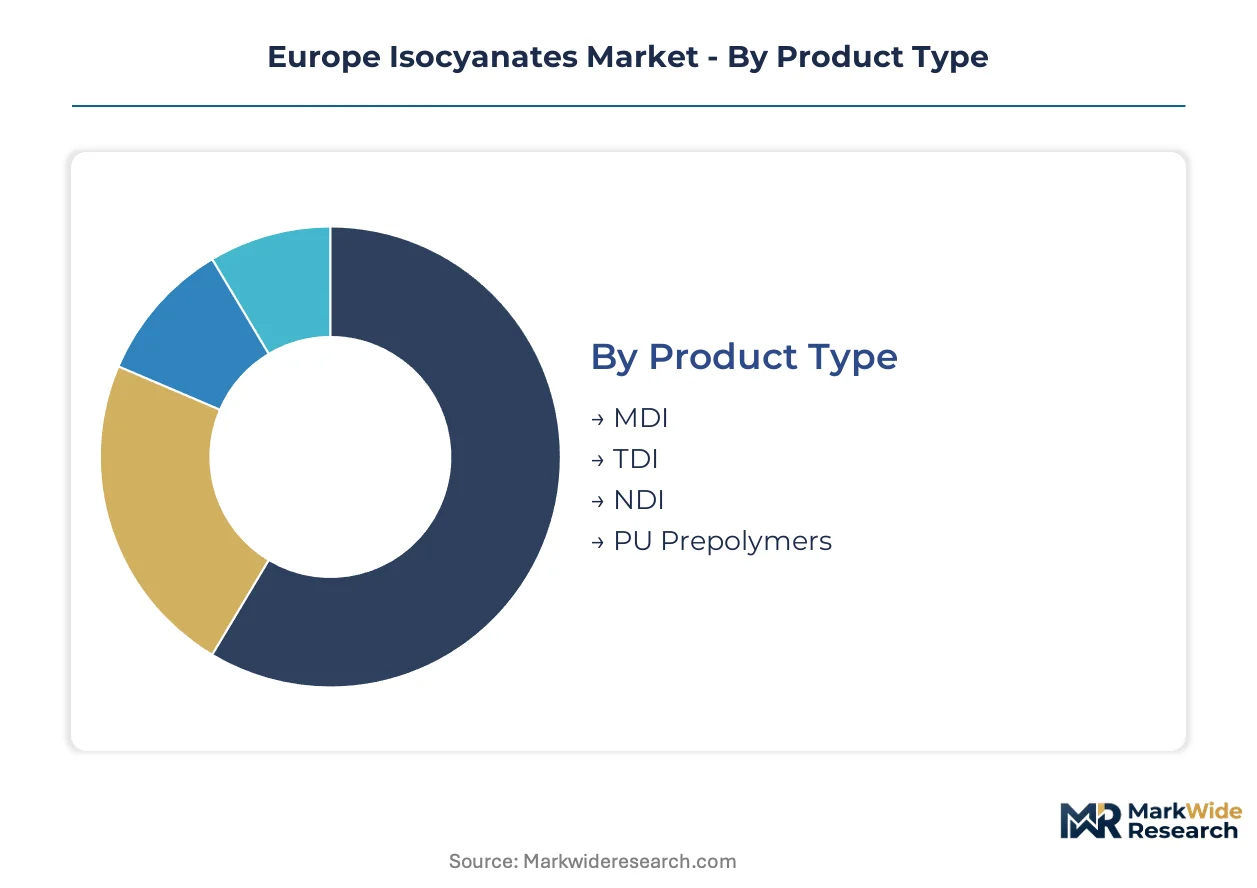
Isocyanate segmentation in Europe tracks divergent margin trajectories between incumbent phosgene-based commodity flows and emerging non-phosgene specialty platforms. Producers calibrate portfolio allocation across these categories based on ECHA authorization timelines and carbon border exposure.
Product Type:
Margin pools concentrate in MDI derivatives serving thermal conductivity specifications, while TDI sustains premium pricing in automotive seating formulations.
- MDI:Polymer-grade purity exceeding 99.5% enables rigid foam crosslinking with thermal conductivity below 0.022 W/m·K. German and French construction permits under EU Green Deal carbon performance mandates anchor volume concentration for energy-efficient building envelopes.
- TDI:Aliphatic formulations deliver resilience and compression set properties critical for flexible polyurethane applications. OEM seating programs in Germany and Spain sustain derivative demand where automotive lightweighting specifications favor elastomer performance.
- NDI:Naphthalene-based specialty isocyanate serving high-performance elastomer and coating applications with superior heat resistance.
- PU Prepolymers:Custom-formulated systems house products combining isocyanate functionality with tailored polyol blends for processor-specific requirements.
MDI holds installed capacity across Ludwigshafen and Antwerp Verbund sites. PU Prepolymers are rotating up the share rankings as systems houses unbundle formulation services.
End User:
Customer concentration patterns split between project-driven construction procurement and contract-based automotive supply.
- Construction:Building renovation wave targets under EU Green Deal trigger rigid foam specification for German and French envelope applications with lifecycle embodied carbon requirements.
- Automotive:German OEM seating divisions consolidate supplier panels to three-to-four approved sources with integrated technical service mandates.
- Coatings:Industrial protective and automotive refinish applications demanding aliphatic isocyanate durability for UV resistance and weathering performance.
- Furniture:Flexible foam cushioning for residential and contract seating where resilience specifications favor TDI-based formulations.
Construction commands volume leadership. Coatings is climbing fastest on industrial aftermarket expansion.
Application:
Application-level margins diverge between specification-locked insulation and commoditized adhesive formulations.
- Insulation:Rigid polyurethane foam delivering thermal conductivity below 0.022 W/m·K for EU Green Deal-compliant building envelopes. Pentane-compatible MDI formulation adoption accelerates under F-Gas Regulation phase-down constraints.
- Adhesives:Reactive hot-melt and solvent-based systems for automotive assembly and construction panel bonding with fast cure requirements.
- Sealants:Elastic joint fillers for building envelopes and transportation applications requiring movement accommodation and weather resistance.
- Rigid Foam:Structural insulation boards and spray-applied systems for commercial and residential building envelopes with fire performance ratings.
Insulation maintains capacity dominance. Sealants is gaining share on building envelope refurbishment cycles.
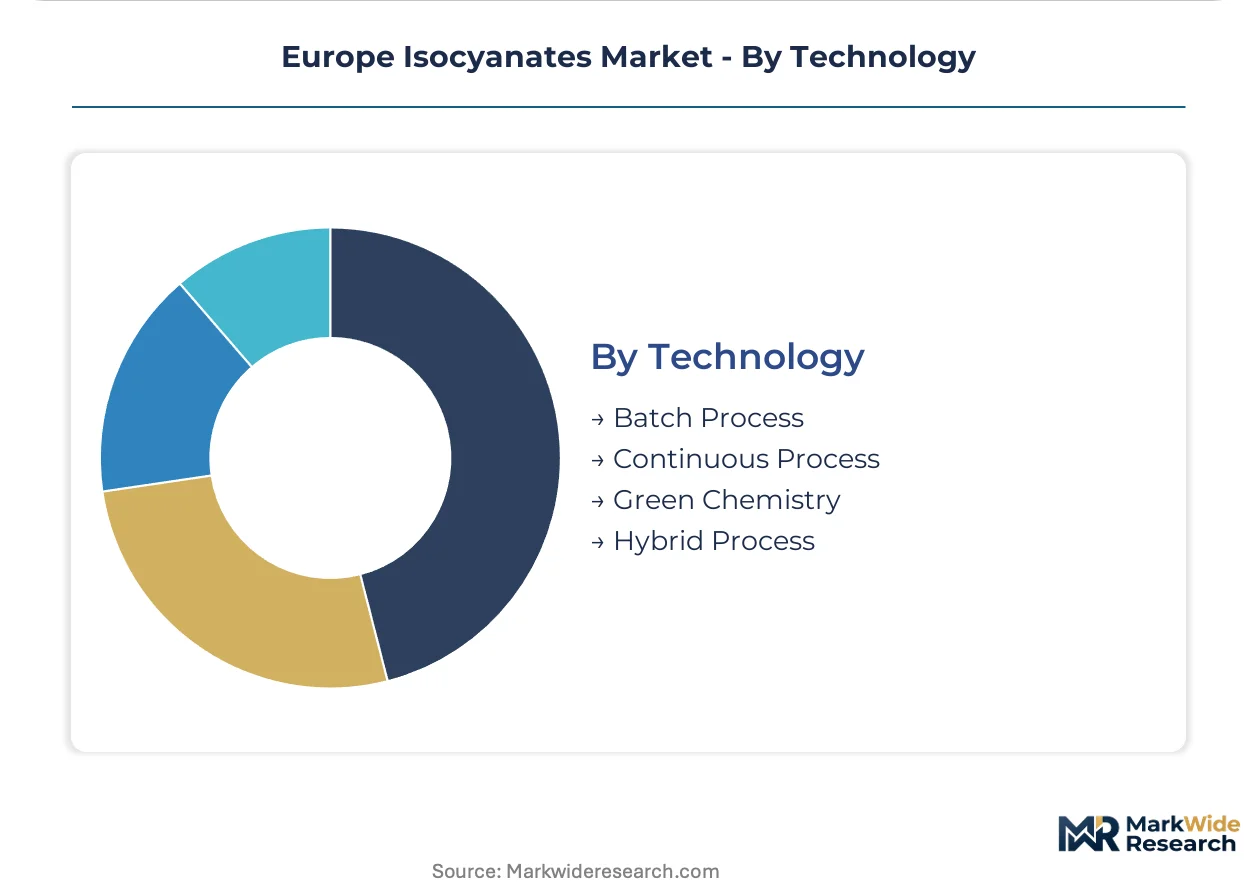
Technology:
Technology selection determines REACH authorization exposure and capital recovery timelines for European producers.
- Batch Process:Discontinuous phosgenation enabling flexible campaign production of specialty isocyanate grades for coating and adhesive applications.
- Continuous Process:Large-scale phosgenation trains at Brunsbüttel and Antwerp delivering commodity MDI and TDI with economies of scale.
- Green Chemistry:Non-phosgene carbonate and carbamate routes attracting pilot investment from diversified chemical groups seeking REACH de-risking and lifecycle carbon reduction.
- Hybrid Process:Combined batch-continuous configurations optimizing asset utilization across product grade transitions.
Continuous Process holds legacy asset base. Green Chemistry is expanding most quickly on authorization timeline compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates with German and Benelux integrated producers while Eastern European compounders absorb margin compression from feedstock volatility and compliance cost escalation.
Germany
Ludwigshafen and Brunsbüttel chemical clusters anchor European MDI capacity with captive chlorine and aniline supply chains. ECHA diisocyanate training mandates elevate processor compliance costs for downstream compounders in North Rhine-Westphalia. BASF SE leverages Verbund integration at Ludwigshafen to sustain cost position against import competition.
Belgium
Antwerp port infrastructure enables deep-sea feedstock access for phosgenation assets serving French and Dutch construction markets. F-Gas Regulation phase-down accelerates pentane-compatible formulation adoption among Benelux insulation processors. Covestro AG anchors MDI network capacity with backward integration into regional aniline supply.
France
Building renovation wave targets under EU Green Deal trigger rigid foam specification for thermal conductivity compliance in Île-de-France construction permits. REACH authorization timelines compress strategic optionality for processors evaluating asset refurbishment against alternative chemistry migration. Greater Paris envelope specialists consolidate supplier panels to amortize compliance infrastructure.
Spain
Automotive seating programs in Catalonia sustain TDI derivative demand for resilience-critical polyurethane elastomer applications. OEM procurement functions consolidate approved sources to three-to-four suppliers with integrated technical service mandates. Barcelona and Valencia chemical processing clusters face feedstock cost pressure from European chlor-alkali curtailments.
Poland
Building stock renovation lags Western Europe by 15-20 years, creating specification upgrade runway for rigid foam systems in Warsaw and Kraków construction markets. EU Green Deal carbon performance standards drive pentane-compatible MDI formulation penetration. Non-integrated compounders face margin compression from REACH compliance cost escalation without Verbund scale advantages.
Europe Isocyanates Market Competitive Landscape
Concentration sits with integrated chemical conglomerates commanding captive phosgene and precursor supply chains. Three producers control 85% of European phosgenation capacity, creating single-source vulnerability for non-integrated systems houses. Strategic archetypes span Verbund-integrated majors, specialized systems houses, and diversified chemical groups funding non-phosgene pilot investments. Competitive moves center on asset modernization commitments and alternative chemistry platform development to de-risk REACH authorization exposure.
Among Verbund-integrated producers, BASF SE and Covestro AG exemplify the scale-driven archetype with captive upstream supply chains, while Huntsman Corporation occupies a position within the specialized systems house tier navigating custom formulation demand without phosgene ownership. Wanhua Chemical Group Co. Ltd. represents the import-competitive vector with Chinese production base and European distribution presence. These three anchors illustrate the tripartite competitive structure: integrated incumbent, formulation specialist, and import-oriented challenger.
| Leading Market Players |
|---|
| Wanhua Chemical Group Co. Ltd. |
| Huntsman Corporation |
| BASF SE |
| Lanxess AG |
| Mitsui Chemicals, Inc. |
| Covestro AG |
| Tosoh Corporation |
| Dow Inc. |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
REACH diisocyanate authorization timelines gate both supplier qualification and price differentiation across European isocyanate procurement. ECHA training mandates and exposure protocols create tiered compliance costs that separate certified systems houses from commodity compounders.
Pricing Analysis
Configured-to-order pricing for custom prepolymer formulations commands 15-25% premiums over standard MDI and TDI spot deliveries. Three-tier pricing structure across premium certified, standard industrial, and economy spot grades tracks ECHA compliance investment and technical service bundling. Cost compression in economy grades intensifies because Chinese import competition and feedstock volatility squeeze non-integrated compounders. Automotive OEM seating divisions show lowest price sensitivity due to specification lock-in, while Eastern European construction distributors absorb highest margin pressure.
Supply Chain Analysis
Germany and Belgium anchor European phosgenation capacity with Ludwigshafen and Antwerp Verbund sites commanding captive chlorine and aniline supply chains. European production draws from benzene derivatives, chlorine via chlor-alkali networks, and imported aniline intermediates. Single-source vulnerability concentrates risk at Brunsbüttel and Antwerp trains where four producers control 85% of regional phosgenation. Distribution runs through systems house technical service networks and construction chemical distributors with formulation support bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a defensive-moat story anchored in regulatory entrenchment. ECHA authorization timelines and phosgenation safety expertise create switching costs that protect incumbent positions.
For Market Incumbents: Secure phosgenation asset life extension commitments before authorization timeline compression closes the refurbishment window. Anchor backward integration into aniline supply at Antwerp and Brunsbüttel to defend margin position against feedstock volatility. Prioritize carbonate chemistry pilot investments to de-risk REACH exposure while recovering sunk costs from legacy trains. For New Entrants and Emerging Players: Anchor in Eastern European construction markets where building stock renovation lags create specification upgrade runway without Verbund scale requirements. Target Polish and Romanian rigid foam processors with pentane-compatible MDI formulations and unbundled technical service contracts. Lead with REACH compliance outsourcing as a go-to-market wedge against cost-burdened local compounders. For Investors and Strategic Acquirers: ECHA diisocyanate restriction phase-in reshapes the acquisition landscape toward systems houses with captive technical service capabilities. Five-to-ten year viability favors targets with formulation IP and automotive OEM seating approvals rather than pure commodity exposure. Watch non-phosgene carbonate route pilot announcements as inflection signals for incumbent asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline | Covestro's Antwerp supply chain anchors MDI margin stability against benzene derivative swings. |
| Green Chemistry Transition | Carbamate route pilots at diversified chemical groups circumvent REACH phosgene authorization exposure. |
| Long-term Supply Agreement | German automotive OEMs consolidate seating compounder panels to three approved sources with technical integration. |
| Capacity Modernization | Brunsbüttel MDI train refurbishment requires 200-300 million euro commitments with uncertain ECHA timelines. |
| Joint Venture | Systems house partnerships with Eastern European distributors amortize REACH compliance infrastructure across volume bases. |
Research Methodology
Cross-validation between plant manager interviews at Ludwigshafen and Antwerp Verbund sites and customs trade data anchors the qualitative findings. Primary fieldwork engaged procurement leads at German automotive OEM seating divisions, technical directors at Benelux insulation processors, and distribution channel partners across France and Poland. Secondary sources encompassed Cefic chemical industry reports, ECHA authorization databases, SEC 10-K filings from listed producers, and EU Green Deal implementation trackers. Bottom-up volume builds from application-level consumption patterns triangulate against top-down capacity assessments across European phosgenation assets.
Sensitivity analysis around ECHA authorization timeline scenarios and feedstock price volatility bands stress-tests the analytical framework. Segmentation dimensions span product grade tier, end-use industry concentration, regional production hub configuration, and technology route phosgene exposure. CAGRs derive from regression against construction permit volumes, automotive production forecasts, and insulation specification adoption curves. Pentane-compatible formulation penetration rates and green chemistry pilot scale-up timelines serve as industry-specific demand drivers.
Material uncertainties — ECHA restriction enforcement timing, chlor-alkali curtailment severity, Chinese import pricing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and feedstock supply stability that revision triggers could invalidate. Recalibration cycles align with material shifts in EU Green Deal implementation pace and non-phosgene technology maturation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Europe Modified Bitumen Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market