
 Global Specialty Oils Market | 2026-2036
Global Specialty Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Oils Market Outlook
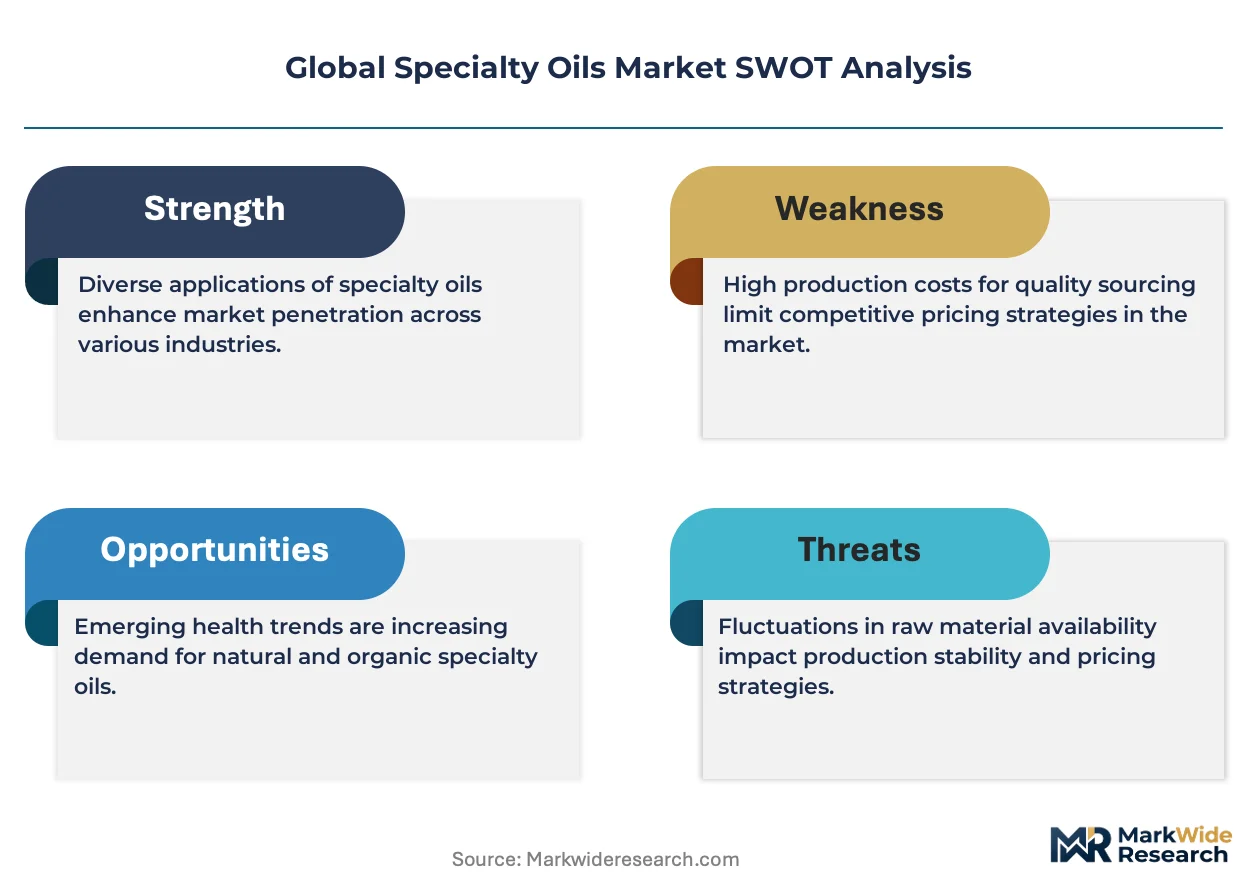
Personal care brands is decoupling from traditional mineral oil dependency as clean-label formulations accelerate. Fuji Oil leverages its oleochemical expertise to supply high-purity esters for premium skincare. AAK AB anchors its position through backward integration into shea and palm fractions across West African and Southeast Asian processing assets. Wilmar International competes on manufacturing scale, operating integrated refineries that convert crude palm and lauric oils into cosmetic and pharmaceutical grades.
Specialty oils are refined or chemically modified lipid fractions distinguished by specific fatty acid profiles, iodine values, and viscosity parameters engineered for targeted functional performance. These oils serve as emollients, lubricants, carriers, or active delivery systems across food, cosmetic, pharmaceutical, and industrial applications. Vegetable oils command the largest volume pool due to their renewable sourcing and broad regulatory acceptance, while essential oils extract premium margins from fragrance and aromatherapy demand. The food industry application segment remains mature with steady reformulation demand, whereas cosmetics and pharmaceuticals represent faster expansion channels as brands seek natural-origin alternatives to petrochemical ingredients.
REACH in Europe mandates full substance registration and hazard communication for cosmetic and industrial oil imports, raising compliance costs for non-EU suppliers. FDA oversight in the United States enforces GRAS and food-contact substance standards that shape product development timelines for edible specialty oils. EFSA evaluations of novel vegetable oil sources further condition market access decisions for European food manufacturers. Stakeholders must monitor evolving bioprospecting regulations and carbon-footprint disclosure rules that will determine sourcing competitiveness in the next planning cycle.
Market Dynamics
Clean-label formulation mandates from personal care brands are forcing oleochemical suppliers to reengineer purity specifications and carbon accounting across their entire supply base, compressing margins for non-compliant processors.
Growth Catalysts
- EU Green Deal compliance deadlines:Cosmetic-grade oil importers into Germany, France, and the Netherlands must now verify deforestation-free sourcing through geolocation data, creating certified supply premiums.
- Shea butter fractionation advances:West African processors deploy enzymatic interesterification to yield stearin-rich fractions for high-melting-point cosmetic applications previously served by petrochemicals.
- Pharmaceutical excipient demand:Lipid-based drug delivery systems for biologics now specify medium-chain triglycerides from sustainable palm kernel sources, pulling volume from food-grade pools.
Market Restraints
- Crude palm oil price volatility:El Niño-driven production shortfalls in Indonesia and Malaysia transmit directly to lauric oil derivative costs, compressing blender margins.
- REACH registration cost escalation:ECHA's updated substance evaluation fees for novel vegetable oil derivatives now exceed €50,000 per registration, excluding smaller exporters.
- Coconut oil supply concentration:Over 70% of global copra crushing capacity sits in the Philippines and Indonesia, creating single-origin risk for MCT producers.
Strategic Opportunities
- Indian ayurvedic export channel:Cold-pressed sesame and neem oils for European wellness brands bypass conventional cosmetic ingredient distributors through direct e-commerce partnerships.
- CSRD-aligned carbon disclosure:EU corporate sustainability reporting requirements create audit-ready traceability premiums for suppliers with farm-level GPS mapping.
- Supercritical CO2 extraction convergence:Combining this solvent-free technology with AI-driven terpene profiling enables custom essential oil blends for precision aromatherapy.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry expertise for fatty acid methyl ester profiling is concentrated among retiring technicians in European refineries.
- Organic certification timeline:Three-year conversion periods for wild-collection shea and jojoba operations delay revenue recognition for African cooperatives.
- Legacy ERP integration:Batch-level traceability systems for FDA-compliant pharmaceutical oils require expensive middleware to connect with decades-old refinery control software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Oils Market |
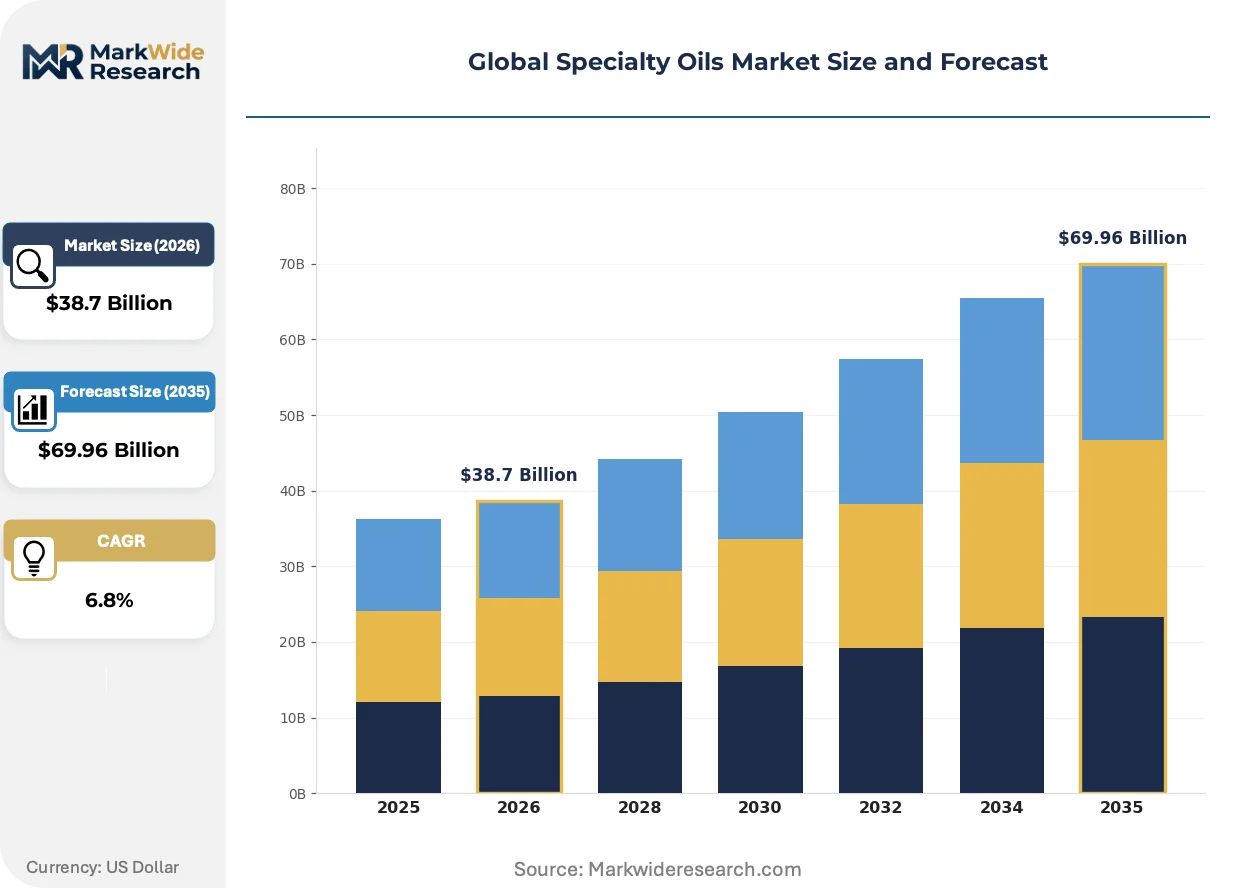
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oils, Essential Oils, Mineral Oils, Fatty Acids Application: Food Industry, Cosmetics, Pharmaceuticals, Industrial Applications End User: Food Manufacturers, Personal Care Brands, Pharmaceutical Companies, Chemical Producers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Fuji Oil, AAK AB, Bunge Limited, Sime Darby Oils, Musim Mas, Cargill, Nisshin OilliO, Archer Daniels Midland, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Oils Market Strategic Shifts
Biotechnology-enabled lipid modification and precision fermentation are collapsing the traditional boundaries between plant-extracted and microbially-synthesized specialty oils, forcing incumbent refiners to reevaluate asset strategies.
Enzymatic glycerolysis is electrifying the production of mono- and diglyceride emulsifiers for clean-label bakery and cosmetic applications. European and North American formulators now specify these enzymatically-produced alternatives at triple the rate of chemical interesterification routes. The technology is electrifying competitive positioning among mid-scale oleochemical houses that invested early in lipase immobilization capacity.
REACH's 2024 updated authorization list now restricts certain phthalate-derived plasticizers, redirecting demand toward epoxidized soybean oil and citrate ester alternatives for food-contact and cosmetic applications. German and Dutch compounders face reformulation deadlines that compress product development cycles. Personal care brands with EU manufacturing footprints are accelerating supplier audits to lock in compliant ester supplies before authorization dates take effect.
Direct farm-to-brand contracting is displacing traditional commodity broker networks for high-identity-preserved oils. Cosmetic multinationals now source shea, moringa, and marula through verified cooperatives in Ghana, Kenya, and Namibia, stripping margin from layered traders. This pattern is most visible in German and French premium skincare lines where blockchain-verified provenance commands shelf price premiums.
Global Specialty Oils Market Segmentation
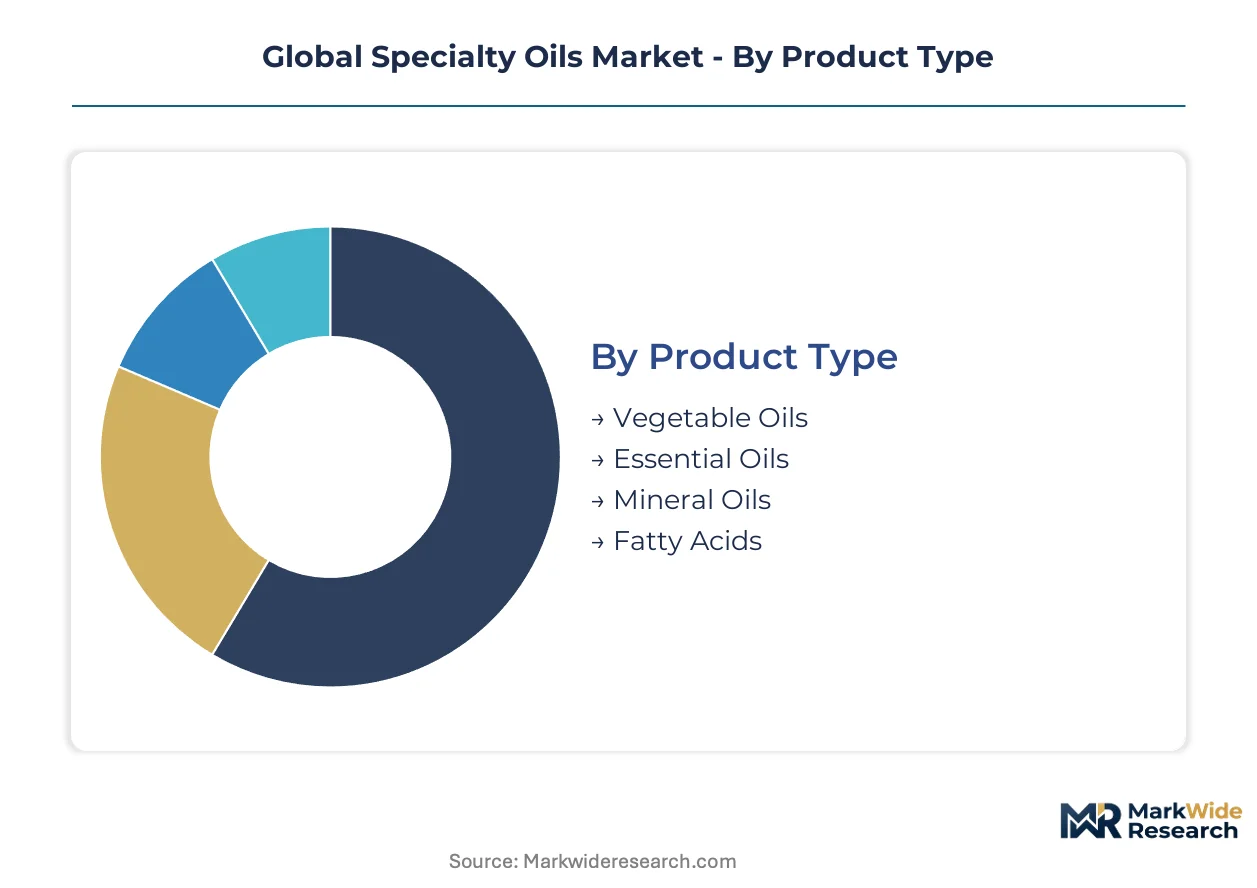
Specialty oils markets fragment sharply across sourcing chemistry and functional specification, with each segment carrying distinct regulatory burdens and margin profiles. Procurement teams must match purity requirements to end-use certification tiers rather than treating oils as interchangeable commodities.
Product Type:
Supply concentration for lipid feedstocks varies dramatically by extraction source, dictating which processors can achieve cost-competitive scale.
- Vegetable Oils:Refined or chemically modified lipid fractions from palm, soybean, sunflower, and shea sources dominate volume pools. Demand concentrates in German and Indonesian cosmetic manufacturing where REACH compliance and deforestation-free verification create certified supply premiums.
- Essential Oils:Steam-distilled or cold-pressed terpene-rich extracts from botanical sources command fragrance and aromatherapy applications. French and German wellness brands now source directly through verified cooperatives in Ghana and Namibia, bypassing traditional commodity brokers.
- Mineral Oils:Petrochemical-derived lubricant and cosmetic bases face displacement as clean-label mandates accelerate.
- Fatty Acids:Fractionated oleic, linoleic, and lauric acid chains serve emulsifier and surfactant production for food and personal care.
Today's leader: Vegetable Oils. Tomorrow's challenger: Essential Oils.
Application:
Cost tier stratification separates mature food-grade volumes from premium cosmetic and pharmaceutical specifications.
- Food Industry:Mature reformulation demand for clean-label bakery and confectionery emulsifiers drives steady volume. Wilmar International and Fuji Oil supply enzymatically-produced mono- and diglycerides at triple the specification rate of chemical routes.
- Cosmetics:Bio-based emollient demand from personal care brands forces reengineering of purity specifications and carbon accounting. German formulators now mandate geolocation-verified deforestation-free sourcing for palm-derived inputs.
- Pharmaceuticals:Lipid-based drug delivery systems for biologics specify medium-chain triglycerides from sustainable palm kernel sources.
- Industrial Applications:REACH authorization restrictions on phthalate-derived plasticizers redirect demand toward epoxidized soybean oil and citrate ester alternatives.
Food Industry holds volume dominance. Cosmetics presents the steepest expansion trajectory.
End User:
Customer type determines specification stringency, with pharmaceutical and personal care buyers imposing traceability requirements that food manufacturers rarely match.
- Food Manufacturers:Volume purchasers of bakery, confectionery, and frying oil specifications prioritize cost stability over identity preservation.
- Personal Care Brands:L'Oréal and Unilever procurement teams now audit farm-level GPS mapping for shea and moringa cooperatives to satisfy CSRD-aligned carbon disclosure requirements.
- Pharmaceutical Companies:FDA-compliant excipient specifications demand batch-level traceability systems that require expensive middleware integration with legacy refinery control software.
- Chemical Producers:Industrial compounders in the Netherlands face compressed reformulation cycles as REACH authorization deadlines approach for restricted plasticizer alternatives.
Personal Care Brands currently drive specification innovation. Pharmaceutical Companies will tighten purity mandates fastest.
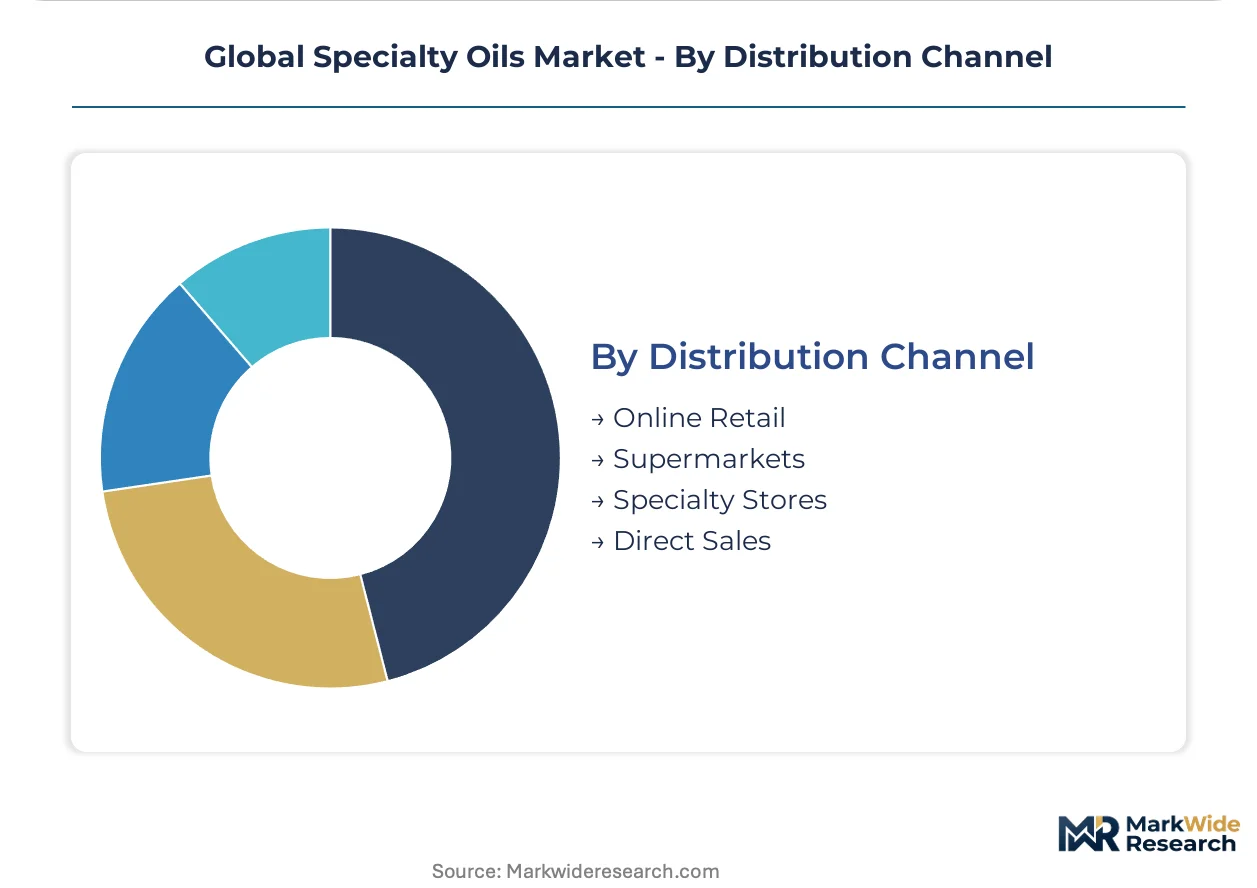
Distribution Channel:
Channel selection reflects identity preservation requirements, with high-specification oils bypassing conventional wholesale networks.
- Online Retail:Cold-pressed sesame and neem oils for European wellness brands bypass conventional cosmetic ingredient distributors through direct e-commerce partnerships with Indian ayurvedic exporters.
- Supermarkets:Mass-market cooking and carrier oils move through conventional grocery wholesale with limited traceability documentation.
- Specialty Stores:Premium aromatherapy and small-batch cosmetic oils target consumer segments willing to pay blockchain-verified provenance premiums.
- Direct Sales:Farm-to-brand contracting displaces layered traders for high-identity-preserved shea, marula, and jojoba fractions.
Direct Sales commands the highest margins. Online Retail is gaining share fastest among emerging wellness brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as compliance cost differentials between jurisdictions widen. Manufacturers now site fractionation assets where REACH-equivalent standards remain unenforced, capturing margin from European customers unwilling to absorb full certification premiums.
Germany
Cosmetic formulators in Hamburg and Düsseldorf drive demand for geolocation-verified shea and palm fractions. ECHA enforcement of updated REACH substance evaluation fees above €50,000 per registration excludes smaller exporters from market access. The Cologne-Ruhr industrial corridor concentrates enzymatic interesterification capacity for high-purity cosmetic emollients.
Indonesia
Integrated palm kernel refineries supply medium-chain triglycerides for pharmaceutical lipid-based drug delivery systems. El Niño-driven production volatility transmits directly to lauric oil derivative costs, compressing blender margins. The Medan-Belawan processing cluster dominates crude palm oil fractionation for export-grade cosmetic and food applications.
United States
FDA GRAS and food-contact substance standards shape development timelines for edible specialty oils. Personal care brands in New Jersey and California audit farm-level GPS mapping to satisfy emerging carbon disclosure requirements. The Chicago-Gary refining corridor anchors North American capacity for hydrogenated vegetable oil fractions.
France
Wellness brands in Grasse and Paris source cold-pressed essential oils through direct cooperatives in West Africa, bypassing layered commodity brokers. ANSM oversight of cosmetic ingredient purity tightens documentation requirements for imports. The Provence-Alps-Côte d'Azur region concentrates supercritical CO2 extraction technology for precision aromatherapy blends.
India
Ayurvedic exporters in Gujarat and Maharashtra bypass conventional cosmetic ingredient distributors through direct e-commerce partnerships with European wellness brands. FSSAI standards for cold-pressed sesame and neem oils create baseline quality tiers. The Mumbai-Pune industrial corridor hosts fractionation capacity serving domestic pharmaceutical excipient demand.
Global Specialty Oils Market Competitive Environment
Capacity expansion dominates the current landscape as processors race to install enzymatic interesterification lines ahead of REACH authorization deadlines. The vendor base stratifies across three tiers: integrated agribusiness conglomerates with captive palm and shea supply, mid-scale oleochemical houses with specialized fractionation expertise, and regional crushers serving identity-preserved niche markets. Backward integration into West African and Southeast Asian sourcing assets represents the primary defensive maneuver. Technology licensing agreements for lipase immobilization capacity constitute secondary competitive vectors.
Within the integrated agribusiness tier, Wilmar International and Bunge Limited exemplify scale-driven positioning through refinery networks that convert crude tropical oils into cosmetic and pharmaceutical grades. Fuji Oil occupies a distinct specialist position, leveraging oleochemical expertise to supply high-purity esters for premium skincare applications. AAK AB anchors the mid-scale tier through controlled sourcing relationships across shea and palm fraction operations.
| Leading Market Players |
|---|
| Fuji Oil |
| AAK AB |
| Bunge Limited |
| Sime Darby Oils |
| Musim Mas |
| Cargill |
| Nisshin OilliO |
| Archer Daniels Midland |
| Wilmar International |
| Others |
Value Chain & Pricing Dynamics
Cosmetic multinationals in Germany and France concentrate procurement power through direct farm-to-brand contracting, shifting pricing leverage from commodity brokers toward identity-preserved supply premiums. This buyer consolidation forces tiered pricing stratification across certification grades rather than volume scales alone.
Pricing Analysis
Distributor margins for conventional commodity oils compress as direct sales channels capture premium tiers. Price differentiation hinges on REACH compliance certification and deforestation-free geolocation verification, with German formulators paying certified supply premiums. Cost compression in standard-grade pools intensifies as El Niño-driven feedstock volatility transmits through lauric oil derivatives. Small-scale African cooperatives exhibit highest price sensitivity due to three-year organic conversion timelines, while pharmaceutical excipient buyers absorb premiums for batch-level traceability.
Supply Chain Analysis
EU Green Deal domestic-content mandates for deforestation-free verification reshape sourcing toward West African and Southeast Asian cooperatives with GPS-mapped assets. Supply concentration centers on Indonesia, Malaysia, and the Philippines for crude palm and coconut feedstocks. Raw material dependencies include crude palm oil, copra, and shea nuts. Single-origin risk from Philippine-Indonesian copra crushing dominance creates vulnerability for medium-chain triglyceride producers. Distribution runs through integrated refinery networks for cosmetic and pharmaceutical grades, with direct e-commerce partnerships bypassing wholesale layers for ayurvedic exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where REACH authorization deadlines and EU Green Deal compliance milestones structurally expand demand for certified supply tiers.
For Market Incumbents: Cement defensible positioning through backward integration into Ghanaian and Namibian shea cooperatives before blockchain-verified provenance becomes table stakes. Prioritize enzymatic interesterification capacity additions in the Cologne-Ruhr corridor to capture reformulation demand from phthalate-restricted cosmetic applications. Incumbent refiners must counter biotechnology-enabled lipid synthesis threats by locking long-term offtake with West African sourcing assets. For New Entrants and Emerging Players: Direct e-commerce partnerships with European wellness brands offer the most penetrable channel for cold-pressed ayurvedic oils bypassing conventional cosmetic ingredient distributors. Target Indian sesame and neem oil exports through FSSAI-certified quality tiers. White-space exists in precision aromatherapy blends combining supercritical CO2 extraction with AI-driven terpene profiling for French and German markets. For Investors and Strategic Acquirers: Integrated agribusiness conglomerates represent the most active acquirer category in this space, consolidating mid-scale oleochemical houses with specialized fractionation expertise. Long-term viability favors targets with captive palm and shea supply anchored in geolocation-verified sourcing. Watch for CSRD-aligned carbon disclosure mandates as the inflection signal accelerating audit-ready traceability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Shea Assets | Captures certified supply premiums as EU Green Deal geolocation mandates tighten. |
| Enzymatic Interesterification Capacity Expansion | Positions refiners to supply clean-label emulsifiers at triple the specification rate. |
| Blockchain-Verified Provenance Systems | Enables German and French cosmetic brands to command shelf price premiums. |
| Direct E-Commerce Channel Development | Bypasses layered commodity brokers for Indian ayurvedic oil exports to Europe. |
| Supercritical CO2 Extraction Technology Licensing | Supports precision aromatherapy blending for Grasse-based wellness formulators. |
Study Parameters
Direct dialogue with refinery operations managers, cosmetic procurement leads at L'Oréal and Unilever, West African cooperative directors, and ECHA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from REACH substance registration databases, EFSA novel food evaluations, EU customs trade flows, and SEC filings from listed agribusiness conglomerates. Bottom-up volume modeling across enzymatic interesterification capacity and top-down market sizing through end-use consumption patterns enabled triangulation.
Bottom-up modeling anchored projections across the analysis window through refinery capacity utilization rates and end-use demand elasticity by certification tier. Segmentation dimensions included vegetable versus essential oil chemistry, food versus cosmetic versus pharmaceutical application, and direct sales versus distributor channel. CAGRs derived from regression analysis against historical price-volume relationships and regulatory implementation timelines. Forecast inputs incorporated El Niño cycle impacts on lauric oil feedstock costs and REACH authorization list expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biotechnology-enabled lipid synthesis disruption and evolving bioprospecting regulations. Projections reflect assumptions around EU Green Deal enforcement consistency and West African cooperative capacity scaling. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
South America Starch Derivatives Market