
 Ankylosing Spondylitis Treatment Market | 2026-2036
Ankylosing Spondylitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ankylosing Spondylitis Treatment Market Intelligence
The proliferation of biosimilar alternatives to established TNF inhibitors is fragmenting the traditional market structure for ankylosing spondylitis therapies. AbbVie Inc. leverages its strong portfolio of originator biologics to maintain market share. Amgen Inc. competes through both its originator products and a growing pipeline of biosimilars. Novartis AG specializes in interleukin inhibitors, targeting specific inflammatory pathways.
Ankylosing spondylitis treatment involves pharmacological interventions to manage a chronic inflammatory disease affecting the axial skeleton. These therapies modulate immune pathways, like the tumor necrosis factor (TNF) pathway, to reduce pain and prevent joint fusion. Within product types, TNF inhibitors form the foundational therapy class, but interleukin inhibitors represent the fastest-growing segment. Subcutaneous injections are the primary delivery mode, valued for self-administration in chronic care settings.
Market access and clinical trial requirements are governed by agencies like the U.S. FDA, the European Medicines Agency (EMA), and China's NMPA. These bodies enforce stringent efficacy and safety standards for new biologics and biosimilars, influencing development timelines. Navigating the divergent regulatory pathways for biosimilar approval remains a critical strategic consideration for market participants.
Market Dynamics
The central structural force shaping the ankylosing spondylitis treatment market is the patent expiry of first-generation TNF inhibitors. This dynamic allows for the entry of biosimilars, which fundamentally alters competitive pricing, market access strategies, and physician prescribing habits.
Growth Catalysts
- Novel Therapeutic Pathways:The development of therapies beyond TNF inhibitors, such as Janus kinase (JAK) inhibitors and interleukin (IL) inhibitors, provides effective alternatives for patients with inadequate response or contraindications to foundational biologics.
- Improved Diagnostics:Advances in imaging and genetic marker identification are enabling earlier and more accurate diagnosis of axial spondyloarthritis, expanding the treatable patient population before significant structural damage occurs.
- Expanding Reimbursement:Growing healthcare expenditure and the inclusion of advanced biologics in national formularies and reimbursement lists in countries like China and Brazil are improving patient access to treatment.
Market Restraints
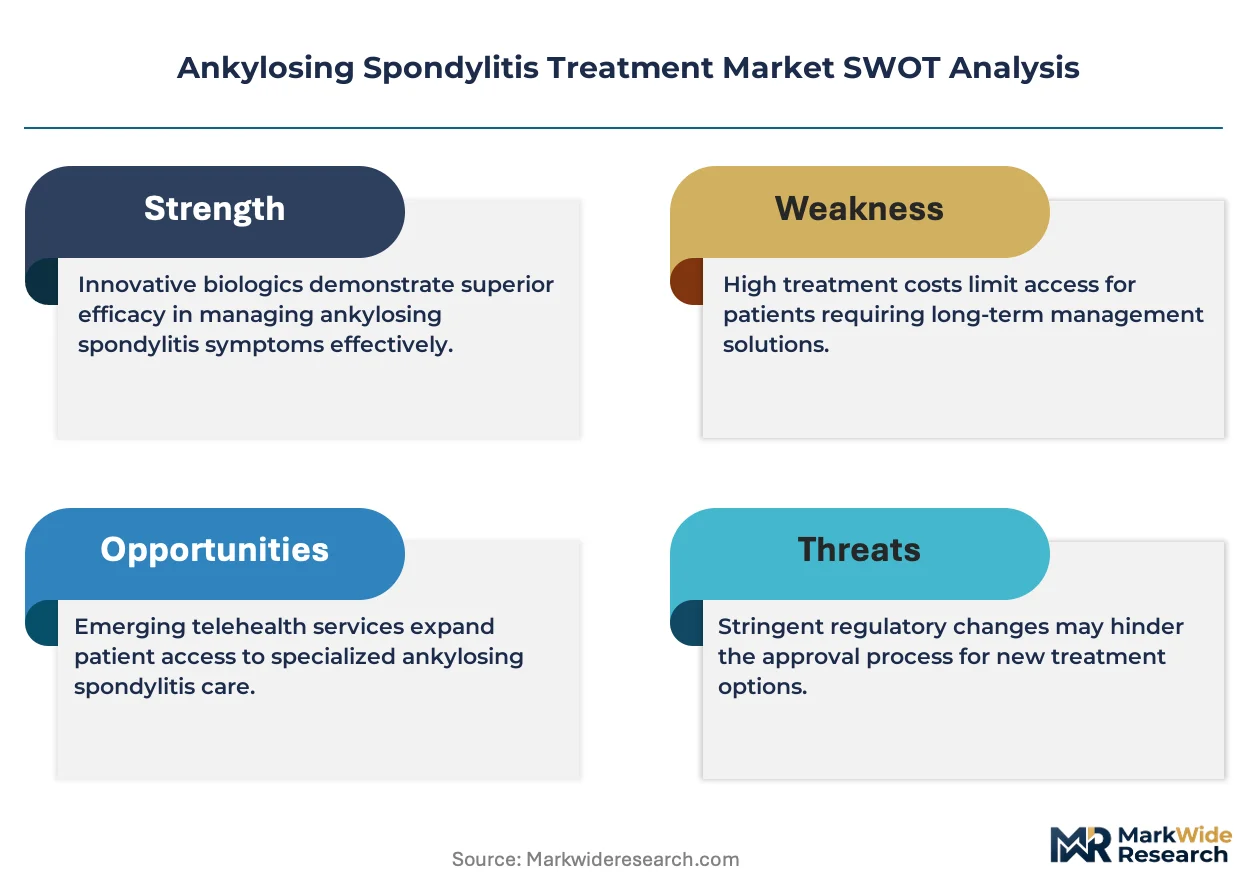
- High Treatment Costs:The substantial price of biologic and targeted synthetic disease-modifying antirheumatic drugs places a significant economic burden on healthcare systems and patients, limiting access in markets without comprehensive reimbursement.
- Divergent Regulatory Hurdles:Navigating disparate requirements for biosimilar interchangeability and efficacy data between the U.S. FDA and the European Medicines Agency (EMA) creates complexity and delays market entry.
- Long-Term Safety Concerns:The chronic immunosuppression associated with long-term biologic use poses risks of infections and other adverse events, necessitating continuous patient monitoring and limiting use in some patient profiles.
Strategic Opportunities
- Oral Formulations:Developing and marketing effective oral therapies, such as JAK inhibitors, presents a significant opportunity to capture patient share from the injectable-dominated market by offering greater convenience and reducing administration burdens.
- Non-Radiographic Disease Focus:Targeting the non-radiographic axial spondyloarthritis (nr-axSpA) patient population represents a major market expansion opportunity, as therapies are approved for this earlier disease stage.
- Geographic Expansion:Untapped patient populations in regions like the Middle East and Southeast Asia, where disease awareness and diagnostic infrastructure are improving, offer new growth frontiers for established therapies.
Industry Challenges
- Clinical Trial Complexity:Executing global placebo-controlled trials for a chronic, slowly progressing disease requires long timelines, large patient cohorts, and sophisticated endpoint measurements, increasing development costs and risks for new entrants.
- Payer and Formulary Management:Securing and maintaining favorable formulary placement against lower-cost biosimilars and other branded competitors demands extensive real-world evidence generation and health-economic outcome data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ankylosing Spondylitis Treatment Market |
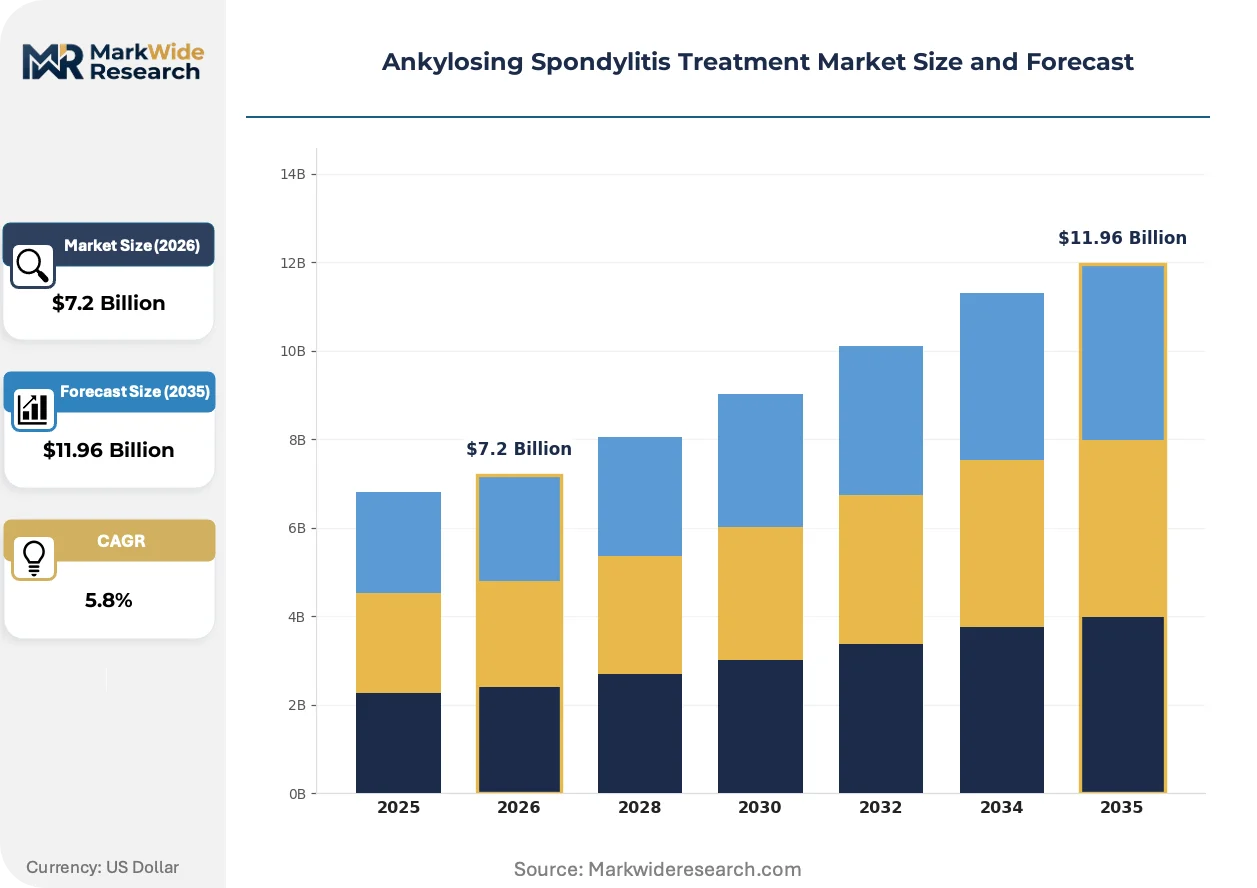
| Market Size in 2026 | $7.2 Billion |
| Market Size in 2035 | $11.96 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TNF Inhibitors, Interleukin Inhibitors, NSAIDs, Corticosteroids, Disease-Modifying Antirheumatic Drugs Therapy Area: Axial Spondyloarthritis, Peripheral Arthritis, Enthesitis, Uveitis, Psoriasis-Associated Disorders End User: Specialty Clinics, Rheumatology Centers, Ambulatory Surgical Centers, Home Care Services, Diagnostic Laboratories Delivery Mode: Subcutaneous Injection, Intravenous Infusion, Oral Administration, Topical Application, Implantable Devices |
| Companies Covered | Amgen Inc., Janssen Pharmaceuticals Inc., AbbVie Inc., Merck & Co. Inc., Eli Lilly and Company, Novartis AG, UCB Inc., Boehringer Ingelheim, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ankylosing Spondylitis Treatment Market Strategic Shifts & Innovations
The evolution of ankylosing spondylitis therapy is defined by a push towards more precise immunomodulation and patient-friendly administration. This movement favors targeted mechanisms over broad immunosuppression and creates new standards for efficacy and long-term management.
Janus kinase (JAK) inhibitors are oral small molecules that modulate specific intracellular signaling pathways involved in inflammation. Rheumatology specialty clinics are increasingly prescribing these therapies for patients who have failed or are intolerant to biologic treatments. The availability of a potent oral option is collapsing the market's historical dependence on subcutaneous or intravenous injections for moderate-to-severe disease management.
Regulatory frameworks established by bodies like the U.S. FDA and the European Medicines Agency (EMA) are accelerating biosimilar entry. These abbreviated approval pathways, such as the FDA's 351(k) process, lower development costs and timelines compared to originator biologics. The TNF inhibitor class is the most impacted segment, forcing a strategic response from originator drug manufacturers as competition intensifies across North America and Europe.
A notable shift in demand involves payers and health technology assessment bodies requiring robust real-world evidence to justify treatment costs. This change moves the focus from simple drug acquisition price to a holistic assessment of a therapy's value in preventing disease progression and reducing long-term healthcare utilization. This value-based procurement model is particularly evident in single-payer healthcare systems in Canada and the United Kingdom.
Ankylosing Spondylitis Treatment Market Segmentation
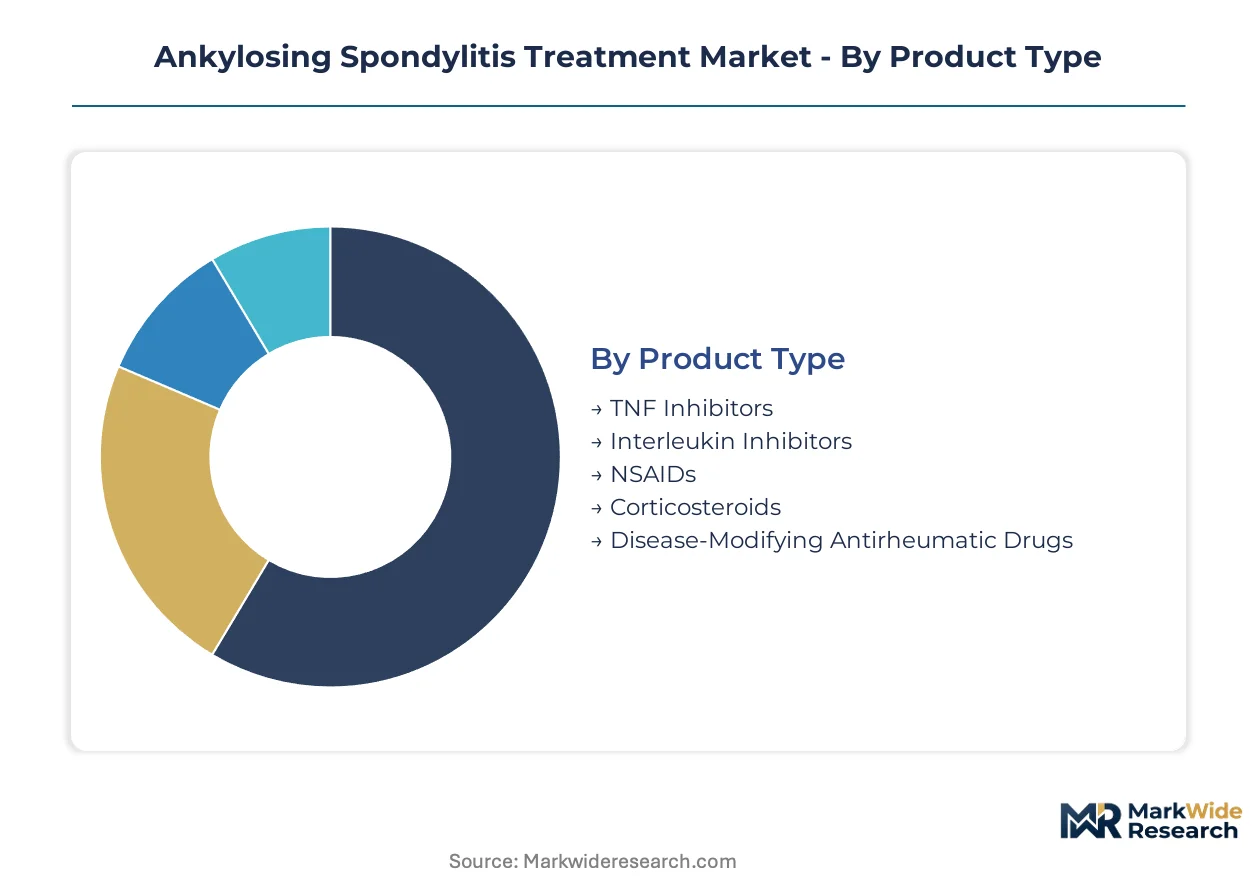
The Ankylosing Spondylitis Treatment Market is categorized across product types, therapy areas, end users, and delivery modes. This segmentation clarifies the diverse treatment landscape and highlights where innovation and patient care are most concentrated within the chronic inflammatory disease management.
Product Type:
The after-sales service intensity for Ankylosing Spondylitis treatments varies significantly by product type, reflecting differing administration complexities and patient support requirements.
- TNF Inhibitors:These foundational biologics target tumor necrosis factor-alpha, a key inflammatory cytokine, to reduce pain and inflammation. Demand remains high in the United States and Europe, despite biosimilar competition, due to their established efficacy and long-term safety profiles.
- Interleukin Inhibitors:These targeted biologics block specific interleukin pathways, such as IL-17 or IL-23, offering alternative mechanisms for patients unresponsive to TNF inhibitors. Their adoption is rapidly expanding in countries like Germany and Canada, driven by strong clinical outcomes in specialized rheumatology centers.
- NSAIDs:Non-steroidal anti-inflammatory drugs provide symptomatic relief by reducing pain and stiffness, serving as a first-line therapy for many patients. These oral medications are widely prescribed globally for their accessibility and cost-effectiveness.
- Corticosteroids:These potent anti-inflammatory agents are used for short-term management of acute flares, primarily delivered orally or via local injection. Their use is carefully managed due to potential long-term side effects.
- Disease-Modifying Antirheumatic Drugs:This category includes conventional synthetic DMARDs that modulate the immune system to slow disease progression, often used in combination with biologics. Methotrexate and sulfasalazine are common examples.
By volume, NSAIDs lead the market. By growth pace, Interleukin Inhibitors are ahead.
Therapy Area:
Application diversity within the Ankylosing Spondylitis Treatment Market allows for tailored therapeutic strategies across specific disease manifestations and patient profiles.
- Axial Spondyloarthritis:This primary therapeutic application targets inflammation affecting the spine and sacroiliac joints, which is the hallmark of ankylosing spondylitis. Treatment focuses on preserving spinal mobility and reducing structural damage in patients across all major economies.
- Psoriasis-Associated Disorders:Therapies for ankylosing spondylitis often overlap with treatments for psoriasis and psoriatic arthritis, addressing skin and joint inflammation simultaneously. This co-morbidity drives significant therapeutic innovation for dual-acting agents.
- Peripheral Arthritis:This application focuses on inflammation in the peripheral joints, such as hips and shoulders, which can occur in conjunction with axial involvement. Treatment aims to reduce pain and swelling in these specific joint areas.
- Enthesitis:This therapy area addresses inflammation where tendons and ligaments attach to bone, a common and painful symptom in ankylosing spondylitis patients. Localized treatments or systemic biologics are employed.
- Uveitis:This application targets ocular inflammation, a common extra-articular manifestation of ankylosing spondylitis, requiring specialized treatment alongside systemic disease management. Ophthalmologists collaborate with rheumatologists for patient care.
Axial Spondyloarthritis forms the core therapeutic application, while Psoriasis-Associated Disorders represent a significant co-morbidity challenge.
End User:
Patient type and care setting heavily influence the end-user landscape for Ankylosing Spondylitis treatments, dictating infrastructure and service demands.
- Specialty Clinics:These facilities manage complex cases requiring advanced diagnostic tools and specialized therapeutic interventions, including biologic administration and monitoring. Their role is critical in countries with developed healthcare systems like Japan and the United Kingdom.
- Rheumatology Centers:These dedicated centers provide comprehensive care for rheumatic diseases, offering a full spectrum of diagnostic, treatment, and patient education services. They serve as primary hubs for long-term management of ankylosing spondylitis.
- Ambulatory Surgical Centers:These centers primarily handle outpatient procedures, though their role in ankylosing spondylitis treatment is limited to specific diagnostic interventions or minor orthopedic procedures. They offer a cost-effective alternative to hospital settings for certain services.
- Home Care Services:These services support patients with self-administered therapies, particularly subcutaneous injections, ensuring adherence and convenience. Growth in home care is notable in the United States and Canada, driven by patient preference.
- Diagnostic Laboratories:These facilities perform essential blood tests and genetic markers for diagnosis and monitoring of disease activity and treatment response. They underpin clinical decision-making across all treatment pathways.
Specialty Clinics provide advanced care for complex cases, while Rheumatology Centers offer comprehensive disease management.
Delivery Mode:
Margin structures for Ankylosing Spondylitis treatments are significantly impacted by the delivery mode, reflecting differences in manufacturing, administration, and patient convenience.
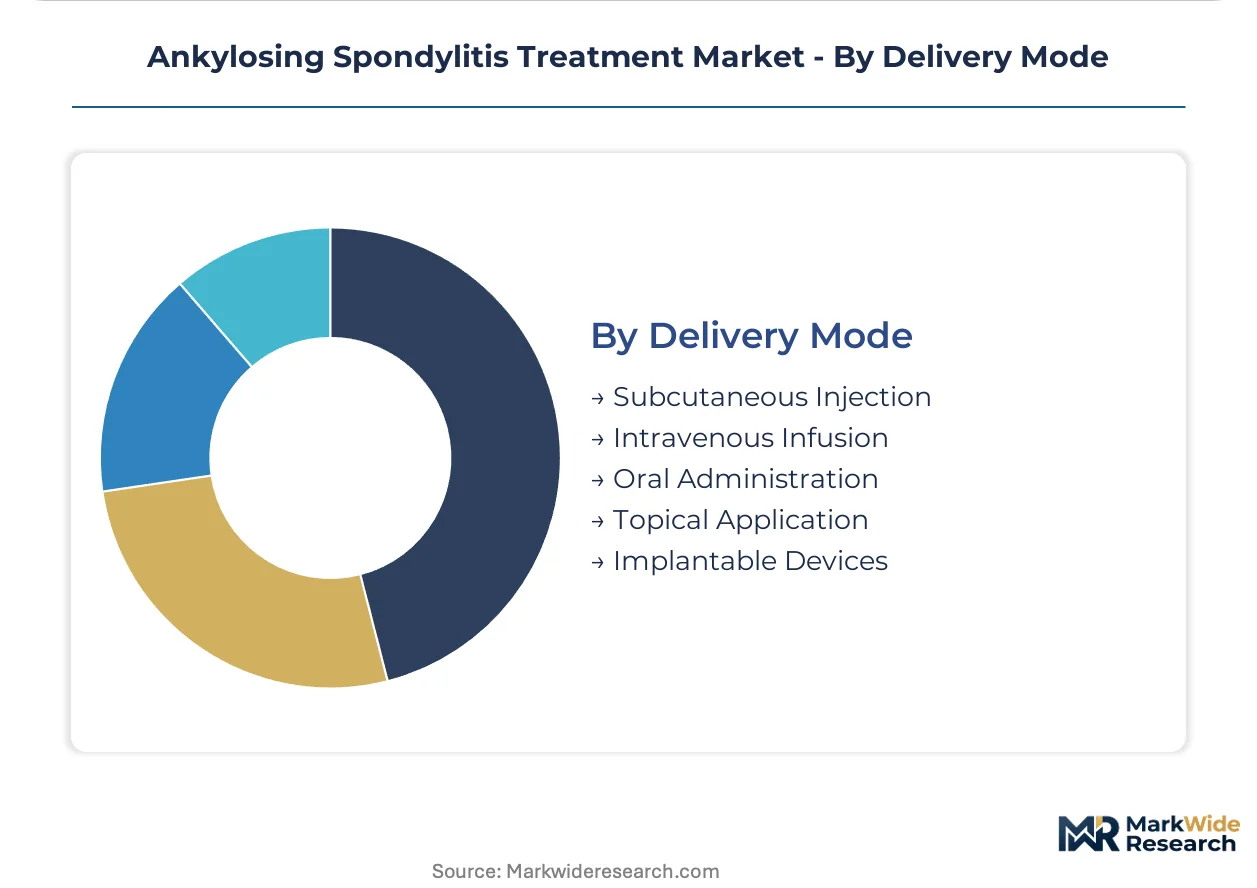
- Subcutaneous Injection:This delivery method involves self-administration of biologics under the skin, offering convenience for chronic care and reducing healthcare facility visits. It dominates the market due to ease of use in patient homes, particularly across North America.
- Oral Administration:Oral therapies, such as JAK inhibitors, offer significant patient convenience by eliminating the need for injections, potentially improving adherence. This mode is gaining substantial traction as new oral small molecules enter the market.
- Intravenous Infusion:This mode requires administration in a clinical setting, typically a hospital or infusion center, for biologics requiring slower, controlled delivery. It ensures direct systemic drug delivery under medical supervision.
- Topical Application:Topical treatments, such as NSAID gels, are used for localized pain relief in peripheral joints or enthesitis, offering targeted symptomatic management. They provide localized relief without systemic exposure.
- Implantable Devices:This nascent category explores long-acting drug delivery systems or pain management devices, though their application in ankylosing spondylitis remains largely experimental. Research in this area focuses on sustained therapeutic effect.
Subcutaneous Injection remains the primary delivery mode for biologics, while Oral Administration represents a significant growth opportunity for patient convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The highest concentration of ankylosing spondylitis treatment buyers emerges in developed economies, driven by advanced diagnostic capabilities and comprehensive patient access programs. These regions often feature robust healthcare infrastructure that supports specialized rheumatology care and the adoption of advanced biologic therapies.
United States
Demand for ankylosing spondylitis treatments in the United States remains high, fueled by a large patient population and the rapid uptake of novel therapies. The U.S. FDA governs the approval of new biologics and biosimilars, influencing development timelines. Major pharmaceutical clusters around Boston and San Francisco continue to drive innovation in targeted therapies.
Germany
Germany exhibits strong demand for interleukin inhibitors, with their adoption rapidly expanding due to favorable clinical outcomes in specialized rheumatology centers. The European Medicines Agency (EMA) sets stringent efficacy and safety standards for new treatments across the European Union. Berlin and Munich are significant hubs for pharmaceutical research and clinical trials.
Japan
Specialty clinics in Japan play a critical role in managing complex ankylosing spondylitis cases, supported by a developed healthcare system. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates drug approvals and market access for innovative therapies. Tokyo and Osaka host numerous pharmaceutical companies and advanced medical research facilities.
Canada
Canada demonstrates expanding adoption of interleukin inhibitors, with value-based procurement models influencing treatment selection. Health Canada oversees the approval and post-market surveillance of ankylosing spondylitis medications. Toronto and Montreal serve as key centers for clinical research and healthcare delivery.
China
Expanding reimbursement policies and improving diagnostic infrastructure are catalyzing demand for ankylosing spondylitis treatments in China. China's NMPA enforces strict efficacy and safety standards for new biologics and biosimilars. Shanghai and Beijing are critical locations for pharmaceutical manufacturing and clinical development activities.
Ankylosing Spondylitis Treatment Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic market for ankylosing spondylitis treatments. The market structure exhibits fragmentation with the entry of biosimilar alternatives to established therapies. Strategic archetypes include originator biologic developers, biosimilar manufacturers, and companies specializing in novel targeted therapies. Dominant competitive moves involve portfolio diversification and geographic expansion into emerging markets.
Within the originator biologic tier, AbbVie Inc. leverages its strong portfolio of established treatments to maintain market share. Amgen Inc. occupies a position across both originator products and a growing pipeline of biosimilars, reflecting a dual-strategy approach. Novartis AG exemplifies a specialized approach, focusing on interleukin inhibitors that target specific inflammatory pathways for ankylosing spondylitis treatment.
| Leading Market Players |
|---|
| Amgen Inc. |
| Janssen Pharmaceuticals Inc. |
| AbbVie Inc. |
| Merck & Co. Inc. |
| Eli Lilly and Company |
| Novartis AG |
| UCB Inc. |
| Boehringer Ingelheim |
| Pfizer Inc. |
| Others |
Cost & Logistics Intelligence
Biologic manufacturing capacity in Europe, particularly for TNF inhibitors, drives supplier behavior and pricing posture. This capacity utilization influences market entry strategies and cost structures for biosimilar manufacturers.
Pricing Analysis
Value-based procurement models with national formulary indexation are becoming prevalent for ankylosing spondylitis treatments. Price differentiation stems from originator biologic brand premiums and the specific regulatory approvals (e.g., U.S. FDA, EMA) obtained. Pricing pressure stems from the proliferation of lower-cost biosimilar alternatives, especially for TNF inhibitors. Payers and health technology assessment bodies are highly price-sensitive, while specialty clinics prioritize efficacy for complex cases.
Supply Chain Analysis
Export control regimes for advanced biologic manufacturing technologies limit flows, impacting global supply chain resilience. Supply concentration for biologics is significant in the United States, Germany, and Switzerland, drawing from specialized active pharmaceutical ingredients and cell culture media. Regulatory restrictions on cross-border movement of sensitive materials pose a structural risk. Distribution runs through a network of specialty pharmacies and hospital systems, particularly for infused therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ankylosing spondylitis treatment market is characterized by a critical substitution defense imperative. Incumbent biologic developers must navigate the persistent threat of biosimilar alternatives to established TNF inhibitors.
For Market Incumbents: Pre-empt biosimilar erosion by aggressively diversifying portfolios into novel therapeutic pathways like JAK and IL inhibitors. Reinforce market position through enhanced patient support programs and robust real-world evidence generation. Strategic partnerships with specialty clinics can further defend market share against generic competition.
For New Entrants and Emerging Players: Establish a beachhead in the non-radiographic axial spondyloarthritis (nr-axSpA) patient population, representing a significant untapped segment. Target geographic expansion into regions like the Middle East and Southeast Asia, where diagnostic infrastructure is improving. Offer novel oral formulations, such as JAK inhibitors, as a differentiated go-to-market strategy.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across novel oral therapy development, favoring agile R&D models over large-scale biologic manufacturing. The long-term viability of ankylosing spondylitis treatment hinges on precision medicine and chronic disease management. Acquire specialized biotech firms with strong pipelines in JAK or IL inhibitors or advanced diagnostic developers. Clinical trial success for next-generation oral therapies serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for Oral JAK Inhibitors | Successful trials expand treatment options for patients intolerant to biologics. |
| Accelerate Biosimilar Regulatory Approvals | Abbreviated pathways (e.g., FDA 351(k)) lower development costs for new market entrants. |
| Expand Patient Access Programs | Programs in the United States and Canada improve treatment adherence for chronic conditions. |
| Diversify Biologic Pipeline with IL Inhibitors | Interleukin inhibitors offer alternative mechanisms for patients unresponsive to TNF therapies. |
| Invest in Real-World Evidence Generation | Robust data justifies treatment costs for payers and health technology assessment bodies. |
Research Approach
Operator-level perspectives from rheumatologists, hospital formulary managers, pharmaceutical R&D executives, and patient advocacy groups anchored the qualitative base. Primary interviews were triangulated with secondary validation from U.S. FDA filings, EMA submissions, and ClinicalTrials.gov. This approach ensured a robust bottom-up and top-down data triangulation for market sizing.
Scenario-bracketing informed the quantitative analytical framework across the analysis window, integrating multiple potential market trajectories. Segmentation dimensions modeled included product types (TNF inhibitors, IL inhibitors), therapy areas (axial spondyloarthritis), end users, and delivery modes (subcutaneous, oral). Compound annual growth rates were derived from historical trends and projected market dynamics, with forecast inputs including patent expiry schedules for biologics and clinical trial success rates.
Macroeconomic conditions sit as an overlay; deviation in global healthcare expenditure or regulatory policies would shift the trajectory. Forecasts reflect assumptions regarding clinical trial outcomes and market access strategies. Material shifts in reimbursement policies or unexpected safety concerns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Glucagon Therapy Market