
 China Ulcerative Colitis Market | 2026-2036
China Ulcerative Colitis Market Size, Share, and Industry Trends Forecast 2026-2036
China Ulcerative Colitis Market Insights
Domestic biopharma manufacturing clusters in Jiangsu and Zhejiang provinces are pivoting toward monoclonal antibody production to serve the inflammatory bowel disease pipeline. AbbVie Inc. leverages its established immunology infrastructure to sustain prescriber loyalty in Chinese tertiary hospitals. Johnson & Johnson anchors its position through deep channel partnerships with provincial procurement platforms. HUTCHMED competes on localized clinical development and adaptive trial design for novel mechanisms.
Ulcerative colitis denotes a chronic relapsing inflammatory condition of the colonic mucosa characterized by continuous superficial ulceration, crypt abscess formation, and variable disease extent from proctitis to pancolitis; its primary clinical purpose centers on achieving mucosal healing and preventing colectomy through sustained immunosuppression. Biologics command the fastest expansion within product type categories as anti-TNF and integrin inhibitor classes penetrate earlier lines of therapy. Injectable delivery modes concentrate margin pools due to cold-chain requirements and infusion center economics, while oral 5-aminosalicylic acid formulations occupy the high-volume maintenance segment where generic competition intensifies.
NMPA's Center for Drug Evaluation maintains accelerated pathways for innovative biologics while GB standards govern manufacturing quality for domestically produced biosimilars. The National Healthcare Security Administration shapes demand through centralized procurement and reimbursement list updates that determine patient out-of-pocket exposure for advanced therapies. Stakeholders must monitor how provincial unified bidding platforms rebalance originator versus biosimilar access as manufacturing capacity localizes and cost containment pressures intensify.
Market Dynamics
NMPA's accelerated biosimilar approval pathways under updated drug evaluation frameworks are compressing originator exclusivity windows and forcing incumbent biologic manufacturers to defend prescriber relationships through deeper hospital partnerships and real-world evidence generation.
Growth Catalysts
- Centralized procurement expansion:The National Healthcare Security Administration's reimbursement list updates are extending advanced therapy access to provincial tier-two hospitals previously restricted to originator biologics.
- Specialist center concentration:Beijing and Shanghai tertiary hospitals are consolidating IBD patient volume through dedicated inflammatory bowel disease centers that standardize biologic initiation protocols.
- Cold-chain infrastructure maturation:Jiangsu and Zhejiang biopharma clusters are building captive injectable fill-finish capacity that reduces import dependency for monoclonal antibody therapies.
Market Restraints
- Reimbursement lag structure:Provincial unified bidding platforms impose 12-18 month delays between NMPA approval and formulary inclusion, constraining patient out-of-pocket affordability for novel mechanisms.
- Manufacturing quality variance:GB standards enforcement gaps between domestic biosimilar producers create batch inconsistency risks that slow prescriber confidence building in non-originator alternatives.
- Specialist workforce scarcity:Gastroenterology fellowship programs produce insufficient IBD-focused clinicians to match patient volume growth in tier-one city referral centers.
Strategic Opportunities
- Guangdong-Sichuan corridor penetration:Underpenetrated southwestern provinces present whitespace for biosimilar entrants to establish hospital formulary position ahead of originator channel deepening.
- Oral small molecule convergence:JAK inhibitor and S1P modulator development pipelines are creating non-injectable alternatives that bypass cold-chain infrastructure requirements entirely.
- Real-world evidence mandates:NMPA Center for Drug Evaluation guidance on post-marketing studies rewards sponsors who generate China-specific efficacy data with accelerated label expansion pathways.
Industry Challenges
- Adaptive trial design expertise scarcity:Domestic CROs lack sufficient experience executing basket and umbrella protocols for IBD subpopulation stratification, forcing sponsors toward multinational contract research partnerships.
- Infusion center capex intensity:Hospital-based biologic administration requires dedicated pharmacy compounding suites and adverse event monitoring infrastructure that strains capital budgets in tier-two facilities.
- Originator data exclusivity navigation:Biosimilar developers face complex freedom-to-operate analyses around formulation patents and manufacturing process trade secrets that delay program initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Ulcerative Colitis Market |
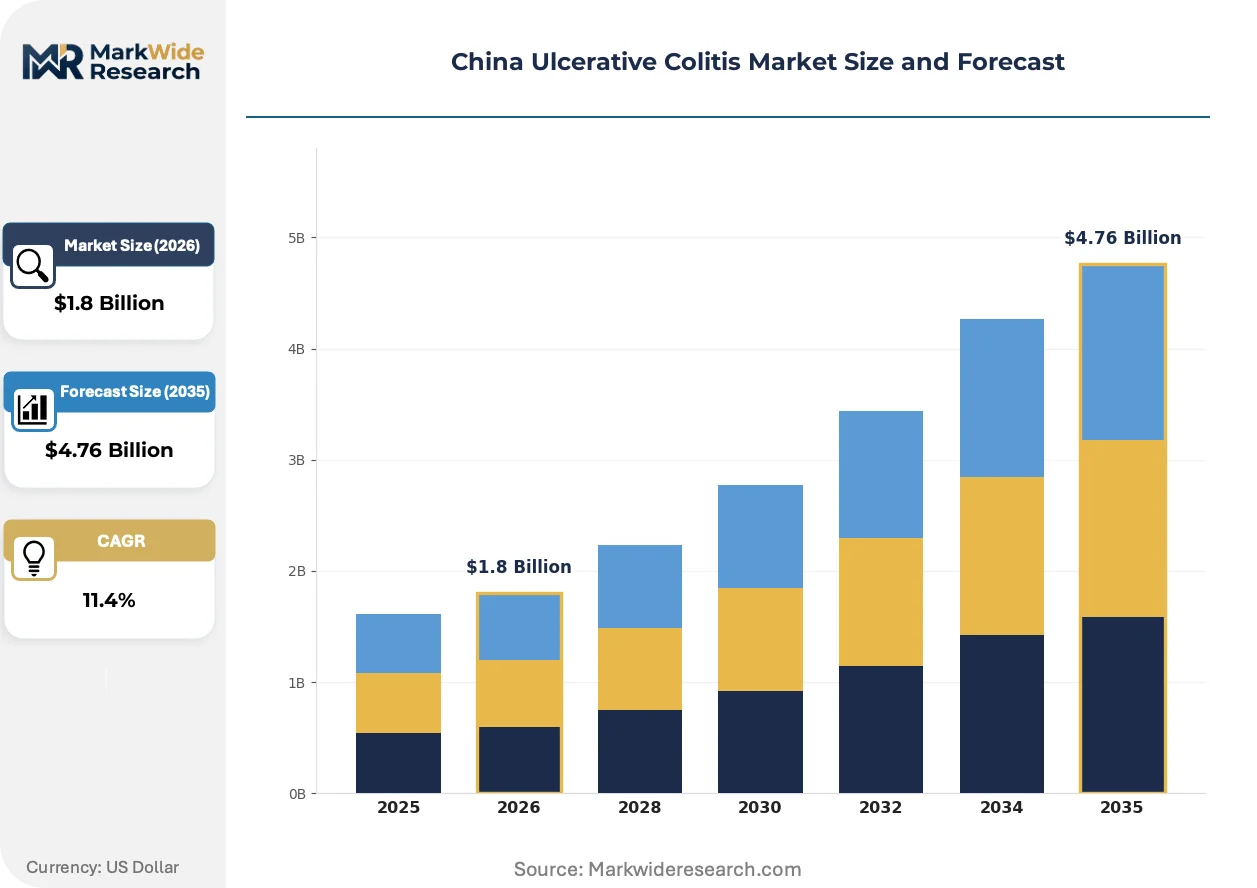
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 5-Aminosalicylic Acid, Corticosteroids, Biologics, Immunomodulators Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Homecare Therapy Area: Inflammatory Bowel Disease, Gastroenterology, Autoimmune Disorders, Digestive Health |
| Companies Covered | AbbVie Inc., Johnson & Johnson, Merck & Co., Inc., Novartis AG, Takeda Pharmaceutical Company Limited, Bausch Health Companies Inc., HUTCHMED, EA Pharma Co., Ltd., Theravance Biopharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Ulcerative Colitis Market Trends and Innovations
Biologic therapy paradigms in Chinese ulcerative colitis care are pivoting toward earlier-line intervention and mechanism diversification, with prescriber education and real-world evidence generation becoming primary competitive battlegrounds alongside traditional clinical trial outcomes.
Anti-integrin and IL-23 pathway inhibitors are rewriting therapeutic sequencing algorithms in Beijing and Shanghai tertiary hospitals, where gastroenterology departments now initiate biologics before immunomodulator failure in moderate-to-severe cases. Specialist centers are adopting these mechanisms at pace, compressing anti-TNF dominance from 70% to under 50% of biologic initiations within three years. This mechanism diversification is rewriting margin pools across the supply chain as cold-chain logistics providers and infusion center operators retool for monoclonal antibody classes with distinct dosing intervals and monitoring requirements.
NMPA's Center for Drug Evaluation maintains accelerated pathways for innovative biologics while tightening GB standards enforcement on domestic biosimilar manufacturing quality. The regulatory divergence creates a two-speed approval environment where novel mechanisms receive priority review timelines while biosimilars face extended pharmacovigilance requirements. Jiangsu and Zhejiang manufacturing clusters are responding by segregating production lines between originator-contract and biosimilar-dedicated facilities to prevent cross-contamination audit failures.
Hospital procurement committees are consolidating vendor relationships around integrated supply contracts that bundle drug, infusion administration, and patient monitoring services into single-source agreements. Traditional pharmaceutical distribution channels face displacement by hospital-owned pharmacy entities that capture margin through captive dispensing. This vertical integration is most visible in Shanghai, where Renji Hospital and Ruijin Hospital have established wholly-owned specialty pharmacies that control biologic patient flow from prescription through administration.
China Ulcerative Colitis Market Segmentation
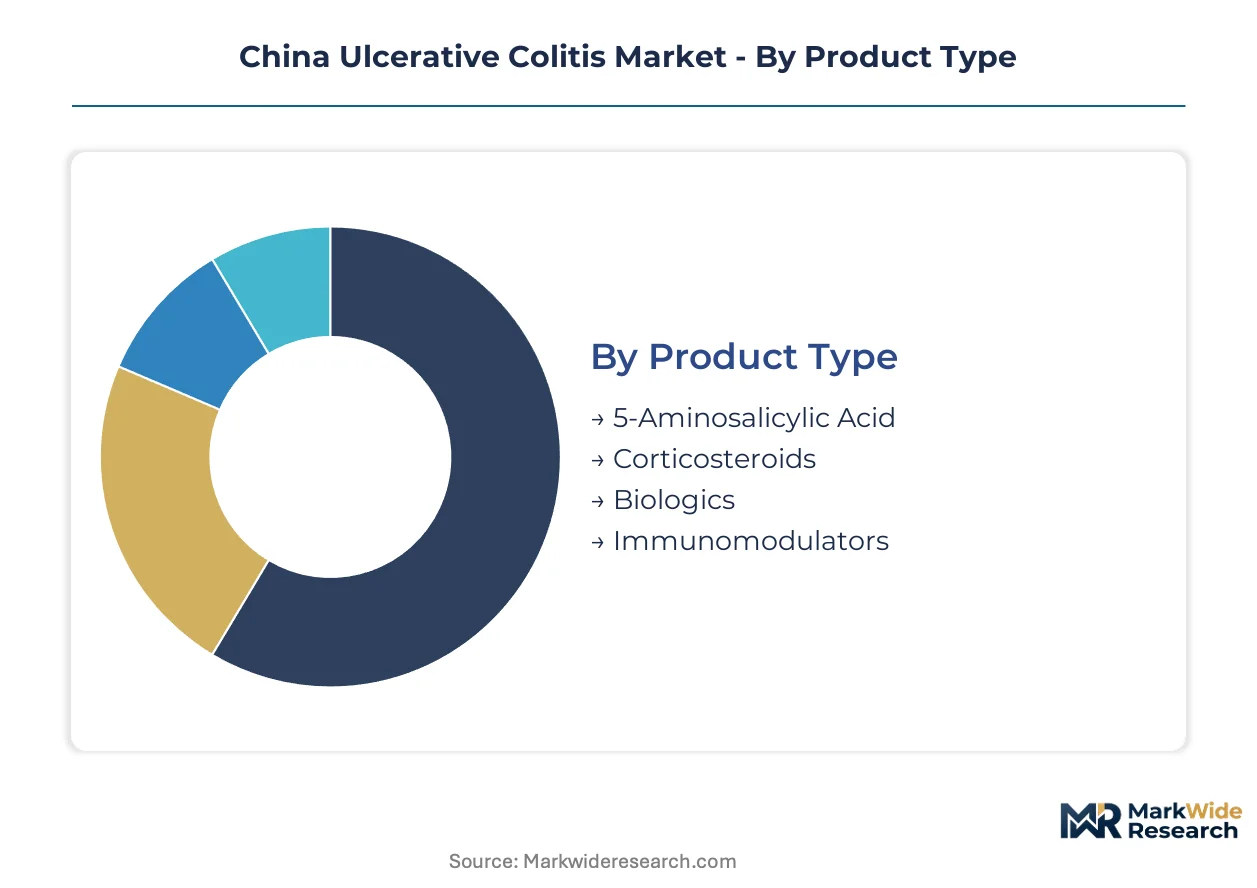
Therapeutic modality selection in Chinese ulcerative colitis care hinges on disease severity staging and prescriber familiarity with mechanism classes. Segmentation reveals how reimbursement tiering and hospital infrastructure shape patient access across product categories.
Product Type:
Standalone pharmaceutical agents dominate maintenance therapy while combination biologic-immunomodulator protocols embed within hospital-based protocols.
- 5-Aminosalicylic Acid:First-line maintenance therapy formulated as delayed-release or extended-release mesalamine preparations. Prescribing concentrates in Shanghai and Beijing community hospitals where mild-to-moderate cases comprise the bulk of patient volume; generic price erosion intensifies as provincial procurement platforms consolidate suppliers.
- Biologics:Monoclonal antibody therapies targeting TNF-alpha, integrin, and IL-23 pathways administered via infusion or subcutaneous injection. Jiangsu and Zhejiang manufacturing clusters are scaling fill-finish capacity to serve Beijing and Shanghai tertiary hospital demand; NMPA accelerated pathways compress approval timelines for novel mechanisms.
- Corticosteroids:Systemic and topical glucocorticoid formulations for acute flare induction.
- Immunomodulators:Thiopurine and methotrexate-based agents bridging to biologic therapy.
Volume placements concentrate in 5-Aminosalicylic Acid; the faster expansion belongs to Biologics.
Delivery Mode:
Route selection maps directly to therapy intensity and hospital pharmacy infrastructure investment levels.
- Injectable:Subcutaneous and intramuscular formulations requiring cold-chain distribution to hospital pharmacies. Zhejiang biopharma clusters are building captive pre-filled syringe capacity; prescriber preference for patient self-administration drives outpatient adoption.
- Intravenous:Hospital-based infusion center administration for biologic loading doses and maintenance. Beijing tertiary hospitals concentrate infusion suite capacity; adverse event monitoring requirements strain capital budgets in tier-two facilities.
- Oral:Tablet and capsule formulations for maintenance therapy.
- Topical:Rectal suppository and enema preparations for distal colitis.
Oral formulations capture the highest prescription counts; intravenous administration claims the steepest expansion trajectory as biologic penetration deepens.
End User:
Care setting fragmentation reflects reimbursement tiering and specialist concentration across China's hospital hierarchy.
- Hospitals:Tertiary and secondary general hospitals with dedicated gastroenterology departments. Shanghai Renji Hospital and Ruijin Hospital anchor biologic initiation volume; vertical pharmacy integration captures dispensing margin through wholly-owned specialty pharmacies.
- Specialty Clinics:Dedicated inflammatory bowel disease centers in tier-one cities. Beijing and Shanghai concentrate prescriber expertise; patient referral networks extend reach into surrounding provinces.
- Ambulatory Surgical Centers:Procedure-focused facilities with limited IBD therapeutic scope.
- Homecare:Self-administered maintenance therapy outside institutional settings.
Patient encounters cluster in hospitals; specialty clinics are gaining share fastest as IBD center certification expands.
Therapy Area:
Clinical positioning varies between gastrointestinal-specific protocols and broader autoimmune frameworks.
- Inflammatory Bowel Disease:Dedicated ulcerative colitis and Crohn's disease treatment pathways. NMPA Center for Drug Evaluation guidance shapes trial endpoints; mucosal healing benchmarks now standard for biologic approval.
- Gastroenterology:General digestive disease management including functional disorders.
- Autoimmune Disorders:Cross-specialty immunology frameworks sharing biologic mechanisms.
- Digestive Health:Preventive and nutritional interventions adjacent to pharmaceutical therapy.
Clinical investment concentrates in Inflammatory Bowel Disease; Autoimmune Disorders are climbing fastest as mechanism-based prescribing crosses specialty boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Monoclonal antibody manufacturing feedstock supply chains concentrate in Jiangsu and Zhejiang provinces, anchoring biologic therapy production capacity for the national market. Provincial healthcare procurement platforms tier reimbursement access across urban hospital networks.
Beijing-Tianjin-Hebei
Peking Union Medical College Hospital and Beijing Friendship Hospital anchor IBD specialist referral volume for northern China. NMPA headquarters proximity accelerates clinical trial protocol consultations for sponsors. The region's tertiary hospitals concentrate biologic initiation protocols and train gastroenterology fellows who disperse to provincial centers.
Yangtze River Delta
Shanghai Renji Hospital and Ruijin Hospital operate wholly-owned specialty pharmacies that capture biologic dispensing margin through vertical integration. Jiangsu manufacturing clusters in Suzhou and Taizhou scale pre-filled syringe fill-finish capacity for domestic monoclonal antibody output. NMPA Center for Drug Evaluation maintains regional office presence for sponsor engagement.
Pearl River Delta
Guangdong province's centralized procurement platform leads national tendering reform for biosimilar inclusion. Shenzhen biopharma parks attract Hong Kong-listed sponsors seeking mainland clinical trial sites. The corridor's logistics infrastructure supports cold-chain distribution to tier-two hospitals in Fujian and Guangxi.
Sichuan-Chongqing
Chengdu's West China Hospital anchors southwestern IBD patient volume with expanding biologic formulary access. Provincial reimbursement lists lag coastal tiers by 12-18 months, constraining novel mechanism penetration. Chongqing's pharmaceutical distribution hubs serve as transshipment points for cold-chain therapies entering western provinces.
Shandong Peninsula
Jinan and Qingdao hospitals concentrate gastroenterology departments with moderate biologic adoption rates below coastal benchmarks. Provincial unified bidding platforms prioritize cost containment, favoring 5-aminosalicylic acid generics over biologic expansion. Local CROs partner with multinational sponsors for patient recruitment into NMPA-registration trials.
China Ulcerative Colitis Market Competitive Landscape
Global majors compete with regional champions across hospital formulary access and prescriber relationship depth. Originators defend position through real-world evidence generation and deeper channel partnerships with provincial procurement platforms. Domestic biopharma developers accelerate via localized clinical trials and adaptive study designs. Competitive moves center on biosimilar manufacturing scale-up and vertical pharmacy integration.
Within the multinational originator tier, AbbVie Inc. and Johnson & Johnson occupy positions sustained by immunology infrastructure and hospital partnership depth. HUTCHMED represents the domestic biopharma archetype competing through China-specific clinical development and novel mechanism pipelines. These three anchors illustrate the market's bifurcation between global incumbents with established prescriber loyalty and emerging local sponsors leveraging regulatory proximity and adaptive trial capabilities.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson |
| Merck & Co., Inc. |
| Novartis AG |
| Takeda Pharmaceutical Company Limited |
| Bausch Health Companies Inc. |
| HUTCHMED |
| EA Pharma Co., Ltd. |
| Theravance Biopharma |
| Others |
Pricing and Supply Chain Analysis
Monoclonal antibody raw material costs cascade through Jiangsu and Zhejiang manufacturing clusters into tiered patient access structures across Chinese provincial reimbursement schemes. Cold-chain logistics premiums and infusion center service bundling separate originator biologics from biosimilar alternatives in hospital procurement negotiations.
Pricing Analysis
Service bundling distinguishes originator biologics from unbundled biosimilar alternatives in Chinese hospital procurement. Three-tier pricing structure across premium, standard, and economy levels reflects originator brand premiums, NMPA biosimilar certification tiers, and provincial reimbursement inclusion status. Price erosion runs through the 5-aminosalicylic acid maintenance segment as provincial unified bidding platforms consolidate generic suppliers. Community hospitals in tier-two cities exhibit highest price sensitivity; tertiary IBD centers in Beijing and Shanghai sustain originator premiums through prescriber loyalty and real-world evidence protocols.
Supply Chain Analysis
Dual-sourcing mandates from Beijing and Shanghai tertiary hospital procurement committees require monoclonal antibody sponsors to qualify at least two fill-finish contractors. Active pharmaceutical ingredient supply concentrates in Jiangsu and Zhejiang provinces, with fill-finish capacity expanding in Suzhou and Taizhou biopharma parks. Supply chain risk centers on single-source vulnerability for cold-chain distribution networks serving western provinces. Distribution runs through hospital-owned specialty pharmacies that capture dispensing margin through vertical integration of drug, infusion, and monitoring services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's ulcerative colitis market is consolidating around manufacturing scale and prescriber relationship depth, with NMPA biosimilar pathway acceleration forcing subscale originator-contract manufacturers toward exit or acquisition.
For Market Incumbents: Cement prescriber loyalty through real-world evidence generation partnerships with Beijing and Shanghai IBD centers. Deepen backward integration into Jiangsu fill-finish capacity to secure supply continuity against Zhejiang competitor expansion. Threats from domestic biopharma adaptive trial capabilities demand faster label expansion cycles; channel control through wholly-owned specialty pharmacies offers defensive margin capture. For New Entrants and Emerging Players: Provincial procurement platform managers represent the critical channel partner type for biosimilar formulary inclusion ahead of originator relationship deepening. Whitespace concentrates in Sichuan-Chongqing and Shandong Peninsula tier-two hospitals where reimbursement lags create 12-18 month access windows. Oral small molecule pipelines bypassing cold-chain infrastructure requirements offer the most penetrable mechanism class for market entry without incumbent infusion center partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic biopharma developers with NMPA-approved biosimilar assets and adaptive trial capabilities in Jiangsu manufacturing clusters. Long-term viability rests on mechanism diversification beyond anti-TNF dominance as IL-23 and integrin inhibitors reshape therapeutic sequencing. Watch NMPA Center for Drug Evaluation guidance on post-marketing study requirements as the inflection signal for label expansion premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Jiangsu and Zhejiang fill-finish expansion reduces import dependency for monoclonal antibody therapies. |
| Regulatory Approval Pathway | NMPA accelerated biosimilar frameworks compress originator exclusivity windows for domestic entrants. |
| Hospital System Partnership | Vertical pharmacy integration at Renji and Ruijin Hospitals captures biologic patient flow from prescription through administration. |
| Pipeline Diversification | JAK inhibitor and S1P modulator development creates non-injectable alternatives bypassing cold-chain requirements. |
| Clinical Trial Advancement | Adaptive basket protocols for IBD subpopulation stratification reward sponsors with faster label expansion pathways. |
Research Methodology
NMPA regulatory filings, ClinicalTrials.gov protocol registrations, and provincial procurement platform tender records formed the secondary backbone for this analysis. Primary interviews with drug development executives at domestic biopharma sponsors, regulatory affairs leads navigating NMPA Center for Drug Evaluation pathways, hospital formulary directors at Beijing and Shanghai tertiary centers, and payer access specialists at the National Healthcare Security Administration validated secondary findings. Bottom-up patient volume modeling and top-down biologic penetration rate triangulation anchored market size estimation across the analysis window.
Historical trendline analysis of anti-TNF and novel mechanism adoption rates informed projection frameworks through the forecast period. Segmentation dimensions modeled include therapeutic modality, delivery route, care setting tier, and provincial reimbursement cluster. CAGRs derived from spline interpolation of approved therapy access expansion and manufacturing capacity buildout trajectories. Forecast inputs incorporated NMPA approval timeline compression effects and cold-chain infrastructure maturation curves specific to Jiangsu and Zhejiang biopharma cluster development.
Caveats apply where NMPA biosimilar quality enforcement gaps or provincial reimbursement list revision delays could materially shift the outlook. Deviation in specialist gastroenterology workforce expansion rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Quadriplegia Treatment Market
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Axillary Hyperhidrosis Treatment Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Germ Cell Tumors Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Nocturnal Polyuria Treatment Market