
 Radiation Toxicity Treatment Market | 2026-2036
Radiation Toxicity Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Toxicity Treatment Market Analytics
The radiation toxicity treatment landscape is recalibrating around a widening gap between premium biologic radioprotectors and commodity generic chelating agents, with reimbursement thresholds diverging sharply across national health systems. Amgen leverages its established oncology infrastructure to anchor distribution in North American hospital networks. Novartis AG competes through sustained investment in long-acting myeloid growth factors that reduce neutropenia duration post-radiation exposure.
Radiation toxicity treatment encompasses pharmaceutical and biologic interventions designed to prevent, mitigate, or repair cellular damage caused by ionizing radiation, including free-radical scavengers, hematopoietic growth factors, and cytokine modulators administered at specified dose intensities calibrated to exposure level. The acute phase treatment segment dominates current revenue as stockpiling agreements by national strategic reserves prioritize immediate-response countermeasures, while long-term management represents the fastest-expanding margin pool as survivors of radiotherapy and nuclear incidents require extended hematologic and gastrointestinal support. Intravenous delivery anchors hospital-based revenue, though subcutaneous formulations are gaining traction in outpatient clinics seeking to reduce infusion chair time.
FDA emergency use authorization pathways and the Strategic National Stockpile program shape procurement volumes and product specifications for developers targeting the United States, while EMA orphan designation and the EU Health Emergency Preparedness and Response Authority framework govern market access across European member states. Japan's PMDA has streamlined review timelines for radioprotective biologics following revised nuclear disaster preparedness protocols. Stakeholders must monitor evolving stockpile replenishment cycles and dual-use military-civilian procurement policies that increasingly determine commercial viability ahead of traditional reimbursement negotiations.
Market Dynamics
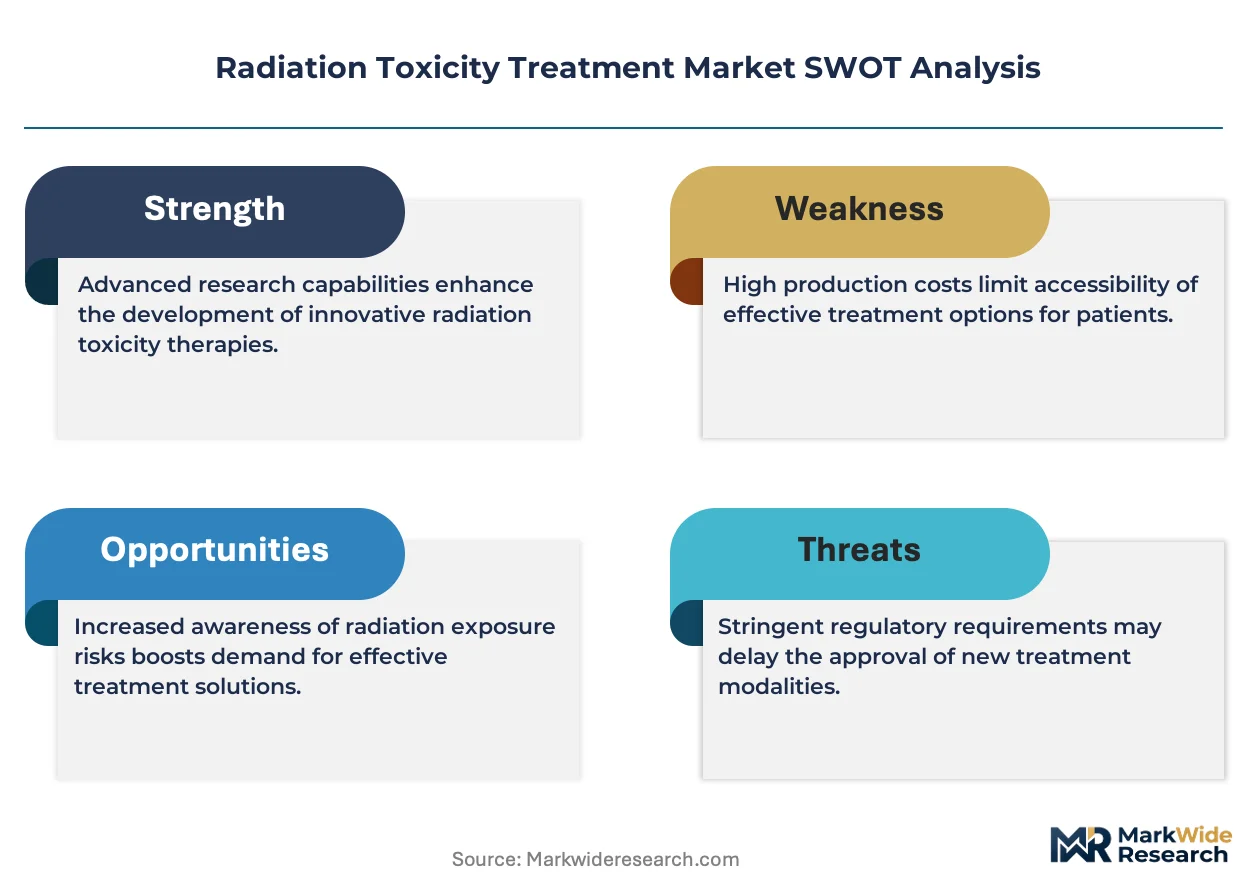
The radiation toxicity treatment market is bifurcating around procurement modality, with national strategic stockpiles commanding bulk volumes at compressed margins while oncology networks negotiate premium pricing for biologic radioprotectors calibrated to individual patient protocols.
Growth Catalysts
- FDA orphan-drug incentives:Developers targeting rare radiation injury indications receive seven-year market exclusivity and tax credits, accelerating pipeline prioritization toward hematopoietic syndrome countermeasures.
- External-beam radiation volumes:Oncology centers in the United States are expanding linear accelerator fleets, creating parallel demand for prophylactic agents that reduce mucositis and myelosuppression incidence.
- Japan's revised nuclear disaster protocols:PMDA streamlined review timelines for radioprotective biologics following Fukushima infrastructure overhauls, opening procurement channels for cytokine-based countermeasures.
Market Restraints
- Plasmid DNA manufacturing concentration:Contract development organizations for gene-therapy-based radioprotectors cluster in Massachusetts and North Carolina, creating single-source vulnerability for viral vector supply.
- EMA accelerated assessment thresholds:The requirement for substantial therapeutic benefit over existing myeloid growth factors excludes incremental formulation improvements from reduced-fee pathways.
- Generic chelating agent substitution:Diethylenetriaminepentaacetic acid and Prussian blue analogs commoditize acute decorporation therapy, compressing reimbursement for novel small-molecule entrants.
Strategic Opportunities
- Subcutaneous formulation expansion:Outpatient oncology clinics in Germany are adopting self-administered hematopoietic growth factors to reduce infusion chair utilization, opening ambulatory channels previously reserved for hospital-based intravenous delivery.
- Dual-use military-civilian procurement:NATO strategic reserves and national health ministries are converging specifications for radiation countermeasures, enabling single-product qualification across defense and civilian emergency-response tenders.
- Long-term survivor management protocols:Extended hematologic and gastrointestinal support for radiotherapy survivors represents an underserved margin pool as five-year survival metrics improve across solid tumor indications.
Industry Challenges
- Radiation biodosimetry integration:Deploying cytokine-based countermeasures requires real-time exposure quantification that current cytogenetic assays cannot deliver at triage scale, complicating dosing protocol validation.
- Current Good Manufacturing Practice retrofits:Legacy fill-finish facilities for sterile biologics require multimillion-dollar isolator upgrades to meet FDA sterility guidance revisions for parenteral radioprotectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Toxicity Treatment Market |
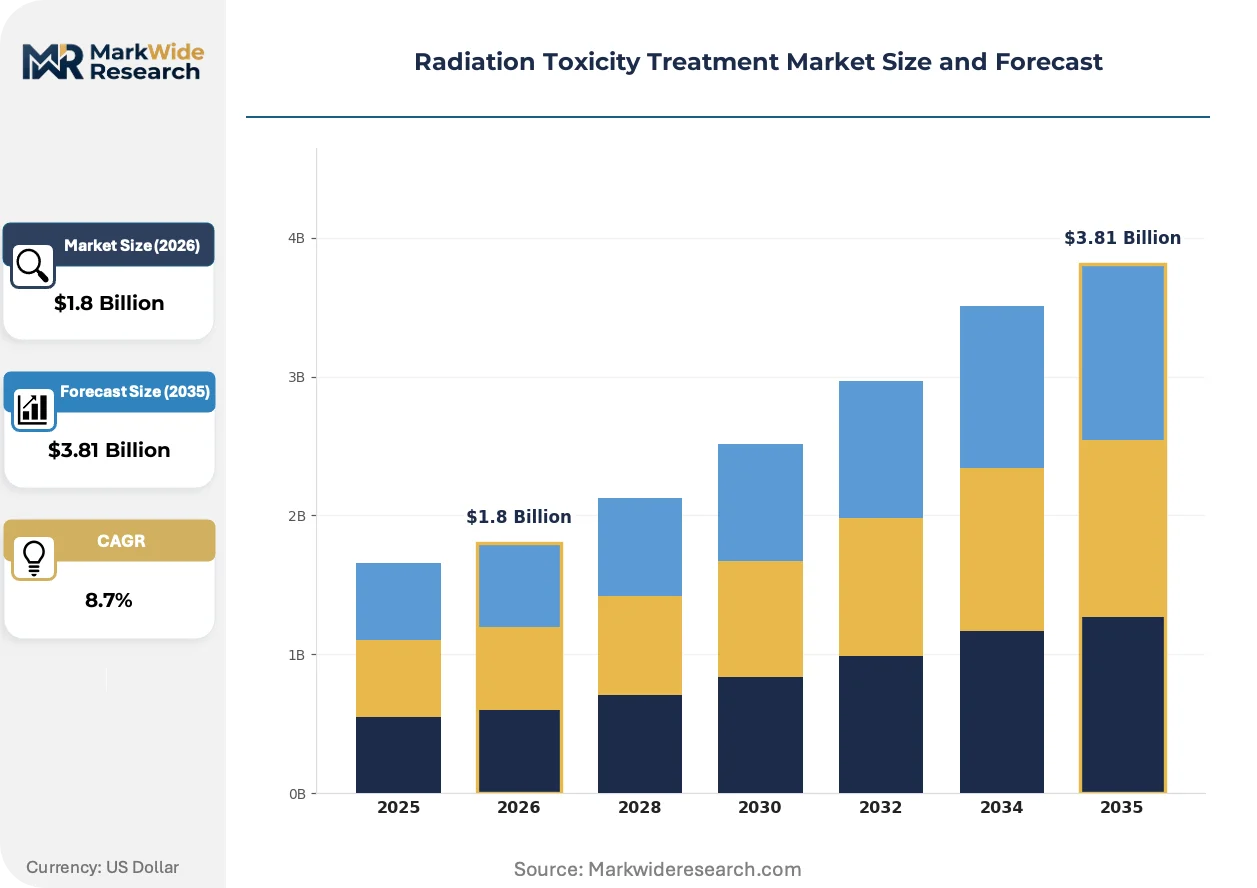
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cobalt-60, Cesium-137, Strontium-90, Iodine-131 Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Research Laboratories, Rehabilitation Centers, Outpatient Clinics Treatment Stage: Acute Phase, Post-Acute Care, Long-Term Management, Palliative Care |
| Companies Covered | Amgen, Novartis AG, Partner Therapeutics, Inc., Mylan NV, Coherus BioSciences Inc, Jubilant Life Sciences, Siegfried Holdings, Recipharm AB, Heyl Chemisch-pharmazeutische Fabrik GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Toxicity Treatment Market Evolving Landscape
Automation and algorithmic dosing are penetrating radiation toxicity management, compressing the latency between exposure assessment and therapeutic intervention while reshaping how prophylactic agents integrate into radiotherapy workflows.
Machine learning algorithms for radiation dose reconstruction are automating the triage prioritization of countermeasure administration in mass-casualty scenarios. Emergency medicine departments at academic medical centers in the United States are piloting these systems for radiological incident response. The technology is automating clinical decision support that previously required specialist consultation, compressing time-to-treatment windows from hours to minutes.
EMA's Health Emergency Preparedness and Response Authority framework is mandating centralized procurement specifications for radiation medical countermeasures across EU member states. Developers must now demonstrate thermal stability and extended shelf-life under variable climate conditions to qualify for joint procurement tenders. The regulation is forcing reformulation investments among biologics manufacturers previously optimized for cold-chain distribution.
Hospital networks are consolidating radioprotector purchasing through group purchasing organizations rather than individual pharmacy and therapeutics committees. This aggregation transfers price negotiation leverage from individual oncology centers to centralized procurement entities with formulary exclusion authority. The pattern is most visible in the United States, where three national GPOs now control access decisions for a majority of academic radiation oncology departments.
Radiation Toxicity Treatment Market Segmentation
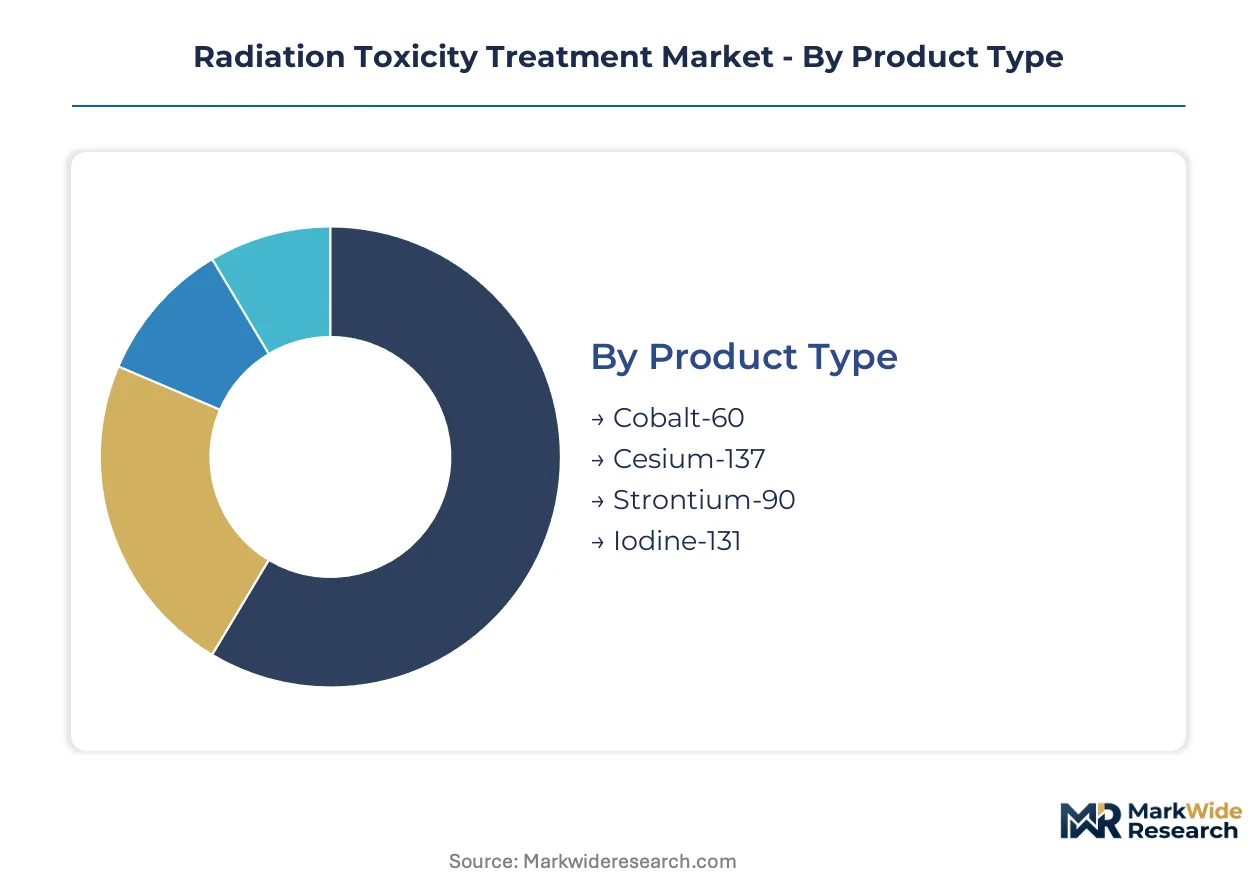
Radiation toxicity treatment procurement diverges sharply across institutional settings, with national stockpiles prioritizing shelf-stable formulations while oncology networks demand patient-calibrated biologics. Segmentation reveals how reimbursement modality and clinical workflow constraints reshape product development priorities.
Product Type:
Procurement officers weight isotope half-life against decay chain complexity when selecting decorporation agents for strategic reserves.
- Cobalt-60:Gamma-emitting isotope with 5.27-year half-life requiring chelation therapy with diethylenetriaminepentaacetic acid derivatives. Demand concentrates in United States Strategic National Stockpile contracts where thermal stability under variable storage conditions drives vendor selection.
- Cesium-137:Beta-gamma emitter with 30-year half-life treated with Prussian blue analogs. Oncology centers in Germany are expanding procurement for radiotherapy contamination protocols following revised nuclear medicine safety guidelines.
- Strontium-90:Pure beta-emitter with bone-seeking affinity managed through alginate-based decorporation agents. Research laboratories in Japan utilize this segment for biodosimetry calibration studies under PMDA streamlined review pathways.
- Iodine-131:Thyroid-targeting isotope with 8-day half-life blocked by potassium iodide prophylaxis. Outpatient clinics across the United States stockpile this agent for nuclear emergency response under FDA emergency use authorization frameworks.
Volume sits with Cesium-137; growth tilts toward Cobalt-60.
Delivery Mode:
Infusion chair economics and patient mobility requirements are redistributing formulation investments across the hospital-to-home continuum.
- Intravenous:Hospital-based administration of myeloid growth factors and cytokine modulators requiring sterile compounding infrastructure. Academic medical centers in the United States anchor demand where centralized pharmacy operations justify batch preparation economics.
- Oral:Self-administered decorporation agents including Prussian blue and potassium iodide formulations. Rehabilitation centers in Germany are adopting this mode to reduce length-of-stay for radiotherapy survivors managing chronic gastrointestinal toxicity.
- Subcutaneous:Prefilled syringe delivery of hematopoietic growth factors enabling ambulatory administration. Outpatient clinics in Japan are converting infusion protocols to subcutaneous alternatives under revised nuclear disaster preparedness guidelines.
- Topical:Cutaneous radioprotectors for localized radiation dermatitis management. Research laboratories in the United States are validating efficacy for proton therapy-induced skin reactions.
Intravenous commands current revenue; subcutaneous is expanding most quickly.
End User:
Institutional purchasing power and formulary control authority determine pricing tier access for developers.
- Hospitals:Comprehensive radiation oncology departments with centralized pharmacy and therapeutics committees governing biologic radioprotector access. United States academic medical centers concentrate procurement volume through group purchasing organization aggregation.
- Research Laboratories:Biodosimetry and countermeasure validation facilities requiring reference-grade isotopes and assay reagents. Japan's national radiation research institutes anchor regional demand under METI-funded infrastructure programs.
- Rehabilitation Centers:Long-term hematologic and gastrointestinal support for radiotherapy survivors. German outpatient rehabilitation networks are expanding cytokine-based protocols as five-year survival metrics improve.
- Outpatient Clinics:Ambulatory oncology settings seeking to reduce infusion chair utilization through self-administered formulations. United States community oncology practices are consolidating purchasing through national GPO networks.
Hospitals dominate absolute volume; outpatient clinics are gaining share fastest.
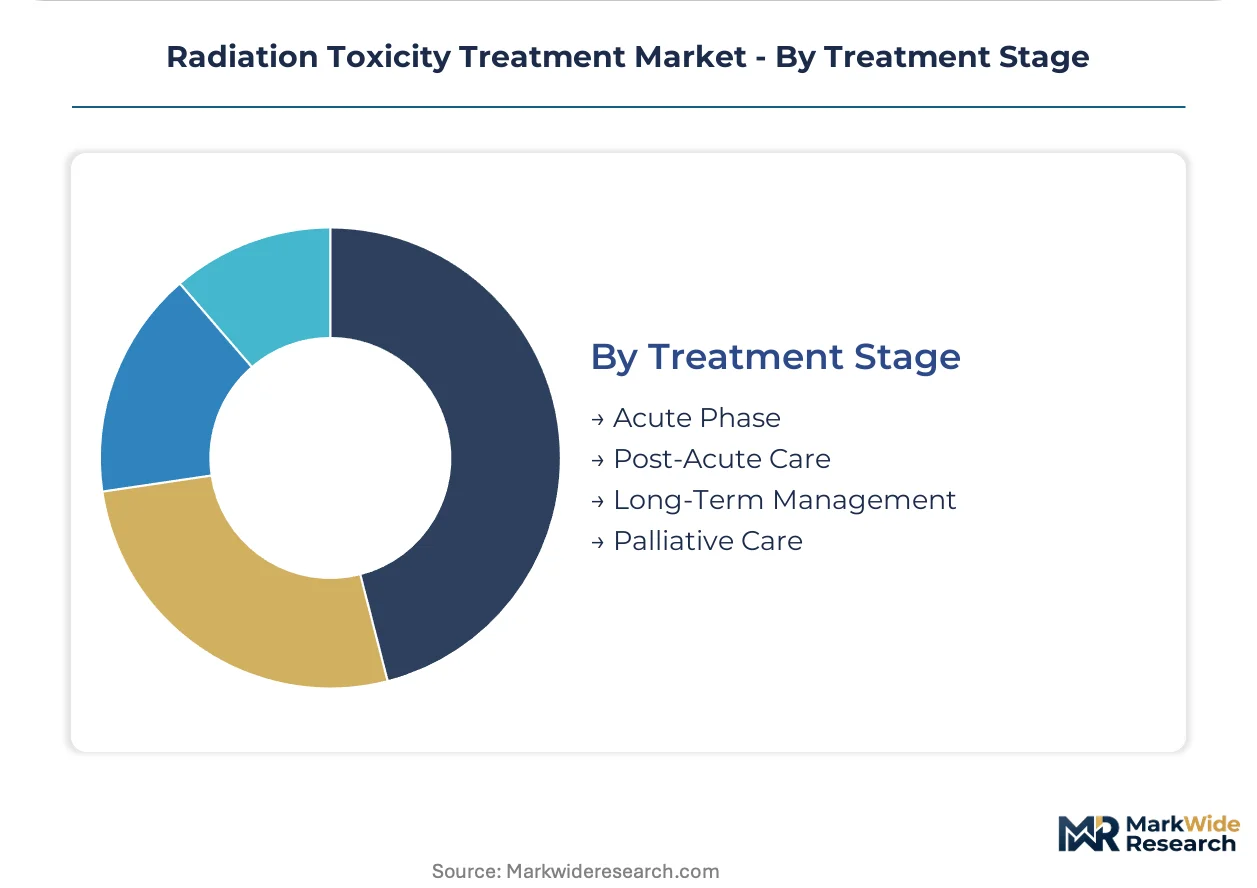
Treatment Stage:
Reimbursement coding and episode-based payment models are fragmenting revenue capture across the care continuum.
- Acute Phase:Immediate-response countermeasures administered within 24-48 hours of exposure, including cytokine-based hematopoietic syndrome management. National strategic reserves in the United States prioritize this stage through SNS replenishment cycles.
- Post-Acute Care:Subacute hematologic recovery protocols bridging hospital discharge to outpatient monitoring. German rehabilitation centers are developing standardized pathways for this transitional stage.
- Long-Term Management:Extended gastrointestinal and hematologic support for radiotherapy survivors and nuclear incident survivors. Japan's revised nuclear disaster protocols are expanding reimbursement for this previously underserved margin pool.
- Palliative Care:Symptom-directed interventions for radiation-induced mucositis and dermatitis in advanced oncology populations. Hospice networks in the United States are integrating topical radioprotectors into comfort-care protocols.
Acute Phase anchors current procurement; Long-Term Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors the world's densest concentration of radiation countermeasure research, hosting contract development organizations that manufacture plasmid DNA vectors for gene-therapy radioprotectors.
United States
The Strategic National Stockpile program drives bulk procurement of cytokine-based hematopoietic syndrome countermeasures, with FDA emergency use authorization pathways compressing vendor qualification timelines. Amgen leverages established oncology infrastructure to anchor distribution across academic medical centers in the Northeast and California.
Germany
Outpatient rehabilitation networks in Bavaria and North Rhine-Westphalia are expanding long-term gastrointestinal support protocols for radiotherapy survivors. EMA's Health Emergency Preparedness and Response Authority framework mandates centralized procurement specifications, forcing reformulation investments for thermal stability under variable climate conditions.
Japan
PMDA streamlined review timelines for radioprotective biologics following Fukushima infrastructure overhauls, opening procurement channels for cytokine-based countermeasures. Tokyo's national radiation research institutes anchor regional demand under METI-funded biodosimetry calibration programs.
United Kingdom
The NHS Specialized Commissioning framework governs access to premium biologic radioprotectors, creating tiered reimbursement thresholds that diverge from strategic stockpile procurement. London's academic medical centers pilot machine learning algorithms for radiation dose reconstruction in mass-casualty triage scenarios.
Switzerland
Swissmedic's accelerated assessment pathways for orphan radiation injury indications attract developers seeking European market access. Basel's pharmaceutical cluster hosts formulation specialists serving dual-use military-civilian procurement tenders through NATO strategic reserve channels.
Radiation Toxicity Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the biologic-versus-generic divide, with reimbursement thresholds diverging sharply between national health systems and strategic stockpile procurement. The market structures around three archetypes: established oncology infrastructure holders, long-acting myeloid growth factor specialists, and contract manufacturing organizations for sterile biologics. Consolidation pressures favor M&A activity among fill-finish capacity providers, while portfolio diversification into subcutaneous formulations reshapes competitive positioning.
Among US-based biopharmaceutical developers, Amgen and Novartis AG exemplify the premium-tier infrastructure archetype, occupying positions that leverage established hospital network relationships. Partner Therapeutics, Inc. represents the emerging radioprotective specialist segment. German and Swiss contract manufacturers including Siegfried Holdings and Recipharm AB anchor the supply-side concentration for sterile parenteral production.
| Leading Market Players |
|---|
| Amgen |
| Novartis AG |
| Partner Therapeutics, Inc. |
| Mylan NV |
| Coherus BioSciences Inc |
| Jubilant Life Sciences |
| Siegfried Holdings |
| Recipharm AB |
| Heyl Chemisch-pharmazeutische Fabrik GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up contract manufacturing organizations in Massachusetts and North Carolina anchor sterile fill-finish capacity for parenteral radioprotectors, concentrating ownership among financial sponsors who impose margin discipline through batch-size optimization and multi-year offtake minimums. This ownership pattern tightens pricing power at the biologic tier while compressing commodity chelating agent margins through volume consolidation.
Pricing Analysis
Value-based pricing anchored to neutropenia duration reduction commands premium tiers for long-acting myeloid growth factors in oncology networks. Three-tier pricing structure across premium biologics, standard biosimilars, and economy generics separates hospital formulary access from strategic stockpile procurement. Cost compression in the generic chelating agent tier intensifies because Prussian blue and DTPA analogs face therapeutic substitution. National stockpile buyers exhibit lowest price sensitivity due to emergency-use authorization mandates, while outpatient clinics negotiate hardest on per-dose economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA sterility guidance revisions force developers to qualify multiple fill-finish contractors across Massachusetts, North Carolina, and Switzerland. Plasmid DNA vectors for gene-therapy radioprotectors draw from single-source contract development organizations, creating vulnerability. Single-source vulnerability concentrates in viral vector supply. Distribution runs through group purchasing organizations that aggregate hospital network demand and transfer price negotiation leverage from individual pharmacy committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile biologics manufacturing capacity constraints prop pricing power for qualified suppliers, as FDA sterility guidance revisions and legacy facility retrofit costs create bottlenecks that outpace demand growth from expanding radiotherapy volumes.
For Market Incumbents: Deploy subcutaneous formulation investments to capture ambulatory oncology clinic conversions away from intravenous protocols. Consolidate fill-finish capacity through targeted acquisitions of Massachusetts and North Carolina contract manufacturers facing isolator upgrade capital requirements. Generic chelating agent substitution threatens margin pools in the acute decorporation segment. For New Entrants and Emerging Players: FDA emergency use authorization pathways in the United States open a window for developers targeting hematopoietic syndrome countermeasures with streamlined review timelines. Long-term management protocols for radiotherapy survivors represent the most penetrable segment, underserved by current cytokine-based portfolios. Pursue dual-use military-civilian procurement qualification to access NATO strategic reserve tenders alongside civilian stockpile contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap sterile biologics manufacturers with isolator-compliant facilities in Switzerland and Germany facing temporary margin pressure from reformulation investments. Long-term viability rests on five-to-ten year radiotherapy volume expansion and nuclear disaster preparedness protocol revisions. Watch for PMDA streamlined review pathway expansion as the inflection signal for Japanese procurement channel opening.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces infusion chair utilization at German outpatient clinics seeking workflow efficiency. |
| Dual-Use Military-Civilian Qualification | Enables single-product access to NATO strategic reserves and national health ministry tenders. |
| Isolator Retrofit Investment | Meets FDA sterility guidance revisions for parenteral radioprotector manufacturing compliance. |
| Long-Term Survivor Protocol Expansion | Captures underserved margin pools as five-year survival metrics improve across solid tumors. |
| Machine Learning Triage Integration | Compresses time-to-treatment windows at academic medical centers piloting dose reconstruction algorithms. |
Research Methodology
Document review covered FDA emergency use authorization filings, EMA orphan designation records, and Strategic National Stockpile procurement specifications, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Secondary validation drew from ClinicalTrials.gov entries, CMS Medicare reimbursement databases, and GPO contract repositories. Bottom-up patient-flow modeling and top-down epidemiological scaling were triangulated against manufacturer capacity disclosures.
Historical volume trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include treatment stage, delivery mode, end-user institution type, and regional regulatory cluster. CAGRs were derived from fitting logistic adoption curves to radiotherapy volume expansion and nuclear preparedness protocol revision timelines. Forecast inputs incorporated linear accelerator fleet expansion data and stockpile replenishment cycle schedules.
The model assumes a particular technology adoption path for machine learning-based radiation biodosimetry; alternative pathways for cytogenetic assay automation would alter the outlook for cytokine-based countermeasure dosing protocol validation. Deviation in FDA sterility guidance enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market