
 Global Synthetic Spider Silk Market | 2026-2036
Global Synthetic Spider Silk Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synthetic Spider Silk Market Intelligence
The fragmentation of buyers across niche research and development projects is decoupling early-stage material validation from large-scale commercial offtake agreements. In this environment, AMSilk specializes in cosmetic and medical-grade silk proteins for high-margin applications. Kraig Biocraft Laboratories focuses on genetically engineered silkworms for military and industrial textile production. Bolt Threads leverages its bio-fermentation platform to develop materials for the apparel industry.
Synthetic spider silk refers to bio-engineered materials that replicate the protein structure, primarily spidroins, of natural spider silk. These materials are produced via methods like fermentation and exhibit exceptional tensile strength and elasticity, far exceeding many conventional polymers. Recombinant DNA and fermentation technologies represent the foundational production methods, while electrospinning is used for fiber formation. Within applications, textile manufacturing and biomedical implants are the most prominent segments, with automotive components emerging as a long-term opportunity.
Biomedical applications of synthetic spider silk fall under the purview of regulators like the US FDA and the European Medicines Agency (EMA), requiring extensive biocompatibility and safety data. For industrial and textile uses, compliance with chemical safety frameworks such as the EU's REACH regulation is necessary for market access. Stakeholder success will depend on navigating the complex regulatory pathways for novel biomaterials while scaling production to meet cost targets for commercial adoption.
Market Dynamics
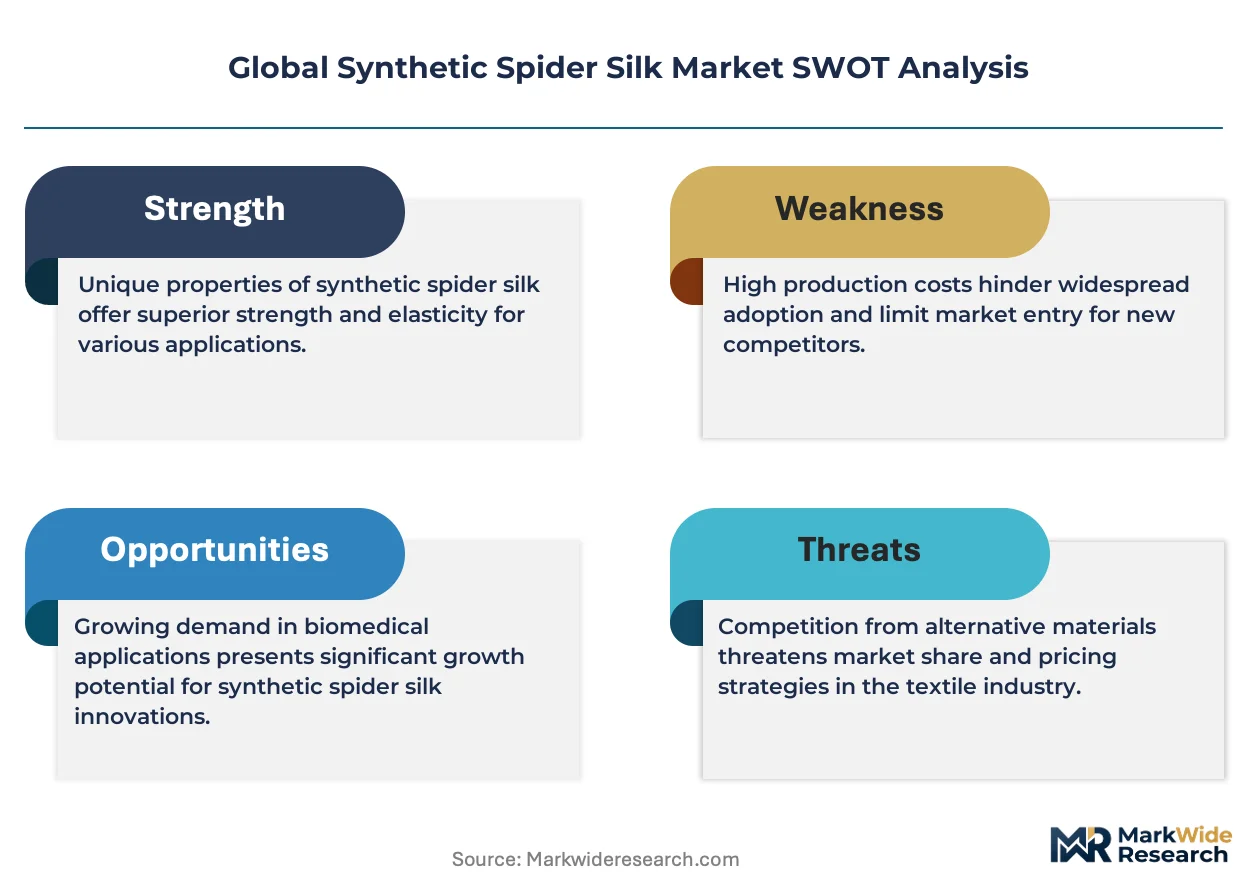
The central dynamic shaping the synthetic spider silk market is the bifurcation of demand between high-margin, low-volume biomedical applications and the cost-sensitive, high-volume textile industry. This split influences everything from production technology choices to regulatory strategy and investment priorities.
Growth Catalysts
- Advances in Biotechnology:Progress in recombinant DNA technology and scaled fermentation processes is improving the yield and consistency of spidroin protein production, making industrial-scale manufacturing more economically viable.
- Sustainable Textile Demand:The apparel industry's search for high-performance, petroleum-free fibers, amplified by regulations like the EU's Corporate Sustainability Reporting Directive (CSRD), creates a significant pull for biodegradable materials like synthetic spider silk.
- Government Procurement Programs:Defense and security agencies, particularly in the United States, are funding research and placing procurement orders for next-generation ballistic textiles and lightweight gear, providing critical early-stage revenue.
Market Restraints
- High Production Costs:The expense of sterile fermentation, protein purification, and fiber spinning keeps synthetic spider silk at a significant price premium over incumbent materials like nylon and polyester, limiting its adoption in mass-market applications.
- Technical Scaling Hurdles:Replicating the consistent tensile strength and elasticity of natural spider silk at an industrial scale remains a significant engineering challenge, with batch-to-batch variability affecting material reliability for demanding applications.
- Stringent Regulatory Pathways:Medical applications require extensive biocompatibility and clinical trial data to gain approval from bodies like the US FDA and the European Medicines Agency (EMA), creating long and costly development cycles.
Strategic Opportunities
- Automotive Lightweighting:The automotive sector presents a long-term opportunity for using synthetic spider silk in interior components, composites, and tire cords to reduce vehicle weight and improve fuel efficiency.
- Smart Textile Integration:Combining synthetic spider silk with conductive elements opens pathways for creating advanced smart textiles for use in wearable health monitoring devices and integrated electronics.
- Asia-Pacific Market Entry:The advanced materials markets in Japan and South Korea, with their strong focus on high-tech textiles and electronics, represent underpenetrated geographies for specialized spidroin-based products.
Industry Challenges
- Capital-Intensive Scale-Up:Constructing and operating large-scale bioreactors and fiber spinning facilities requires substantial capital investment, creating a high barrier to entry for new players and constraining capacity growth for incumbents.
- Lack of Industry Standards:The absence of globally accepted ISO standards for testing and grading synthetic spider silk creates uncertainty for industrial purchasers and complicates material specification in supply contracts.
- Intellectual Property Density:A complex and crowded patent landscape surrounding spidroin gene sequences and manufacturing processes creates significant legal risks and can complicate technology licensing agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synthetic Spider Silk Market |
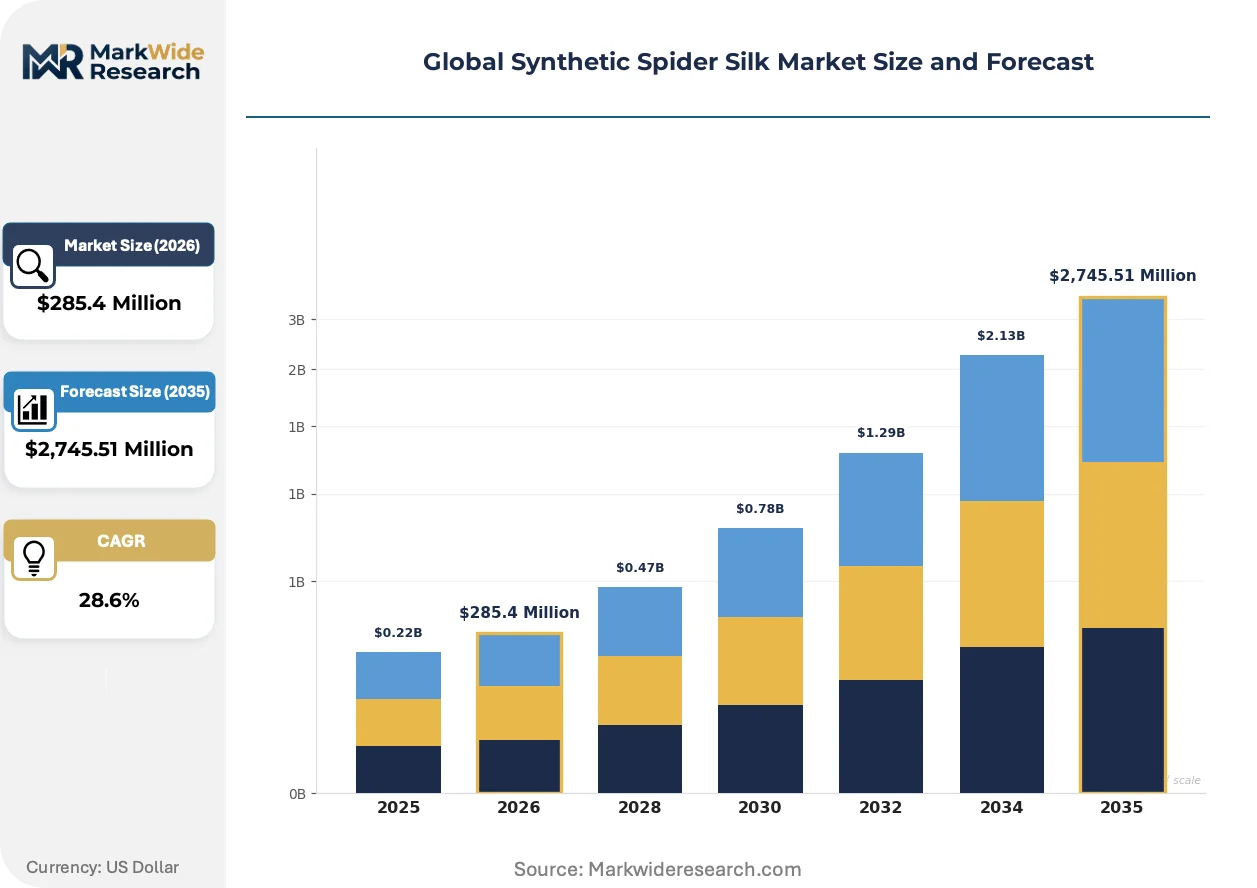
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $2,745.51 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spider Silk Fibers, Spidroin Proteins, Non-Woven Fabrics, Composite Materials Technology: Recombinant DNA, Fermentation, Electrospinning, Synthetic Polymer Blending, Biomimicry Application: Textile Manufacturing, Biomedical Implants, Automotive Components, Aerospace Materials, Military Gear, Electronics End User: Research Laboratories, Apparel Brands, Defense Contractors, Aerospace Manufacturers, Medical Device Developers |
| Companies Covered | Spiber, Xampla, Kraig Biocraft Laboratories, Inspidere BV, Spidey Tek, Bolt Threads, Seevix Material Sciences, Spintex Engineering, AMSilk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synthetic Spider Silk Market Strategic Shifts & Innovations
Bioprocessing advancements are enabling a critical shift from lab-scale curiosities to commercially viable materials. This evolution is unlocking new functionalities and pushing synthetic spider silk into application areas far beyond simple textile replacement, focusing on tailored performance characteristics.
Electrospinning is a key fiber formation technology that allows for the creation of non-woven mats with nanoscale fiber diameters. Biomedical device developers are adopting this method to produce scaffolds for tissue engineering and advanced wound dressings. The technique's precision in controlling fiber morphology is electrifying material development for regenerative medicine, enabling the design of complex structures that mimic the extracellular matrix.
Compliance with the EU's REACH regulation is a primary consideration for producers targeting the European market. This framework requires comprehensive safety data on all chemical substances, including novel biomaterials, before they can be sold. Consequently, manufacturers of industrial and textile-grade silk must invest heavily in toxicological and environmental impact studies to secure market access, affecting cost structures and development timelines.
Co-development partnerships are replacing traditional material sales models in specialized sectors. Instead of purchasing off-the-shelf fibers, end-users in aerospace and medical fields are collaborating directly with silk producers from the earliest stages of research and development. This model is most visible in the United States and Germany, where application-specific performance is paramount and material properties must be precisely tuned.
Global Synthetic Spider Silk Market Segmentation
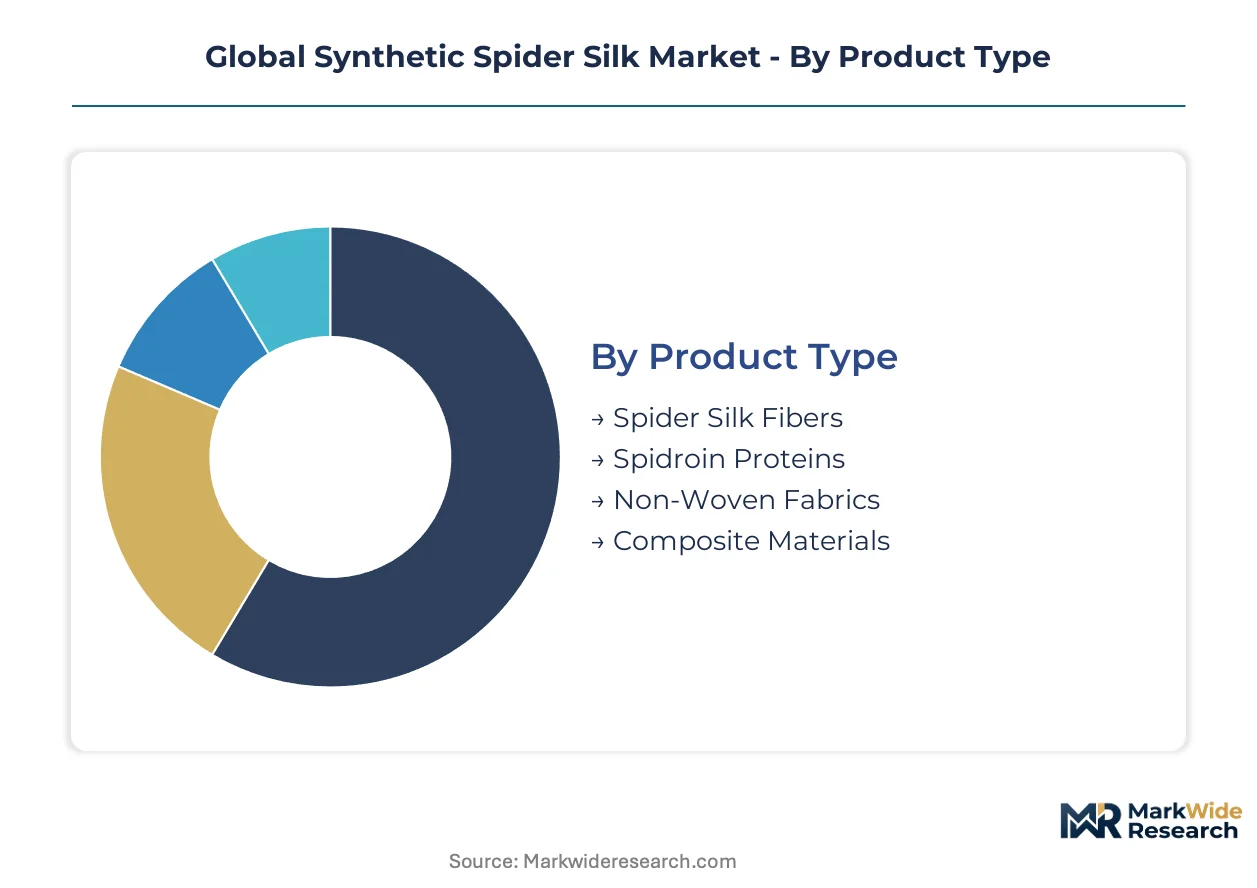
The synthetic spider silk market segments reflect diverse material forms, production methods, and end-use requirements. Understanding these distinct categories is crucial for stakeholders to identify areas of concentrated demand and technological specialization. Each segment presents unique challenges and opportunities for product development and market penetration.
Product Type:
The product type segmentation differentiates synthetic spider silk based on its level of processing and integration into final material forms, ranging from raw protein to finished composites.
- Spider Silk Fibers:These are extruded filaments replicating the mechanical properties of natural spider silk, known for exceptional tensile strength and elasticity. Demand concentrates in high-performance textile manufacturing for lightweight and durable materials.
- Spidroin Proteins:These are the foundational protein precursors, typically produced via recombinant DNA and fermentation, before being spun or formulated. Biomedical implant developers procure these for scaffold fabrication due to inherent biocompatibility.
- Non-Woven Fabrics:These materials form by binding or interlocking fibers through mechanical, thermal, or chemical means, without weaving. Medical device developers use non-woven fabrics for advanced wound dressings.
- Composite Materials:Synthetic spider silk reinforces matrices like resins or polymers to enhance strength-to-weight ratios. Aerospace manufacturers explore these composites for lightweight structural components.
Spider Silk Fibers leads volumes today; Spidroin Proteins are gaining share fastest.
Technology:
The technology segment outlines the diverse methods employed for producing and processing synthetic spider silk, each offering distinct advantages for specific applications and scalability.
- Fermentation:This biotechnological process uses microorganisms, often genetically modified, to produce spidroin proteins in large bioreactors. This method is critical for scaling protein production economically for industrial textile applications.
- Electrospinning:This technique uses an electric field to draw fine fibers from a polymer solution, creating nanoscale non-woven mats. Biomedical device developers leverage electrospinning for creating scaffolds that mimic the extracellular matrix for tissue regeneration.
- Recombinant DNA:This genetic engineering technique modifies organisms to produce specific spidroin proteins, forming the basis for scalable and consistent protein synthesis. Research laboratories apply recombinant DNA for developing new protein variants.
- Synthetic Polymer Blending:Synthetic spider silk combines with conventional synthetic polymers to create hybrid materials with enhanced properties or reduced costs. Automotive components integrate these blends for improved durability.
- Biomimicry:This approach involves designing materials and processes that imitate the structures and functions found in natural spider silk. Defense contractors apply biomimicry for developing advanced ballistic protection.
Fermentation offers the most cost-efficient production route; Electrospinning provides precision for high-value applications.
Application:
The application segment distinguishes the primary end-use industries where synthetic spider silk materials are deployed, highlighting the varied performance requirements across sectors.
- Textile Manufacturing:This segment integrates synthetic spider silk fibers into fabrics for apparel, sportswear, and industrial textiles, valued for strength, elasticity, and sustainability. Demand for high-performance, petroleum-free fibers drives adoption.
- Biomedical Implants:Synthetic spider silk is used in medical devices such as sutures, surgical meshes, and tissue engineering scaffolds due to its biocompatibility. The US FDA requires extensive safety data for these applications.
- Automotive Components:The material finds potential use in lightweight vehicle parts, interior textiles, and tire cords, contributing to fuel efficiency. Automotive manufacturers explore these materials for weight reduction initiatives.
- Aerospace Materials:Synthetic spider silk offers high strength-to-weight ratios suitable for lightweight structural components, advanced composites, and protective coatings in aircraft. Aerospace manufacturers seek improved performance and fuel efficiency.
- Military Gear:This includes ballistic protection, lightweight uniforms, and specialized equipment requiring extreme durability and performance. Defense agencies fund research into next-generation ballistic textiles.
- Electronics:Emerging applications include flexible electronics, sensors, and protective coatings for sensitive components due to unique electrical and mechanical properties. Research laboratories investigate novel conductive spider silk composites.
Biomedical Implants present high-margin opportunities; Automotive Components show significant long-term potential.
End User:
The end user segmentation categorizes the primary entities procuring or utilizing synthetic spider silk products, reflecting different market drivers and procurement strategies.
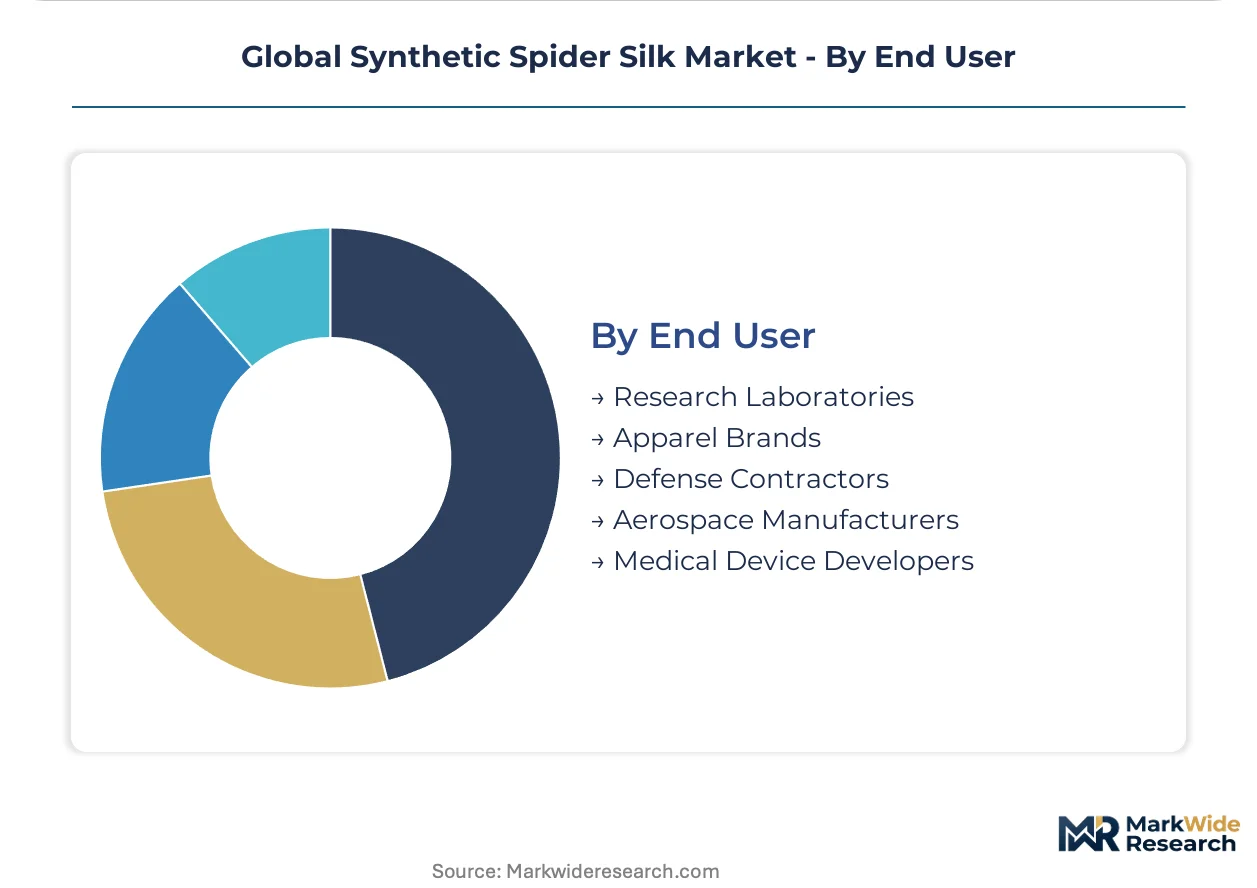
- Apparel Brands:These companies integrate synthetic spider silk into their product lines to offer high-performance, sustainable, and innovative clothing and accessories. The EU's Corporate Sustainability Reporting Directive influences material choices for apparel brands.
- Medical Device Developers:These firms incorporate synthetic spider silk into products for surgical, regenerative medicine, and diagnostic applications, valuing its biocompatibility. Regulatory approval from bodies like the EMA is crucial for medical device developers.
- Research Laboratories:Academic institutions and corporate R&D centers conduct fundamental and applied research on synthetic spider silk properties, production methods, and novel applications. These laboratories drive early-stage material validation.
- Defense Contractors:These entities procure synthetic spider silk for military applications, including advanced body armor, ballistic fabrics, and lightweight tactical equipment. Government procurement programs in the United States support defense contractors.
- Aerospace Manufacturers:Companies in the aerospace sector use synthetic spider silk for lightweight structural components, interior materials, and advanced composites. These manufacturers prioritize superior strength-to-weight ratios.
Apparel Brands represent a high-volume customer base; Medical Device Developers require specialized, high-margin materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentrations in biotechnology and advanced materials research anchor regional development in synthetic spider silk. These specialized workforces drive innovation in protein engineering and fiber spinning techniques. Regulatory environments and government funding initiatives further shape market growth across key geographies.
United States
Demand for advanced military gear and high-performance biomedical implants drives significant research and procurement activity. The US FDA imposes stringent requirements for medical applications, necessitating extensive biocompatibility studies. Major biotech clusters like Boston and San Francisco are hubs for spidroin protein development and medical device innovation.
Germany
The country's robust automotive and advanced materials sectors create a strong pull for lightweight components and high-tech textiles. Compliance with the EU's REACH regulation is essential for market entry, ensuring chemical safety and environmental responsibility. Cities such as Munich and Stuttgart concentrate automotive R&D and advanced manufacturing capabilities.
Japan
High-tech textile manufacturing and electronics integration are primary demand drivers for specialized spider silk materials. The Ministry of Economy, Trade and Industry (METI) supports advanced materials innovation through various industrial policies. The Kansai region, including Osaka, is a center for advanced fiber production and materials science research.
South Korea
Smart textile integration and high-performance apparel manufacturing are key application areas. The Ministry of Food and Drug Safety (MFDS) regulates biomedical applications, ensuring product safety and efficacy. The Seoul Capital Area is a focal point for R&D in wearable electronics and advanced textile development.
China
Large-scale textile manufacturing and emerging industrial applications represent significant volume opportunities. National GB standards guide product quality and safety for new materials entering the market. The Yangtze River Delta region is a major hub for textile production and materials science innovation.
Global Synthetic Spider Silk Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the synthetic spider silk market. This dynamic creates a tiered structure, from large-scale material producers to niche application developers. Strategic archetypes include bio-fermentation innovators, fiber spinning experts, and application-specific solution providers. Companies frequently engage in strategic partnerships and technology licensing to expand their market reach.
Within the bio-fermentation innovator archetype, Bolt Threads leverages its platform to develop materials for the apparel industry. Kraig Biocraft Laboratories exemplifies specialists in genetically engineered silkworms for military and industrial textiles. AMSilk occupies a position among the niche application developers, specializing in cosmetic and medical-grade silk proteins for high-margin uses.
| Leading Market Players |
|---|
| Spiber |
| Xampla |
| Kraig Biocraft Laboratories |
| Inspidere BV |
| Spidey Tek |
| Bolt Threads |
| Seevix Material Sciences |
| Spintex Engineering |
| AMSilk |
| Others |
Cost & Logistics Intelligence
The EU's Corporate Sustainability Reporting Directive actively gates qualified supply and premium-tier pricing access for novel biomaterials. This mandate compels manufacturers to demonstrate comprehensive environmental and social performance.
Pricing Analysis
The bundled-vs-unbundled service split influences synthetic spider silk pricing, particularly for specialized applications. Contract-based long-term offtake agreements dominate high-volume textile procurement, while value-based pricing prevails for biomedical implants. Quality grade, differentiated by regulatory certifications from the US FDA or European Medicines Agency, drives significant price differentiation. Cost compression in mass-market textile applications stems from direct competition with established polymers like nylon and polyester. The textile industry remains highly price-sensitive, contrasting with biomedical and aerospace sectors where performance justifies premium pricing.
Supply Chain Analysis
Single-source vulnerability sits with specialized bioreactor and protein purification equipment suppliers, impacting overall production capacity. Spidroin protein production is geographically dispersed, with significant R&D and early-stage manufacturing in the United States and Germany. Raw material dependencies include specialized fermentation media and recombinant DNA technologies. Technical scaling hurdles represent a significant supply chain risk, affecting batch-to-batch consistency and volume. Distribution runs primarily through direct sales channels to advanced materials manufacturers and medical device developers, with some specialized distributors serving niche R&D markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with mandates like the EU's Corporate Sustainability Reporting Directive driving demand. These regulations compel industries to seek sustainable, high-performance material alternatives.
For Market Incumbents: Lock in long-term off-take agreements with high-volume textile manufacturers to stabilize revenue streams. Invest further in proprietary spidroin protein strains to reduce production costs and improve yield consistency, mitigating cost pressure from conventional polymers. Expand production capacity in advanced manufacturing hubs to meet future demand. Pursue strategic partnerships for co-development of application-specific materials in aerospace and biomedical fields.
For New Entrants and Emerging Players: Enter via niche, high-margin biomedical applications like electrospun tissue engineering scaffolds, where performance outweighs cost. Target smart textile components for wearable health monitoring devices, leveraging unique material properties. The most penetrable segment remains specialized medical device components due to their stringent performance requirements. A strong go-to-market angle involves co-development partnerships with R&D-intensive end-users in the United States and Germany.
For Investors and Strategic Acquirers: Roll-up economics work for bio-fermentation innovators because intellectual property density and scaling hurdles create barriers to entry. Long-term viability remains strong for biomaterials over the next decade, driven by sustainability mandates and performance needs. Acquisition targets should focus on companies with proven spidroin protein production platforms and robust patent portfolios. A key signal to watch is the successful commercialization of textile-grade synthetic spider silk fibers at competitive price points.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Bioreactor Technology Investment | Optimizes spidroin protein yield and consistency, enhancing economic viability for industrial textile applications. |
| Biomedical Certification Pathway Acceleration | Expedites US FDA and European Medicines Agency approvals, unlocking high-margin medical implant markets. |
| Sustainable Textile Co-Development Programs | Secures early adoption with apparel brands, aligning with EU's Corporate Sustainability Reporting Directive. |
| Intellectual Property Portfolio Expansion | Defends core technology and creates licensing opportunities, navigating a crowded patent landscape. |
| Asia-Pacific Manufacturing Footprint Expansion | Accesses large-scale textile manufacturing and high-tech markets in China and Japan. |
Research Approach
Bottom-up textile manufacturing and biomedical implant modeling reconciled against top-down spidroin protein supply tracking forms the analytical core. This approach integrates primary interviews with material scientists, textile engineers, medical device developers, and defense procurement officers. Secondary validation draws from academic journals, patent databases, corporate financial filings, and regulatory submissions to the US FDA and European Medicines Agency. This triangulation ensures robust data integrity across diverse market facets.
Historical trendline analysis informs the quantitative framework, projecting market evolution across the analysis window. The model segments the market by product type, technology, application, end user, and regulatory compliance level. Compound annual growth rates derive from historical growth rates and projected market drivers such, as sustainable textile demand and government procurement programs. Key industry-specific forecast inputs include spidroin protein yield improvements and bio-fermentation scale-up costs over the projection horizon.
Inputs from corporate filings and scientific publications were available through the study window; gaps in early-stage pilot project data introduce uncertainty bands. Forecasts reflect assumptions regarding continued bioprocessing advancements and stable regulatory environments. Rapid technological shifts in bioproduction or unforeseen regulatory changes could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Melt Spun Fibers Market