
 E-Glass Fiber Yarn and Roving Market | 2026-2036
E-Glass Fiber Yarn and Roving Market Size, Share, and Industry Trends Forecast 2026-2036
E-Glass Fiber Yarn and Roving Market Analysis
Heavy roving bundling for wind turbine blade preforms is consolidating buyer preference toward larger tex packages that reduce lay-up labor. Owens Corning leverages its North American furnace network to anchor supply commitments for blade OEMs. Jushi Group specializes in ultra-high tex roving for offshore wind applications, while CPIC dominates domestic yarn distribution across China's thermoplastics compounding sector.
E-glass fiber yarn and roving consists of continuous filaments drawn from boron-free aluminosilicate glass melt, typically exhibiting tensile strength above 3,400 MPa and modulus near 72 GPa, engineered primarily as reinforcement for polymer matrix composites in structural load-bearing applications. Roving commands the dominant volume position due to its direct feeding into pultrusion and filament winding processes for wind energy and construction, whereas yarn maintains premium positioning in aerospace prepregs where precision filament alignment determines laminate performance. Continuous filament technology leads manufacturing throughput, though chopped strand formats are gaining traction in automotive underbody shields where automated spray-up replaces hand lay-up.
China's SAMR enforces GB/T 18369 standards for alkali content and filament diameter consistency, while the EU REACH framework restricts boron leaching in glass formulations exported to European automotive and marine end users. The US FAA and EPA jointly influence aerospace-grade yarn certification and emissions controls at melting furnace operations, creating compliance layering that favors producers with multi-jurisdiction testing capabilities. Stakeholders must monitor evolving recyclability mandates across these regulatory spheres, as mechanical recycling infrastructure for end-of-life wind blades will reshape raw material specifications and supplier qualification timelines.
Market Dynamics
Wind turbine blade scaling is compressing roving specifications toward ultra-high tex formats that slash lay-up labor while demanding tighter filament diameter tolerances from melt operations. This specification compression is redrawing supplier qualification timelines and furnace investment priorities across the value chain.
Growth Catalysts
- China's dual carbon goals:Binding emissions targets under MEE oversight are accelerating wind farm deployment, pulling heavy roving demand into Jiangsu and Shandong production clusters.
- Automotive lightweighting mandates:EU REACH restrictions on boron leaching are favoring compliant E-glass formulations in electric vehicle underbody shields and battery enclosures.
- Chopped strand automation:Thermoplastics compounding lines are adopting automated spray-up systems that displace hand lay-up in bumper beam manufacturing.
Market Restraints
- Energy cost volatility:Melting furnace operations consume natural gas and electricity at intensity levels that erode margin when European energy prices spike.
- Supply concentration in China:GB/T 18369-certified production clusters dominate global yarn output, creating single-source risk for aerospace prepreg qualification.
- Carbon fiber substitution:Pressure vessel and high-performance automotive applications are migrating toward T700-grade carbon where modulus requirements exceed 72 GPa.
Strategic Opportunities
- India thermoplastics penetration:BIS certification alignment for automotive compounding is opening yarn demand from Pune and Chennai molding clusters serving domestic OEMs.
- Blade recycling infrastructure:Mechanical shredding capacity for end-of-life wind turbines is creating circular feedstock specifications that favor boron-free formulations.
- Digital twin furnace control:Convergence of IoT sensors and predictive analytics is enabling real-time alkali content adjustment that reduces off-spec filament.
Industry Challenges
- FAA aerospace certification timelines:Prepreg qualification for commercial aviation requires 18-24 month testing cycles that lock suppliers into rigid process documentation.
- Skilled furnace operator scarcity:Platinum-rhodium bushing maintenance and glass melt chemistry control demand expertise that aging workforces in North America and Europe cannot replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Glass Fiber Yarn and Roving Market |
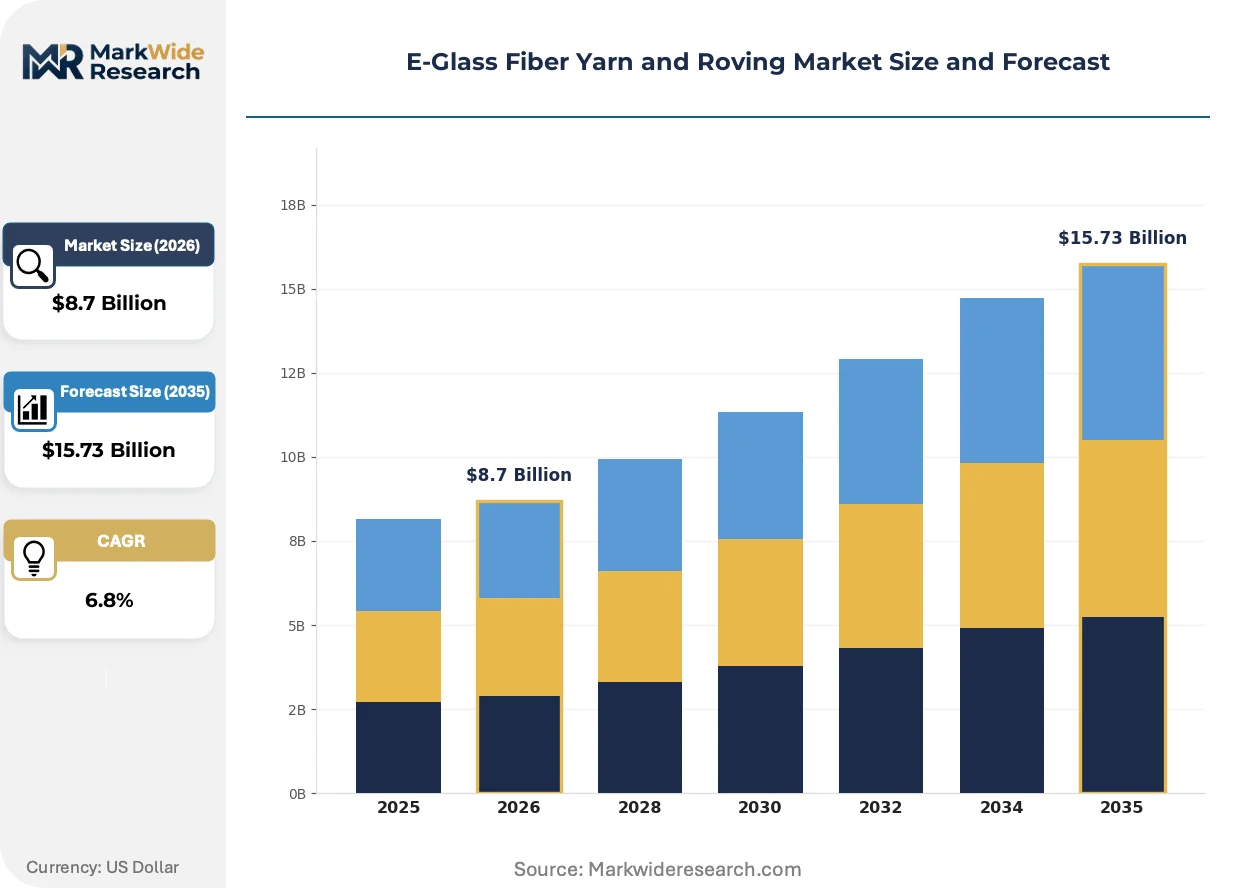
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yarn, Roving, Fabrics, Mats Technology: Continuous Filament, Chopped Strand, Braiding, Woven Application: Aerospace, Automotive, Construction, Marine End User: Manufacturers, OEMs, Suppliers, Contractors |
| Companies Covered | Chongqing Polycomp International Corp. (CPIC), Saint-Gobain Vetrotex, Owens Corning, Johns Manville, Nippon Electric Glass, Jushi Group, PPG Industries, Advanced Glassfiber Yarns, Taishan Fiberglass (Sinoma), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Glass Fiber Yarn and Roving Market Emerging Trajectories
Direct roving formats are displacing assembled roving in wind blade roots, while GB standards on composite recycling are forcing reformulation of sizing chemistry. These shifts are compressing the technology refresh cycle for melt operations and sizing development labs.
Automated guided tow placement systems are automating preform lay-up for wind turbine spar caps, eliminating manual roving handling that previously consumed 40% of blade manufacturing labor. Vestas and Siemens Gamesa are piloting these systems at blade facilities in Denmark and Spain. The technology is automating quality inspection through integrated laser profilometry that detects gaps and overlaps in real time.
China's updated GB standards on composite recycling mandate recoverable fiber content thresholds that tighten sizing chemistry specifications for E-glass bound for wind energy applications. SAMR enforcement is pushing roving producers to reformulate silane coupling agents that release cleanly during pyrolysis. European blade OEMs sourcing from Chinese suppliers are accelerating dual-certification testing to maintain EU REACH compliance alongside domestic requirements.
Blade OEMs are consolidating roving procurement through multi-year direct supply agreements that displace distributor intermediaries. Vestas and Goldwind are negotiating furnace-dedicated output from Jushi and CPIC facilities. This channel compression is most visible in offshore wind programs where qualification costs and volume guarantees favor captive supplier relationships over spot market purchasing.
E-Glass Fiber Yarn and Roving Market Segmentation
E-glass fiber markets fragment across reinforcement formats, manufacturing processes, and end-use specifications that dictate tensile performance requirements. Supplier qualification timelines and furnace investment priorities diverge sharply between volume-driven wind energy roving and premium aerospace yarn segments.
Product Type:
Volume concentration sits with heavy roving formats for wind blade manufacturing, while premium positioning clusters in precision yarn for aerospace prepregs.
- Yarn:Continuous filament bundles engineered for controlled tex counts and precise filament alignment, serving aerospace prepreg laminates where modulus consistency determines structural performance. Demand concentrates in thermoset prepregs for commercial aviation, with FAA certification timelines locking suppliers into 18-24 month qualification cycles that favor established melt operations.
- Roving:Untwisted parallel filament bundles fed directly into pultrusion and filament winding, dominating wind turbine blade root and spar cap production. Procurement is consolidating toward ultra-high tex formats that reduce lay-up labor, with direct supply agreements displacing distributor channels in offshore wind programs.
- Fabrics:Woven reinforcement sheets serving hand lay-up and vacuum infusion in marine hull construction. CPIC and Jushi facilities in Jiangsu supply export markets facing EU REACH boron restrictions.
- Mats:Chopped strand bundles bonded with powder or emulsion binders for closed mold automotive applications. Automated spray-up systems in bumper beam manufacturing are displacing manual handling.
Mature deployment sits with Roving. Newer deployment is concentrated in Mats.
Technology:
Cost tiering separates continuous filament furnace operations from secondary processing formats that add value through mechanical conversion.
- Continuous Filament:Direct melt-drawn filaments from platinum-rhodium bushings, yielding the highest tensile strength above 3,400 MPa. Owens Corning's North American furnace network anchors supply for blade OEMs requiring diameter tolerance below 1 micron.
- Chopped Strand:Mechanically cut filaments 3-50mm in length, bound with sizing chemistry for thermoplastics compounding. China's GB/T 18369 alkali content standards tighten as automotive underbody shield demand accelerates.
- Braiding:Interlaced yarn architectures producing tubular preforms for pressure vessel reinforcement. T700-grade carbon fiber substitution is eroding share in high-modulus applications exceeding 72 GPa.
- Woven:Interlaced warp and weft roving for biaxial and multiaxial fabrics in construction panel lamination. Jiangsu production clusters serve both domestic infrastructure and Middle East export contracts.
Established capacity concentrates in Continuous Filament. Capacity expansion is climbing the fastest in Chopped Strand.
Application:
Margin structure inverts between construction commodity reinforcement and aerospace qualification premiums.
- Aerospace:Prepreg and filament wound structures requiring FAA-certified yarn with full traceability from melt to laminate. The US FAA and EPA jointly influence certification and furnace emissions controls, creating compliance layering that favors multi-jurisdiction testing capabilities.
- Automotive:Lightweighting mandates under EU REACH boron restrictions favor compliant E-glass in electric vehicle battery enclosures and underbody shields. Thermoplastics compounding lines in Pune and Chennai are opening yarn demand as BIS certification aligns with automotive OEM requirements.
- Construction:Geogrids and reinforcing mesh for concrete and asphalt, competing with steel on installed cost. Natural gas price volatility at European melting furnaces is eroding margin in this price-sensitive segment.
- Marine:Hull laminates and deck structures facing EU REACH leaching restrictions on boron content. Boatbuilders in Spain and Italy are dual-certifying Chinese-sourced roving for domestic and export hull production.
Qualification intensity peaks in Aerospace. Volume scaling is gaining share fastest in Automotive.
End User:
Customer type determines contract structure, with OEM direct agreements compressing distributor margins.
- Manufacturers:Composite part fabricators purchasing roving and yarn for conversion into finished components. Vestas and Goldwind are negotiating furnace-dedicated output from Chinese suppliers, channel compression most visible in offshore wind.
- OEMs:Original equipment builders integrating composite structures into final products, driving specification compression toward ultra-high tex formats. Blade OEMs are consolidating procurement through multi-year direct supply agreements.
- Suppliers:Distributor and converter intermediaries facing margin pressure as channel compression accelerates. Spot market purchasing is retreating to construction and marine segments with fragmented demand.
- Contractors:Installation and field application specialists for construction geogrids and infrastructure rehabilitation. Labor availability constraints in North America and Europe limit project throughput.
Contract maturity sits with Manufacturers. Procurement restructuring is concentrating in OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of E-glass fiber output but Western markets consume specialized grades for aerospace and marine applications. This production-consumption divide shapes trade flows and regulatory compliance requirements across major economies.
China
Wind turbine blade manufacturing and thermoplastics compounding drive heavy roving procurement from Jiangsu and Shandong province clusters. SAMR enforces GB/T 18369 standards on alkali content and filament diameter consistency. Jushi Group and CPIC anchor supply commitments for domestic blade OEMs and export markets.
United States
Commercial aviation prepreg demand and wind energy blade production sustain aerospace-grade yarn consumption. The FAA and EPA jointly influence certification timelines and furnace emissions controls at melting operations. Owens Corning leverages its North American furnace network to serve blade manufacturers with diameter tolerance below 1 micron.
Germany
Automotive lightweighting for electric vehicle battery enclosures and construction geogrids shape E-glass formulation requirements. EU REACH restrictions on boron leaching favor compliant E-glass in automotive underbody shields. Industrial clusters in Bavaria and North Rhine-Westphalia process imported roving for domestic OEM supply chains.
India
Thermoplastics compounding lines in Pune and Chennai are adopting automated spray-up systems for bumper beam manufacturing. BIS certification alignment for automotive applications is opening yarn demand from domestic molding clusters. Maharashtra and Tamil Nadu serve as the primary consumption centers for imported roving formats.
Japan
Pressure vessel and electronics applications sustain demand for precision filament alignment and modulus consistency. METI oversees industrial standards that influence sizing chemistry specifications for domestic composite manufacturers. Kanto and Kansai regions concentrate downstream processing capacity for specialty yarn grades.
E-Glass Fiber Yarn and Roving Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across furnace operations and downstream conversion. The vendor base clusters around three strategic archetypes: integrated glass manufacturers with captive melt capacity, specialized roving converters serving wind energy OEMs, and regional distributors facing margin compression from direct procurement. Capacity expansion and multi-year supply agreements represent the dominant competitive moves as blade manufacturers consolidate vendor relationships.
Among integrated manufacturers, Owens Corning exemplifies the diversified conglomerate archetype with North American furnace assets, while Jushi Group represents the China-focused specialist with heavy roving concentration in offshore wind. CPIC occupies a position within the domestic distribution tier serving thermoplastics compounding demand across Jiangsu and Shandong production clusters.
| Leading Market Players |
|---|
| Chongqing Polycomp International Corp. (CPIC) |
| Saint-Gobain Vetrotex |
| Owens Corning |
| Johns Manville |
| Nippon Electric Glass |
| Jushi Group |
| PPG Industries |
| Advanced Glassfiber Yarns |
| Taishan Fiberglass (Sinoma) |
| Others |
Supply Flow & Price Mechanics
Natural gas price indices at European melting furnaces cascade through E-glass fiber supply chains into three distinct pricing tiers: aerospace-grade yarn commanding certification premiums, heavy roving for wind energy under volume pressure, and commodity chopped strand facing margin compression from automated compounding lines.
Pricing Analysis
Margin tightening in heavy roving reflects furnace-dedicated supply agreements that lock in multi-year pricing while compressing distributor markups. Three-tier pricing structure across aerospace-certified, wind-grade, and automotive commodity levels separates segments by filament diameter tolerance and GB/T 18369 compliance. Price differentiation hinges on platinum-rhodium bushing maintenance costs and SAMR certification timelines. Automotive underbody shield buyers exhibit highest price sensitivity; aerospace prepreg OEMs absorb premiums for FAA traceability.
Supply Chain Analysis
Skilled furnace operator scarcity in North America and Europe constrains melt capacity expansion despite wind blade demand acceleration. Manufacturing gravity centers on China, the United States, and Germany, with Jiangsu and Shandong clusters feeding global yarn output. Platinum-rhodium alloy bushings, boron-free aluminosilicate melt formulations, and silane sizing chemistry constitute critical input dependencies. Single-source vulnerability concentrates in GB-certified roving for aerospace qualification. Distribution runs through direct OEM procurement agreements that displace spot market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furnace capacity scarcity across North America and Europe props pricing power for incumbents with qualified melt operations, while Chinese overcapacity in standard grades intensifies margin pressure elsewhere.
For Market Incumbents: Deepen captive supply relationships with offshore wind blade OEMs through furnace-dedicated output commitments that preempt carbon fiber substitution in spar cap applications. Anchor backward integration into platinum-rhodium bushing refurbishment capabilities to offset skilled operator scarcity eroding melt consistency. For New Entrants and Emerging Players: Begin with BIS-certified yarn supply to Pune and Chennai automotive compounding clusters where incumbent presence remains thin. Penetrate India's thermoplastics sector through automated spray-up system partnerships that displace manual chopped strand handling in bumper beam manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale roving converters with GB/T 18369 certification and stranded wind energy customer relationships in Jiangsu province. Long-term viability hinges on blade recycling infrastructure deployment that reshapes sizing chemistry specifications. Watch for SAMR enforcement actions on composite recycling thresholds as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Capacity Expansion | Captive melt additions in Texas and South Carolina anchor Vestas and Goldwind supply commitments. |
| Backward Integration into Platinum-Rhodium Recycling | In-house bushing alloy recovery reduces dependency on South African and Russian primary supply. |
| Long-term Supply Agreement | Multi-year direct contracts with Siemens Gamesa displace distributor intermediaries in offshore wind. |
| Joint Venture for Blade Recycling | Mechanical shredding partnerships with Veolia position boron-free formulations for circular feedstock. |
| Green Manufacturing Transition | Electric furnace pilots in Norway align with EU Green Deal emissions benchmarks for marine exports. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with furnace operations managers, wind blade procurement leads, thermoplastics compounding directors, and SAMR certification specialists. Glass fiber production databases, GB/T 18369 audit reports, EU REACH compliance disclosures, and FAA material qualification records provided demand-side validation. Bottom-up segment sizing triangulated against top-down industry association aggregates.
Data-stream reconciliation across continuous filament throughput, chopped strand conversion rates, and end-use consumption patterns enabled projection modeling across the analysis window. Segmentation dimensions included reinforcement format, manufacturing technology, application sector, and end-user contract structure. CAGRs derived from trend extrapolation of furnace investment cycles and blade OEM procurement timelines, with sensitivity testing against natural gas price volatility and carbon fiber modulus benchmarks.
Underlying measurement precision varies by segment; aerospace yarn carries tighter precision than commodity construction grades due to FAA certification documentation density. Forecasts reflect assumptions on wind farm deployment trajectories under China's dual carbon goals and EU Green Deal implementation. Material deviation in SAMR recycling enforcement or platinum-rhodium supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market