
 North America Aramid Fiber Market | 2026-2036
North America Aramid Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aramid Fiber Market Analytics
Project finance for specialty chemical facilities is reconfiguring competitive entry barriers across the North America aramid fiber landscape. DuPont leverages its integrated para-aramid supply chain from polymer to finished fiber to sustain margin control. Teijin Aramid anchors its position through advanced meta-aramid formulations for thermal protection. Kolon Industries Inc. competes by specializing in cost-optimized para-aramid variants for industrial reinforcement.
Aramid fibers comprise aromatic polyamide chains with rigid molecular structures, typically exhibiting tensile strengths exceeding 3,000 MPa and thermal stability above 400°C, manufactured through dry-jet wet spinning of liquid crystalline solutions for ballistic protection, fire resistance, and structural reinforcement. Para-aramid dominates volume through defense and aerospace composites where strength-to-weight ratios command premium positioning. Meta-aramid captures margin pools in protective clothing and insulation where thermal stability requirements resist substitution. Polybenzimidazole occupies niche high-temperature filtration and semiconductor applications where extreme chemical resistance justifies specialized supply chains.
NHTSA flammability standards and FAA fire-blocking regulations in the United States, alongside OSHA workplace protection mandates, are elevating certified aramid content requirements across automotive seating, aircraft interiors, and industrial protective equipment. The EPA oversees chemical emissions from aramid polymerization facilities, constraining capacity expansion timelines and favoring producers with established environmental compliance infrastructure. Stakeholders must monitor evolving FAA reauthorization priorities and state-level clean manufacturing incentives to anticipate where certification burdens and cost advantages will shift across the value chain.
Market Dynamics
Defense procurement consolidation along the US Gulf Coast is compressing supplier margins while elevating certification requirements for ballistic-grade para-aramid. This geographic concentration of demand is forcing fiber producers to co-locate polymerization and spinning assets near military assembly plants.
Growth Catalysts
- FAA fire-blocking mandates:Aircraft interior retrofit programs across United States commercial aviation fleets are expanding meta-aramid content in seat assemblies and cabin partitions. Thermal barrier specifications now exceed previous generation requirements.
- Petrochemical cluster expansion:Louisiana and Texas industrial corridors are driving specialty fiber procurement for offshore platform mooring lines and refinery protective equipment. Energy sector capital deployment favors domestically sourced reinforcement materials.
- Advanced composite integration:Automated fiber placement systems for aerospace primary structures are enabling thicker aramid preform layups without manual labor bottlenecks. Boeing and Airbus tier suppliers in Wichita and Montreal are qualifying these processes.
Market Restraints
- Acrylonitrile cost volatility:Feedstock price swings for para-aramid polymerization constrain margin predictability for non-integrated producers. Gulf Coast petrochemical supply disruptions propagate directly into fiber economics.
- Single-source precursor dependence:Meta-phenylenediamine supply concentrates among three North American chemical manufacturers. Any production interruption cascades through the entire meta-aramid value chain.
- Ultra-high molecular weight polyethylene substitution:Ballistic armor procurement is evaluating hybrid vests combining UHMWPE with reduced aramid content. Law enforcement budget constraints favor lower-cost protection solutions.
Strategic Opportunities
- Canadian Arctic infrastructure:Cold-weather pipeline reinforcement and ice-resistant offshore cabling in Newfoundland and Labrador waters represent unserved demand for cryogenic-rated aramid composites.
- Electric vehicle battery enclosures:NHTSA thermal runaway protection standards are creating new specification categories for flame-resistant cell-to-pack barriers. Automotive tier suppliers are qualifying meta-aramid nonwovens.
- Recycling technology convergence:Depolymerization processes for end-of-life ballistic vests and aerospace scrap are unlocking circular feedstock streams. Joint development between fiber producers and chemical recyclers is advancing in Georgia and South Carolina.
Industry Challenges
- Spinneret engineering talent scarcity:Dry-jet wet spinning process optimization requires expertise in liquid crystalline solution rheology that has not transferred across generations of chemical engineers. DuPont and Teijin are competing for a limited pool of specialists.
- DoD MIL-SPEC recertification timelines:New para-aramid variants require 18-24 month qualification cycles for body armor insertion. Development costs accumulate without revenue during validation phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aramid Fiber Market |
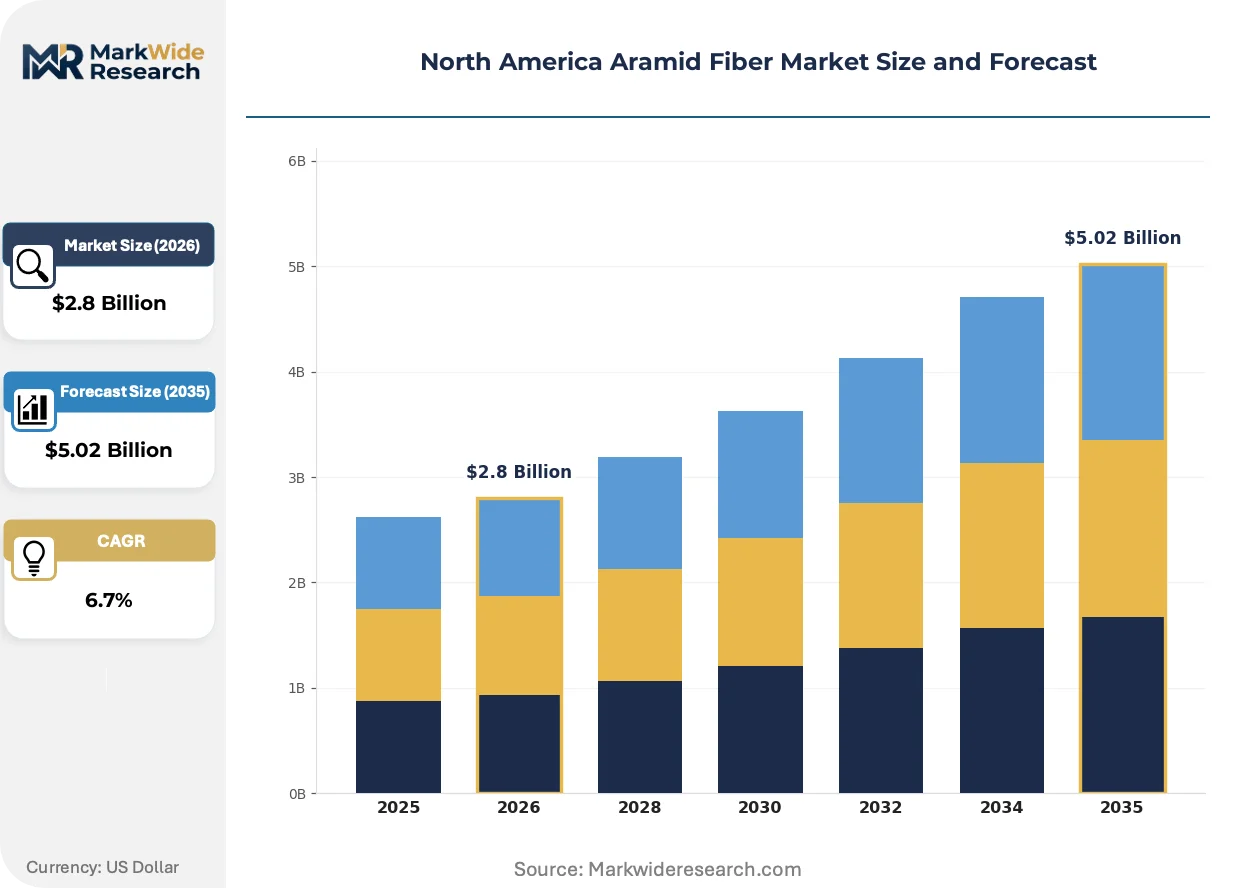
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Para-Aramid, Meta-Aramid, Polybenzimidazole, Others End User: Aerospace, Automotive, Electronics, Protective Clothing Application: Composites, Insulation, Reinforcement, Filtration Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Dupont, Teijin Aramid, HYOSUNG, Huvis Corp, TORAY INDUSTRIES, INC., Kolon Industries Inc., Aramid Hpm, LLC., Bally Ribbon Mills, KERMEL, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aramid Fiber Market Evolving Landscape
Material science advances and regulatory tightening are converging to redefine performance thresholds across defense, aerospace, and industrial protection applications. Fiber producers are repositioning around thermal-mechanical property combinations that resist commoditization.
Hybrid aramid-carbon fiber prepregs with tailored damage tolerance are rendering obsolete monolithic carbon layups in helicopter rotor hub assemblies. Sikorsky and Bell suppliers in Connecticut and Texas are transitioning production lines to these interlaced architectures. The shift compresses qualification timelines for secondary structural components while elevating raw material complexity.
NHTSA updated flammability standards for automotive seating materials are mandating 45-second flame resistance thresholds that conventional polyester foams cannot achieve. Seat manufacturers in Michigan and Ontario are integrating meta-aramid barrier fabrics between foam and upholstery. The regulatory pressure is accelerating specification convergence across North American vehicle platforms previously fragmented by regional sourcing preferences.
Consolidated procurement by defense prime contractors is displacing fragmented purchasing across military base supply chains. Raytheon and Lockheed Martin tier managers in Arizona and Massachusetts now specify fiber grades directly rather than delegating to subcontractors. The concentration of buying power is compressing supplier margins while rewarding producers with MIL-PRF-46100 certification breadth.
North America Aramid Fiber Market Segmentation
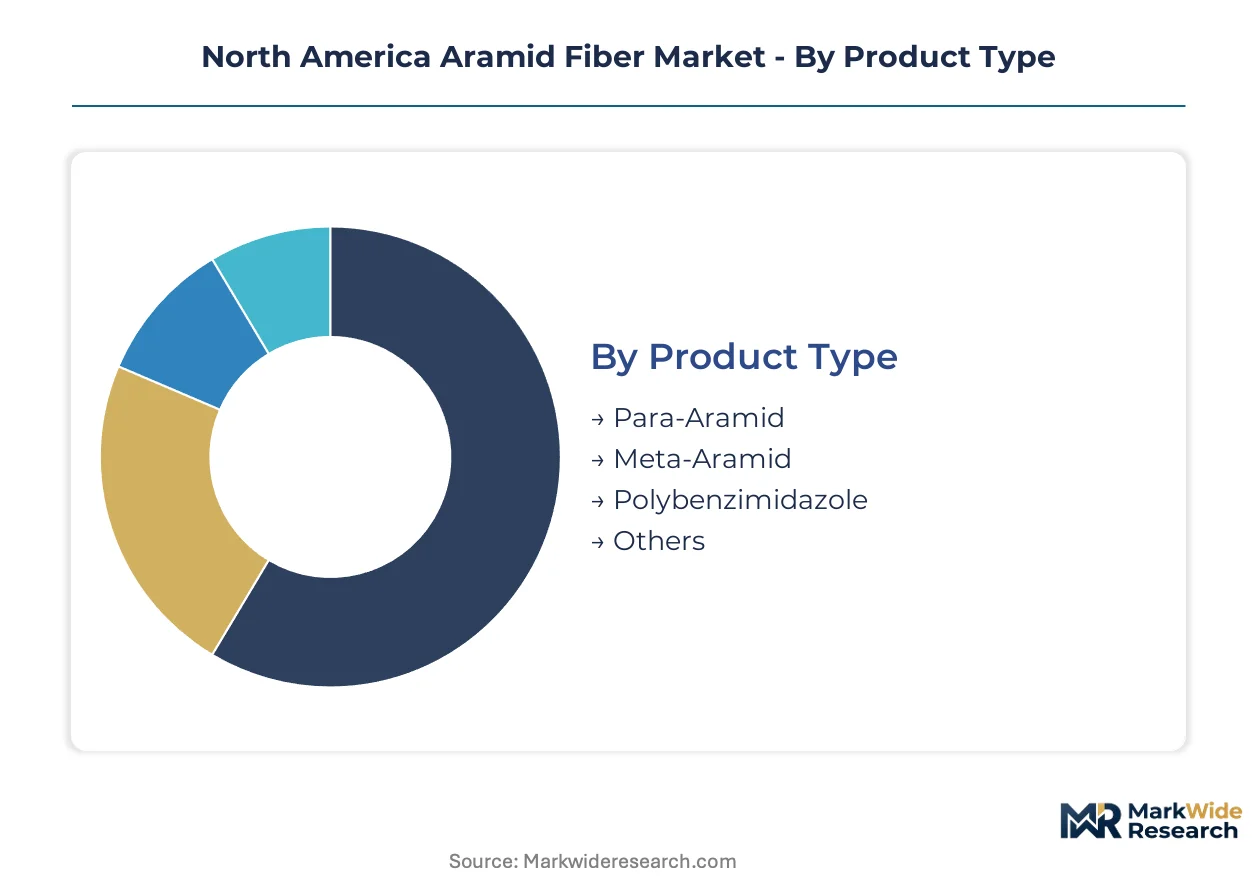
Segmentation reveals how aramid fiber value pools concentrate across molecular architectures, end-use specifications, and procurement channels. Each dimension carries distinct margin profiles, certification burdens, and technical service requirements that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across aramid chemistries, with para-aramid demanding ballistic certification support and meta-aramid requiring thermal testing documentation throughout product lifecycles.
- Para-Aramid:Rigid-rod molecular chains of poly-p-phenylene terephthalamide deliver tensile strength exceeding 3,000 MPa with modulus above 70 GPa. Demand concentrates in US Gulf Coast defense assembly corridors where DoD MIL-SPEC recertification cycles lock in supplier relationships. Acrylonitrile feedstock volatility compresses margins for non-integrated producers.
- Meta-Aramid:Poly-m-phenylene isophthalamide structures provide thermal stability above 400°C without the crystalline orientation of para variants. Protective clothing manufacturers in Michigan and Ontario drive procurement, with NHTSA automotive seating mandates expanding specification categories faster than aerospace applications.
- Polybenzimidazole:Heterocyclic aromatic polymer chains serve semiconductor fabrication and ultra-high-temperature filtration above 500°C.
- Others:Copolyaramids and modified aromatic polyamides occupy niche industrial belting and specialty rope applications.
Para-aramid holds the largest share; momentum sits with meta-aramid as thermal protection regulations tighten across transport sectors.
End User:
Cost tier stratification separates defense-aerospace premiums from automotive volume plays and industrial commodity procurement.
- Aerospace:Primary and secondary structural composites for commercial and military aircraft demand FAA fire-blocking certification with 45-second flame resistance thresholds. Wichita and Montreal tier suppliers qualify automated fiber placement systems for thicker aramid preform layups.
- Automotive:EV battery enclosure thermal barriers and seating fire-blocking layers represent the steepest expansion trajectory. NHTSA thermal runaway protection standards create new specification categories where meta-aramid nonwovens command price premiums over conventional barriers.
- Electronics:Printed circuit board substrates and cable insulation require dielectric stability with low moisture absorption.
- Protective Clothing:Firefighter turnout gear and industrial worker protection balance thermal ratings against wear comfort and laundering durability.
Aerospace captures the highest margin per kilogram; automotive offers the largest volume expansion pathway.
Application:
Application focus determines whether producers compete on mechanical property certification or chemical resistance specifications.
- Composites:Hybrid aramid-carbon fiber prepregs with tailored damage tolerance displace monolithic carbon layups in helicopter rotor hub assemblies. Sikorsky and Bell suppliers in Connecticut and Texas transition production lines to interlaced architectures.
- Insulation:Thermal barrier papers and felts for electrical equipment and aircraft interiors require controlled thickness uniformity. Meta-aramid dominates where 400°C continuous service ratings resist substitution.
- Reinforcement:Tire cord, hose reinforcement, and conveyor belting demand fatigue resistance under cyclic loading.
- Filtration:Hot gas filtration bags and liquid filtration media compete against PTFE and fiberglass alternatives.
Composites generate the most complex supply relationships; insulation offers the most predictable recurring revenue.
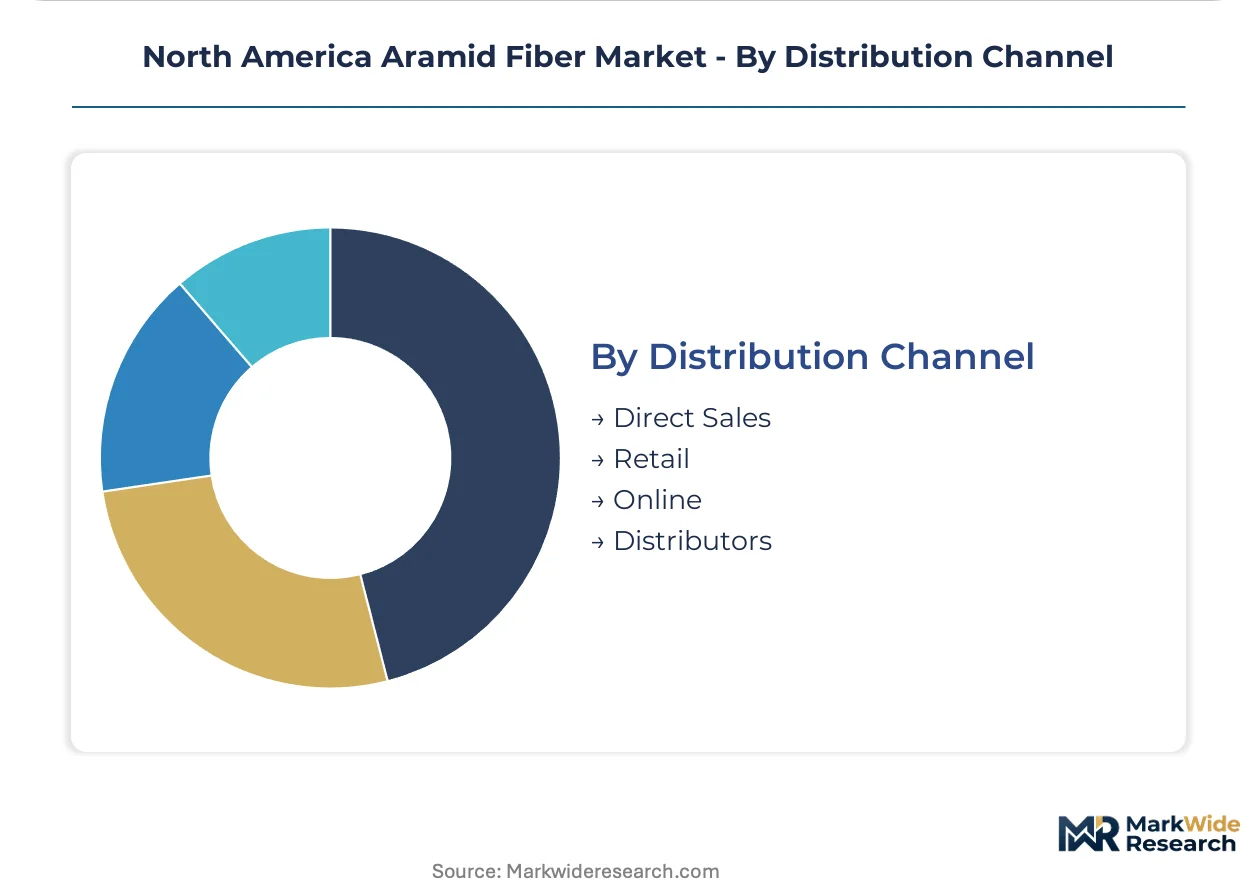
Distribution Channel:
Channel selection reflects order size, technical service requirements, and certification documentation burdens.
- Direct Sales:Defense prime contractors and aerospace OEMs specify fiber grades directly rather than delegating to subcontractors. Raytheon and Lockheed Martin tier managers in Arizona and Massachusetts consolidate procurement, compressing supplier margins while rewarding MIL-PRF-46100 certification breadth.
- Distributors:Industrial reinforcement and protective clothing applications rely on regional stocking distributors for smaller lot sizes and technical support.
- Retail:Specialty outdoor and tactical gear consumers access aramid through sporting goods and safety equipment retailers.
- Online:Commodity grades for hobbyist composites and small-scale industrial applications move through digital procurement platforms.
Direct sales dominate value capture; distributors handle the greatest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement incentives and state-level clean manufacturing credits are redistributing aramid fiber demand across North American industrial corridors. Regulatory tightening at the FAA and NHTSA level creates compliance premiums that favor domestic producers with established certification infrastructure.
United States
Defense procurement consolidation along the Gulf Coast compresses supplier margins while elevating MIL-SPEC requirements for ballistic-grade para-aramid. The FAA fire-blocking mandates for commercial aviation retrofit programs expand meta-aramid content in seat assemblies and cabin partitions. Wichita, Kansas and Hartford, Connecticut aerospace clusters qualify automated fiber placement systems for thicker aramid preform layups.
Canada
Cold-weather pipeline reinforcement and ice-resistant offshore cabling in Newfoundland and Labrador waters generate unserved demand for cryogenic-rated aramid composites. Health Canada workplace protection mandates tighten industrial safety equipment specifications. Montreal's aerospace tier suppliers integrate hybrid aramid-carbon fiber prepregs for Bell and CAE production lines.
Mexico
Automotive seating manufacturers in Querétaro and Guanajuato integrate meta-aramid barrier fabrics to meet NHTSA-equivalent export standards for US-bound vehicle platforms. The Secretariat of Economy's nearshoring incentives attract protective equipment fabricators to Baja California. Tijuana industrial parks host cut-and-sew operations for firefighter turnout gear serving California procurement contracts.
North America Aramid Fiber Market Competitive Landscape
On the supply side, the industry is consolidating around integrated polymer-to-fiber producers with captive acrylonitrile supply and established MIL-PRF certification breadth. Three strategic archetypes dominate: vertically integrated chemical conglomerates controlling upstream monomer production; specialized aramid spinners focusing on thermal protection formulations; and regional fabricators serving niche industrial reinforcement. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers co-locating spinning assets near defense assembly plants to compress logistics costs.
Within the integrated chemical conglomerate tier, DuPont and Teijin Aramid exemplify producers with backward control over polymerization inputs. Kolon Industries Inc. occupies a position among specialized para-aramid variants optimized for cost-sensitive industrial reinforcement. These three anchors represent divergent strategic postures: full-chain integration versus formulation specialization versus volume-driven cost positioning.
| Leading Market Players |
|---|
| Dupont |
| Teijin Aramid |
| HYOSUNG |
| Huvis Corp |
| TORAY INDUSTRIES, INC. |
| Kolon Industries Inc. |
| Aramid Hpm, LLC. |
| Bally Ribbon Mills |
| KERMEL |
| Others |
Value Network & Pricing Analysis
The US Gulf Coast petrochemical corridor's freight economics compress delivery premiums for acrylonitrile feedstock while amplifying price spreads between MIL-SPEC-certified para-aramid and commodity-grade industrial reinforcement. This logistics concentration rewards backward-integrated producers with captive monomer supply and punishes non-integrated spinners exposed to spot feedstock volatility.
Pricing Analysis
Certification level (MIL-PRF-46100 versus industrial grade) creates the primary spread between premium ballistic fiber and standard reinforcement tiers. Contract-based long-term offtake dominates defense procurement, while spot transactions govern industrial belting. Price differentiation rests on DoD recertification breadth and volume scale, with Gulf Coast defense primes least sensitive and Midwest industrial distributors most responsive to acrylonitrile cost swings. Margins are tightening due to UHMWPE substitution in law enforcement vests.
Supply Chain Analysis
Export-control restrictions on liquid crystalline polymer spinning technology limit equipment flows to Chinese and Russian defense programs. Supply concentrates in the United States, Japan, and South Korea, with meta-phenylenediamine precursors drawing from three North American chemical manufacturers. Single-source vulnerability cascades through meta-aramid value chains. Distribution runs through direct sales to Raytheon and Lockheed Martin tier managers, with regional distributors handling protective clothing lots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification support services and thermal testing documentation generate recurring revenue streams expanding faster than base fiber tonnage. After-sales service intensity separates sustainable margin pools from commodity trap segments.
For Market Incumbents: Build regulatory moats through accelerated MIL-SPEC recertification investments to lock out Korean cost-optimized entrants. Deepen backward integration into acrylonitrile polymerization along the Louisiana-Texas corridor. Capture channel control by co-locating spinning assets near Sikorsky and Bell assembly plants in Connecticut and Texas. For New Entrants and Emerging Players: Build out cryogenic-rated composite capabilities for Newfoundland and Labrador offshore cabling before incumbents qualify Arctic service ratings. Target EV battery enclosure thermal barriers in Michigan and Ontario where NHTSA standards outpace supplier certification. Pursue joint development agreements with Georgia and South Carolina chemical recyclers for circular feedstock positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming aramid divisions lacking defense certification breadth. Long-term viability hinges on regulatory compliance infrastructure rather than capacity scale. Watch FAA reauthorization priorities as the inflection signal for fire-blocking mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile | Captive feedstock supply insulates DuPont and Teijin from Gulf Coast petrochemical disruptions. |
| MIL-PRF-46100 Certification Expansion | Broad certification portfolios reward producers with consolidated Raytheon and Lockheed Martin procurement. |
| Arctic Composite Qualification | Cryogenic-rated formulations unlock unserved demand in Newfoundland and Labrador offshore infrastructure. |
| Depolymerization Joint Ventures | Circular feedstock partnerships in Georgia and South Carolina address EPA emissions constraints. |
| Automated Fiber Placement Integration | Thicker preform layups qualify Wichita and Montreal tier suppliers for Boeing and Airbus contracts. |
Research Methodology
A spread of perspectives from defense procurement officers, aerospace tier supplier engineers, petrochemical plant managers, and protective clothing manufacturers converged on the working assumptions. Primary interviews combined with secondary validation from FAA fire-blocking regulation filings, NHTSA safety standard updates, SEC 10-K disclosures, and US Gulf Coast customs trade data. Bottom-up fiber demand modeling and top-down chemical industry revenue triangulation anchored the analytical framework.
Demand-supply balance dynamics across para-aramid and meta-aramid grades shaped the projection horizon. Segmentation dimensions included molecular architecture, end-use certification tier, and regional procurement cluster. CAGRs derived from capacity utilization trends and defense budget allocation patterns. Forecast inputs incorporated DoD MIL-SPEC recertification timelines and NHTSA thermal runaway protection standard evolution.
Stress conditions across acrylonitrile price volatility, UHMWPE substitution rates, and FAA mandate acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about defense procurement consolidation and clean manufacturing incentive durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Spandex Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Melt Spun Fibers Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Synthetic Fiber Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
High-Strength Polyester Thread Market