
 Global Lidocaine Transdermal Patch Market | 2026-2036
Global Lidocaine Transdermal Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lidocaine Transdermal Patch Market Foresight
Silicone-based adhesives are displacing traditional acrylate backings in premium patch construction, which is realigning raw material cost structures and manufacturing yields across the industry. Hisamitsu Pharmaceutical leverages its vertically integrated adhesive film production to sustain margin advantages in matrix patch formats. Teva Pharmaceutical Industries competes through generic reservoir patch portfolios that anchor its position in hospital procurement channels. Pfizer differentiates via polymer matrix innovations that extend wear-time claims for neuropathic pain indications.
A lidocaine transdermal patch consists of a backing layer, drug reservoir or matrix, release liner, and pressure-sensitive adhesive formulated to deliver local anesthetic through intact skin at controlled rates, typically achieving therapeutic plasma concentrations within two to four hours of application. The patch serves primarily as an opioid-sparing intervention for localized pain conditions including postherpetic neuralgia and peripheral nerve disorders. Matrix patches dominate current volume owing to simpler manufacturing and lower unit costs, while polymer matrix variants represent the fastest-expanding category due to their enhanced drug-loading capacity and improved skin adhesion profiles. Home healthcare channels are capturing disproportionate growth as patients and payors favor self-administered chronic pain management outside institutional settings.
The FDA regulates lidocaine patches as combination products requiring adherence to Current Good Manufacturing Practice standards and specific bioequivalence protocols for abbreviated new drug applications. The EMA's Medical Device Regulation and the EU F-Gas framework indirectly shape patch economics through adhesive solvent restrictions and environmental compliance obligations for European manufacturers. Japan's PMDA maintains distinct pharmacovigilance requirements for transdermal systems that influence labeling and post-market surveillance intensity. Stakeholders must monitor evolving opioid-alternative reimbursement policies and adhesive material qualification timelines as determinants of competitive positioning in this market.
Market Dynamics
Silicone adhesive chemistry is forcing a wholesale reconfiguration of patch manufacturing economics, compressing legacy acrylate supply chains while elevating barrier-to-entry for new market entrants.
Growth Catalysts
- FDA Opioid Prescribing Guidelines:Tightened federal restrictions on systemic analgesics are redirecting chronic pain protocols toward lidocaine-based transdermal alternatives in US hospital systems and pain clinics.
- Japan's Aging Demographics:Concentrated demand from elderly population centers in Osaka and Tokyo is accelerating home healthcare adoption of self-administered neuropathic pain management.
- Polymer Matrix Technology:Enhanced drug-loading capacity and extended wear-time profiles in advanced matrix formats are displacing conventional reservoir designs in premium therapeutic segments.
Market Restraints
- Adhesive Raw Material Concentration:Medical-grade silicone supply chains cluster among Japanese and German specialty chemical producers, creating input vulnerability for matrix patch manufacturers.
- EMA F-Gas Compliance Burden:Solvent restrictions under the EU framework impose environmental qualification timelines that extend European manufacturing certification cycles.
- Systemic Analgesic Substitution:Oral gabapentinoids and topical diclofenac formulations retain formulary preference in cost-sensitive procurement channels.
Strategic Opportunities
- German Pain Clinic Expansion:Underpenetrated ambulatory care networks in Bavaria and North Rhine-Westphalia present channel development potential for non-opioid analgesic protocols.
- Home Healthcare Channel Maturation:Direct-to-patient distribution models and remote monitoring integration are capturing disproportionate volume growth outside institutional settings.
- PMDA Transdermal Streamlining:Japan's pharmacovigilance pathway revisions for established active ingredients are compressing post-market surveillance intensity for lidocaine systems.
Industry Challenges
- Bioequivalence Protocol Complexity:FDA abbreviated new drug application requirements for combination products demand specialized clinical pharmacology expertise that constrains generic development timelines.
- Adhesive Formulation Talent Scarcity:Pressure-sensitive adhesive chemistry specialization sits with a narrow cohort of formulation scientists, elevating R&D compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lidocaine Transdermal Patch Market |
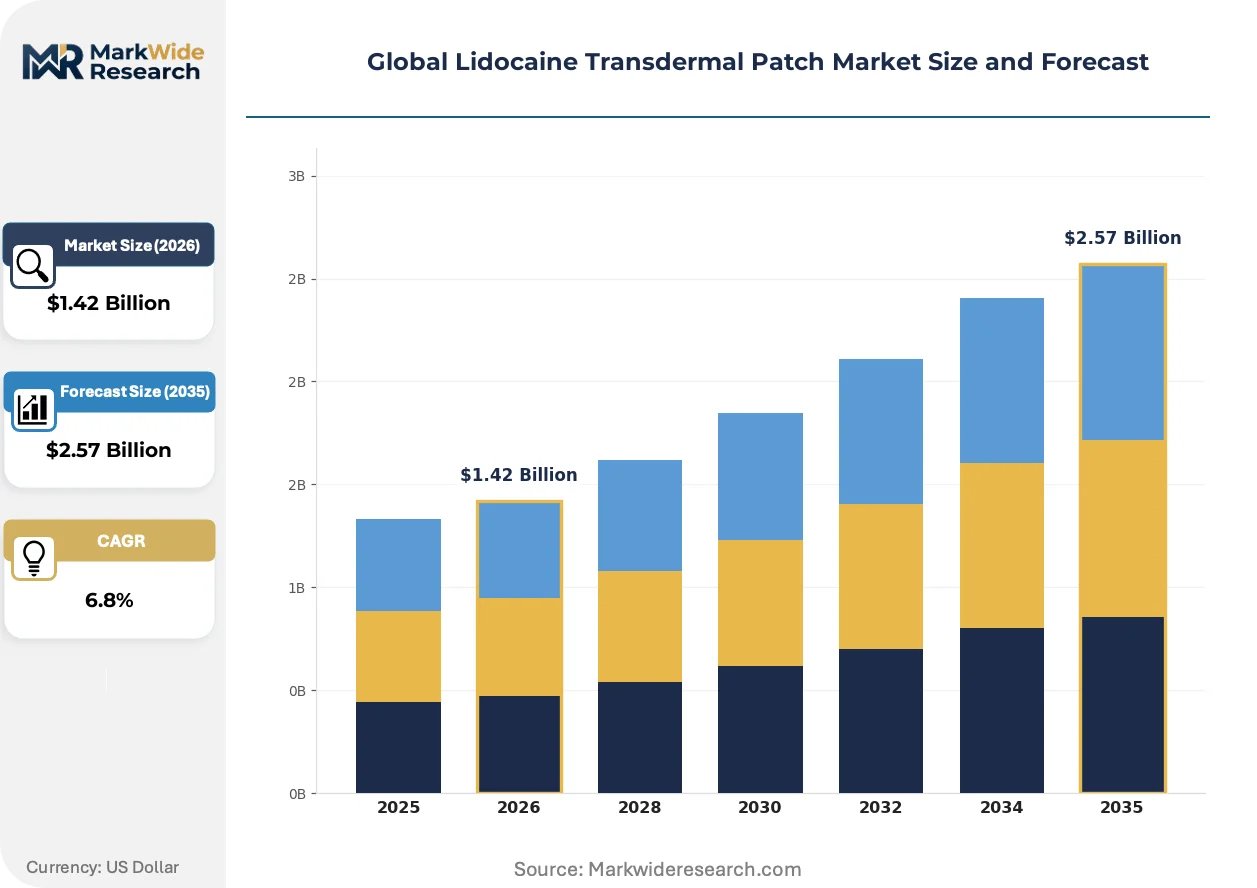
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Patch, Reservoir Patch, Matrix Patch, Polymer Matrix Patch Therapy Area: Neuropathic Pain, Postherpetic Neuralgia, Musculoskeletal Pain, Peripheral Nerve Pain End User: Hospitals, Pain Clinics, Ambulatory Surgical Centers, Home Healthcare Distribution Channel: Hospital Pharmacy, Retail Pharmacy, Online Pharmacy, Wholesale Distributors |
| Companies Covered | Hisamitsu Pharmaceutical Co., Inc., Teikoku Seiyaku Co., Ltd., Teva Pharmaceutical Industries Ltd., Pfizer Inc., Endo International plc, Viatris Inc., Novartis AG, Johnson & Johnson, Aurobindo Pharma Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lidocaine Transdermal Patch Market Shifts & Advancements
Matrix patch architecture is fragmenting into specialized sub-variants as manufacturers compete on wear-time claims and skin adhesion performance, compressing the competitive set around material science capabilities rather than scale economics alone.
Silicone-based pressure-sensitive adhesive systems are modularizing patch construction by enabling discrete functional layers that separate drug release control from skin adhesion mechanics. Pain clinics in Germany and the United States are adopting these constructions for neuropathic pain protocols requiring multi-day wear. This modularization is compressing traditional integrated-backbone designs into commodity positioning while elevating premium tier pricing power for differentiated formats.
REACH adhesive solvent restrictions and the EU F-Gas framework are imposing environmental compliance obligations that reshape European manufacturing economics. Solvent recovery systems and alternative coating technologies now absorb capital allocation previously directed toward capacity expansion. German and French manufacturers are responding with qualified solvent-free adhesive deposition processes that extend production qualification timelines but secure regional market access.
Hospital procurement is consolidating around outcome-based formulary contracts that unbundle patch acquisition from pain management protocol adherence metrics. Group purchasing organizations in the United States are displacing standalone product tenders with integrated therapeutic outcome agreements. This behavioral shift is most visible in North American health systems seeking to reduce systemic drug exposure while capturing opioid-sparing reimbursement incentives.
Global Lidocaine Transdermal Patch Market Segmentation
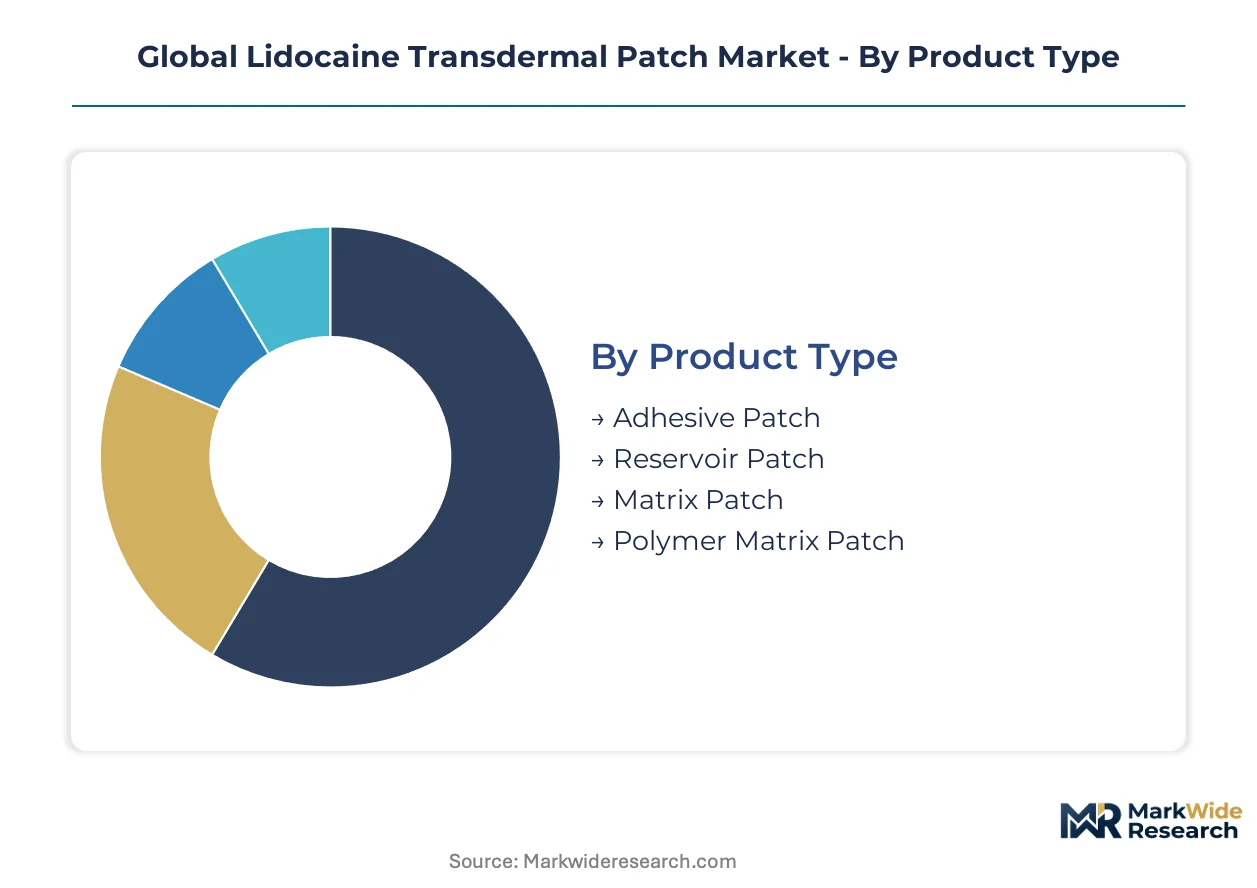
Patch architecture and therapy specialization create distinct competitive arenas where material science capabilities, regulatory pathways, and reimbursement structures diverge sharply. Manufacturers must align portfolio depth against specific channel access and clinical validation requirements.
Product Type:
Cost tier separates commodity formats from premium constructions that command formulary preference through extended wear-time claims.
- Adhesive Patch:Basic pressure-sensitive construction with lidocaine dispersed directly in adhesive layer. Demand concentrates in retail pharmacy channels across Germany and France where OTC accessibility drives volume turnover.
- Reservoir Patch:Liquid or gel drug compartment separated from skin by rate-controlling membrane. Pain clinics in the United States favor these systems for titratable dosing in postherpetic neuralgia protocols, though manufacturing complexity elevates unit costs.
- Matrix Patch:Drug uniformly distributed through solid polymer matrix without separate reservoir. Hospital procurement channels in Japan standardize on these formats for their simpler logistics and lower cold-chain requirements.
- Polymer Matrix Patch:Advanced copolymer systems with enhanced drug-loading capacity and multi-day adhesion profiles. Osaka and Tokyo pain centers are transitioning patients to these constructions for home-based neuropathic pain management.
Matrix Patch leads volumes today; Polymer Matrix Patch is gaining share fastest.
Therapy Area:
Application severity dictates reimbursement tier and prescriber specialty, concentrating margin in indication-specific clinical trials.
- Neuropathic Pain:Chronic nerve damage conditions including diabetic peripheral neuropathy. German ambulatory networks in Bavaria are expanding lidocaine protocols as first-line non-opioid intervention.
- Postherpetic Neuralgia:Persistent pain following herpes zoster infection with established FDA labeling. United States pain clinics prioritize this indication for prior authorization efficiency.
- Musculoskeletal Pain:Localized joint and soft tissue conditions. Retail pharmacy demand in France concentrates here for self-directed acute pain management.
- Peripheral Nerve Pain:Entrapment and trauma-related nerve compression. Japanese home healthcare channels capture disproportionate growth as elderly patients seek alternatives to systemic gabapentinoids.
Postherpetic Neuralgia anchors premium pricing; Neuropathic Pain is expanding most quickly across prescriber categories.
End User:
Customer type determines protocol adherence requirements and outcome measurement sophistication.
- Hospitals:Institutional procurement with integrated therapeutic outcome contracts. North American health systems are unbundling patch acquisition from pain management adherence metrics.
- Pain Clinics:Specialized ambulatory settings with protocol-driven prescribing. German networks in North Rhine-Westphalia present underpenetrated channel development potential.
- Ambulatory Surgical Centers:Procedure-focused settings requiring rapid-onset formulations. These facilities favor single-use reservoir designs for post-operative nerve block continuation.
- Home Healthcare:Direct-to-patient distribution with remote monitoring integration. Japan's aging population centers are accelerating adoption of self-administered multi-day wear systems.
Hospitals dominate current procurement volume; Home Healthcare is climbing the fastest as reimbursement shifts toward outpatient management.
Distribution Channel:
Supply concentration among qualified logistics providers shapes regional market access and inventory carrying costs.
- Hospital Pharmacy:Captive dispensing tied to formulary contracts and group purchasing organization agreements. United States systems are consolidating procurement around integrated therapeutic outcome frameworks.
- Retail Pharmacy:OTC and prescription counter access with pharmacist counseling. French and German chains are expanding shelf space for non-opioid alternatives.
- Online Pharmacy:Direct-to-patient fulfillment with prescription verification requirements. Japanese platforms are capturing elderly patient demand for recurring delivery schedules.
- Wholesale Distributors:Regional warehousing and cold-chain logistics for temperature-sensitive formulations. These intermediaries absorb EMA F-Gas compliance documentation burdens for European manufacturers.
Hospital Pharmacy leads transaction volume; Online Pharmacy is gaining share fastest through chronic patient subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka-based pharmaceutical manufacturing clusters anchor lidocaine patch production capacity, while regulatory divergence across FDA, EMA, and PMDA jurisdictions fragments standardization pathways.
United States
FDA abbreviated new drug application requirements for combination products compress generic development timelines. Hospital procurement consolidation around group purchasing organization agreements reshapes distribution economics. Pain clinics in Florida and Texas are expanding non-opioid protocols under tightened federal prescribing guidelines.
Germany
EMA F-Gas solvent restrictions extend manufacturing certification cycles for European producers. REACH adhesive compliance obligations absorb capital allocation previously directed toward capacity expansion. Bavarian and North Rhine-Westphalian ambulatory networks present underpenetrated channel development potential for lidocaine-based interventions.
Japan
PMDA pharmacovigilance pathway revisions for established active ingredients compress post-market surveillance intensity. METI standards influence transdermal system labeling requirements. Osaka and Tokyo pain centers are transitioning elderly patients to multi-day wear polymer matrix formats for home-based neuropathic pain management.
China
NMPA bioequivalence protocols for transdermal combination products demand specialized clinical pharmacology expertise. SAMR pricing oversight shapes hospital formulary access negotiations. Yangtze River Delta manufacturing clusters are absorbing technology transfer partnerships for matrix patch production.
Global Lidocaine Transdermal Patch Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers realign around material science capabilities rather than scale economics alone. The vendor base separates into three tiers: vertically integrated adhesive film producers, generic reservoir patch specialists, and polymer matrix innovators. Strategic archetypes include Japanese pharmaceutical conglomerates with captive silicone supply chains, Israeli-American generics houses anchoring hospital procurement, and diversified multinationals competing on extended wear-time claims. M&A activity and adhesive formulation talent acquisition represent the dominant competitive vectors reshaping positioning.
Among Japanese pharmaceutical conglomerates, Hisamitsu Pharmaceutical Co., Inc. and Teikoku Seiyaku Co., Ltd. exemplify the vertically integrated archetype with in-house adhesive film production capabilities. Teva Pharmaceutical Industries Ltd. occupies a position within the generic reservoir patch tier, while Pfizer Inc. anchors the polymer matrix innovation segment. These three entities collectively illustrate how geographic origin and corporate structure map to divergent competitive strategies in this market.
| Leading Market Players |
|---|
| Hisamitsu Pharmaceutical Co., Inc. |
| Teikoku Seiyaku Co., Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Endo International plc |
| Viatris Inc. |
| Novartis AG |
| Johnson & Johnson |
| Aurobindo Pharma Limited |
| Others |
Supply & Pricing Matrix
Group purchasing organizations in United States hospital systems anchor procurement volume and compress pricing power toward contract-based long-term offtake structures. Silicone adhesive cost pass-through from Japanese and German specialty chemical producers reshapes margin allocation across patch manufacturing tiers.
Pricing Analysis
Medical-grade silicone input costs pass through directly to patch manufacturers, with three-tier pricing structure across premium, standard, and economy levels stratifying by adhesive chemistry sophistication. Price differentiation centers on wear-time certification grade and cold-chain handling requirements. Pricing pressure stems from oral gabapentinoid substitution in cost-sensitive procurement channels. Retail pharmacy buyers in France exhibit highest price sensitivity, while United States pain clinics prioritize formulary adherence metrics over unit cost.
Supply Chain Analysis
Freight costs for temperature-sensitive adhesive films elevate landed costs for European manufacturers sourcing from Osaka-based production clusters. Supply concentrates in Japan, Germany, and the United States for medical-grade silicone polymers, release liners, and rate-controlling membranes. Raw material dependencies include silicone adhesive polymers, polyester backing films, and aluminum foil barrier layers. Single-source vulnerability concentrates in Japanese specialty chemical producers for pharmaceutical-grade silicone. Distribution runs through wholesale distributors absorbing EMA F-Gas compliance documentation for European market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand structures, with FDA opioid prescribing guideline revisions redirecting chronic pain protocols toward lidocaine-based transdermal alternatives.
For Market Incumbents: Extend polymer matrix innovation pipelines to capture home healthcare channel growth as Japanese elderly patients transition to self-administered multi-day wear systems. Deepen in-house silicone adhesive production capabilities to offset raw material concentration risk from Japanese and German specialty chemical suppliers. Secure outcome-based formulary contracts with United States group purchasing organizations before generic reservoir patch competition intensifies. For New Entrants and Emerging Players: Direct-to-patient online pharmacy platforms offer the most penetrable route for bypassing established hospital procurement barriers in Japan's aging population centers. Target Bavarian and North Rhine-Westphalian ambulatory networks in Germany where lidocaine protocols remain underpenetrated. Lead with polymer matrix formats differentiated by extended wear-time claims to avoid commodity positioning against Teva's generic reservoir portfolios. For Investors and Strategic Acquirers: Japanese pharmaceutical conglomerates with captive silicone supply chains are the most active acquirer in this space, seeking adhesive formulation talent to fill capability gaps. The five-to-ten year viability window favors targets with vertically integrated film production and established PMDA regulatory pathways. Monitor FDA abbreviated new drug application approval velocity for generic reservoir patches as an inflection indicator for pricing compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Adhesive Backward Integration | Captive supply of medical-grade polymers insulates margin from Japanese specialty chemical pricing volatility. |
| PMDA Pharmacovigilance Streamlining | Reduced post-market surveillance intensity accelerates polymer matrix patch lifecycle management in Osaka and Tokyo. |
| GPO Outcome-Based Contracting | United States hospital systems unbundle patch acquisition from pain management adherence metrics. |
| Solvent-Free Coating Qualification | German manufacturers absorb extended EMA F-Gas certification cycles to secure regional market access. |
| Home Healthcare Channel Partnership | Remote monitoring integration captures disproportionate volume growth outside institutional settings in Japan. |
Research Methodology
Bottom-up home healthcare channel modeling reconciled against top-down silicone adhesive supply tracking forms the analytical core of this study. Primary interviews with formulary directors, pain clinic physicians, hospital procurement managers, and adhesive formulation scientists combined with secondary validation from FDA filings, EMA submissions, PMDA pharmacovigilance databases, and hospital GPO contract repositories. Triangulation between prescriber-level demand signals and raw material supply capacity ensures segmentation integrity.
Input-output matrix framing connects polymer matrix patch production capacity to end-user adoption rates across therapy areas. Segmentation dimensions modeled include patch architecture type, therapy indication, end-user setting, and regional regulatory cluster. CAGRs derive from reconciling bottom-up prescription volume trajectories against top-down manufacturer capacity announcements. Forecast inputs incorporate PMDA pathway revision timelines and FDA abbreviated new drug application approval velocity assumptions.
The model assumes a particular technology adoption path; alternative pathways for silicone-based modular patch architectures would alter the outlook for acrylate-backed legacy formats. Forecasts reflect assumptions about opioid-alternative reimbursement policy stability and adhesive material qualification timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Montelukast Sodium Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Warts Therapeutics Market