
 Naproxen Market | 2026-2036
Naproxen Market Size, Share, and Industry Trends Forecast 2026-2036
Naproxen Market Foresight
Hospital procurement is bifurcating as home care and self-administration channels capture greater volume share. Teva Pharmaceutical Industries Ltd. leverages its generic portfolio depth to sustain formulary positioning across North American and European retail pharmacies. Jiangxi Tianxin Pharmaceutical Co., Ltd. anchors cost-competitive API supply to Indian and European formulators. Bayer AG differentiates through consumer-branded OTC naproxen sodium lines that command shelf space in major retail chains.
Naproxen is a propionic acid-derived nonsteroidal anti-inflammatory drug (NSAID) with a molecular weight of 230.26 g/mol, functioning as a non-selective cyclooxygenase inhibitor for pain, inflammation, and fever management. Tablet formulations dominate volume due to manufacturing simplicity and patient familiarity, while suspension formats address pediatric and geriatric populations with swallowing difficulties. Pain Management therapy areas generate the largest revenue pool, though Rheumatoid Arthritis segments attract premium pricing for sustained-release and combination therapies. Retail distribution channels remain the primary volume pathway, though online channels are gaining traction where telehealth prescribing has expanded.
The FDA enforces stringent dissolution and bioequivalence standards for generic naproxen through its Office of Generic Drugs, while the EMA's Committee for Medicinal Products for Human Use monitors cardiovascular risk labeling across the European Union. India's CDSCO aligns with ICH Q3D guidelines for elemental impurities, pushing domestic API producers toward upgraded purification infrastructure. Stakeholders must monitor evolving pharmacovigilance requirements for NSAID cardiovascular and gastrointestinal risk profiles as regulators weigh benefit-risk recalibrations.
Market Dynamics
Home care consumption and direct-to-patient channels are compressing traditional hospital procurement volumes while elevating quality mandates from FDA and EMA around impurity profiling and bioequivalence standards. This structural shift is forcing API manufacturers to upgrade purification infrastructure and reformulate distribution strategies.
Growth Catalysts
- Telehealth prescribing expansion:Digital health platforms in the United States are generating prescription volumes that bypass traditional clinic channels, accelerating direct-to-patient fulfillment models for chronic pain management.
- EMA cardiovascular risk labeling harmonization:Standardized benefit-risk frameworks across European Union member states are reducing regulatory fragmentation for sustained-release formulations, streamlining multi-market launches.
- Hyderabad-Ahmedabad API clusters:India's contract research and bulk drug production infrastructure supplies cost-competitive active pharmaceutical ingredients to regulated markets, concentrating manufacturing scale in these cities.
Market Restraints
- Elemental impurity compliance costs:India's CDSCO alignment with ICH Q3D guidelines is forcing domestic API producers toward capital-intensive purification upgrades, squeezing margin structures for mid-tier manufacturers.
- Single-source API concentration:European formulators remain dependent on Indian and Chinese bulk drug supplies, creating vulnerability to export license delays and geopolitical trade friction.
- Cardiovascular risk substitution:Selective COX-2 inhibitors and non-pharmacological pain interventions are capturing physician preference in geriatric populations, constraining naproxen volume growth in risk-averse prescribing environments.
Strategic Opportunities
- Pediatric suspension formulations:Underpenetrated dosing formats for swallowing-difficult populations present white space for geriatric and pediatric specialists seeking differentiated product lines.
- PLI scheme API incentives:India's production-linked incentive scheme for bulk drugs offers tax benefits and capital subsidies for greenfield manufacturing investments, attracting domestic capacity expansion.
- Online pharmacy channel penetration:Direct-to-consumer platforms in Germany and the United Kingdom are capturing prescription fulfillment volumes previously routed through brick-and-mortar retail chains.
Industry Challenges
- Dissolution method development talent:FDA bioequivalence standards require specialized analytical chemists capable of designing discriminating dissolution profiles, creating recruitment bottlenecks for generic sponsors.
- Legacy ERP integration:Track-and-trace serialization mandates from multiple regulators are forcing formulators to reconfigure warehouse management systems, generating implementation delays and validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naproxen Market |
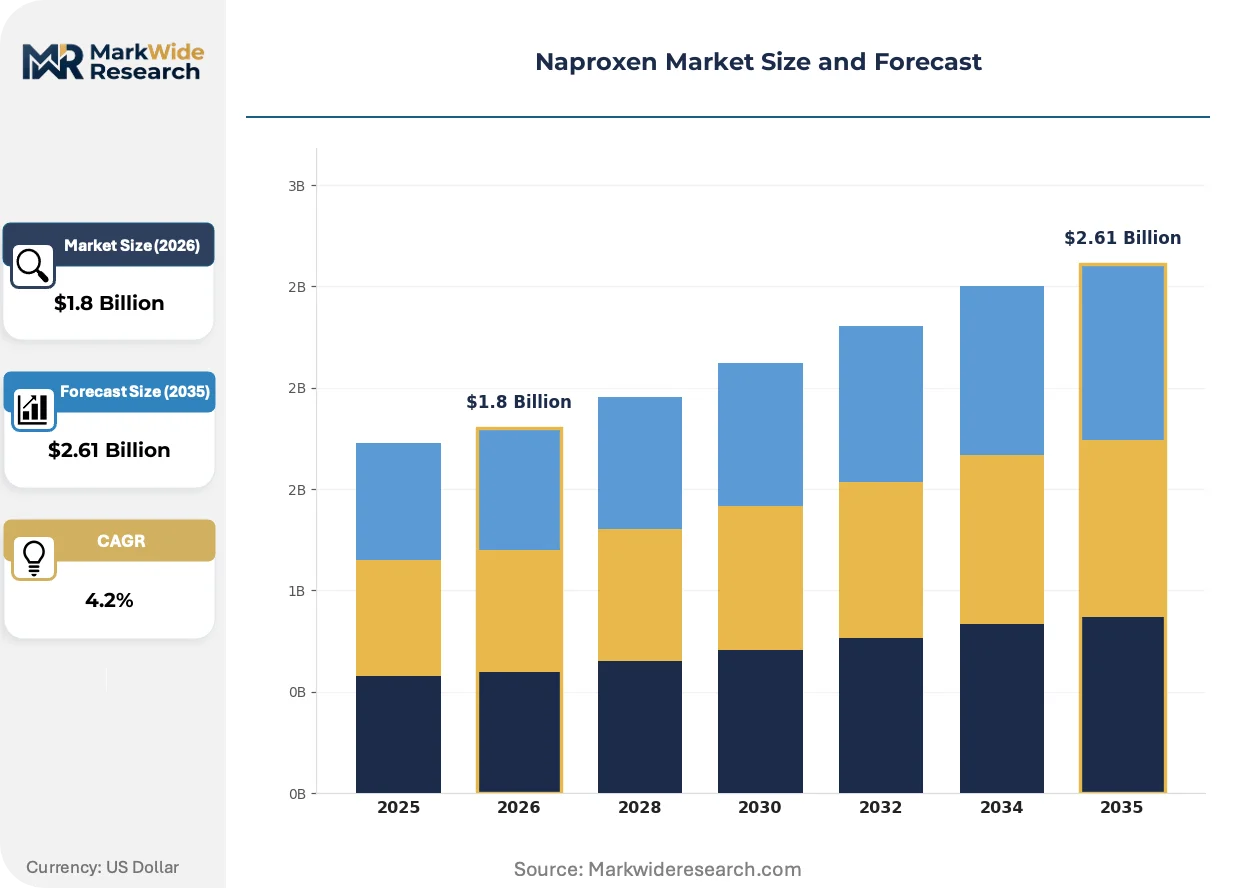
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Suspension, Injection Therapy Area: Inflammatory Disorders, Pain Management, Osteoarthritis, Rheumatoid Arthritis End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Dr. Reddy's Laboratories Ltd., Divi's Laboratories Ltd., Johnson & Johnson, Jiangxi Tianxin Pharmaceutical Co., Ltd., Huazhong Pharmaceutical Co., Ltd, Teva Pharmaceutical Industries Ltd., Aurobindo Pharma Ltd., Zhejiang Charioteer Pharmaceutical Co., Ltd., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naproxen Market Shifts & Advancements
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times while regulatory convergence around elemental impurity standards is harmonizing quality benchmarks across major markets. These developments are reshaping competitive differentiation from scale economies toward technical compliance capabilities.
Continuous direct compression systems are fragmenting traditional wet granulation workflows in tablet manufacturing. Mid-size formulators in Italy and Spain are adopting these platforms to reduce cleaning validation burdens and enable smaller batch sizes for niche markets. This technology is fragmenting the historical advantage of high-volume batch producers, enabling regional players to compete on flexibility rather than scale.
REACH registration requirements for pharmaceutical intermediates are tightening supply chain documentation obligations for European formulators sourcing APIs from non-EU manufacturers. The industrial consequence is accelerated supplier qualification timelines and elevated third-party audit costs. Generic sponsors in Germany and France are responding by consolidating vendor panels and demanding pre-registered intermediate streams from Indian suppliers.
Self-administration preferences among arthritis patients are displacing clinic-dependent injection therapies with oral NSAID regimens in home care settings. Retail pharmacies in the United States and United Kingdom are capturing this volume through automated refill programs and adherence packaging services. This behavioral shift is most visible in Medicare Part D and NHS England prescribing data, where 90-day supply dispensing for chronic pain indications has expanded substantially.
Naproxen Market Segmentation
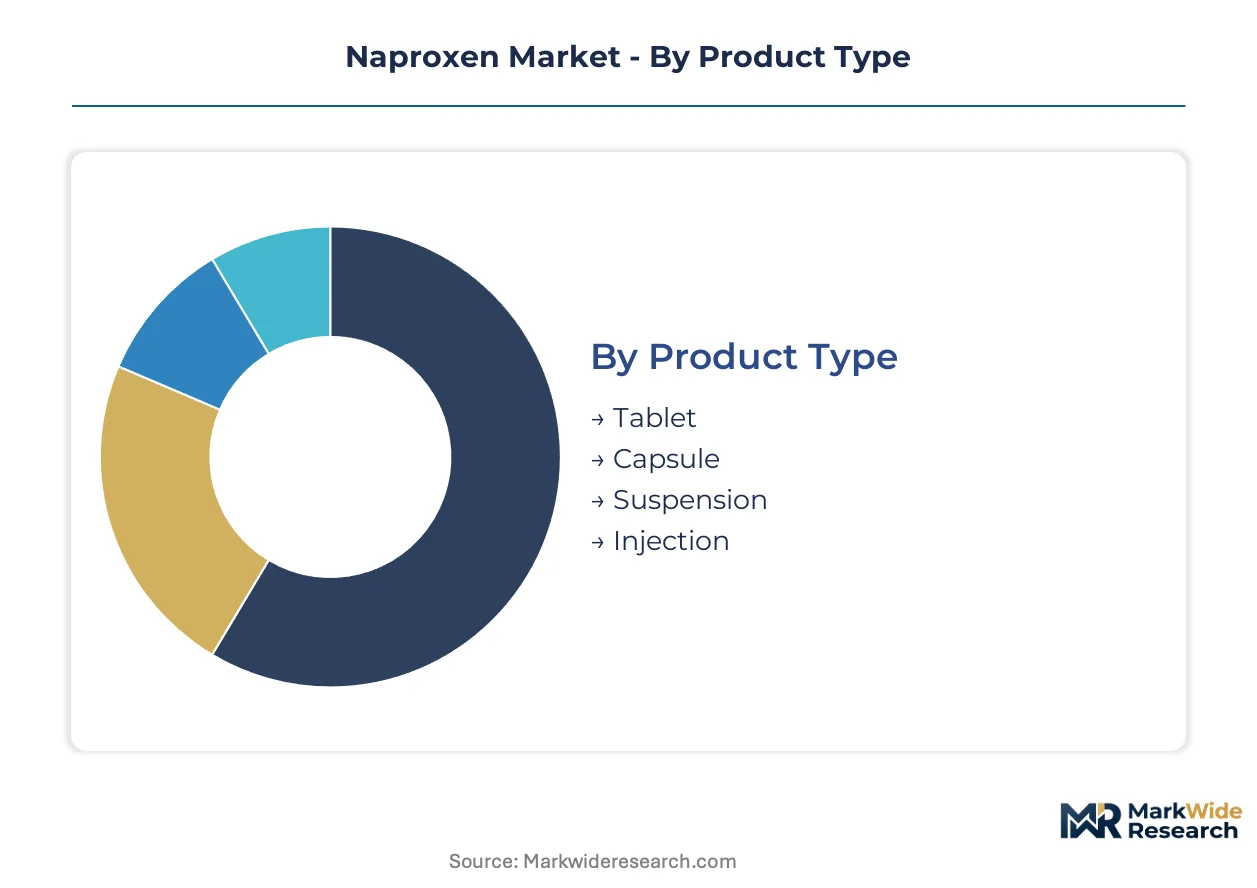
Naproxen market dynamics fragment sharply across formulation formats and care settings. Channel economics and reimbursement pathways determine which segments capture volume versus margin.
Product Type:
Tablet formulations flow predominantly through retail pharmacy and online channels, while suspension and injectable formats concentrate in hospital and home care settings with specialized handling requirements.
- Tablet:Direct compression manufacturing enables high-volume production with minimal processing steps. Demand concentrates in North American and European retail pharmacies where 90-day supply dispensing for chronic pain management has expanded under Medicare Part D and NHS England frameworks.
- Suspension:Liquid formulations incorporate viscosity modifiers and flavor masking systems for pediatric and geriatric populations with swallowing difficulties. Home care settings in Germany and the United Kingdom are capturing this volume through automated refill programs and adherence packaging services.
- Capsule:Gelatin shell encapsulation offers dose flexibility and gastric protection through enteric coating options. Compounding pharmacies in the United States utilize capsule formats for customized strength adjustments.
- Injection:Parenteral formulations require sterile manufacturing infrastructure and cold chain distribution. Hospital procurement channels maintain preference for acute post-surgical pain management where oral bioavailability is compromised.
Tablet dominates installed base. Suspension is where expansion concentrates.
Therapy Area:
Cost tier stratification separates acute episodic treatment from chronic disease management, with sustained-release formulations commanding premium positioning in Rheumatoid Arthritis.
- Pain Management:Acute musculoskeletal and post-operative pain indications drive the largest prescription volumes. Retail channels in the United States and United Kingdom capture this demand through over-the-counter naproxen sodium lines and generic prescription fulfillment.
- Rheumatoid Arthritis:Chronic autoimmune inflammation requires long-term NSAID therapy with gastroprotective co-therapy. Rheumatology specialists in France and Germany prefer sustained-release formulations with documented cardiovascular safety profiles.
- Osteoarthritis:Degenerative joint disease in aging populations generates steady demand for combination therapies with proton pump inhibitors. Medicare Part D data shows expanding 90-day supply dispensing for this indication.
- Inflammatory Disorders:Broader autoimmune and soft-tissue inflammatory conditions utilize naproxen as first-line or adjunct therapy. Prescribing patterns vary by national formularies and step-therapy protocols.
Pain Management captures the highest prescription volumes. Rheumatoid Arthritis is climbing the fastest on a value basis.
End User:
Volume concentration is accelerating in patient-directed settings while institutional procurement faces reimbursement compression.
- Home Care:Self-administration preferences among arthritis patients are displacing clinic-dependent injection therapies. Telehealth prescribing in the United States generates prescription volumes that bypass traditional clinic channels entirely.
- Pharmacies:Community and retail pharmacy networks remain the primary dispensing node for acute and chronic therapy. Automated refill programs in the United Kingdom capture recurring demand for maintenance therapy.
- Hospitals:Inpatient and surgical settings utilize injectable and high-dose oral formulations for acute pain management. Procurement teams face formulary pressure from generic substitution mandates.
- Clinics:Outpatient rheumatology and pain management practices initiate therapy before transferring stable patients to pharmacy-based refill models.
Home Care is gaining share fastest. Pharmacies retain the deepest installed base.
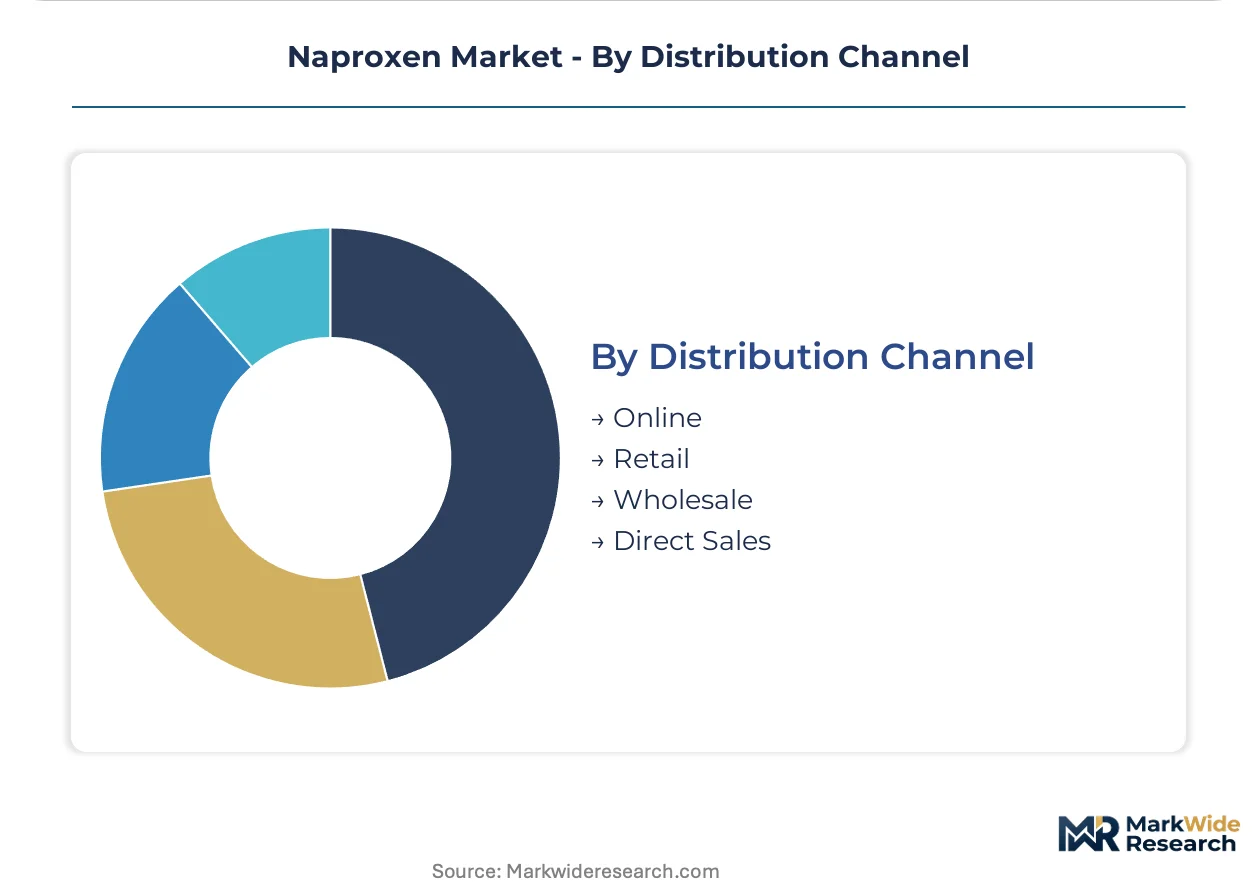
Distribution Channel:
Margin structure varies dramatically by channel, with direct-to-patient models capturing adherence value and wholesale retaining scale economies.
- Retail:Brick-and-mortar pharmacy chains command shelf space for OTC naproxen sodium lines and generic prescription fulfillment. Major chains in the United States negotiate formulary positioning through volume commitments.
- Online:Direct-to-consumer platforms in Germany and the United Kingdom are capturing prescription fulfillment volumes previously routed through retail chains. Telehealth integration enables seamless prescribing-to-delivery workflows.
- Wholesale:Distributor networks supply institutional and independent pharmacy accounts with inventory management and cold chain services for temperature-sensitive formulations.
- Direct Sales:Manufacturer-to-institution contracts serve hospital systems and managed care organizations with customized packaging and 340B pricing programs in the United States.
Retail maintains the broadest geographic footprint. Online is where steepest expansion trajectory is visible.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API manufacturers export bulk naproxen sodium to European formulators and North American generic sponsors, with Hyderabad-Ahmedabad production clusters supplying regulated markets under FDA and EMA quality mandates.
United States
Telehealth prescribing platforms generate prescription volumes bypassing traditional clinic channels entirely. The FDA enforces stringent dissolution and bioequivalence standards through its Office of Generic Drugs, elevating compliance costs for sponsors. Retail pharmacy chains in the United States negotiate formulary positioning through volume commitments for OTC naproxen sodium lines.
Germany
Direct-to-consumer online platforms capture prescription fulfillment volumes previously routed through brick-and-mortar retail chains. EMA cardiovascular risk labeling harmonization reduces regulatory fragmentation for sustained-release formulations. Rheumatology specialists in Germany prefer sustained-release naproxen with documented cardiovascular safety profiles for chronic autoimmune therapy.
India
Contract research and bulk drug production infrastructure supplies cost-competitive APIs to regulated markets worldwide. CDSCO alignment with ICH Q3D guidelines pushes domestic producers toward upgraded purification infrastructure. Hyderabad and Ahmedabad manufacturing clusters concentrate production scale for export-oriented naproxen API supply.
United Kingdom
Automated refill programs and adherence packaging services capture recurring demand for maintenance therapy in home care settings. NHS England prescribing data shows expanding 90-day supply dispensing for chronic pain indications. Online pharmacy penetration in the United Kingdom accelerates direct-to-patient fulfillment models integrated with telehealth workflows.
China
Domestic formulators source intermediates from specialized chemical manufacturers serving pharmaceutical applications. NMPA regulations govern drug registration and manufacturing quality standards for local production. Zhejiang and Jiangxi provinces host API and intermediate producers supplying both domestic formulators and export markets.
Naproxen Market Competitive Landscape
Listed leaders compete with private specialists across generic formulation and API supply tiers. The vendor base spans multinational pharmaceutical corporations, Indian bulk drug manufacturers, and Chinese chemical intermediates producers. Three archetypes dominate: vertically integrated generics majors with retail pharmacy reach, API specialists supplying regulated markets under contract, and consumer health divisions marketing branded OTC lines. Competitive moves concentrate on M&A for portfolio depth and capacity expansion in Indian production clusters.
Among Israeli-listed generics majors, Teva Pharmaceutical Industries Ltd. occupies a position exemplifying formulary breadth across North American and European retail channels. Indian API and formulation specialists anchor cost-competitive supply, with Dr. Reddy's Laboratories Ltd. and Aurobindo Pharma Ltd. representing the contract manufacturing archetype serving regulated markets. German diversified healthcare conglomerate Bayer AG exemplifies the consumer-branded OTC strategy, commanding shelf space through sodium salt formulations in major retail chains.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories Ltd. |
| Divi's Laboratories Ltd. |
| Johnson & Johnson |
| Jiangxi Tianxin Pharmaceutical Co., Ltd. |
| Huazhong Pharmaceutical Co., Ltd |
| Teva Pharmaceutical Industries Ltd. |
| Aurobindo Pharma Ltd. |
| Zhejiang Charioteer Pharmaceutical Co., Ltd. |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Continuous manufacturing adoption is displacing traditional wet granulation workflows, simultaneously pulling production scale toward mid-size Italian and Spanish formulators while compressing batch-premium pricing for legacy high-volume manufacturers. This technology substitution fragments historical supply geography and forces price recalibration across tablet manufacturing tiers.
Pricing Analysis
Generational technology gaps separate continuous direct compression platforms from legacy wet granulation batch systems and emerging real-time release testing integrations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade against FDA bioequivalence standards and volume scale commitments from retail pharmacy chains. Pricing pressure stems from elemental impurity compliance costs under ICH Q3D guidelines squeezing mid-tier API manufacturers. Hospital procurement teams exhibit highest price sensitivity due to formulary substitution mandates, while consumer-branded OTC lines command lowest sensitivity through shelf-space premiums.
Supply Chain Analysis
Inbound logistics costs through Mumbai-Jawaharlal Nehru Port and Mundra Port corridors influence API landed costs for European formulators sourcing from Indian suppliers. Supply concentrates in India, China, and the United States for bulk naproxen sodium API and finished formulations. Raw material dependencies rest on propionic acid derivatives, specialized solvents, and gelatin excipients for capsule shells. Single-source API concentration creates vulnerability to export license delays from CDSCO regulatory actions. Distribution runs through wholesale distributor networks supplying institutional and independent pharmacy accounts with inventory management services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities emerge as home care consumption and direct-to-patient channels displace traditional hospital procurement, creating niche entry points for specialized formulation players outside incumbent retail pharmacy networks.
For Market Incumbents: Consolidate formulary positioning through backward integration into API supply and acquisition of pediatric suspension specialists. Teva Pharmaceutical Industries Ltd.'s generic portfolio depth faces pressure from Indian contract manufacturers expanding into regulated markets; defend through CDSCO-aligned purification infrastructure investments and 90-day supply dispensing contracts with Medicare Part D plans.
For New Entrants and Emerging Players: Differentiate on pediatric and geriatric suspension formulations for swallowing-difficult populations, the most penetrable white space in current tablet-dominated supply. Target automated refill program partnerships with United Kingdom home care services as primary go-to-market angle, leveraging telehealth prescribing integration for direct-to-patient fulfillment bypassing retail chain gatekeepers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian API specialists possessing Hyderabad-Ahmedabad production clusters and FDA establishment inspection histories. Long-term viability hinges on regulatory compliance capabilities rather than scale economies alone. Watch EMA cardiovascular risk labeling harmonization progress as inflection indicator for sustained-release formulation premium pricing sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Italian and Spanish formulators compress batch cycle times against legacy high-volume producers. |
| API Purification Infrastructure Upgrade | CDSCO ICH Q3D alignment forces capital deployment toward elemental impurity compliance. |
| Pediatric Formulation Development | Geriatric and pediatric specialists capture underpenetrated suspension demand in home care settings. |
| Telehealth Platform Integration | Direct-to-patient fulfillment models bypass traditional clinic and retail pharmacy channels. |
| PLI Scheme Capacity Expansion | India's production-linked incentives attract greenfield bulk drug investments for export markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads at API manufacturers, formulary directors at retail pharmacy chains, and CDSCO compliance officers; and secondary validation through FDA Office of Generic Drugs filings, EMA Committee for Medicinal Products for Human Use assessments, and CMS Medicare Part D dispensing data. Bottom-up volume triangulation from formulation batch records and top-down value estimation from wholesale distributor invoices were cross-referenced against trade flow documentation.
Across the projection horizon, the analytical framework modeled segmentation across dosage form, therapy area, distribution channel, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of prescription volume growth and pricing trajectory analysis. Forecast inputs incorporated telehealth prescribing expansion rates, ICH Q3D compliance cost pass-through assumptions, and continuous manufacturing adoption curves among mid-size European formulators.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA regulatory convergence, stable India-EU trade lane access, and continued Medicare Part D 90-day supply reimbursement would require recalibration. Forecasts reflect documented assumptions regarding cardiovascular risk labeling stability and generic substitution mandate intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Norway Pharmaceutical Market