
 Benzodiazepine Drugs Market | 2026-2036
Benzodiazepine Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Benzodiazepine Drugs Market Analysis
Modular dosing kits that pair benzodiazepine vials with pre-filled syringes are rebalancing hospital procurement toward bundled anesthesia-sedation packages. Pfizer Inc. leverages its injectable manufacturing scale to dominate institutional channels. Teva Pharmaceutical Industries Ltd. anchors the generic oral tablet segment through vertically integrated API production. F. Hoffmann-La Roche Ltd. differentiates via legacy brand strength in psychiatric specialty clinics.
Benzodiazepine drugs comprise a class of psychoactive compounds structurally derived from fused benzene and diazepine rings, typically formulated as tablets, injectable solutions, or sublingual films with half-lives ranging from short-acting triazolam to long-acting diazepam, primarily prescribed for GABA-receptor-mediated CNS depression in anxiety management, procedural sedation, and seizure termination. The alprazolam product type occupies the largest revenue pool due to panic disorder labeling, while lorazepam injection leads parenteral delivery mode growth through emergency department seizure protocol standardization. Anxiety disorders indication sustains the deepest prescriber penetration, though insomnia applications face erosion from non-benzodiazepine hypnotics.
The FDA's REMS requirements for certain extended-release formulations and the DEA's Schedule IV controlled-substance quotas jointly constrain production volumes while elevating compliance costs. The EMA's PRAC signal assessments on dependence and withdrawal further narrow European label expansions. Stakeholders must monitor evolving pharmacovigilance mandates that could redirect R&D investment toward abuse-deterrent formulation platforms.
Market Dynamics
The FDA's boxed warning mandate for concurrent opioid-benzodiazepine prescribing is restructuring clinical protocols and procurement criteria across emergency departments and psychiatric institutions. This regulatory pressure is compressing legacy prescribing patterns while elevating documentation and monitoring requirements.
Growth Catalysts
- Emergency Department Protocol Standardization:Seizure management algorithms at US trauma centers now specify lorazepam injection as first-line intervention, embedding parenteral benzodiazepines into institutional formularies.
- DEA Schedule IV Quota Adjustments:The US Drug Enforcement Administration's production volume allocations for alprazolam and diazepam APIs sustain controlled-substance supply security against shortage risks.
- Chronic Anxiety Prevalence:Diagnostic expansion of generalized anxiety disorder in American primary care settings sustains long-acting agent utilization despite hypnotic segment erosion.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Benzodiazepine API synthesis clusters in Indian and Chinese chemical manufacturing zones, exposing finished-dose producers to geopolitical supply interruptions.
- EMA Pharmacovigilance Constraints:The European Medicines Agency's PRAC signal assessments on dependence and withdrawal syndromes block label expansions for extended-release formulations across EU member states.
- Non-Benzodiazepine Hypnotic Substitution:Z-drugs and melatonin receptor agonists displace benzodiazepine prescriptions in insomnia indications, compressing the sleep-disorder addressable market.
Strategic Opportunities
- Abuse-Deterrent Formulation Platforms:Polymeric matrix technologies that resist crushing or dissolution present white-space R&D investment for manufacturers seeking differentiation in the US controlled-substance landscape.
- Ambulatory Surgery Center Expansion:Procedural sedation demand at freestanding ASCs in Texas and Florida creates channel diversification beyond hospital emergency departments.
- Japan's Aging Demographic:METI-supported geriatric mental health initiatives elevate benzodiazepine utilization for anxiety and agitation management in institutional eldercare settings.
Industry Challenges
- REMS Compliance Infrastructure:FDA Risk Evaluation and Mitigation Strategy requirements for certain extended-release products demand specialized distribution and prescriber certification systems that strain mid-scale generic manufacturers.
- Pharmacovigilance Workforce Scarcity:Signal detection and periodic safety update report preparation for benzodiazepine portfolios requires scarce regulatory science specialists, elongating compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzodiazepine Drugs Market |
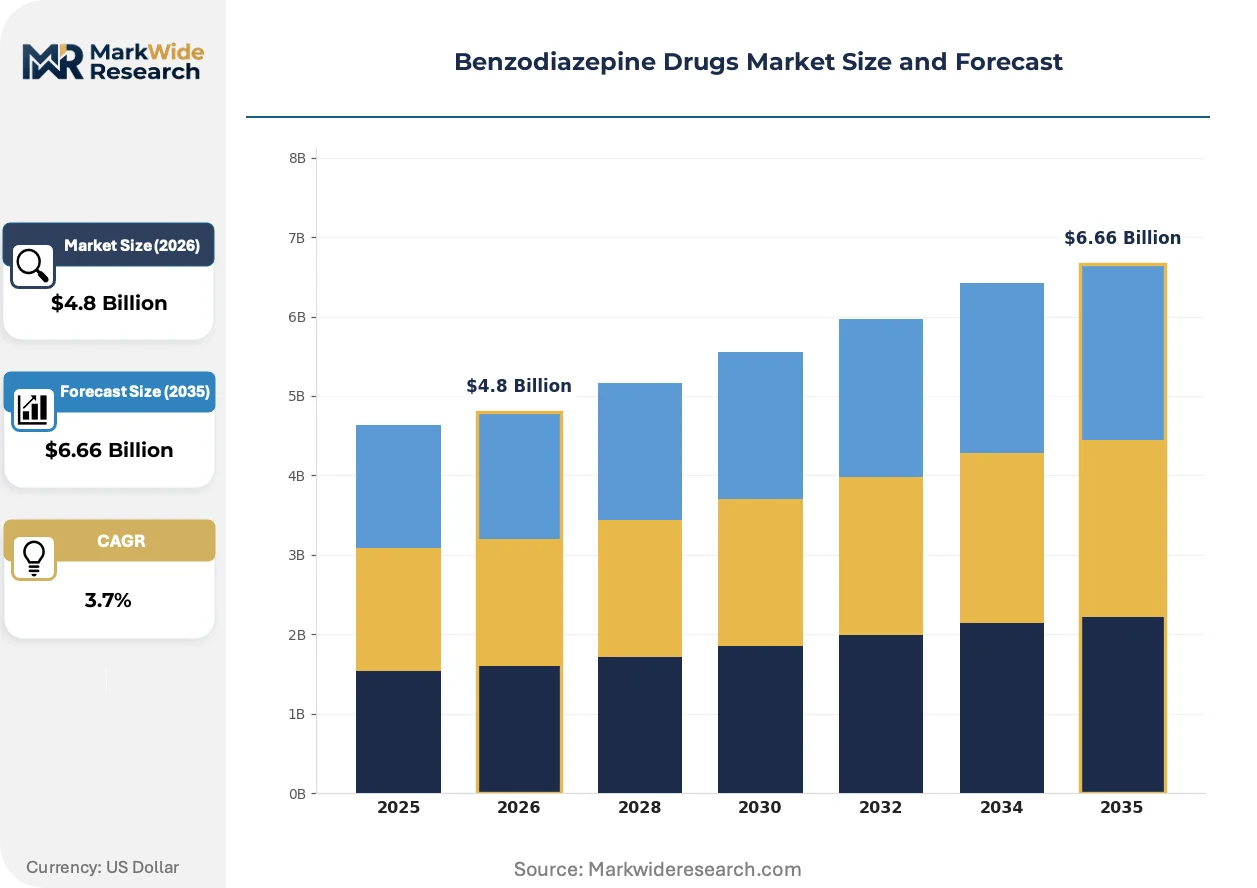
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diazepam, Lorazepam, Clonazepam, Alprazolam Indication: Anxiety Disorders, Insomnia, Muscle Spasms, Seizure Disorders Delivery Mode: Oral, Injection, Topical, Sublingual Patient Type: Adults, Seniors, Pediatric, Pregnant Women |
| Companies Covered | Pfizer Inc., AbbVie Inc., Teva Pharmaceutical Industries Ltd., Boehringer Ingelheim International GmbH, Sun Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd., Amneal Pharmaceuticals LLC., Bausch Health Companies Inc., GlaxoSmithKline Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzodiazepine Drugs Market Emerging Trajectories
Formulation engineering and digital therapeutics convergence are fragmenting traditional benzodiazepine delivery paradigms while regulatory surveillance intensifies post-market accountability requirements.
Prefilled syringe systems paired with vial-based dosing kits are modularizing hospital anesthesia-sedation procurement into bundled package contracts. Emergency department pharmacy directors at US academic medical centers are adopting these configurations to streamline inventory management and reduce compounding errors. This standardization is compressing vendor diversity while elevating manufacturing scale requirements for institutional suppliers.
The EMA's PRAC signal assessment framework on benzodiazepine dependence and withdrawal syndromes is narrowing European label expansion pathways for extended-release formulations. Pharmaceutical sponsors now face elongated benefit-risk review timelines that redirect development investment toward abuse-deterrent platforms or non-benzodiazepine mechanisms. Psychiatric specialty clinics in Germany and France are responding by intensifying non-pharmacological intervention protocols to reduce long-term benzodiazepine exposure.
Hospital formulary committees are consolidating anesthesia-sedation purchasing through centralized procurement consortia that unbundle legacy distributor relationships. These buying collectives at US health systems are negotiating direct manufacturer contracts for parenteral benzodiazepines, bypassing wholesale intermediaries. The concentration is most visible in the Southeast and Midwest, where multi-hospital networks command volume discounts that reshape competitive access dynamics.
Benzodiazepine Drugs Market Segmentation
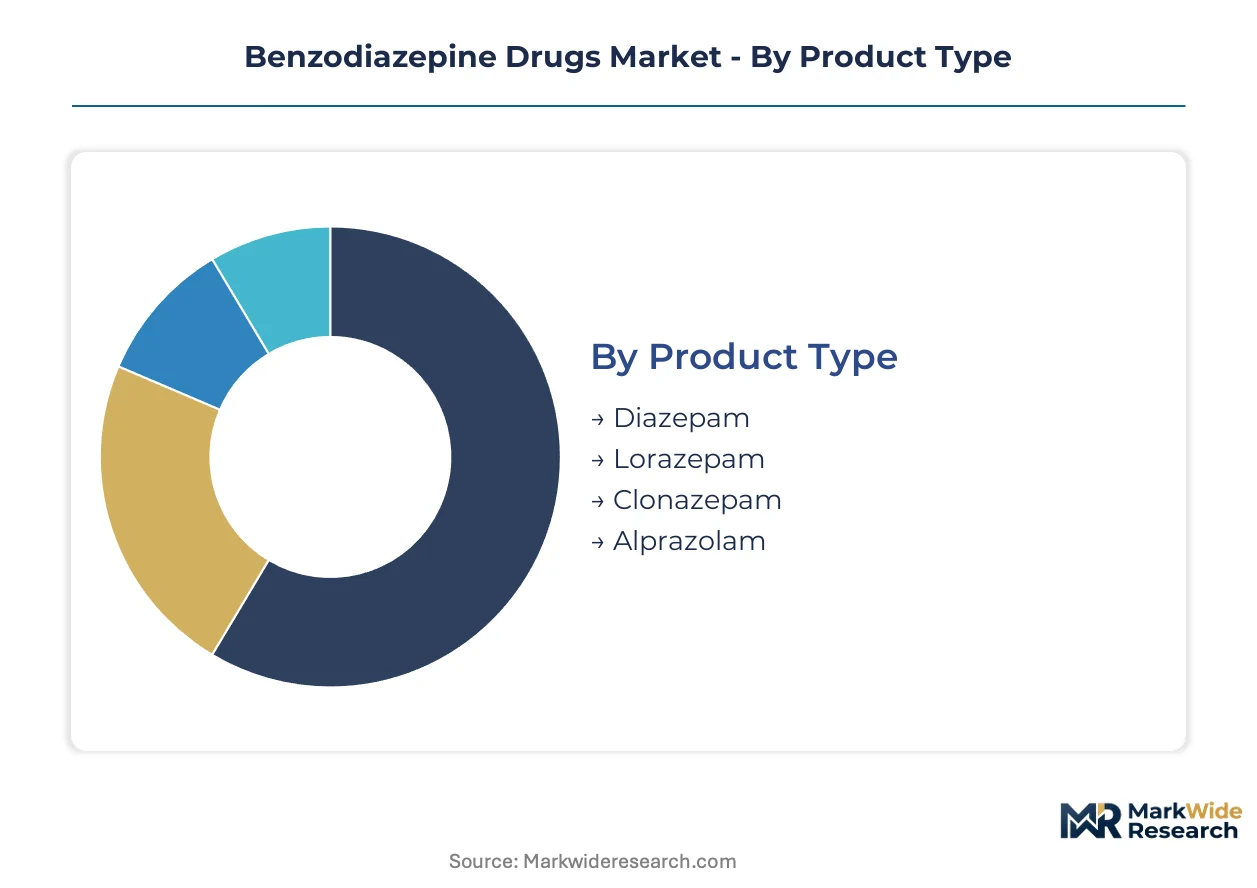
Segmentation in the benzodiazepine market reveals how formulation choices and patient risk profiles reshape procurement patterns across institutional and retail channels. Prescribing protocols diverge sharply between emergency seizure management and chronic anxiety maintenance, creating distinct competitive arenas.
Product Type:
Standalone oral tablets dominate chronic therapy, while injectable formats embed into hospital emergency protocols as integrated sedation systems.
- Alprazolam:Rapid-onset anxiolytic with intermediate half-life optimized for panic disorder protocols. US psychiatric clinics and primary care networks in Texas and Florida sustain volume through chronic generalized anxiety maintenance, though FDA boxed warnings on opioid co-prescribing compress new-patient starts.
- Lorazepam:Water-soluble benzodiazepine formulated for both oral and parenteral delivery with predictable metabolism independent of hepatic oxidation. Emergency departments at US academic medical centers embed lorazepam injection into first-line status epilepticus algorithms, anchoring institutional formulary placement.
- Diazepam:Long-acting classic benzodiazepine with active metabolite accumulation suited for tapering protocols.
- Clonazepam:High-potency agent with serotonergic modulation used in seizure prophylaxis and movement disorders.
Volume placements concentrate in alprazolam; the faster expansion belongs to lorazepam injection.
Indication:
Cost tier stratification separates acute intervention reimbursements from chronic maintenance prescribing economics.
- Anxiety Disorders:Primary therapeutic application spanning generalized anxiety, panic disorder, and social phobia with established GABA-A receptor agonism. US primary care settings in the Southeast and Midwest sustain the deepest prescriber penetration, though diagnostic expansion faces scrutiny from CDC opioid-benzodiazepine interaction alerts.
- Seizure Disorders:Acute termination of status epilepticus and chronic epilepsy adjunct therapy with rapid CNS penetration requirements. Level I trauma centers across California, New York, and Illinois standardize lorazepam injection in pre-hospital and ED protocols, embedding parenteral formats into critical care formularies.
- Insomnia:Hypnotic indication facing displacement from non-benzodiazepine GABA modulators and melatonin agonists.
- Muscle Spasms:Spasticity management in multiple sclerosis and cerebral palsy with limited label expansion.
Revenue concentration sits with anxiety disorders; seizure applications are climbing the fastest.
Delivery Mode:
Patient risk profiles and procedural settings dictate format selection across the care continuum.
- Injection:Parenteral formulation enabling rapid bioavailability for emergency seizure termination and procedural sedation. Ambulatory surgery centers in Texas and Florida are expanding lorazepam and midazolam injection procurement for endoscopy suites, diversifying demand beyond hospital emergency departments.
- Oral:Tablet and capsule formats for chronic outpatient management with dose-titration flexibility. Retail pharmacy chains across the US dispense alprazolam and clonazepam tablets under DEA Schedule IV quotas, with CVS and Walgreens capturing volume through 90-day maintenance prescriptions.
- Sublingual:Rapid absorption format for acute panic episodes without swallowing requirement.
- Topical:Transdermal and rectal gel preparations for pediatric and geriatric populations with compliance challenges.
Oral tablets retain volume dominance; injection formats are gaining share fastest through ASC expansion.
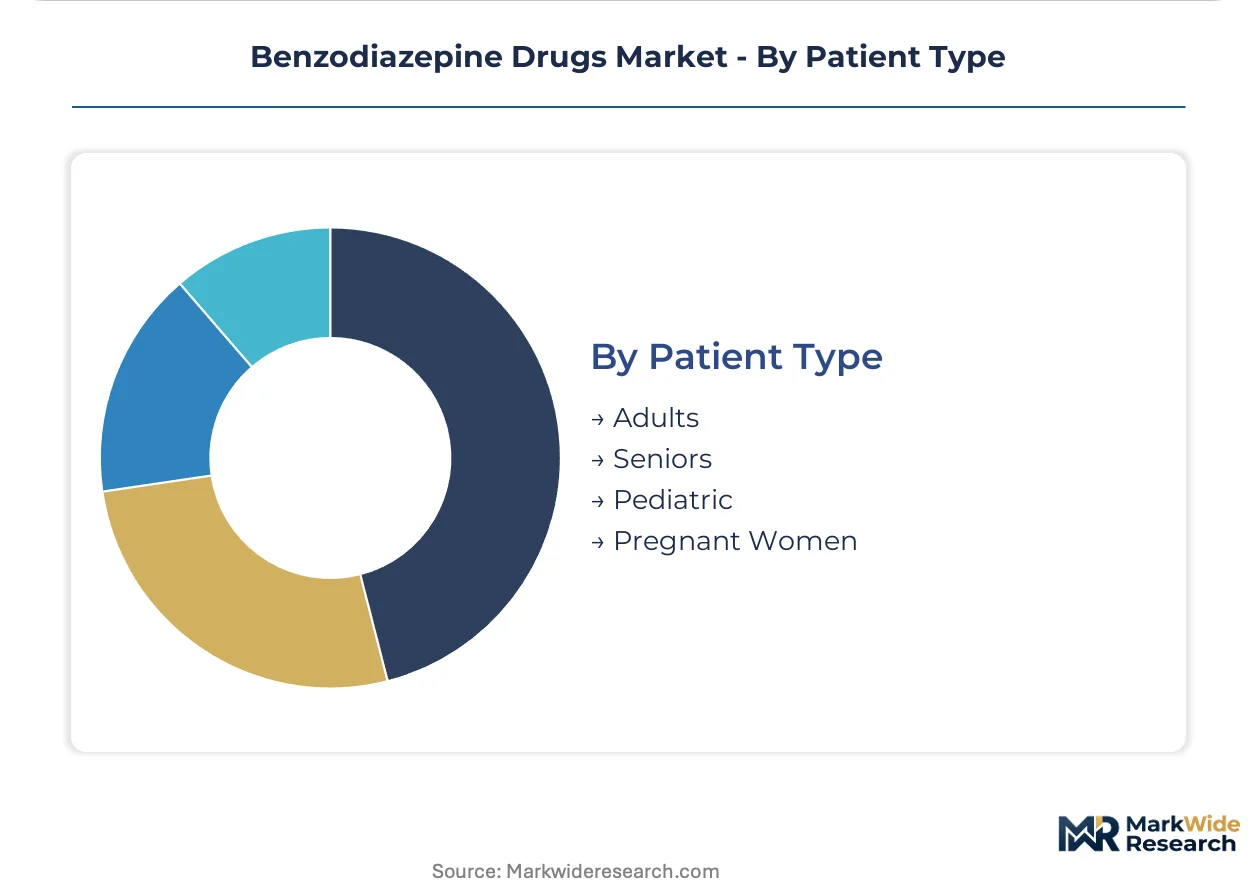
Patient Type:
Maturity and physiological vulnerability stratify prescribing surveillance and formulary restrictions.
- Adults:Core demographic for both acute and chronic benzodiazepine therapy with established risk-benefit frameworks. Working-age populations in US metropolitan areas drive alprazolam and lorazepam tablet consumption, though employer-sponsored health plans are tightening prior authorization requirements for extended courses.
- Seniors:Geriatric patients with heightened sensitivity to sedation, falls, and cognitive impairment requiring dose reduction. Medicare Part D formularies and P&T committees at US health systems impose benzodiazepine avoidance protocols for adults over 65, redirecting anxiety management to SSRIs and psychotherapy.
- Pediatric:Restricted applications in seizure disorders and procedural sedation with weight-based dosing.
- Pregnant Women:Category D risk classification limiting use to refractory seizure emergencies.
Adult populations anchor volume placements; pediatric applications are expanding most quickly through specialty seizure protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical manufacturing zones in Hyderabad and Ahmedabad concentrate active pharmaceutical ingredient synthesis for benzodiazepine production. These chemical manufacturing clusters supply finished-dose producers across North America and Europe.
United States
Chronic anxiety disorder prevalence sustains alprazolam and lorazepam tablet consumption through retail pharmacy chains. The FDA's boxed warning mandate for concurrent opioid-benzodiazepine prescribing restructures emergency department protocols. Academic medical centers in California, New York, and Illinois standardize lorazepam injection in seizure management algorithms.
Germany
Psychiatric specialty clinics in Berlin and Munich intensify non-pharmacological intervention protocols to reduce long-term benzodiazepine exposure. The EMA's PRAC signal assessments on dependence and withdrawal syndromes block label expansions for extended-release formulations. Chemical manufacturing clusters in North Rhine-Westphalia supply API intermediates to European formulation facilities.
India
Vertically integrated API producers in Hyderabad and Ahmedabad dominate benzodiazepine intermediate synthesis for global export. CDSCO manufacturing facility inspections and export clearance protocols govern shipment timelines to regulated markets. Gujarat's pharmaceutical special economic zones concentrate diazepam and alprazolam raw material production.
Japan
METI-supported geriatric mental health initiatives elevate benzodiazepine utilization for anxiety and agitation management in institutional eldercare settings. PMDA post-market surveillance requirements mandate periodic safety update reporting for long-acting formulations. Pharmaceutical manufacturing clusters in Osaka and Tokyo supply domestic hospital formulary channels.
Switzerland
Specialty psychiatric prescribing in Zurich and Geneva maintains selective benzodiazepine utilization for treatment-resistant anxiety disorders. Swissmedic pharmacovigilance requirements enforce stringent dependence monitoring for extended-release products. Basel-region pharmaceutical headquarters coordinate European distribution networks for parenteral formulations.
Benzodiazepine Drugs Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the benzodiazepine landscape. The market structure stratifies into three tiers: research-intensive innovators with legacy psychiatric portfolios, vertically integrated generic manufacturers with captive API production, and regional formulation specialists serving institutional channels. Consolidation pressures favor scale-driven players capable of absorbing REMS compliance infrastructure costs. Competitive moves center on abuse-deterrent formulation R&D partnerships and direct hospital procurement contract negotiations.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and F. Hoffmann-La Roche Ltd. occupy positions anchored by injectable manufacturing scale and legacy brand recognition in psychiatric specialty channels. Teva Pharmaceutical Industries Ltd. exemplifies the vertically integrated generic archetype through API-to-tablet production control. These three entities represent distinct competitive vectors: institutional parenteral supply, specialty clinic brand loyalty, and cost-optimized oral generic volume.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Boehringer Ingelheim International GmbH |
| Sun Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Amneal Pharmaceuticals LLC. |
| Bausch Health Companies Inc. |
| GlaxoSmithKline Plc. |
| Others |
Supply Flow & Price Mechanics
Brand-generic bifurcation between legacy psychiatric portfolios and commodity oral tablets manifests in divergent margin structures and procurement channel configurations across the benzodiazepine landscape. Premium pricing for parenteral lorazepam injection at US academic medical centers reflects DEA Schedule IV quota scarcity and REMS compliance infrastructure costs, while generic alprazolam tablets compete on API sourcing efficiency from Indian chemical manufacturing zones.
Pricing Analysis
Short lead-time premiums for emergency department formulary placement command pricing power over spot inventory liquidations through wholesale distributors. Three-tier pricing structure across premium parenteral kits, standard oral tablets, and economy bulk API separates institutional procurement contracts from retail pharmacy dispensing. Price differentiation hinges on DEA quota security and FDA REMS certification status. Pricing pressure stems from centralized hospital procurement consortia negotiating direct manufacturer contracts in the Southeast and Midwest. Generic tablet buyers at CVS and Walgreens exhibit highest price sensitivity; specialty psychiatric clinics show lowest sensitivity due to brand loyalty and protocol standardization.
Supply Chain Analysis
Dual-sourcing requirements at US health systems mandate qualified suppliers across both Indian API producers and domestic formulation facilities to mitigate shortage risks. Active pharmaceutical ingredient synthesis concentrates in Hyderabad and Ahmedabad chemical manufacturing clusters, with finished-dose production anchored in US and European facilities. Raw material dependencies span diazepam and alprazolam API intermediates, pre-filled syringe components, and polymeric matrix materials for abuse-deterrent formulations. Single-source vulnerability in Indian chemical zones exposes finished-dose producers to CDSCO inspection delays and export clearance disruptions. Distribution runs through hospital procurement consortia and retail pharmacy chains with DEA-controlled substance tracking systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
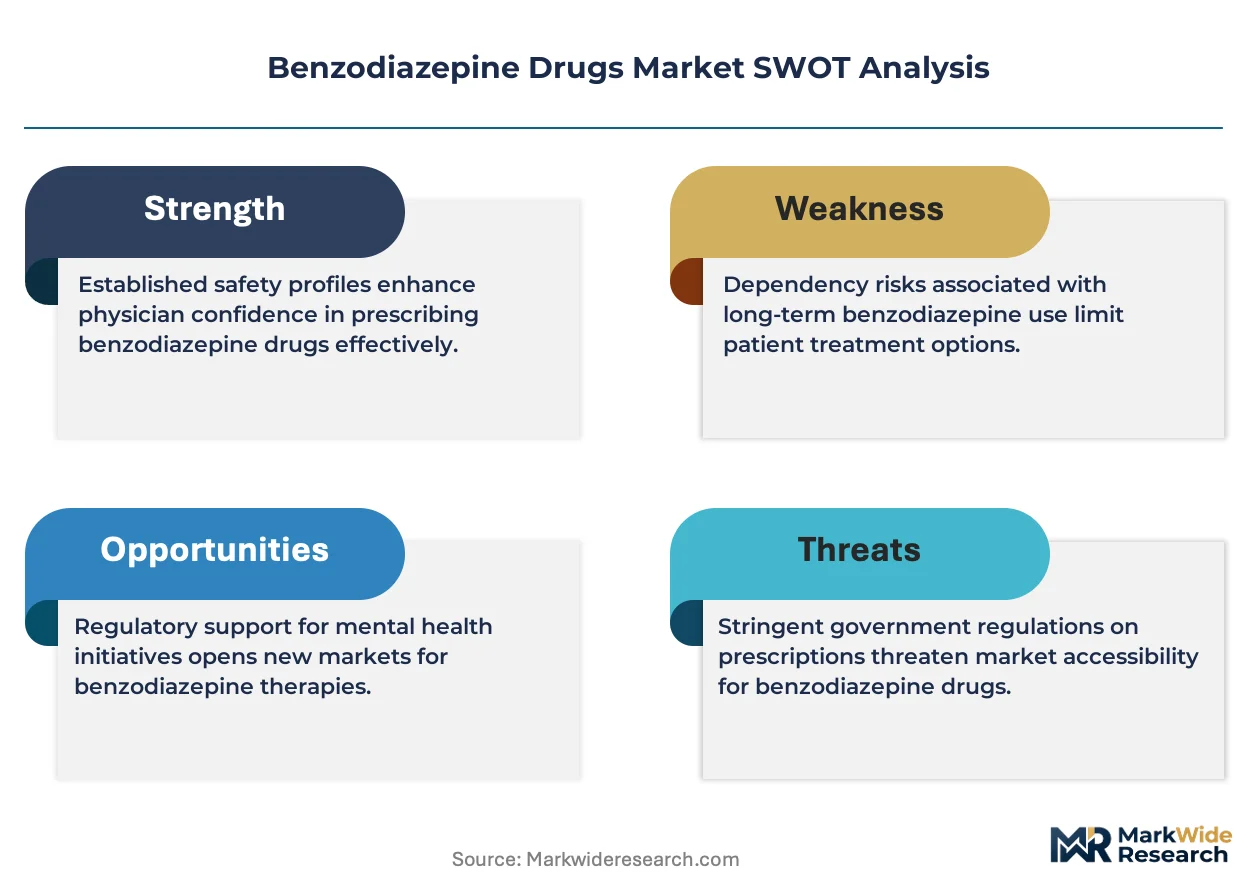
This market functions as a consolidation play where FDA REMS compliance infrastructure costs and pharmacovigilance workforce scarcity force mid-scale generic manufacturers toward exit or acquisition.
For Market Incumbents: Hedge against non-benzodiazepine hypnotic substitution by accelerating abuse-deterrent formulation R&D partnerships with polymeric matrix technology specialists. Secure DEA Schedule IV quota allocations through backward integration into API production at Indian chemical manufacturing zones. Defend institutional channel position through direct procurement contracts with multi-hospital networks in Texas and Florida. For New Entrants and Emerging Players: Capture white-space opportunity in ambulatory surgery center procedural sedation kits by bundling lorazepam injection with pre-filled syringe configurations. Target Japan's institutional eldercare settings under METI-supported geriatric mental health initiatives for anxiety and agitation management. Pursue go-to-market angle through specialized distribution partnerships with ASC pharmacy directors bypassing legacy hospital formulary committees. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated generic manufacturers with captive API production given DEA quota scarcity and supply security premiums. Long-term viability over the next decade favors entities with REMS compliance infrastructure and institutional channel scale. Acquisition target archetype: mid-scale generic manufacturers with Indian API sourcing relationships and pending REMS certification. Signal to watch: EMA PRAC signal assessment outcomes on extended-release formulations redirecting R&D investment toward abuse-deterrent platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Development | Polymeric matrix technologies address FDA REMS requirements while differentiating against commodity generics. |
| DEA Schedule IV Quota Security | Captive API production in Indian chemical zones insulates against supply interruptions and shortage risks. |
| Hospital Procurement Direct Contracting | Bypassing wholesale intermediaries captures volume discounts at multi-hospital networks in Southeast and Midwest. |
| ASC Channel Diversification | Freestanding surgery centers in Texas and Florida expand addressable market beyond emergency department formularies. |
| Pharmacovigilance Infrastructure Investment | Specialized signal detection capabilities satisfy FDA and EMA post-market surveillance mandates for extended-release products. |
Methodological Framework
Independent corroboration across regulatory affairs leads at pharmaceutical manufacturers, hospital formulary directors, and DEA quota administrators underwrites the qualitative findings on prescribing protocol evolution. Primary interviews with drug development executives, hospital procurement managers, and payer access specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases established segment-level demand trajectories. Bottom-up prescription volume modeling and top-down API production quota analysis triangulate market sizing across the benzodiazepine landscape.
Rate-of-change decomposition across the projection horizon separates volume growth from pricing dynamics and mix shifts between parenteral and oral formulations. Segmentation dimensions modeled span product type, indication, delivery mode, and patient population with regional regulatory cluster overlays. CAGRs derive from prescription trend extrapolation, DEA quota allocation trajectories, and formulary adoption curve analysis. Forecast inputs incorporate EMA PRAC signal assessment timelines and METI geriatric mental health initiative funding levels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to DEA Schedule IV quota policy shifts and FDA pharmacovigilance mandate expansions. Deviation in EMA extended-release formulation approval pathways or Indian API export clearance protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Meperidine Drugs Market