
 Loxoprofen Market | 2026-2036
Loxoprofen Market Size, Share, and Industry Trends Forecast 2026-2036
Loxoprofen Market Insights
Multi-source API procurement is consolidating around certified manufacturers in China and Japan. Eisai anchors loxoprofen production through its established Japanese manufacturing base and deep formulary relationships. Daiichi Sankyo competes via broad distribution across hospital and retail pharmacy channels. Boehringer Ingelheim differentiates through integration of loxoprofen into combination pain therapies for European and Asian markets.
Loxoprofen is a propionic acid-derived non-steroidal anti-inflammatory drug (NSAID) with a molecular weight of 246.3 g/mol, formulated as the sodium dihydrate salt for enhanced water solubility in injectable preparations; it functions primarily as a cyclooxygenase inhibitor for acute pain and inflammatory conditions. Tablet formulations dominate volume due to manufacturing scale and patient familiarity, while transdermal patches capture expanding share in Japan and South Korea as prescribers prioritize gastric-sparing delivery modes. The hospital end-user segment sustains premium pricing for injectable loxoprofen in perioperative settings, whereas homecare channels drive patch and gel volume through direct-to-patient pharmacy dispensing.
Japan's PMDA maintains stringent post-market surveillance for NSAID cardiovascular and gastrointestinal risks, shaping manufacturer investment in gastroprotective co-formulations and alternative delivery systems. China's NMPA enforces bioequivalence standards for generic loxoprofen tablets under its consistency evaluation program, filtering domestic suppliers and elevating quality thresholds for market access. Stakeholders must monitor evolving pharmacovigilance requirements across East Asian regulators and calibrate portfolio emphasis between oral solids and transdermal innovations accordingly.
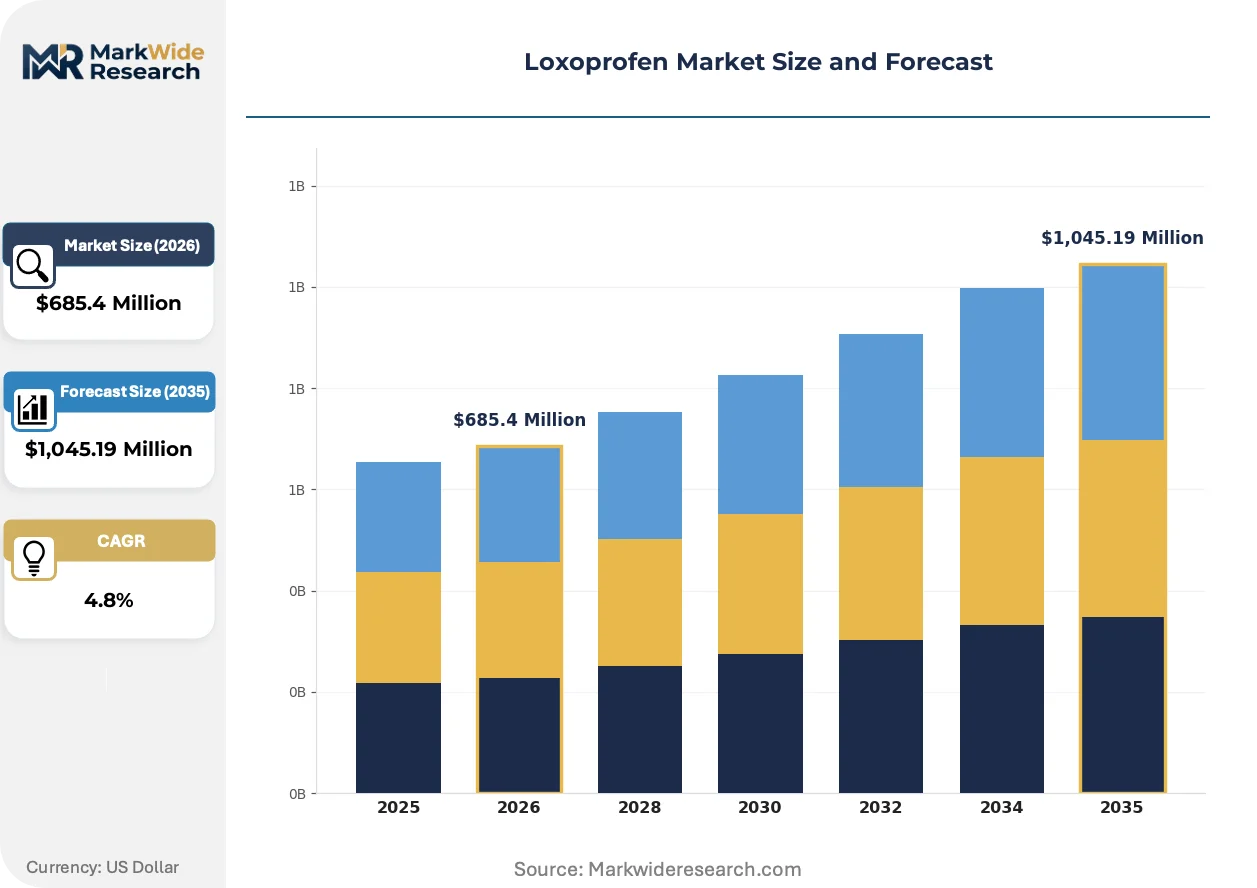
Market Dynamics
Japan's PMDA and China's NMPA are tightening NSAID safety surveillance, forcing manufacturers to redirect R&D investment from oral formulations toward transdermal and gastroprotective delivery systems that reduce cardiovascular and gastrointestinal risk exposure.
Growth Catalysts
- Post-operative pain protocols:Hospital procurement departments across East Asia are expanding loxoprofen inclusion in perioperative care bundles, particularly for orthopedic and abdominal surgery recovery pathways.
- PMDA transdermal pathway incentives:Japan's regulator offers expedited review timelines for novel delivery formats that demonstrate reduced gastric toxicity compared to oral NSAID equivalents.
- Ambulatory surgical center expansion:Same-day discharge protocols in South Korea and Japan are elevating demand for take-home transdermal patches that extend analgesic coverage beyond facility walls.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in specific coastal Chinese provinces, creating single-source vulnerability for multiple finished dose manufacturers.
- Cardiovascular risk labeling:PMDA-mandated boxed warnings for all propionic acid-derived NSAIDs constrain prescriber willingness in elderly populations with comorbid hypertension.
- Acetaminophen substitution:First-line analgesic protocols in Chinese tier-1 hospitals increasingly default to paracetamol for mild-to-moderate pain, compressing loxoprofen trial rates.
Strategic Opportunities
- South Korea's MFDS patch approval pathway:Regulatory harmonization with Japanese transdermal standards creates near-term filing opportunity for manufacturers with existing PMDA approvals.
- Combination therapy positioning:Co-formulation with proton pump inhibitors or gastroprotective agents addresses unmet need in chronic osteoarthritis patients requiring long-term NSAID exposure.
- Direct-to-patient pharmacy channels:Japan's deregulation of behind-the-counter NSAID dispensing enables patch and gel volume growth outside traditional hospital procurement.
Industry Challenges
- Bioequivalence study capacity:China's NMPA consistency evaluation program has created bottlenecks in qualified clinical trial site availability for generic tablet sponsors.
- Transdermal manufacturing scale-up:Patch production requires specialized adhesive coating and release liner technologies that few contract manufacturers in East Asia have validated at commercial volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loxoprofen Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Injection, Gel, Patch End User: Hospitals, Clinics, Pharmacies, Homecare Application: Pain Relief, Anti-inflammatory, Fever Reduction, Musculoskeletal Disorders Delivery Mode: Oral, Injectable, Transdermal, Topical |
| Companies Covered | Lead Chemical Co., Ltd, Shandong Weigao Pharmaceutical, Boehringer Ingelheim, Jilin Yinglian Biopharmaceutical, Hunan Jiudian Pharmaceutical, Eisai, Shanghai Xudong Haipu Pharmaceutical, Ningbo Lihua Pharmaceutical, Daiichi Sankyo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loxoprofen Market Trends and Innovations
Delivery format diversification is fragmenting competitive advantage away from pure API cost position toward formulation science capabilities and regulatory navigation expertise in transdermal development.
Transdermal patch technology is modularizing the loxoprofen value chain by separating drug-in-adhesive engineering from final packaging and distribution. Japanese and South Korean hospital formularies are adopting these patches at accelerating rates for chronic low-back pain patients. This format shift is compressing margins for pure oral-solid manufacturers while creating premium pricing windows for formulation innovators with proprietary permeation enhancers.
China's NMPA bioequivalence consistency evaluation is disqualifying domestic tablet manufacturers that cannot demonstrate dissolution profile match to reference listed drugs. The industrial consequence is a halving of approved generic suppliers since program initiation. Oral solid sponsors with pre-2016 approvals face the steepest re-registration burden, while transdermal developers operate under separate clinical efficacy requirements that bypass direct bioequivalence demands.
Hospital procurement committees are consolidating analgesic purchasing around single-source contracts with guaranteed formulary placement. This behavior shift is displacing fragmented multi-supplier arrangements that previously allowed therapeutic substitution at the prescriber level. Japanese prefectural hospital groups and Chinese provincial centralized procurement platforms represent the geographies where this concentration is most visible, with three-year contract durations becoming standard.
Loxoprofen Market Segmentation
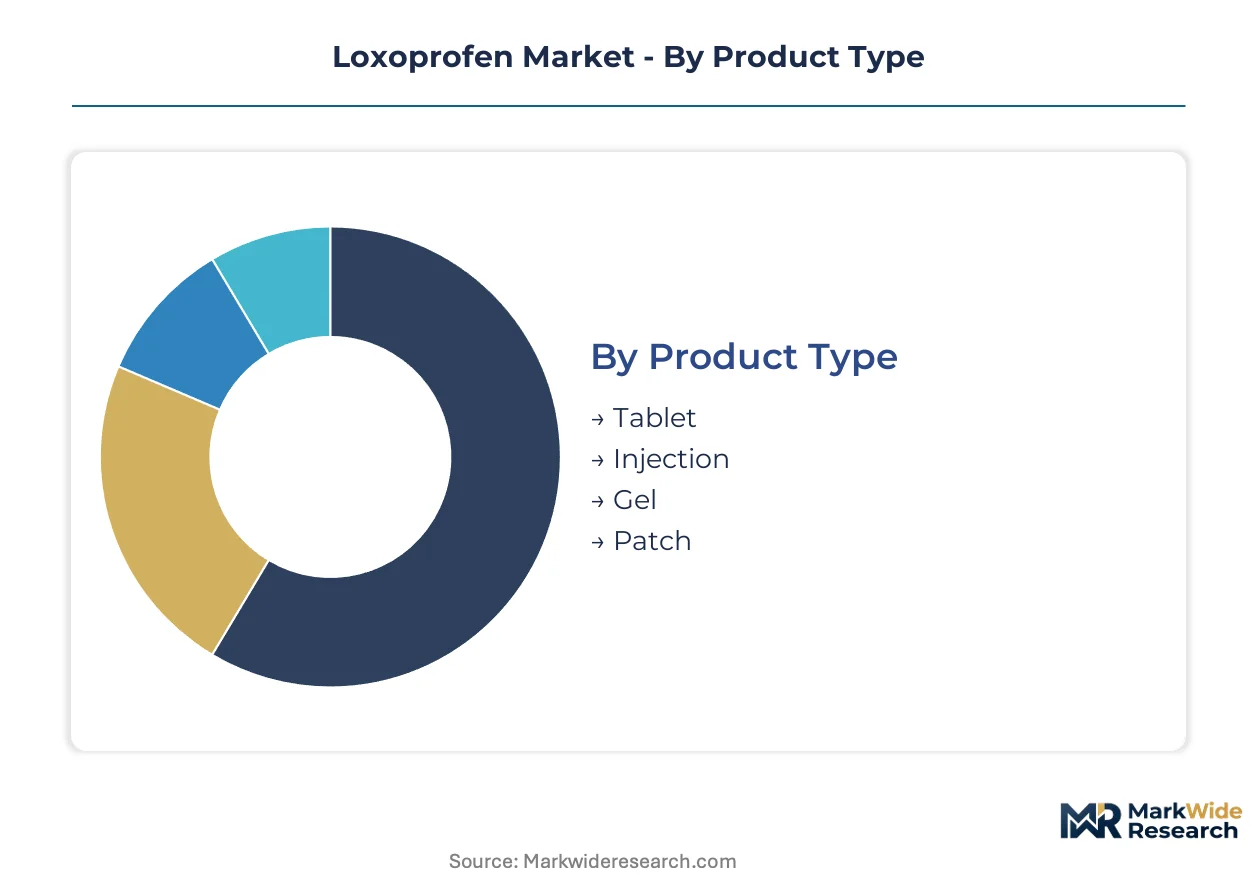
Loxoprofen's formulation diversity creates distinct competitive arenas where manufacturing expertise and regulatory navigation matter more than API scale alone. Each segment demands specialized capabilities that reshape who captures value across the value chain.
Product Type:
Tablet-to-patch upgrade cycles are accelerating as prescribers seek gastric-sparing alternatives and patients demand convenience beyond hospital settings.
- Tablet:Sodium dihydrate salt formulations dominate manufacturing volume due to established compression lines and patient familiarity with oral NSAID regimens. Japanese prefectural hospital groups and Chinese provincial procurement platforms concentrate demand here for chronic osteoarthritis management, though PMDA cardiovascular warnings constrain expansion in elderly hypertensive populations.
- Injection:Aqueous solutions for perioperative pain command premium pricing in orthopedic and abdominal surgery recovery bundles across East Asian tertiary hospitals. Hospital procurement committees in Japan and South Korea favor this format for immediate post-operative analgesia where rapid onset outweighs administration complexity.
- Gel:Topical formulations serve localized musculoskeletal complaints with lower systemic exposure. Pharmacies in Japan's deregulated behind-the-counter channels drive volume for homecare patients seeking self-directed pain management.
- Patch:Drug-in-adhesive systems with proprietary permeation enhancers capture expanding share in South Korea's ambulatory surgical center discharge protocols. MFDS regulatory harmonization with Japanese transdermal standards accelerates filing opportunities for manufacturers with existing PMDA approvals.
Tablet sits at the top of the volume ranking, with Patch climbing the fastest.
End User:
Customer type determines pricing power and contract structure, with institutional buyers extracting volume commitments that reshape manufacturer margin profiles.
- Hospitals:Tertiary medical centers and prefectural hospital groups in Japan consolidate purchasing through single-source three-year contracts with guaranteed formulary placement. Injectable loxoprofen sustains premium positioning here for perioperative care bundles.
- Clinics:Outpatient orthopedic and pain management practices in South Korea favor transdermal patches for chronic low-back pain patients requiring extended analgesic coverage. Same-day discharge protocols elevate take-home prescription volumes.
- Pharmacies:Japan's deregulated behind-the-counter NSAID dispensing enables direct-to-patient patch and gel growth outside traditional hospital procurement channels. Pharmacist counseling requirements shape product selection toward patient-friendly formats.
- Homecare:Self-administered pain management for chronic conditions drives demand for transdermal systems with simplified application. South Korean and Japanese aging populations concentrate need here for osteoarthritis and degenerative joint disease.
Hospitals command the highest contract values, though Pharmacies are expanding most quickly as dispensing deregulation progresses.
Application:
Therapeutic use case dictates dosing frequency, duration, and tolerability requirements that fragment formulation preferences across patient populations.
- Pain Relief:Acute post-operative and trauma-related analgesia represents the core hospital demand driver. Japanese orthopedic surgery protocols and Chinese tier-2 hospital abdominal surgery pathways concentrate injectable and tablet consumption here.
- Anti-inflammatory:Chronic rheumatoid arthritis and soft tissue inflammation management requires long-term NSAID exposure where gastric toxicity concerns elevate transdermal patch preference. Japanese geriatric populations with comorbidities drive format substitution.
- Fever Reduction:Antipyretic applications face intense acetaminophen competition in Chinese tier-1 hospital first-line protocols. Loxoprofen captures residual share where NSAID anti-inflammatory co-benefit is clinically relevant.
- Musculoskeletal Disorders:Chronic low-back pain and degenerative joint conditions favor extended-release transdermal delivery. South Korean MFDS-approved patches gain traction here for elderly patients with polypharmacy concerns.
Pain Relief anchors current volume, while Musculoskeletal Disorders shows the steepest expansion trajectory as population aging deepens.
Delivery Mode:
Route of administration determines manufacturing complexity, regulatory pathway, and competitive moat depth in ways that reshape industry structure.
- Oral:Immediate-release tablets face bioequivalence consistency evaluation pressures under China's NMPA program, filtering domestic suppliers and elevating quality thresholds. Dissolution profile matching to reference listed drugs dominates technical requirements.
- Injectable:Perioperative hospital use demands sterile manufacturing capabilities and cold chain logistics that concentrate supply among established Japanese and Chinese manufacturers. PMDA post-market surveillance for cardiovascular risk shapes labeling constraints.
- Transdermal:Patch production requires specialized adhesive coating and release liner technologies that few East Asian contract manufacturers have validated at commercial scale. PMDA expedited review incentives for reduced gastric toxicity accelerate development investment.
- Topical:Gel and cream formulations serve localized pain with lower barrier to entry for generic manufacturers. Pharmacy channel dispensing in Japan's deregulated environment drives volume growth for self-care applications.
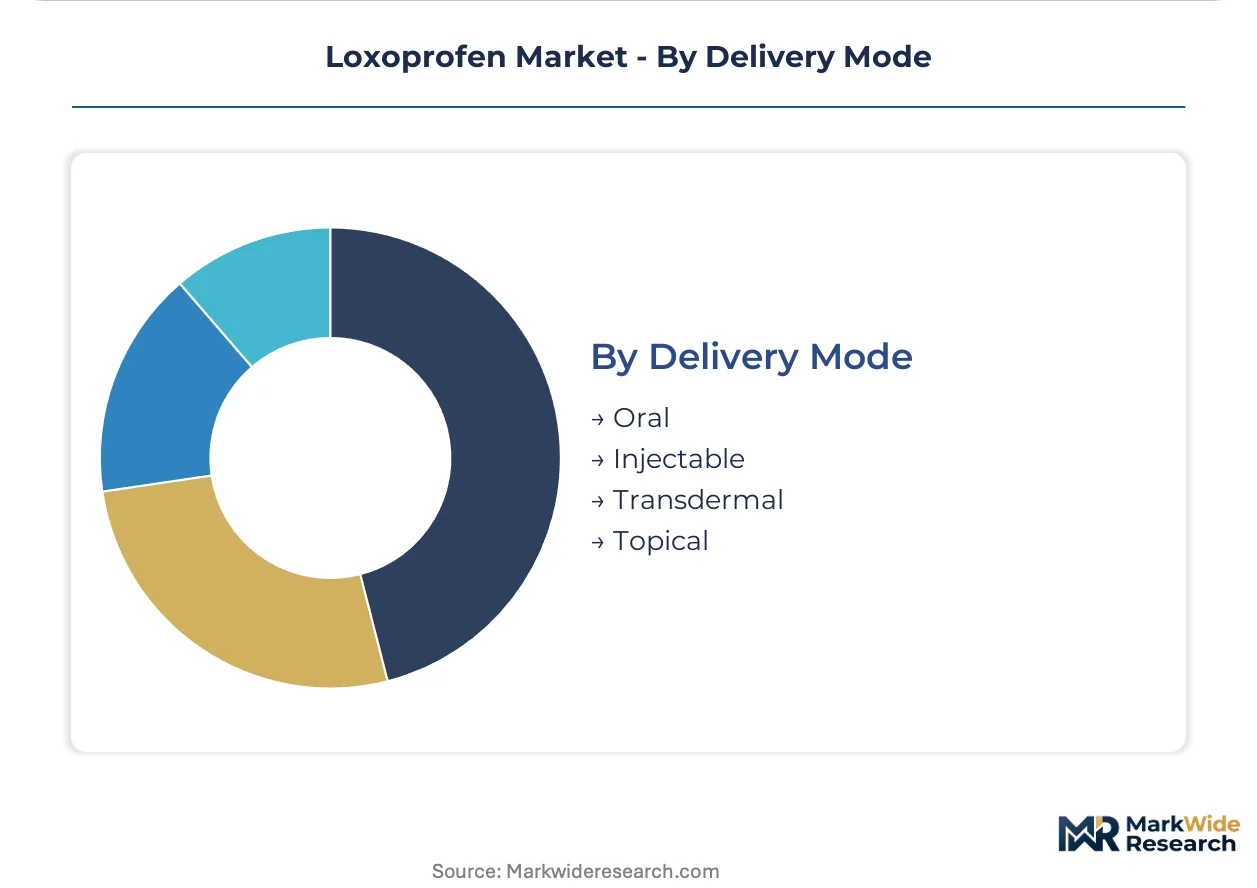
Oral retains dominant share, though Transdermal is gaining share fastest as regulatory incentives and patient preference converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping loxoprofen manufacturing geography as producers migrate toward jurisdictions with streamlined transdermal approval pathways and lower cost-of-compliance burdens for novel delivery formats.
Japan
Post-operative pain protocols in prefectural hospital groups sustain injectable loxoprofen demand for orthopedic surgery recovery. PMDA expedited review timelines for transdermal patches with demonstrated gastric toxicity reduction accelerate domestic R&D investment. Manufacturing clusters in Kanto and Kansai regions concentrate drug-in-adhesive engineering capabilities for export-oriented patch production.
China
NMPA bioequivalence consistency evaluation filters domestic tablet suppliers while elevating quality thresholds for market access. Provincial centralized procurement platforms in Jiangsu and Zhejiang consolidate purchasing around single-source contracts with guaranteed formulary placement. API production concentrates in coastal provinces, creating supply vulnerability for finished dose manufacturers dependent on external sourcing.
South Korea
MFDS regulatory harmonization with Japanese transdermal standards creates near-term filing opportunities for patch manufacturers with existing PMDA approvals. Ambulatory surgical center expansion in Seoul Capital Area elevates take-home transdermal prescription volumes for same-day discharge protocols. Busan-Ulsan pharmaceutical manufacturing corridor develops specialized adhesive coating capabilities for commercial-scale patch production.
Germany
Boehringer Ingelheim anchors European loxoprofen positioning through integration into combination pain therapies for hospital and retail pharmacy channels. EMA post-market surveillance requirements for NSAID cardiovascular risk shape labeling constraints across propionic acid-derived formulations. Baden-Württemberg chemical manufacturing base supplies specialized excipients for gastroprotective co-formulation development.
India
CDSCO accelerated approval pathways for transdermal generics attract contract manufacturing investment from Japanese and Korean sponsors seeking cost-competitive production. Maharashtra and Gujarat pharmaceutical clusters build adhesive formulation capabilities to serve export demand for patch and gel formats. Domestic tablet manufacturers face dissolution profile matching requirements under bioequivalence guidelines that parallel Chinese NMPA standards.
Loxoprofen Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue transdermal specialization and gastroprotective co-formulation niches. The competitive structure fragments across API manufacturing, finished dose formulation, and novel delivery system engineering, with concentration varying by geography and regulatory pathway. Three archetypes dominate: integrated Japanese pharmaceutical conglomerates with formulary depth, Chinese domestic champions with provincial procurement relationships, and European multinationals with combination therapy portfolios. Capacity expansion in transdermal manufacturing and strategic partnerships for permeation enhancer technology represent the dominant competitive moves reshaping positioning.
Among the named participants, Eisai and Daiichi Sankyo exemplify the integrated Japanese archetype with established domestic manufacturing bases and deep hospital formulary relationships. Boehringer Ingelheim occupies a distinct position anchoring European and Asian market presence through combination therapy integration. Chinese domestic manufacturers including Shandong Weigao Pharmaceutical and Hunan Jiudian Pharmaceutical represent scale-oriented suppliers navigating NMPA consistency evaluation pressures and provincial procurement consolidation.
| Leading Market Players |
|---|
| Lead Chemical Co., Ltd |
| Shandong Weigao Pharmaceutical |
| Boehringer Ingelheim |
| Jilin Yinglian Biopharmaceutical |
| Hunan Jiudian Pharmaceutical |
| Eisai |
| Shanghai Xudong Haipu Pharmaceutical |
| Ningbo Lihua Pharmaceutical |
| Daiichi Sankyo |
| Others |
Pricing and Supply Chain Analysis
Japanese prefectural hospital groups consolidating around single-source three-year procurement contracts with guaranteed formulary placement compel manufacturers to absorb volume commitments while defending margin through specialized delivery format differentiation. This buyer-driven concentration forces supply chain reconfiguration toward validated transdermal manufacturing capabilities that command premium positioning against commodity tablet alternatives.
Pricing Analysis
Active pharmaceutical ingredient cost pass-through from coastal Chinese sodium dihydrate salt suppliers shapes finished dose economics for tablet manufacturers facing NMPA bioequivalence consistency evaluation pressures. Pricing stratifies across premium transdermal patches with proprietary permeation enhancers, standard hospital-grade injectables for perioperative bundles, and economy oral solids competing in provincial procurement tenders. Cost compression in economy tablets is intensifying because NMPA-mandated dissolution profile matching elevates technical compliance spend. Homecare patients through Japan's deregulated pharmacy channels show least price sensitivity for patch and gel convenience formats, while Chinese provincial procurement platforms extract maximum concession on oral solid volume commitments.
Supply Chain Analysis
Direct-to-hospital channels handle institutional demand for injectable loxoprofen in perioperative care bundles, while pharmacy and homecare distribution runs through deregulated behind-the-counter dispensing networks in Japan and South Korea. API production draws from coastal Chinese provinces, Japanese Kanto and Kansai chemical clusters, and emerging Busan-Ulsan adhesive coating capabilities in South Korea. Finished dose manufacturing rests on sodium dihydrate salt inputs, specialized drug-in-adhesive polymers, and release liner substrates. Single-source vulnerability concentrates in specific coastal Chinese API production zones, creating supply interruption exposure for multiple finished dose manufacturers. Distribution downstream centers on hospital procurement committees, ambulatory surgical center discharge protocols, and direct-to-patient pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transdermal delivery format premiumization offers margin expansion as PMDA expedited review incentives reduce time-to-market for gastric-sparing alternatives, while API supply consolidation in certified Chinese manufacturers drives input cost discipline.
For Market Incumbents: Deploy transdermal manufacturing capacity expansion in Kanto and Busan-Ulsan corridors to capture PMDA and MFDS regulatory harmonization benefits. Defend hospital formulary positioning through guaranteed supply commitments in single-source procurement contracts. Accelerate gastroprotective co-formulation R&D to address PMDA cardiovascular risk labeling constraints in elderly hypertensive populations. Backward integration into specialized adhesive coating technology reduces dependency on limited contract manufacturing partners. For New Entrants and Emerging Players: Begin with MFDS patch filing pathway leveraging Japanese PMDA approval precedents for accelerated South Korean market access. Target South Korean ambulatory surgical center discharge protocols where take-home transdermal prescription volume expands fastest. Exploit supply gap in validated commercial-scale patch manufacturing capacity across East Asia. Pursue direct-to-patient pharmacy channel partnerships in Japan's deregulated behind-the-counter dispensing environment. For Investors and Strategic Acquirers: Asymmetric upside sits with transdermal formulation specialists possessing proprietary permeation enhancer technology and established PMDA regulatory dossiers. Long-term viability across the analysis window favors manufacturers with dual oral-solid and patch capabilities navigating NMPA consistency evaluation and PMDA safety surveillance simultaneously. Acquisition focus should center on adhesive engineering firms with validated drug-in-adhesive coating lines. Monitor MFDS approval velocity for transdermal filings as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Manufacturing Scale-Up | PMDA expedited review incentives reward gastric-sparing delivery investments with faster market access timelines. |
| Gastroprotective Co-Formulation Development | Combination with proton pump inhibitors addresses unmet chronic osteoarthritis need under cardiovascular risk labeling constraints. |
| Regulatory Harmonization Exploitation | MFDS alignment with Japanese transdermal standards enables near-term South Korean filing for PMDA-approved manufacturers. |
| Direct-to-Patient Channel Expansion | Japan's deregulated pharmacy dispensing creates volume growth outside hospital procurement committee control. |
| API Supply Security Investment | Backward integration into sodium dihydrate salt production reduces coastal Chinese single-source vulnerability exposure. |
Research Methodology
Bottom-up hospital and pharmacy channel modeling reconciled against top-down API production and finished dose manufacturing tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads at PMDA and NMPA, hospital procurement managers, and formulary directors combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and East Asian customs trade data. Triangulation between demand-side prescription volume analysis and supply-side production capacity assessment ensures cross-verified output integrity.
Input-output matrix framing connects API sodium dihydrate salt availability, transdermal adhesive coating capacity, and regulatory approval velocity to finished dose volume and value projections across the modeling period. Segmentation dimensions include formulation type, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derive from calibrated patient population growth, surgical procedure volume trends, and format substitution elasticity estimates. Forecast inputs incorporate PMDA pharmacovigilance evolution, NMPA consistency evaluation completion rates, and MFDS regulatory harmonization progress.
Several conditions sit outside the modeled scope, including unforeseen regulatory safety withdrawals, abrupt API supply disruptions from geopolitical events, and radical therapeutic substitution by non-NSAID analgesic classes. Forecasts reflect assumptions regarding continued PMDA and NMPA policy trajectories and stable East Asian healthcare procurement structures. Periodic stress-testing of base assumptions is recommended given cardiovascular risk labeling evolution and transdermal manufacturing capacity expansion uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
United States Pharmaceutical Logistics Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Antibodies Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Herbal Drugs Market