
 Immunofluorescence Analyzers Market | 2026-2036
Immunofluorescence Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Immunofluorescence Analyzers Market Intelligence
The bundling of advanced imaging software with modular hardware platforms is shifting buyer preferences from standalone units toward fully integrated systems. This trend favors vendors who can provide end-to-end solutions. Thermo Fisher Scientific leverages its extensive portfolio to serve both research and clinical labs. Siemens Healthcare competes by embedding its analyzers into larger hospital-wide diagnostic workflows, while Bio-Rad Laboratories specializes in high-specificity antibodies and reagents for niche research applications.
An immunofluorescence analyzer is a microscopic system that uses fluorophore-conjugated antibodies to visualize and quantify specific antigens within biological samples. These instruments provide critical data on protein expression and localization, which is essential for disease diagnosis and biomedical research. Among product types, automated analyzers are displacing manual methods due to superior throughput and reproducibility in high-volume settings like diagnostic laboratories. The oncology application segment is expanding rapidly, fueled by the rising importance of biomarker discovery for personalized medicine.
Regulatory frameworks from the US FDA and the European Union's Medical Device Regulation (MDR) establish stringent requirements for device performance, safety, and clinical validation. In parallel, China's NMPA governs market entry, often requiring local clinical data for high-risk devices. These regulations directly influence product design, development timelines, and quality control protocols. Successfully navigating the evolving standards for software as a medical device will be a critical determinant of future market leadership.
Market Dynamics
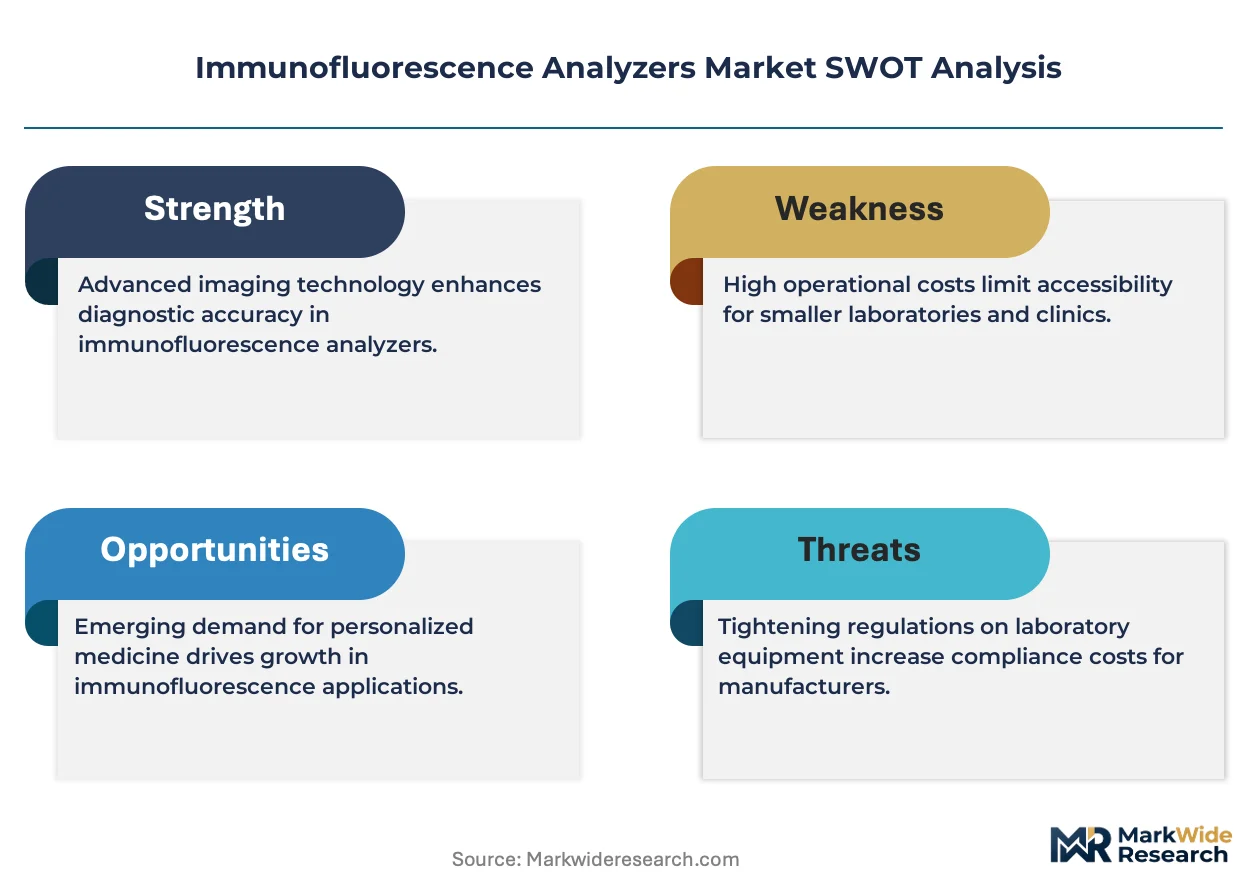
The central force shaping the market is the architectural shift from standalone analyzers to fully integrated, modular systems. This evolution combines hardware with advanced imaging software and reagent supply, compelling vendors to compete on end-to-end workflow solutions rather than on instrument specifications alone.
Growth Catalysts
- Personalized Medicine:The expansion of biomarker discovery in oncology and autoimmune disease research creates sustained demand for high-specificity protein expression and localization data, which immunofluorescence analyzers provide.
- Technological Advancement:Integration of AI-powered image analysis and digital microscopy automates quantification, improves reproducibility, and increases throughput, making the technology more accessible to high-volume diagnostic laboratories.
- Research Funding:Substantial government and private investment in biomedical research, particularly in the United States and Germany, supports the acquisition of advanced imaging instrumentation in academic and clinical research centers.
Market Restraints
- High Capital Cost:The significant initial investment required for automated, high-throughput immunofluorescence systems presents a barrier to adoption for smaller research laboratories and clinics with limited budgets.
- Standardization Gaps:A lack of universally accepted standards for reagents, sample preparation, and imaging protocols can lead to variability in results between different platforms and laboratories, complicating data comparison.
- Regulatory Hurdles:Stringent validation requirements under regulations like the EU's MDR and the FDA's guidance for software as a medical device increase development costs and extend timelines for market entry.
Strategic Opportunities
- Emerging Market Penetration:Developing diagnostic infrastructure in Asia-Pacific countries offers significant growth potential as laboratories upgrade from manual to automated systems to meet rising clinical demand.
- Multiplexing Capabilities:There is a clear opportunity for systems that can simultaneously detect multiple biomarkers in a single tissue sample, enhancing diagnostic efficiency and conserving precious patient material.
- Point-of-Care Development:Miniaturization of analyzer technology could open pathways for developing compact, user-friendly systems suitable for near-patient testing in specialized clinics or resource-limited settings.
Industry Challenges
- Specialized Skill Gap:A shortage of technicians and pathologists with the dual expertise in both complex instrumentation and the bioinformatic analysis of digital pathology data limits the effective use of advanced systems.
- System Integration Complexity:Integrating new immunofluorescence analyzers with existing Laboratory Information Systems (LIS) and hospital-wide electronic health records often requires custom development and poses significant technical hurdles.
- Data Management and Security:The large datasets generated by digital analyzers require robust IT infrastructure for storage and processing, while also demanding stringent cybersecurity measures to protect sensitive patient data per HIPAA or GDPR rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunofluorescence Analyzers Market |
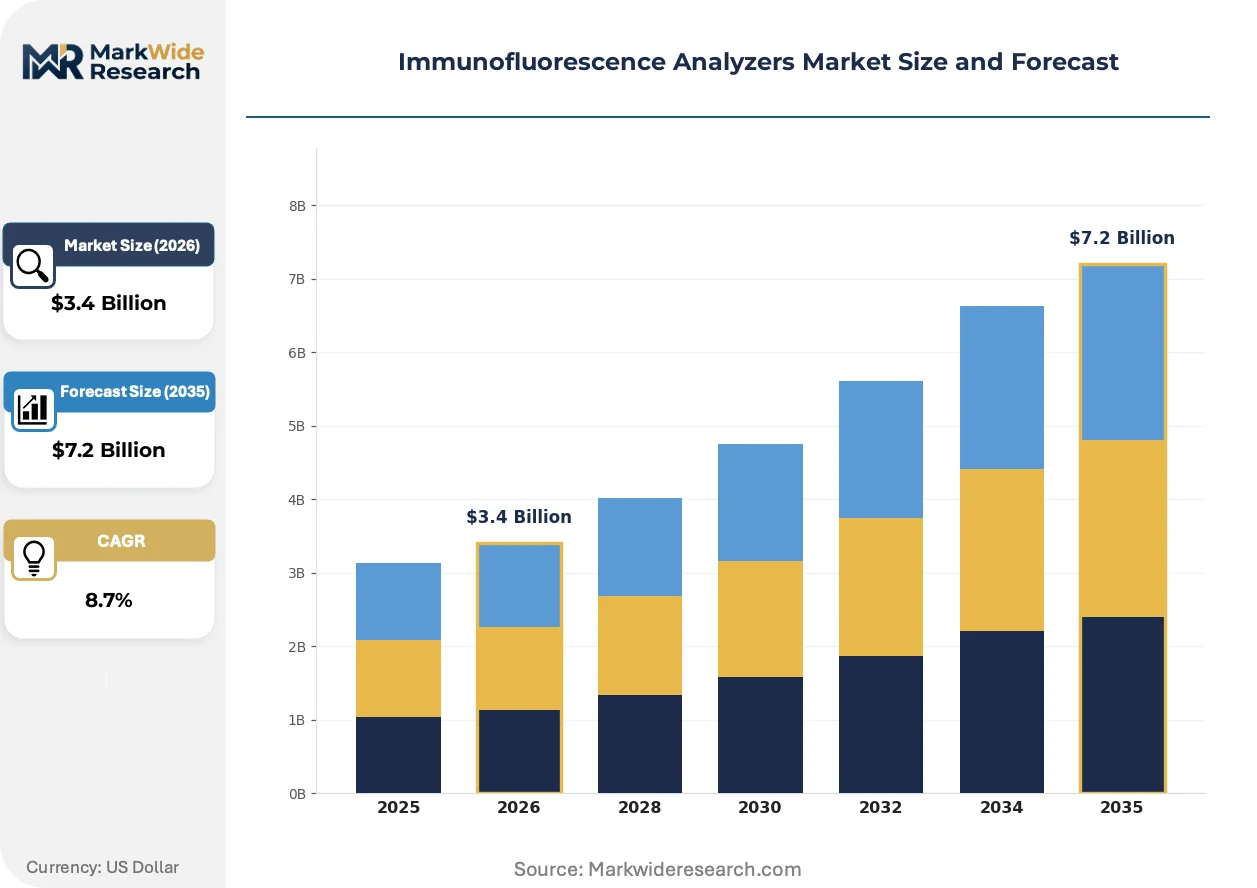
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Semi-Automated Analyzers, Manual Analyzers, Portable Analyzers Technology: Confocal Microscopy, Widefield Microscopy, Flow Cytometry, Digital Microscopy End User: Hospitals, Diagnostic Laboratories, Research Institutions, Pharmaceutical Companies Application: Oncology, Infectious Diseases, Autoimmune Disorders, Neurological Disorders |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, Siemens Healthcare, BioMerieux, EMD Millipore, DiaSorin S.p.A., PerkinElmer Inc., Bio-Rad Laboratories, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunofluorescence Analyzers Market Strategic Shifts & Innovations
Automation and data intelligence are transforming immunofluorescence from a largely qualitative technique into a precise, quantitative discipline. This shift is driven by software advancements that enhance reproducibility and enable more complex biological questions to be answered at scale in clinical and research environments.
AI-driven image analysis software provides automated cell counting, signal quantification, and subcellular pattern recognition. Clinical diagnostic labs and pharmaceutical research organizations are adopting this technology to accelerate workflows and reduce operator-dependent variability. This software-led intelligence is absorbing the manual, subjective interpretation tasks previously performed by pathologists, thereby standardizing diagnostic outputs across different users and sites.
The European Union's Medical Device Regulation (MDR) and the US FDA's evolving framework for software as a medical device impose stricter clinical evidence and performance documentation requirements. This regulatory scrutiny compels manufacturers to invest heavily in validation studies for both their hardware platforms and their analytical software algorithms. The oncology diagnostics segment is particularly affected, as vendors must rigorously prove the clinical utility of their systems for specific biomarker applications.
A preference for bundled procurement models is gaining traction, where laboratories source the analyzer, imaging software, and multi-year reagent supply agreements from a single vendor. This approach disrupts the traditional, fragmented purchasing of instruments and consumables from separate suppliers. This trend is most visible in high-volume diagnostic laboratories in the United States and key European markets, where workflow simplification and total cost of ownership are primary considerations.
Immunofluorescence Analyzers Market Segmentation
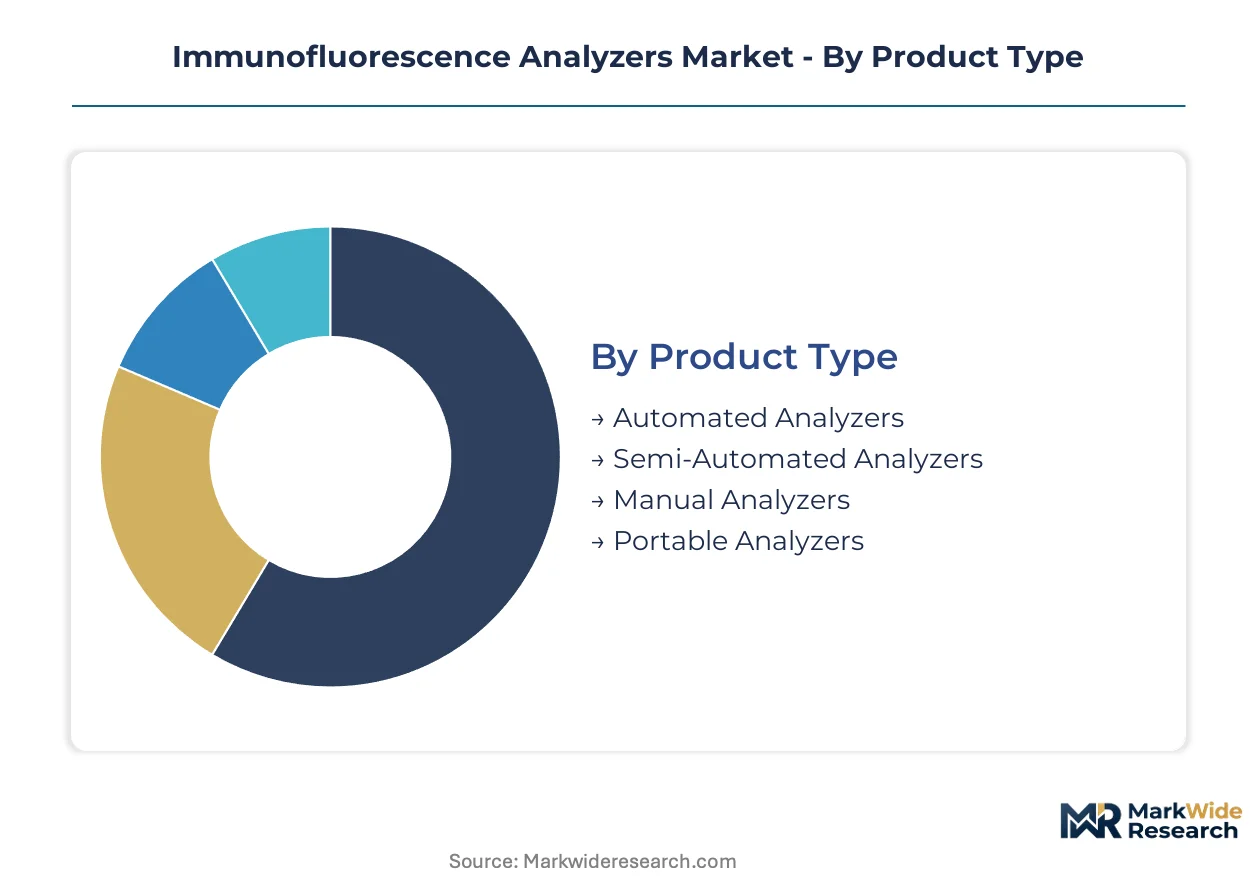
The immunofluorescence analyzers market segments highlight distinct operational requirements and technological preferences across diverse end-user environments. Understanding these segments is crucial for vendors to tailor product development, marketing strategies, and support services to specific client needs.
Product Type:
Buyers evaluate immunofluorescence analyzer product types based on their operational needs and desired levels of automation, directly influencing workflow efficiency and data throughput.
- Automated Analyzers:These systems perform sample loading, reagent addition, imaging, and data analysis with minimal human intervention, ensuring high consistency. Demand concentrates in high-volume diagnostic laboratories in the United States, driven by the need for superior throughput and reproducibility.
- Semi-Automated Analyzers:These instruments combine automated steps with some manual intervention, offering a balance between cost-efficiency and workflow optimization. Clinical research facilities and mid-sized diagnostic labs often adopt these to manage moderate sample volumes effectively.
- Manual Analyzers:These traditional systems require extensive operator involvement for each step of the immunofluorescence assay. Smaller research groups and specialized academic labs utilize manual methods for unique or low-volume experiments.
- Portable Analyzers:Compact and designed for on-site or near-patient testing, these analyzers offer rapid results outside traditional laboratory settings. Emerging market penetration in developing diagnostic infrastructure creates opportunities for these compact systems.
Automated Analyzers leads on scale; Portable Analyzers leads on momentum.
Technology:
Immunofluorescence analyzer technologies are selected based on the specific biological questions and resolution requirements of the application, impacting data quality and analytical depth.
- Confocal Microscopy:This advanced imaging technique uses a pinhole to eliminate out-of-focus light, producing high-resolution optical sections of thick samples. Research institutions in Germany leverage confocal systems for detailed subcellular localization studies.
- Digital Microscopy:These systems capture and digitize images for computer-aided analysis, integrating AI for automated quantification and pattern recognition. Diagnostic laboratories adopt digital microscopy to accelerate workflows and standardize diagnostic outputs.
- Widefield Microscopy:A foundational imaging method, widefield microscopy illuminates the entire field of view, providing broad contextual information. Academic research centers frequently employ widefield systems for general fluorescence observation.
- Flow Cytometry:This technology rapidly analyzes and sorts cells based on their light scattering and fluorescent properties as they pass through a laser beam. Pharmaceutical companies use flow cytometry for high-throughput drug screening and cell population analysis.
Each technology offers distinct advantages, focusing on specific analytical needs.
End User:
End-user segments for immunofluorescence analyzers are largely defined by their sample volume requirements and operational scale, influencing system configuration and integration needs.
- Diagnostic Laboratories:These facilities process large numbers of patient samples for disease diagnosis, requiring high-throughput and reproducible analytical systems. Demand from diagnostic laboratories in Europe is driven by increasing prevalence of autoimmune disorders.
- Research Institutions:Academic and government research centers utilize immunofluorescence analyzers for fundamental biomedical discovery and translational studies. Substantial government funding in the United States supports the acquisition of advanced imaging instrumentation.
- Hospitals:Clinical departments within hospitals use immunofluorescence analyzers for immediate patient diagnostics and specialized testing. Hospitals integrate these systems into larger diagnostic workflows, particularly for pathology.
- Pharmaceutical Companies:Drug discovery and development pipelines employ immunofluorescence for biomarker validation, drug efficacy testing, and toxicology studies. Pharmaceutical research organizations value systems offering high-specificity protein expression data.
Diagnostic Laboratories and Research Institutions represent the strategic importance of specialized diagnostic capabilities.
Application:
The choice of immunofluorescence analyzer application is primarily dictated by its clinical utility in diagnosing specific disease states and advancing biomedical understanding.
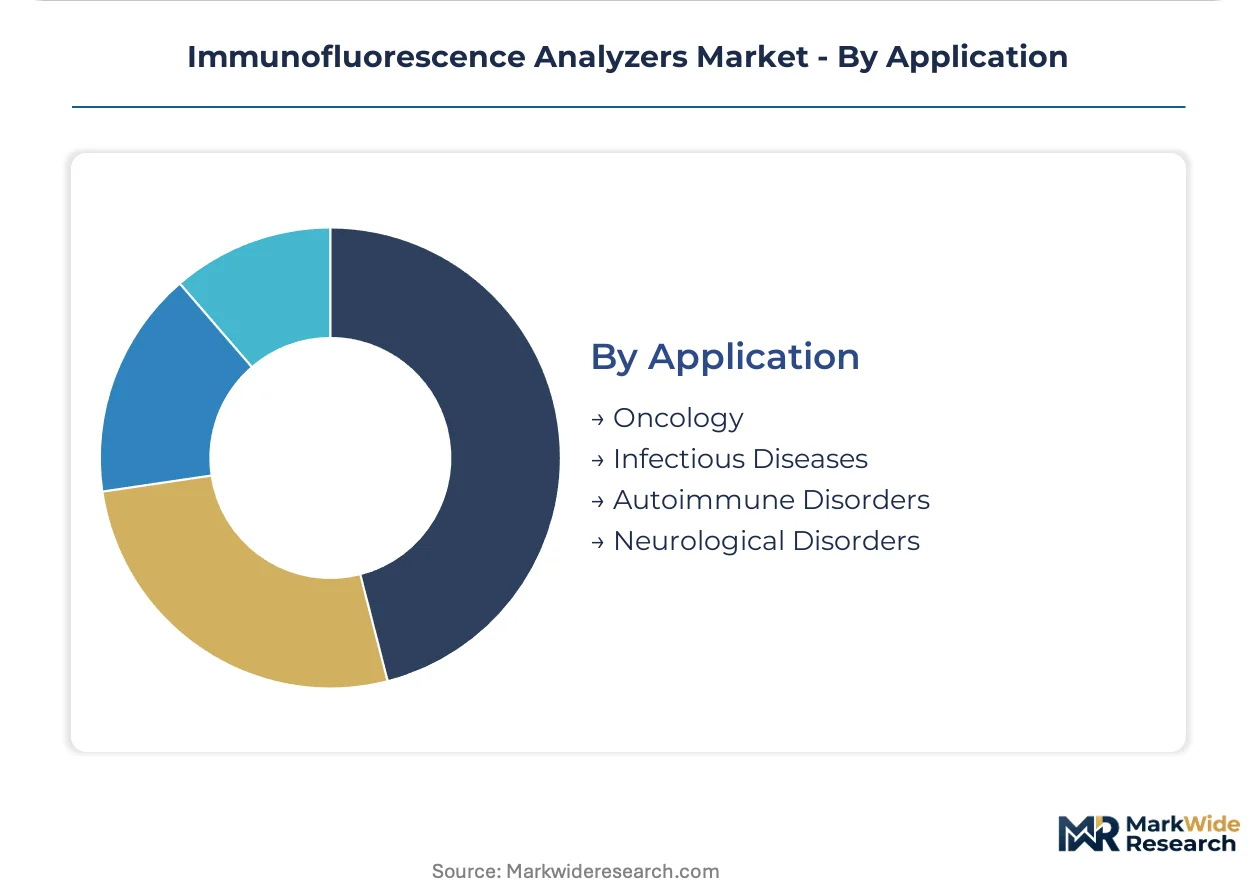
- Oncology:Immunofluorescence analyzers provide critical data on biomarker expression and localization, supporting cancer diagnosis, prognosis, and personalized treatment strategies. The expanding field of biomarker discovery in oncology fuels demand for these systems.
- Autoimmune Disorders:These applications involve detecting autoantibodies and immune complex deposits in patient samples, crucial for diagnosing conditions like lupus and rheumatoid arthritis. Diagnostic laboratories rely on immunofluorescence for precise autoimmune disease characterization.
- Infectious Diseases:Immunofluorescence assays identify specific pathogens or host immune responses, aiding in the diagnosis of viral, bacterial, and parasitic infections. Public health laboratories use immunofluorescence for rapid detection of infectious agents.
- Neurological Disorders:Research into conditions such as Alzheimer's and Parkinson's disease uses immunofluorescence to visualize protein aggregates and cellular pathology. Biomedical researchers apply these analyzers for understanding neurodegenerative processes.
Oncology and Autoimmune Disorders are driving innovation in biomarker discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The immunofluorescence analyzers market initially scaled in established research and diagnostic hubs, particularly in North America and Western Europe. These regions provided the foundational investment and scientific expertise necessary for early technological development. Today, demand continues to concentrate in these mature markets, driven by ongoing biomedical research and diagnostic innovation.
United States
The United States market exhibits strong demand from personalized medicine initiatives and biomarker discovery in oncology. FDA regulations for software as a medical device heavily influence product development and validation timelines. Major biotech clusters in Boston and the San Francisco Bay Area drive innovation in advanced imaging instrumentation.
Germany
Germany's market for immunofluorescence analyzers is propelled by substantial government funding for biomedical research and the prevalence of advanced research institutions. The EU's Medical Device Regulation (MDR) sets stringent performance and safety standards for market entry. Academic and clinical research centers in Heidelberg and Munich are key adopters of high-resolution confocal systems.
China
China's market presents significant growth potential as diagnostic infrastructure upgrades from manual to automated systems. The NMPA governs market entry, often requiring local clinical data for high-risk medical devices. Major diagnostic laboratories and emerging biotech parks in the Yangtze River Delta are driving automation adoption.
Japan
Japan's pharmaceutical companies and advanced research institutions generate demand for high-specificity protein expression data and cell analysis. The PMDA ensures strict regulatory oversight for medical devices, impacting product development and approval processes. Tokyo and Osaka host significant pharmaceutical R&D centers and advanced medical facilities.
United Kingdom
The United Kingdom's market benefits from robust clinical research facilities and academic laboratories focused on fundamental biomedical discovery. The MHRA establishes medical device regulations, ensuring compliance for devices entering the UK market. Biomedical research hubs in London and Cambridge are key sites for advanced immunofluorescence applications.
Immunofluorescence Analyzers Market Key Industry Players
The competitive structure tilts toward integrated solution providers offering end-to-end workflows rather than standalone instruments. This market features a mix of diversified diagnostic conglomerates and specialized technology developers, creating a tiered landscape. Strategic archetypes include comprehensive system vendors, reagent specialists, and software-focused innovators driving automation. Companies are increasingly focused on portfolio diversification and embedding their analyzers into larger diagnostic ecosystems to capture a broader market share.
Integrated solution providers such as Thermo Fisher Scientific, a US-based entity, and Siemens Healthcare, a German-headquartered group, exemplify companies leveraging extensive portfolios to serve both research and clinical laboratories. These major players often emphasize fully integrated systems, combining hardware with advanced imaging software and reagent supply. Bio-Rad Laboratories, another US-based firm, represents the archetype of a specialist in high-specificity antibodies and reagents, often targeting niche research applications. These firms anchor various segments of the immunofluorescence analyzer market by addressing distinct customer needs.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Siemens Healthcare |
| BioMerieux |
| EMD Millipore |
| DiaSorin S.p.A. |
| PerkinElmer Inc. |
| Bio-Rad Laboratories |
| Beckman Coulter |
| Others |
Cost & Logistics Intelligence
Diagnostic laboratories' concentrated demand for fully integrated systems is shifting pricing models toward comprehensive bundled solutions. This trend favors vendors offering complete hardware, software, and reagent packages.
Pricing Analysis
Bundled procurement models dominate, offering laboratories simplified purchasing and predictable operational costs over multi-year agreements. Price differentiation stems from the sophistication of integrated imaging software, the breadth of after-sales service, and the established brand premium of comprehensive solution providers. Pricing pressure arises from the significant initial capital investment required for automated systems, particularly impacting smaller research laboratories and clinics. Large diagnostic labs and pharmaceutical companies exhibit lower price sensitivity, prioritizing workflow efficiency and long-term cost of ownership.
Supply Chain Analysis
Dual-sourcing requirements for critical components like fluorophore-conjugated antibodies and advanced optical sensors enhance manufacturing supply resilience. Geographic supply concentration for specialized inputs draws from established R&D hubs in the United States and Germany. Supply chain risk centers on stringent regulatory hurdles from the EU MDR and US FDA, which extend development timelines and increase validation costs for novel components. Distribution runs primarily through direct sales channels for complex integrated systems and specialized distributors for niche reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market acts as a regulatory compounder, with the EU Medical Device Regulation (MDR) driving demand for robust clinical validation and performance documentation across all device classes.
For Market Incumbents:
Deploy portfolio diversification to offer comprehensive end-to-end workflow solutions across both research and clinical laboratories. Integrate advanced AI-powered image analysis capabilities to counter specialized software innovators and enhance diagnostic reproducibility. Expand long-term service agreements and bundled reagent supply contracts to mitigate customer concerns regarding high capital cost and system integration complexity. Proactive investment in regulatory compliance for software as a medical device will be crucial to maintain market leadership.
For New Entrants and Emerging Players:
A price-point gap exists between premium automated systems and the budget constraints of smaller laboratories and clinics. Target underpenetrated segments like emerging markets in Asia-Pacific or specialized point-of-care settings requiring portable analyzers. Offer modular, scalable solutions with a lower initial investment and simplified integration into existing workflows. Focus on niche applications or specific biomarker detection for a clear go-to-market angle, emphasizing cost-efficiency.
For Investors and Strategic Acquirers:
Diversified diagnostic conglomerates are the most active acquirers in this space, seeking to bolster their integrated solution offerings and expand market reach. The long-term viability of the market hinges on continued advancements in personalized medicine and automation over the coming 5-10 year window. Target firms with proprietary AI imaging software, advanced multiplexing capabilities, or high-specificity reagent portfolios that address critical diagnostic needs. The signal to watch is increased regulatory clarity and accelerated approval pathways for novel digital pathology solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop next-generation AI algorithms | Enhances diagnostic accuracy and reduces operator variability for clinical labs. |
| Expand modular hardware platforms | Increases system flexibility and scalability for diverse research institutions. |
| Form strategic partnerships | Integrates immunofluorescence analyzers into broader hospital diagnostic workflows. |
| Invest in multiplexing capabilities | Conserves precious patient samples and improves diagnostic efficiency in oncology. |
| Navigate NMPA approval processes | Unlocks significant growth potential in China's upgrading diagnostic infrastructure. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive market view. Primary research involved discussions with diagnostic lab directors, research scientists, regulatory affairs specialists, and procurement managers. Secondary validation drew from FDA guidance documents, EU MDR guidelines, NMPA announcements, and academic journals. This approach enabled robust bottom-up and top-down triangulation of market data.
The segment-weighting approach informed market size estimation and forecast modeling across the analysis window. Segmentation dimensions included product type, technology, end user, application, and regional regulatory clusters. Compound annual growth rates were derived from historical data and projected growth drivers, including biomarker discovery rates and government research funding. These inputs shaped the quantitative market outlook.
Caveats apply where rapid technological disruption, unforeseen regulatory changes, or significant shifts in research funding could materially shift the outlook. Forecasts reflect assumptions regarding current market dynamics and expected innovation trajectories. Deviation in biomarker discovery rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Nucleic Acid Electrophoresis and Blotting Market
Biomedical Technology
Neoantigen Market
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Global Cell Dissociation Market