
 PD L1 Biomarker Testing Market | 2026-2036
PD L1 Biomarker Testing Market Size, Share, and Industry Trends Forecast 2026-2036
PD L1 Biomarker Testing Market Outlook
The capital-intensity divergence between automated immunohistochemistry platforms and manual assay workflows is redrawing competitive boundaries in PD-L1 testing. F. Hoffmann-La Roche Ltd leverages its integrated Ventana platform to dominate high-throughput pathology networks. Thermo Fisher Scientific anchors its position through broad menu expansion across oncology biomarkers. NeoGenomics Laboratories, Inc. specializes in centralized reference laboratory services for community oncology practices.
PD-L1 biomarker testing quantifies programmed death-ligand 1 protein expression in tumor tissue or circulating samples, typically reported as a tumor proportion score or combined positive score to guide immune checkpoint inhibitor therapy decisions. The assay requires validated antibodies, calibrated scoring algorithms, and CLIA-certified laboratory environments to ensure clinical utility. Immunohistochemistry occupies the largest installed base due to regulatory precedents and pathologist familiarity, while next-generation sequencing competes fastest as multiplex panels consolidate biomarker workflows. Diagnostic laboratories capture disproportionate margin pools through volume-based contracts with pharmaceutical sponsors.
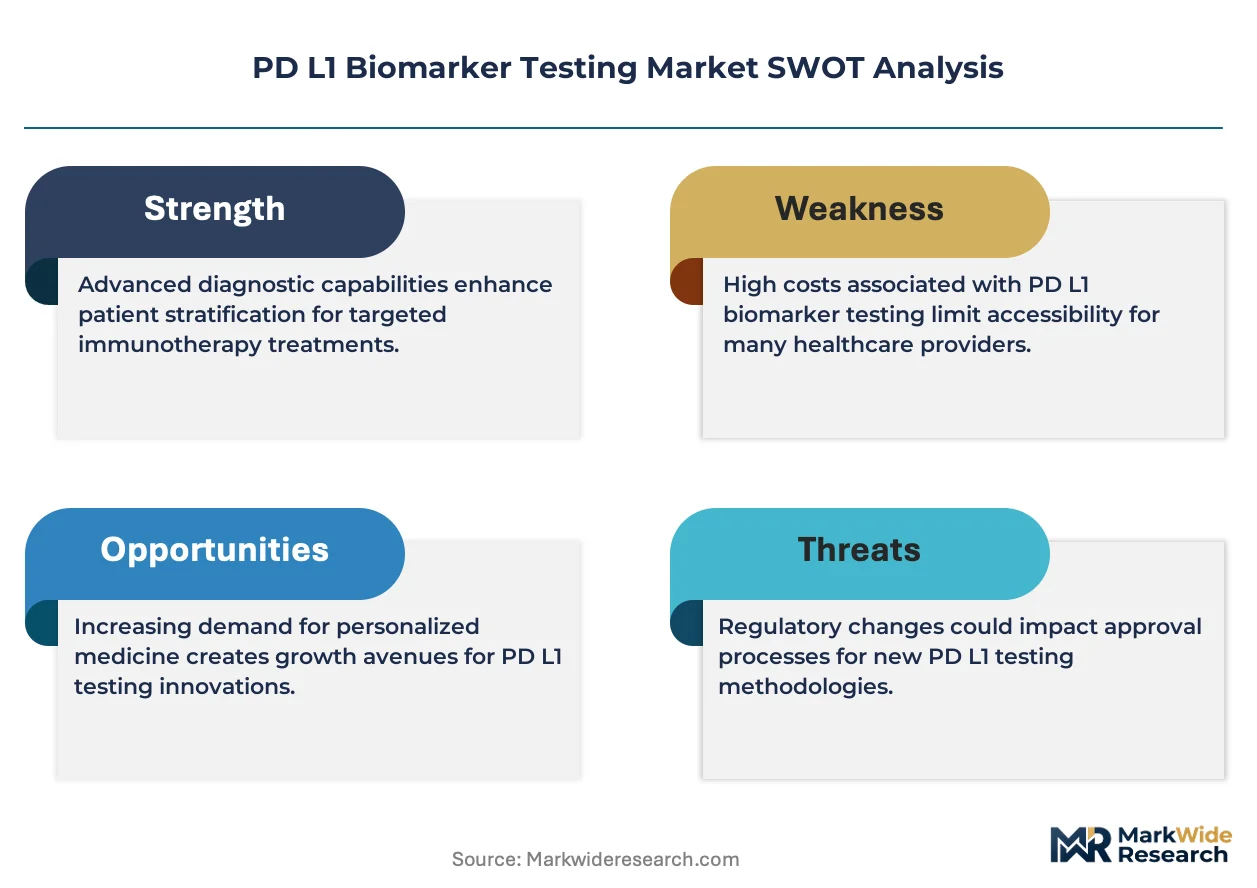
FDA oversees premarket approval and companion diagnostic co-development requirements, while EMA enforces in vitro diagnostic regulation harmonization across European member states. CLIA and CAP accreditation standards shape laboratory market access and reimbursement eligibility in the United States. Stakeholders must monitor evolving PD-L1 expression thresholds across tumor indications and assay-specific scoring harmonization efforts.
Market Dynamics
Companion diagnostic co-development mandates from FDA and EMA are forcing pharmaceutical sponsors to integrate PD-L1 testing earlier in clinical trial design, compressing timelines between biomarker validation and therapy approval.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation harmonization:Streamlined CE marking pathways accelerate assay commercialization across European member states, reducing duplicate validation studies.
- Academic medical center pathology networks:Centralized immunohistochemistry infrastructure at oncology departments enables standardized scoring and inter-laboratory concordance programs.
- Liquid biopsy sample processing:Circulating tumor DNA platforms expand testing access to patients with insufficient tissue for surgical biopsy.
Market Restraints
- Antibody reagent supply concentration:Validated PD-L1 clone production centers in the United States and Germany create single-source dependencies for diagnostic manufacturers.
- Assay-specific scoring threshold heterogeneity:Discordant cutoffs between 22C3, 28-8, SP142, and SP263 clones complicate pathologist training and clinical interpretation.
- Manual workflow labor intensity:Subjective visual assessment requirements limit throughput and introduce inter-observer variability in community laboratory settings.
Strategic Opportunities
- Japan's PMDA biomarker qualification pathway:Streamlined validation frameworks for companion diagnostics create first-mover advantages for multiplex assay developers.
- Artificial intelligence-powered image analysis:Machine learning algorithms trained on tumor proportion scoring reduce pathologist burden and improve reproducibility.
- Community oncology practice reference laboratory outsourcing:Centralized testing partnerships address CLIA certification gaps in smaller pathology groups.
Industry Challenges
- Dual-trained molecular pathologist scarcity:Shortage of professionals credentialed in both immunohistochemistry interpretation and next-generation sequencing analysis constrains laboratory expansion.
- Cross-platform scoring harmonization delays:Industry consortia struggle to align tumor proportion score and combined positive score methodologies across automated platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PD L1 Biomarker Testing Market |
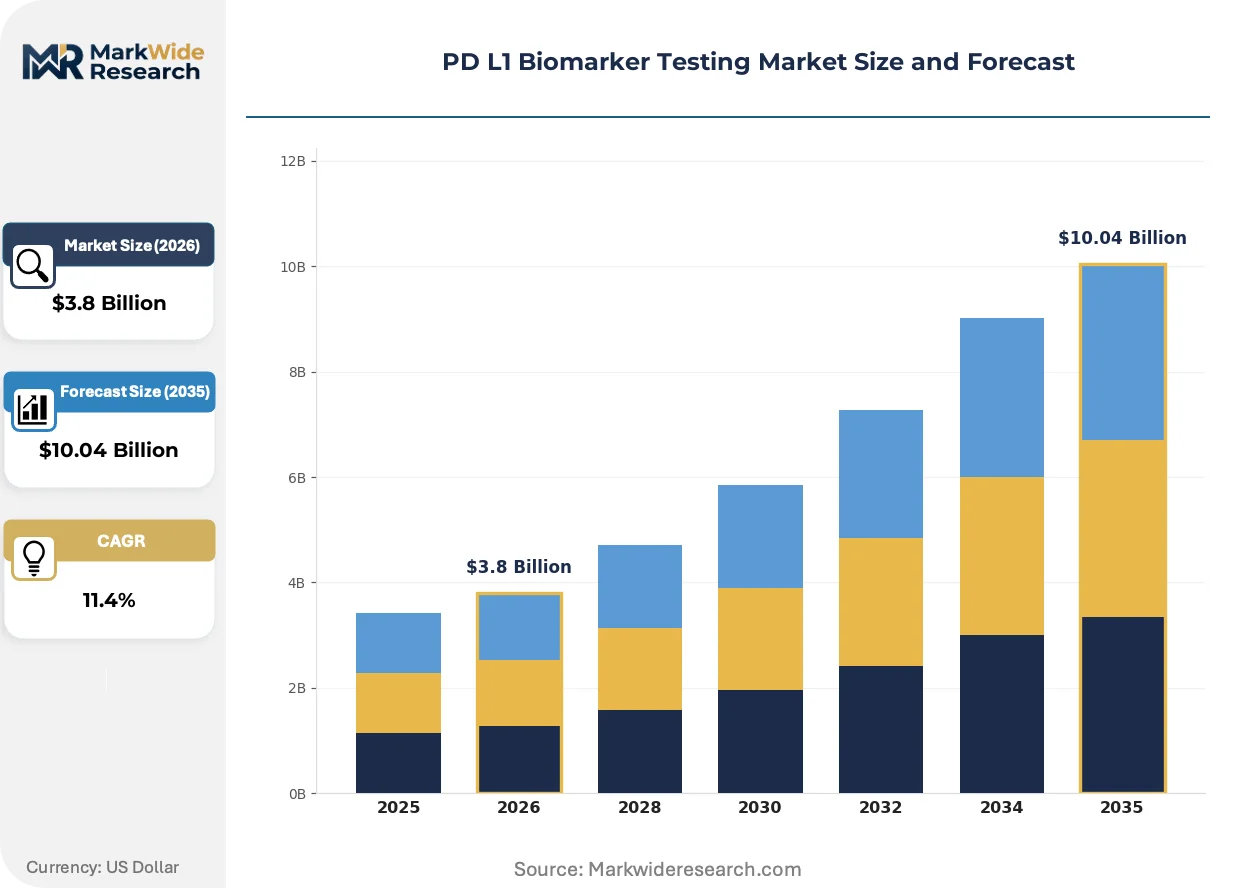
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Immunohistochemistry, PCR, Next-Generation Sequencing, In Situ Hybridization Application: Cancer Diagnosis, Treatment Monitoring, Prognosis, Clinical Trials End User: Hospitals, Diagnostic Laboratories, Research Institutions, Oncologists Technology: Microarray, Flow Cytometry, Fluorescence In Situ Hybridization, RNA Sequencing |
| Companies Covered | F. Hoffmann-La Roche Ltd, Agilent Technologies, Inc., Merck & Co., Inc., Bristol-Myers Squibb, Thermo Fisher Scientific, NeoGenomics Laboratories, Inc., AstraZeneca, Regeneron, Ono Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PD L1 Biomarker Testing Market Strategic Shifts
Multiplex biomarker panels are consolidating oncology testing workflows, compressing the historical separation between single-analyte immunohistochemistry and comprehensive genomic profiling into unified diagnostic protocols.
Next-generation sequencing is decomposing the traditional dominance of immunohistochemistry in PD-L1 testing by enabling simultaneous quantification of PD-L1 expression alongside tumor mutational burden and microsatellite instability. Academic medical centers in Germany and Japan are adopting these panels for first-line non-small cell lung cancer workups. This convergence is compressing reimbursement pathways toward bundled biomarker testing rather than discrete assay billing.
FDA's evolving companion diagnostic labeling requirements are narrowing the acceptable variance between laboratory-developed tests and kit-based assays, forcing reference laboratories to pursue premarket approval pathways previously reserved for manufacturers. The agency's 2024 guidance on assay transfer validation has extended timeline requirements for platform migration. Community oncology practices in the United States are responding by consolidating testing contracts with CAP-accredited central laboratories.
Pathology groups are unbundling interpretive services from technical processing, creating standalone professional component billing for complex scoring cases. Community hospitals in Japan and Germany are outsourcing slide review to specialized telepathology networks while retaining specimen preparation in-house. This bifurcation is most pronounced in rural United States markets where board-certified pathologist density falls below metropolitan benchmarks.
PD L1 Biomarker Testing Market Segmentation
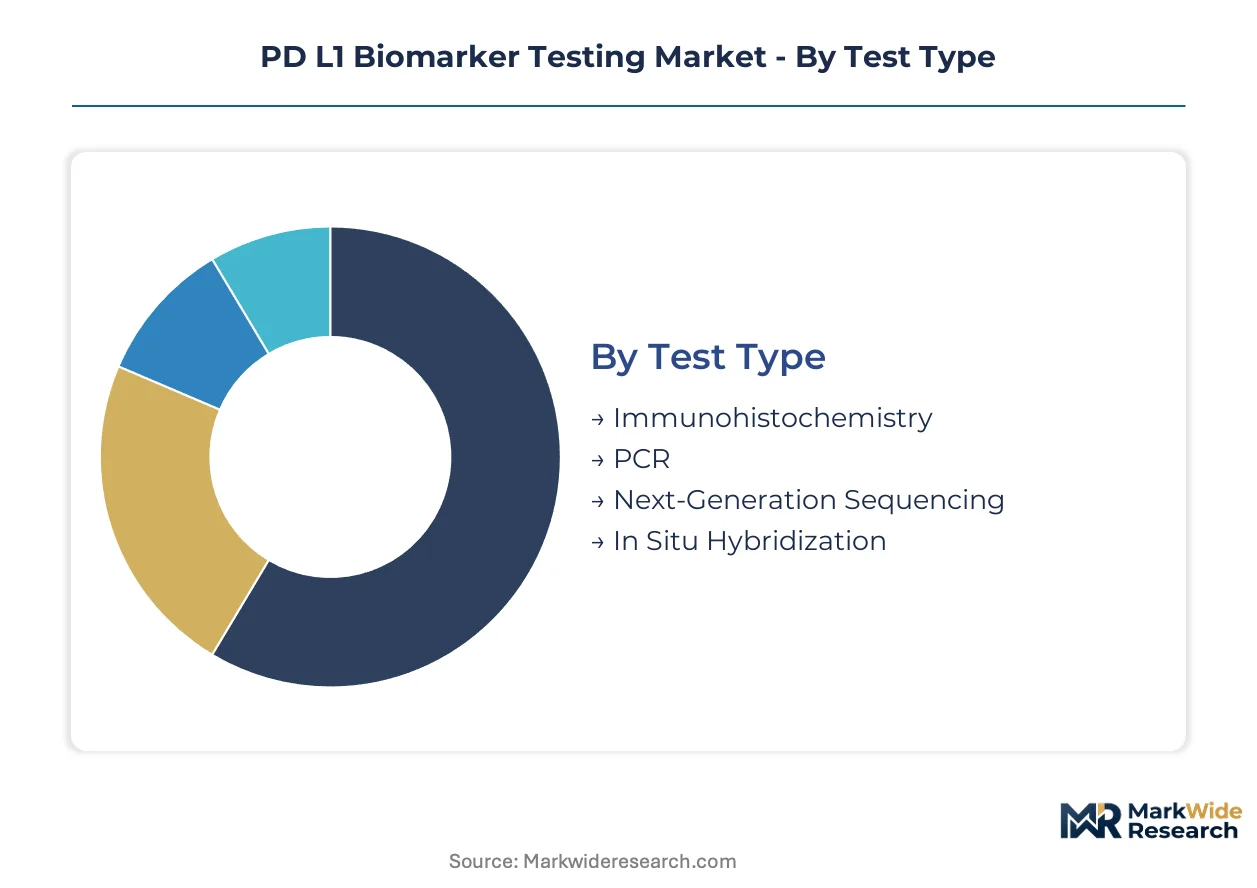
PD-L1 testing workflows fragment across four distinct analytical dimensions. Each segmentation layer reveals divergent margin structures, regulatory burdens, and vendor competitive positions that shape procurement decisions in academic medical centers and community oncology networks.
Test Type:
Domestic laboratory infrastructure in the United States, Germany, and Japan anchors immunohistochemistry demand, while PCR and next-generation sequencing platforms increasingly serve export-oriented reference laboratory networks.
- Immunohistochemistry:Chromogenic antibody-based detection on formalin-fixed paraffin-embedded tissue sections using validated PD-L1 clones. CAP-accredited pathology laboratories in the United States concentrate demand for high-throughput automated platforms like Ventana and Dako Link 48. Labor intensity and subjective scoring requirements constrain expansion in resource-limited settings.
- PCR:Amplification-based quantification of PD-L1 mRNA expression from extracted nucleic acids. German academic medical centers deploy PCR for rapid turnaround in non-small cell lung cancer triage where tissue quantity limits immunohistochemistry feasibility. Sensitivity advantages compete against limited spatial resolution.
- Next-Generation Sequencing:Multiplex panels consolidate PD-L1 expression quantification with tumor mutational burden and microsatellite instability profiling. Japanese PMDA-qualified companion diagnostic pathways accelerate adoption at National Cancer Center hospitals in Tokyo.
- In Situ Hybridization:RNAscope and DNA probe technologies detect PD-L1 transcripts with cellular resolution. Niche applications in research settings and pharmaceutical biomarker qualification studies.
Immunohistochemistry commands the established base. The steepest expansion runs through next-generation sequencing.
Application:
Cost tier differentiation separates premium-priced companion diagnostic-linked testing from standard-of-care monitoring applications with compressed reimbursement.
- Cancer Diagnosis:Frontline PD-L1 testing to establish immune checkpoint inhibitor eligibility in treatment-naive patients. FDA premarket approval requirements for companion diagnostics concentrate highest-value contracts at CAP-accredited laboratories with pharmaceutical sponsor partnerships.
- Treatment Monitoring:Serial biomarker assessment to detect acquired resistance or pseudoprogression during anti-PD-1/PD-L1 therapy. Community oncology practices in rural United States markets outsource to centralized reference laboratories lacking in-house pathology capacity.
- Prognosis:Baseline PD-L1 expression correlation with survival outcomes in retrospective analyses. Academic research protocols at German Comprehensive Cancer Centers drive methodological standardization efforts.
- Clinical Trials:Centralized biomarker qualification for pharmaceutical sponsor studies. EMA In Vitro Diagnostic Regulation harmonization streamlines CE marking for European multi-site enrollment.
Cancer diagnosis captures premium pricing. Treatment monitoring is climbing the fastest as longitudinal testing protocols expand.
End User:
Customer type fragmentation splits procurement between integrated health systems with captive laboratory infrastructure and outsourced reference laboratory relationships.
- Hospitals:In-house anatomic pathology departments with CLIA certification performing same-day immunohistochemistry for urgent treatment decisions. Academic medical centers in Japan and Germany maintain dedicated PD-L1 assay validation programs.
- Diagnostic Laboratories:High-volume reference operations processing specimens from dispersed oncology practices. NeoGenomics and similar centralized providers capture community hospital outsourcing in the United States.
- Research Institutions:Exploratory biomarker studies and assay development programs. National Cancer Institute-designated centers in the United States drive novel clone validation.
- Oncologists:Direct ordering of send-out testing with professional component interpretation. Rural practice consolidation accelerates reference laboratory dependency.
Diagnostic laboratories command the established base. Hospitals are gaining share fastest through vertical integration of pathology services.
Technology:
Maturity gradients separate established microarray and flow cytometry platforms from emerging RNA sequencing methodologies with unproven reimbursement pathways.
- Microarray:Gene expression profiling arrays quantifying PD-L1 alongside immune-related gene signatures. Pharmaceutical biomarker discovery applications predominate over clinical diagnostic use.
- Flow Cytometry:Cell surface PD-L1 detection on circulating tumor cells and immune cell subsets. Specialized applications at German hematology-oncology centers for liquid biopsy correlation studies.
- Fluorescence In Situ Hybridization:Dual-color break-apart and fusion probes for PD-L1 gene rearrangement detection. Research tool status pending clinical validation for solid tumor applications.
- RNA Sequencing:Whole-transcriptome quantification enabling PD-L1 expression analysis within comprehensive immune profiling. Japanese PMDA biomarker qualification pathway accelerates regulatory acceptance for multiplex oncology panels.
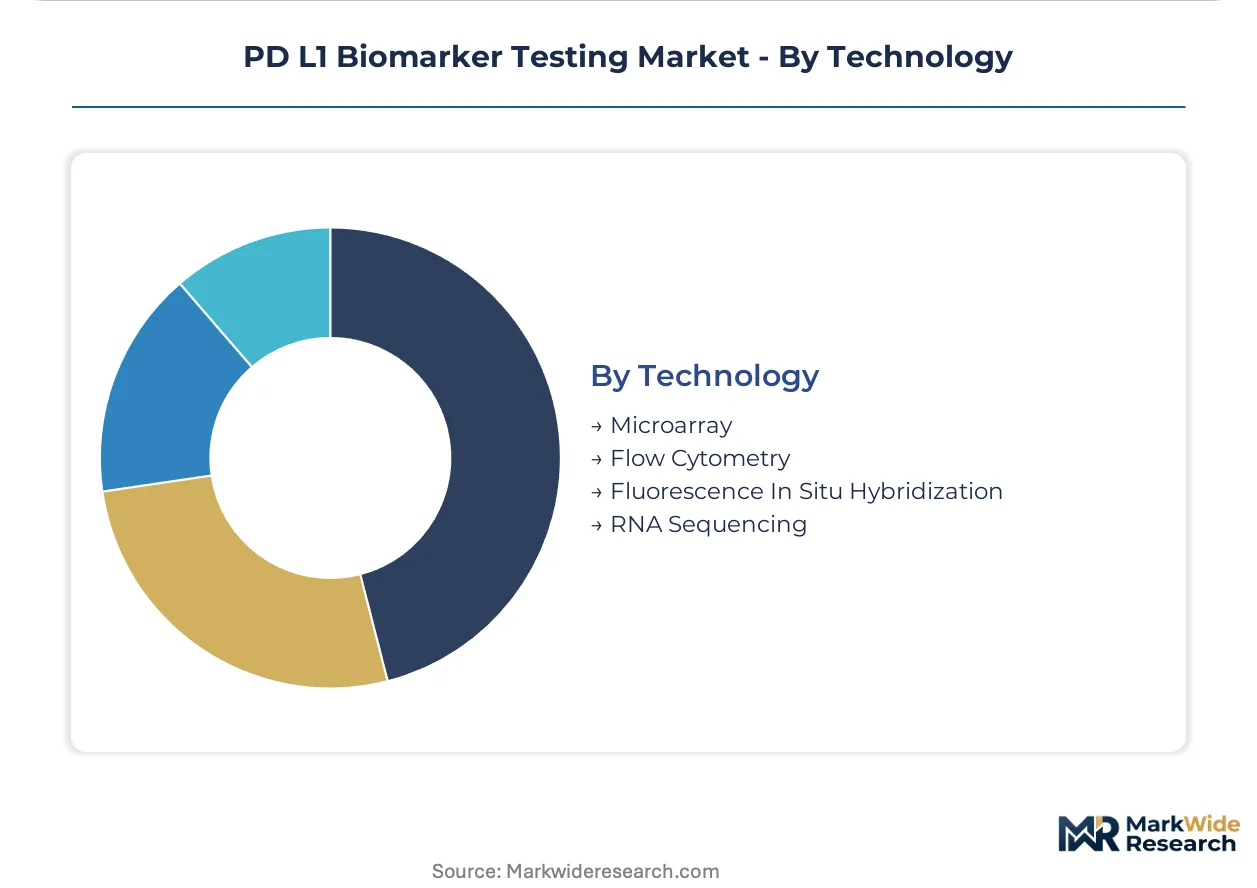
Microarray commands the established base. RNA sequencing shows the steepest expansion trajectory as comprehensive genomic profiling consolidates testing menus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PD-L1 testing consumption patterns diverge sharply by healthcare infrastructure maturity. The United States and Germany concentrate high-throughput automated immunohistochemistry, while Japan and emerging markets accelerate multiplex next-generation sequencing adoption for first-line oncology workups.
United States
Academic medical centers in Boston and Houston drive companion diagnostic co-development with pharmaceutical sponsors. FDA premarket approval requirements for PD-L1 assays concentrate highest-value contracts at CAP-accredited laboratories. The National Cancer Institute's designated cancer centers in Maryland and Texas anchor biomarker qualification studies for novel immunotherapy combinations.
Germany
Comprehensive Cancer Centers in Heidelberg and Munich standardize PD-L1 scoring algorithms across regional pathology networks. EMA In Vitro Diagnostic Regulation harmonization enables streamlined CE marking for multiplex assay developers. The Rhine-Ruhr metropolitan region hosts centralized reference laboratories processing specimens from dispersed community oncology practices.
Japan
National Cancer Center hospitals in Tokyo deploy PMDA-qualified companion diagnostic pathways for non-small cell lung cancer triage. PMDA biomarker qualification frameworks accelerate regulatory acceptance of RNA sequencing panels. Osaka-based pathology groups consolidate telepathology interpretive services for rural prefectures lacking board-certified specialists.
United Kingdom
NHS England's specialized commissioning frameworks concentrate PD-L1 testing at designated genomic laboratory hubs in London and Manchester. MHRA alignment with EMA standards reduces duplicate validation burdens for assay manufacturers. The Cambridge-Oxford-London golden triangle anchors pharmaceutical biomarker discovery partnerships.
Switzerland
Swissmedic's streamlined companion diagnostic approval pathways attract pharmaceutical sponsors conducting multi-site European trials. Basel's pharmaceutical cluster drives demand for standardized PD-L1 assay validation across Roche's integrated diagnostic networks. Zurich academic medical centers participate in EORTC harmonization studies for tumor proportion scoring methodologies.
PD L1 Biomarker Testing Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in PD-L1 testing. Pharmaceutical-diagnostic conglomerates and diversified life science platforms occupy the upper tier through captive companion diagnostic pipelines. Specialist reference laboratories and precision oncology service providers populate the lower tier through outsourced testing relationships. Competitive moves center on assay menu expansion and centralized laboratory network consolidation.
Among Swiss and American integrated diagnostics platforms, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific exemplify the vertically consolidated archetype through automated platform dominance. NeoGenomics Laboratories, Inc. represents the centralized reference laboratory model serving community oncology practices with outsourced immunohistochemistry and next-generation sequencing services.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Agilent Technologies, Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb |
| Thermo Fisher Scientific |
| NeoGenomics Laboratories, Inc. |
| AstraZeneca |
| Regeneron |
| Ono Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Automated immunohistochemistry platform substitution for manual assay workflows is redrawing supply geography toward the United States and Germany while compressing pricing economics at the mid-market tier. This equipment transition simultaneously concentrates procurement power among CAP-accredited laboratory networks and erodes margins for decentralized manual processors.
Pricing Analysis
Reagent rental and service contract tiers drive lifetime value capture for platform manufacturers. Three-tier pricing structure across premium companion diagnostic-linked testing, standard clinical laboratory services, and economy research-grade assays stratifies the market. Price differentiation rests on FDA premarket approval status and pharmaceutical sponsor co-development relationships. Cost compression in the standard tier is intensifying because community oncology practices are consolidating contracts with high-volume reference laboratories. Community hospitals in rural United States markets exhibit highest price sensitivity; academic medical centers with captive companion diagnostic pipelines show least.
Supply Chain Analysis
The United States and Germany anchor validated PD-L1 clone production, while Japan and Switzerland concentrate precision optics and automated platform assembly. Antibody reagent supply draws from hybridoma cell line repositories and recombinant protein expression systems. Single-source dependencies for diagnostic-grade clone SP142 and SP263 create vulnerability to manufacturing site disruptions. Distribution runs through CAP-accredited reference laboratory networks and direct pharmaceutical sponsor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PD-L1 testing market fragmentation creates opportunity across three demand-side niches: liquid biopsy sample processing for tissue-insufficient patients, artificial intelligence-powered image analysis for community pathologist shortage markets, and centralized reference laboratory outsourcing for rural oncology practices.
For Market Incumbents: Shield companion diagnostic co-development relationships through accelerated FDA premarket approval timelines for multiplex assay platforms. Deepen backward integration into validated antibody clone production to reduce single-source supplier exposure. Prioritize CAP accreditation maintenance as community hospital consolidation accelerates reference laboratory dependency. For New Entrants and Emerging Players: Differentiate on artificial intelligence-powered tumor proportion scoring algorithms trained for inter-observer variability reduction. Target Japan's PMDA biomarker qualification pathway for RNA sequencing panel regulatory acceptance. Pursue telepathology interpretive services partnerships with German Comprehensive Cancer Center networks lacking board-certified pathologist density. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed centralized reference laboratories holding CAP-accredited immunohistochemistry infrastructure. Five-to-ten year viability hinges on companion diagnostic co-development pipeline depth and pharmaceutical sponsor contract renewal rates. Monitor FDA guidance evolution on laboratory-developed test premarket approval requirements as inflection indicator for reference laboratory valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA premarket approval pathways concentrate highest-value contracts at CAP-accredited laboratories with pharmaceutical sponsor partnerships. |
| Artificial Intelligence Image Analysis | Machine learning algorithms trained on tumor proportion scoring reduce pathologist burden and improve reproducibility across community laboratory networks. |
| Liquid Biopsy Platform Expansion | Circulating tumor DNA processing addresses tissue-insufficient patient populations and extends testing access beyond surgical biopsy constraints. |
| Centralized Reference Laboratory Consolidation | High-volume contracts with community oncology practices capture economies of scale in immunohistochemistry and next-generation sequencing workflows. |
| PMDA Biomarker Qualification Pathway | Japanese regulatory frameworks accelerate RNA sequencing panel adoption at National Cancer Center hospitals in Tokyo and Osaka. |
Study Parameters
Initial hypotheses were tested against primary input from pathology laboratory directors, pharmaceutical biomarker development leads, regulatory affairs specialists at diagnostic manufacturers, and hospital procurement managers; findings were refined against FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, ClinicalTrials.gov companion diagnostic study records, and CAP laboratory accreditation databases. Bottom-up testing volume estimates from CLIA-certified facilities were triangulated against top-down pharmaceutical sponsor biomarker spending allocations.
Variance decomposition across test type, application, end user, and technology dimensions shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and pricing elasticity assumptions throughout the forecast period. Industry-specific inputs included PD-L1 assay-specific scoring threshold harmonization progress and EMA regulatory implementation timelines across European member states.
The analysis sits within stated boundaries; outcomes outside sustained FDA-EMA regulatory alignment or accelerated artificial intelligence diagnostic software approval pathways would require recalibration. Forecasts reflect assumptions regarding companion diagnostic co-development pipeline maturation and academic medical center pathology network consolidation. Recalibration cycles align with material shifts in FDA guidance on laboratory-developed test oversight and PMDA biomarker qualification framework adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Global RNA Analysis Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Cell Proliferation Assay Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Enzymatic DNA Synthesis Market