
 Neoantigen Market | 2026-2036
Neoantigen Market Size, Share, and Industry Trends Forecast 2026-2036
Neoantigen Market Analysis
Modular trial designs that unbundle monotherapy from combination protocols is realigning how pharmaceutical buyers evaluate neoantigen platforms. BioNTech SE leverages its mRNA manufacturing infrastructure to sustain clinical supply across multiple oncology programs. Moderna Inc anchors its position through R&D intensity in personalized cancer vaccines. Merck & Co Inc competes by extending its immuno-oncology franchise into combination regimens with neoantigen-directed therapies.
Neoantigens are tumor-specific peptides arising from somatic mutations, typically eight to eleven amino acids in length, presented on major histocompatibility complex molecules to elicit T-cell recognition and immune-mediated tumor destruction. RNA-based antigens lead current development pipelines due to rapid manufacturing turnaround and flexible encoding capacity, while bioinformatics platforms represent the fastest-growing technology segment as computational prediction of immunogenic epitopes becomes central to patient selection. Genomic sequencing occupies a mature but essential position, forming the data foundation upon which downstream proteomic validation and mass spectrometry confirmation depend.
The FDA breakthrough therapy designation and the EMA's PRIME scheme shape clinical development economics by compressing regulatory review timelines for neoantigen therapies, while the FDA's draft guidance on co-development of in vitro companion diagnostics directly impacts market access for personalized products. The NIH's funding mechanisms and the NCI's alliance for personalized cancer vaccines further structure early-stage research priorities. Stakeholders must monitor how evolving FDA standards for individualized manufacturing lot release will reshape quality control investments and capacity planning across contract development networks.
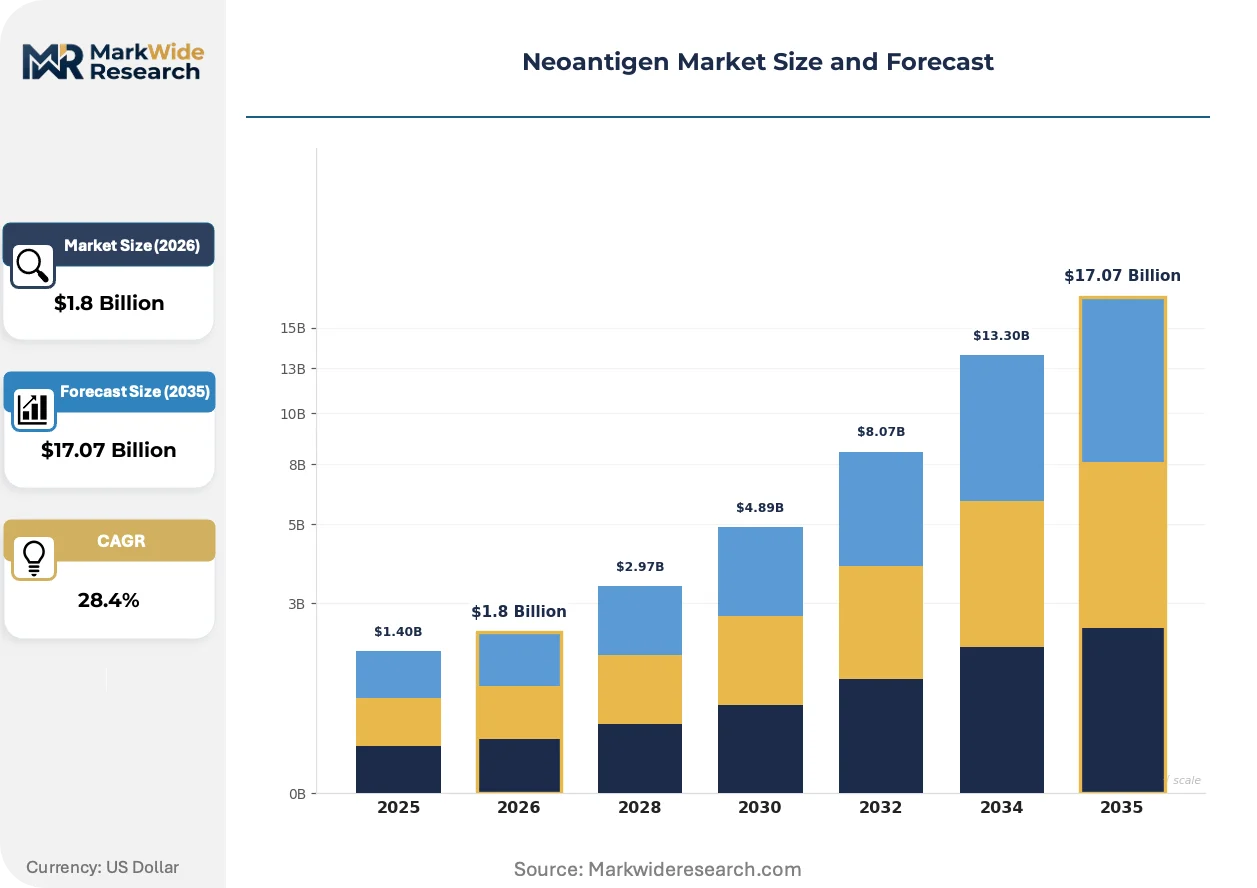
Market Dynamics
Modular trial designs unbundling monotherapy from combination protocols are compressing clinical development timelines and forcing pharmaceutical buyers to reassess platform economics across neoantigen pipelines.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway accelerates regulatory review timelines for personalized cancer vaccines, reducing time-to-market for qualifying candidates and attracting venture capital into early-stage biotech development.
- RNA Manufacturing Infrastructure:Rapid turnaround capabilities for individualized mRNA vaccines enable just-in-time production matched to patient mutation profiles, collapsing the gap between biopsy and dosing.
- Oncology Center Concentration:Major academic medical centers in the United States are building dedicated neoantigen production facilities, creating captive demand that anchors regional supply chain investments.
Market Restraints
- Companion Diagnostic Co-Development:FDA draft guidance requiring parallel validation of in vitro diagnostics imposes dual-track regulatory burden and extends pre-market timelines for personalized products.
- Bioinformatics Talent Scarcity:Computational immunology expertise concentrates in a narrow geographic band around Boston, San Francisco, and Basel, creating recruitment bottlenecks for distributed development programs.
- Mass Spectrometry Validation Costs:Proteomic confirmation of predicted epitopes requires specialized equipment and consumables that inflate per-patient manufacturing costs beyond standard biologics thresholds.
Strategic Opportunities
- EMA PRIME Scheme Expansion:Priority medicines designation in Europe offers accelerated assessment pathways that mirror FDA breakthrough status, enabling parallel market entry strategies across Atlantic jurisdictions.
- Solid Tumor Indication Diversification:Melanoma and non-small cell lung cancer proof-of-concept data is expanding into pancreatic, colorectal, and glioblastoma cohorts where immunotherapy response rates remain suboptimal.
- Artificial Intelligence Epitope Prediction:Machine learning integration with next-generation sequencing platforms is compressing the computational pipeline from weeks to days, enabling real-time manufacturing scheduling.
Industry Challenges
- Individualized Lot Release Protocols:FDA evolving standards for quality control of patient-specific vaccine batches require bespoke validation frameworks that strain contract manufacturing organization capacity planning.
- Cross-Functional Integration:Seamless coordination between genomic sequencing labs, bioinformatics pipelines, GMP manufacturing suites, and clinical sites demands interoperable data systems that most institutions lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neoantigen Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peptides, DNA-based Antigens, RNA-based Antigens, Others Technology: Bioinformatics, Genomic Sequencing, Proteomics, Mass Spectrometry End User: Research Institutes, Pharmaceutical Companies, Contract Research Organizations, Hospitals Application: Cancer Immunotherapy, Vaccine Development, Diagnostic Testing, Personalized Medicine |
| Companies Covered | Moderna Inc, Achilles Therapeutics Limited, BioNTech SE, Genentech Inc, CureVac N.V., Merck & Co Inc, Agenus Inc, Immatics, Gritstone Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neoantigen Market Emerging Trajectories
Computational platforms are displacing empirical screening as the primary engine of epitope discovery, while regulatory frameworks co-evolve to accommodate individualized manufacturing paradigms that defy traditional batch-release conventions.
Next-generation sequencing paired with neoantigen prediction algorithms is expanding into standard-of-care workflows for resectable solid tumors. Oncology centers in the United States and Germany are embedding these platforms into pre-surgical planning protocols, enabling adjuvant vaccine initiation within six weeks of resection. The compression of this timeline is forcing pathology departments to restructure specimen handling and data transfer protocols.
EMA's PRIME scheme and FDA's breakthrough therapy pathway are creating divergent but complementary regulatory tracks that reward early biomarker validation. Sponsors pursuing both designations simultaneously must maintain dual dossier formats, increasing documentation overhead but securing broader market access. European biotechnology firms are responding by establishing US regulatory affairs capabilities earlier in development cycles.
Hospital procurement departments are consolidating neoantigen service contracts under single-source agreements with integrated platform providers. Academic medical centers in Switzerland and the Netherlands are abandoning fragmented vendor relationships in favor of turnkey solutions spanning sequencing through GMP release. This consolidation favors organizations with captive manufacturing infrastructure over pure-play bioinformatics licensors.
Neoantigen Market Segmentation
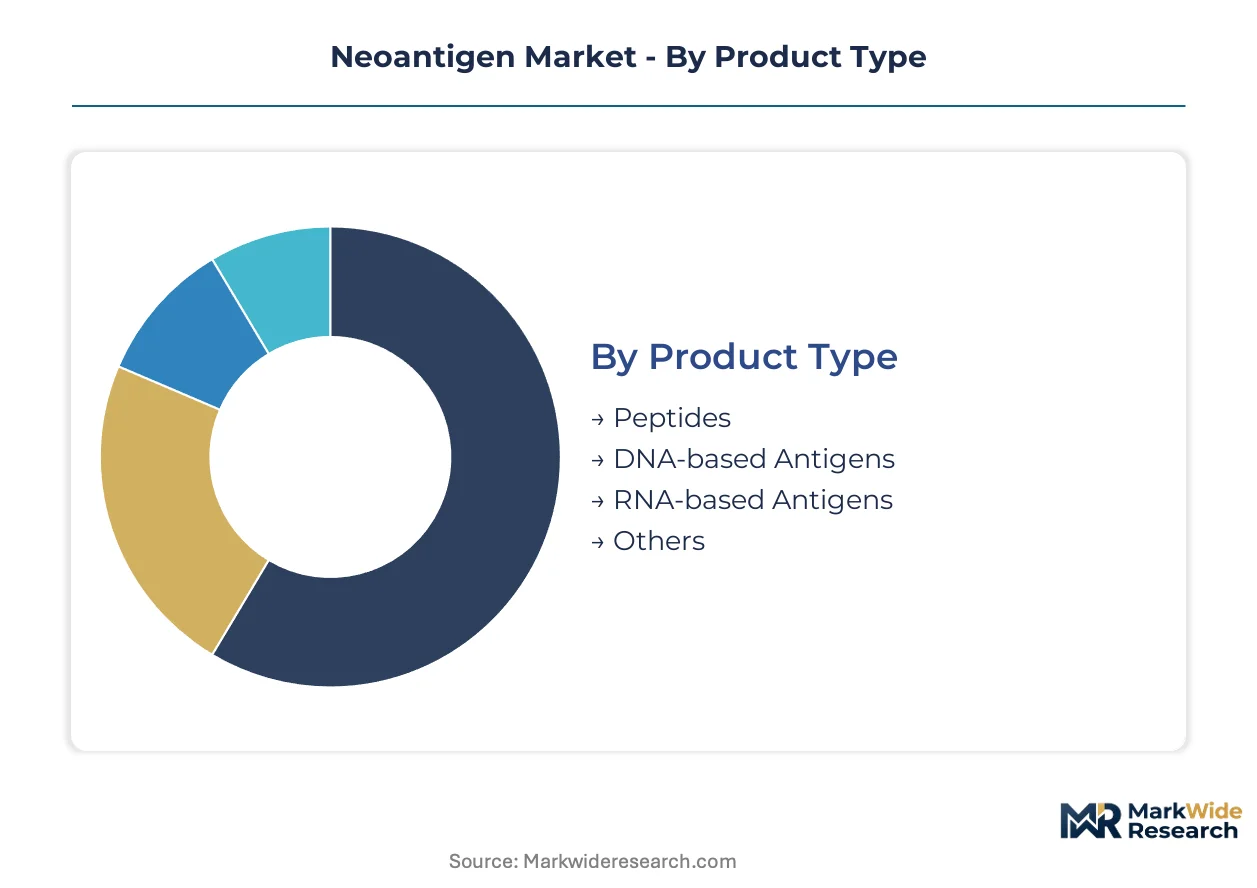
Neoantigen platforms require differentiated capital deployment across manufacturing modalities and computational infrastructure. Segmentation reveals where infrastructure investments concentrate versus where outsourced partnerships dominate.
Product Type:
RNA-based antigens demand the heaviest upfront manufacturing investment due to individualized GMP suite requirements and cold-chain logistics.
- RNA-based Antigens:Messenger RNA encoding patient-specific neoantigens enables rapid synthesis within weeks of biopsy. Manufacturing concentrates in the United States and Germany where dedicated GMP facilities serve academic medical centers. The FDA's individualized lot release standards impose validation costs that favor integrated platform providers over modular suppliers.
- Peptides:Synthetic peptide vaccines represent the most mature manufacturing paradigm with established solid-phase synthesis infrastructure. Production clusters in Switzerland and the Netherlands leverage existing contract manufacturing networks originally built for infectious disease vaccines. Peptide stability during shipping reduces cold-chain capital requirements compared to nucleic acid platforms.
- DNA-based Antigens:Plasmid DNA vaccines offer intermediate stability and manufacturing complexity.
- Others:Viral vector and dendritic cell-based approaches occupy niche positions in early clinical development.
RNA-based antigens absorb the bulk of installed capacity; DNA-based antigens are expanding most quickly.
Technology:
Mass spectrometry and proteomics require specialized equipment that concentrates in elite research clusters.
- Bioinformatics:Computational prediction algorithms identify immunogenic epitopes from next-generation sequencing data. Talent scarcity in Boston, San Francisco, and Basel creates recruitment bottlenecks that inflate compensation costs. Machine learning integration is compressing prediction timelines from weeks to days.
- Mass Spectrometry:Proteomic validation of predicted neoantigens requires high-resolution instrumentation and consumables that inflate per-patient costs beyond standard biologics. Equipment concentrates in the United States and Germany where NIH and DFG funding supports core facility maintenance.
- Genomic Sequencing:Foundation technology for mutation identification with mature vendor ecosystems.
- Proteomics:Protein-level confirmation workflows bridge computational prediction and immunological validation.
Genomic sequencing anchors baseline infrastructure deployment; bioinformatics is gaining share fastest.
End User:
Pharmaceutical companies deploy capital across fully integrated platforms while research institutes rely on shared core facilities.
- Pharmaceutical Companies:BioNTech SE and Moderna Inc maintain captive manufacturing infrastructure spanning mRNA synthesis through GMP release. Internal capacity insulates against contract manufacturing bottlenecks but requires sustained R&D intensity to maintain utilization.
- Research Institutes:NIH and NCI-funded centers in the United States access neoantigen platforms through shared instrumentation grants. Dependency on external bioinformatics partnerships creates coordination friction in multi-site trials.
- Contract Research Organizations:CDMOs specializing in personalized vaccines offer modular manufacturing services.
- Hospitals:Academic medical centers in Switzerland and the Netherlands are consolidating under single-source platform agreements.
Pharmaceutical companies command the largest dedicated capacity footprint; hospitals are consolidating procurement fastest.
Application:
Cancer immunotherapy applications absorb the deepest clinical investment while diagnostic testing offers faster reimbursement pathways.
- Cancer Immunotherapy:Personalized neoantigen vaccines targeting solid tumors require parallel development of companion diagnostics per FDA draft guidance. Melanoma and non-small cell lung cancer lead indication expansion with pancreatic and glioblastoma cohorts advancing behind.
- Personalized Medicine:Patient-specific manufacturing paradigms defy traditional batch economics and force quality control framework innovation. EMA's PRIME scheme and FDA breakthrough designation create dual-track regulatory opportunities for sponsors with transatlantic capabilities.
- Vaccine Development:Infectious disease applications leverage neoantigen discovery platforms for pathogen-specific epitope identification.
- Diagnostic Testing:Immune monitoring assays and predictive biomarker panels enable patient stratification.
Cancer immunotherapy dominates therapeutic development investment; diagnostic testing is scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neoantigen manufacturing capacity clusters in the United States and Germany while clinical demand spreads across oncology centers in Switzerland, the United Kingdom, and Japan. Production infrastructure concentrates where FDA and EMA regulatory pathways intersect with dedicated GMP facilities.
United States
NIH and NCI funding anchors early-stage biotech development in Boston and San Francisco, where academic medical centers build captive neoantigen production facilities. FDA breakthrough therapy designation compresses review timelines for personalized cancer vaccines. The Greater Boston cluster absorbs the deepest concentration of bioinformatics talent and GMP manufacturing suites.
Germany
The DFG funds mass spectrometry core facilities that validate predicted neoantigens for clinical translation. EMA's PRIME scheme offers accelerated assessment pathways parallel to FDA breakthrough status. The Rhine-Main region hosts integrated mRNA manufacturing infrastructure serving both European and transatlantic trials.
Switzerland
Swissmedic regulates patient-specific vaccine batches through individualized lot release frameworks that strain contract manufacturing capacity. Hospital procurement departments in Zurich and Basel consolidate under single-source platform agreements. The Basel cluster leverages existing pharmaceutical manufacturing infrastructure for peptide synthesis operations.
United Kingdom
The MHRA aligns with FDA draft guidance on companion diagnostic co-development for personalized neoantigen products. London and Cambridge academic centers embed sequencing platforms into pre-surgical planning protocols for resectable solid tumors. Cross-functional integration between genomic labs and GMP suites remains the primary operational bottleneck.
Japan
PMDA regulatory timelines for individualized manufacturing paradigms lag FDA and EMA precedents, creating market access friction. The Kanto region around Tokyo concentrates oncology center demand for melanoma and non-small cell lung cancer indications. Japanese pharmaceutical firms establish US regulatory affairs capabilities earlier in development cycles to secure dual-track designations.
Neoantigen Market Vendor Landscape
The competitive structure tilts toward integrated platform providers with captive manufacturing infrastructure. Consolidation favors organizations spanning sequencing through GMP release over pure-play bioinformatics licensors. Three archetypes dominate: mRNA specialists with rapid turnaround capabilities, peptide manufacturers leveraging established synthesis networks, and immuno-oncology incumbents extending franchises into combination regimens. Dominant competitive moves include strategic partnerships with academic medical centers and capacity expansion across dedicated GMP suites.
Within the mRNA specialist tier, Moderna Inc and BioNTech SE exemplify integrated platform providers with transatlantic manufacturing footprints. Merck & Co Inc occupies a position bridging immuno-oncology incumbency with neoantigen combination development. These three anchors represent contrasting strategic postures: rapid manufacturing turnaround, European regulatory sophistication, and checkpoint inhibitor franchise extension respectively.
| Leading Market Players |
|---|
| Moderna Inc |
| Achilles Therapeutics Limited |
| BioNTech SE |
| Genentech Inc |
| CureVac N.V. |
| Merck & Co Inc |
| Agenus Inc |
| Immatics |
| Gritstone Bio |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation under single-source platform agreements in Switzerland and the Netherlands is forcing supply chains to absorb validation costs for individualized lot release, compressing margins for modular suppliers while rewarding integrated providers with captive GMP infrastructure.
Pricing Analysis
Margin tightening in RNA-based antigen manufacturing reflects FDA individualized lot release standards that inflate per-patient validation costs beyond standard biologics thresholds. Pricing stratifies across integrated platform providers, modular CDMOs, and academic core facilities based on turnaround speed and regulatory track record. Cost-down pressure accelerates as oncology centers consolidate procurement under turnkey agreements spanning sequencing through GMP release. Pharmaceutical buyers with captive manufacturing capacity exhibit lowest price sensitivity; research institutes dependent on shared instrumentation grants face highest budget constraints.
Supply Chain Analysis
GMP certification and FDA breakthrough therapy pathway qualification gate access to the highest-value procurement channels in the United States and Germany. Manufacturing infrastructure concentrates in the United States, Germany, and Switzerland where dedicated mRNA synthesis suites and mass spectrometry core facilities cluster. Raw material dependencies span synthetic nucleotides, specialized chromatography resins, and high-resolution mass spectrometry consumables. Single-source vulnerability concentrates in bioinformatics talent pools around Boston, San Francisco, and Basel. Distribution runs through academic medical center networks and pharmaceutical captive channels rather than traditional wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Individualized manufacturing paradigms create structural supply constraints as GMP suite capacity fails to match patient-specific demand growth, propping pricing power for qualified integrated platform providers.
For Market Incumbents: Deepen backward integration into synthetic nucleotide supply and mass spectrometry core facilities to insulate against CDMO bottlenecks. Expand GMP manufacturing footprint in the Rhine-Main region to capture EMA PRIME scheme demand. Defend against emerging AI-native epitope prediction entrants by accelerating machine learning pipeline integration. For New Entrants and Emerging Players: Capture white-space opportunity in pancreatic and glioblastoma indication expansion where immunotherapy response rates remain suboptimal and incumbent clinical data is thinnest. Target hospital procurement consolidation in the Netherlands and United Kingdom where single-source platform agreements favor turnkey challengers over fragmented incumbents. Pursue go-to-market positioning as EMA-FDA dual-track regulatory specialists. For Investors and Strategic Acquirers: The window for entry favors vertically integrated platform providers with transatlantic manufacturing footprints and companion diagnostic co-development capabilities. Long-term viability hinges on sustained R&D intensity to maintain bioinformatics talent density and GMP suite utilization. Watch for FDA finalization of individualized manufacturing lot release standards as inflection signal for contract manufacturing capacity repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA draft guidance mandates parallel validation, creating dual-track regulatory barrier to entry. |
| AI Epitope Prediction Integration | Machine learning compression of computational timelines from weeks to days enables real-time manufacturing scheduling. |
| GMP Manufacturing Scale-Up | EMA PRIME scheme and FDA breakthrough pathway concentrate demand in qualified transatlantic facilities. |
| Academic Medical Center Partnership | Hospital procurement consolidation in Switzerland and Netherlands favors integrated platform providers. |
| Solid Tumor Indication Diversification | Melanoma and NSCLC proof-of-concept data expands into pancreatic and glioblastoma cohorts with suboptimal immunotherapy response. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. FDA breakthrough therapy designations, EMA PRIME scheme submissions, and ClinicalTrials.gov protocol records formed the documentary backbone. Bottom-up patient-flow modeling and top-down market sizing were reconciled through iterative triangulation.
Data-stream reconciliation across genomic sequencing volumes, GMP manufacturing capacity installations, and bioinformatics platform deployments shaped the analytical framework. Segmentation dimensions spanned product type, technology modality, end-user archetype, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated baseline estimates, with inputs spanning NIH funding allocations, NCI alliance commitments, and pharmaceutical R&D intensity disclosures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA individualized lot release standard finalization, bioinformatics talent migration patterns, and companion diagnostic validation timelines. Forecasts reflect documented assumptions about regulatory pathway convergence and manufacturing capacity expansion trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Drug Discovery Enzymes Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Global Cell Sorting Market