
 Life Science Trade Lane Design and Qualification Services Market | 2026-2036
Life Science Trade Lane Design and Qualification Services Market Size, Share, and Industry Trends Forecast 2026-2036
Life Science Trade Lane Design and Qualification Services Market Insights
European cold chain infrastructure is hardening as pharmaceutical manufacturers expand biologics distribution networks. Deutsche Post DHL Group leverages its temperature-controlled warehousing footprint across the continent. Kuehne+Nagel anchors its competitive position through specialized pharmaceutical logistics certifications. FedEx differentiates via integrated customs brokerage paired with real-time shipment monitoring capabilities.
Life science trade lane design and qualification services encompass the systematic mapping, risk evaluation, and regulatory verification of temperature-controlled distribution pathways for pharmaceutical and biologic products, incorporating thermal packaging validation, stability data review, and Good Distribution Practice compliance documentation. The primary purpose is ensuring product integrity from manufacturing site through patient administration while meeting jurisdictional regulatory requirements. Cold chain logistics application segments command premium service margins due to stringent temperature excursion protocols, while clinical supply chain segments sustain faster growth trajectories driven by decentralized trial models. Vendor qualification services occupy mature positions with established pricing benchmarks, whereas route optimization offerings are attracting technology investments from logistics providers seeking competitive separation.
FDA enforcement of Drug Supply Chain Security Act provisions shapes demand for documentation management services, while EMA's Good Distribution Practice guidelines and EU F-Gas Regulation on refrigerant emissions drive cold chain infrastructure upgrades across European trade lanes. WHO prequalification requirements for vaccine distribution corridors further tighten qualification protocols in emerging markets. Stakeholders must monitor evolving pharmacopeial standards for thermal packaging performance as regulatory convergence between FDA and EMA inspection frameworks accelerates service standardization pressures.
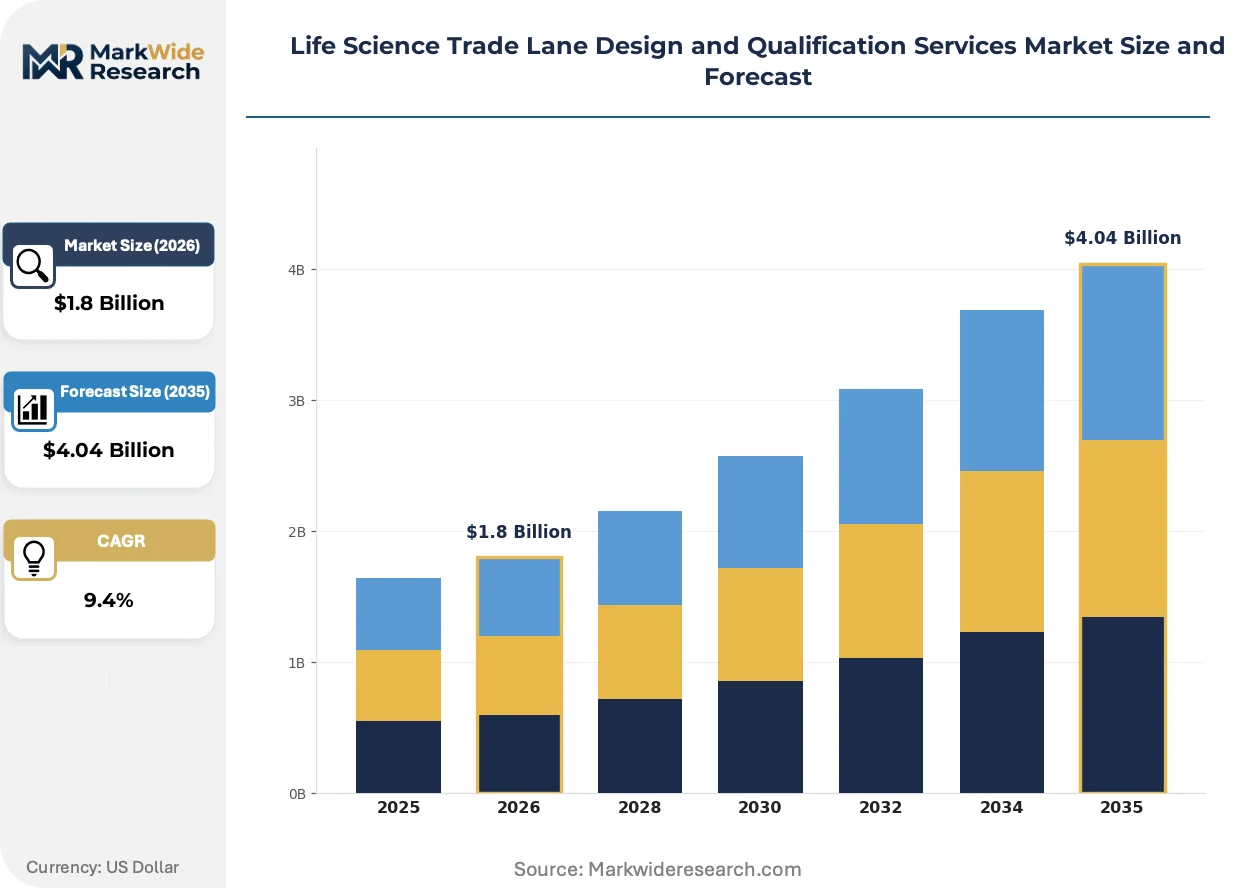
Market Dynamics
FDA enforcement of Drug Supply Chain Security Act documentation requirements is compressing vendor qualification timelines while EMA's Good Distribution Practice inspections are hardening cold chain infrastructure standards across European corridors. Contract research organizations now demand integrated route validation services that bundle thermal packaging certification with real-time monitoring capabilities.
Growth Catalysts
- Biologics pipeline expansion:Monoclonal antibody and cell therapy manufacturing is multiplying temperature-controlled shipment volumes from production sites to clinical depots.
- EMA F-Gas Regulation:Refrigerant emission restrictions are forcing cold chain infrastructure upgrades that require formal re-qualification of existing trade lanes.
- Decentralized clinical trials:Direct-to-patient distribution models are fragmenting shipment endpoints and multiplying route validation requirements per study protocol.
Market Restraints
- Qualified packaging material scarcity:Vacuum-insulated panel and phase-change material supply concentrates among three specialized European converters.
- FDA validation documentation burden:Temperature excursion investigation protocols add 15-20 labor hours per qualified lane.
- Dry ice supply volatility:Carbon dioxide capture rates at ammonia plants fluctuate with fertilizer production cycles.
Strategic Opportunities
- India pharmaceutical exports:CDSCO manufacturing site approvals are accelerating, creating demand for lane qualification services connecting Mumbai and Hyderabad to European distribution hubs.
- Reusable thermal packaging systems:IoT sensor integration with return-logistics networks enables subscription-based qualification service models.
- EU MDR device tracking mandates:Unique device identifier requirements are extending qualification scope to medical device distribution corridors previously exempt from cold chain protocols.
Industry Challenges
- Thermal engineer talent scarcity:Qualified professionals who bridge packaging science, stability data interpretation, and GDP compliance remain concentrated among incumbent logistics providers.
- Multi-site protocol harmonization:Sponsors running parallel studies across US, EU, and Asia-Pacific jurisdictions face conflicting pharmacopeial temperature mapping standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Science Trade Lane Design and Qualification Services Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Trade Lane Strategy, Risk Assessment, Compliance Validation, Route Optimization, Vendor Qualification, Documentation Management Application: Cold Chain Logistics, Clinical Supply Chain, Commercial Distribution, Regulatory Adherence, Quality Assurance, Product Release Coordination End User: Pharmaceutical Manufacturers, Biotech Firms, Contract Research Organizations, Medical Device Producers, Clinical Trial Sponsors, Distribution Specialists Deployment Model: Onsite Consultancy, Remote Assessment, Hybrid Engagement, Managed Services, Project-Based Support, Continuous Improvement |
| Companies Covered | DB Schenker, Deutsche Post DHL Group, United Parcel Service, FedEx, Kuehne+Nagel, DSV, CEVA Logistics, Expeditors International, C.H. Robinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Science Trade Lane Design and Qualification Services Market Trends and Innovations
Digital twin technology is compressing lane qualification timelines from physical trial shipments to simulated thermal performance validation. Logistics providers now compete on predictive risk scoring rather than historical lane performance data alone.
Blockchain-enabled temperature logging is integrating with customs documentation systems to create immutable chain-of-custody records for cross-border biologics movements. Large pharmaceutical sponsors in Germany and Switzerland are mandating this capability for high-value gene therapy shipments. The technology is integrating previously siloed quality assurance and logistics procurement functions into unified vendor scorecards.
REACH chemical safety registrations are restricting refrigerant chemistries available for passive thermal packaging systems. European converters must reformulate phase-change materials using bio-based alternatives that maintain 2-8°C performance windows. Biologics distributors with pan-European networks are absorbing re-qualification costs for legacy lane portfolios.
Direct contracting between sponsors and specialized lane qualification boutiques is displacing bundled offerings from integrated logistics giants. Mid-size biotech companies in the Boston-Cambridge cluster now procure route validation, thermal packaging, and monitoring as separate service lines. This unbundling is most pronounced among cell therapy developers requiring patient-specific shipment coordination.
Life Science Trade Lane Design and Qualification Services Market Segmentation
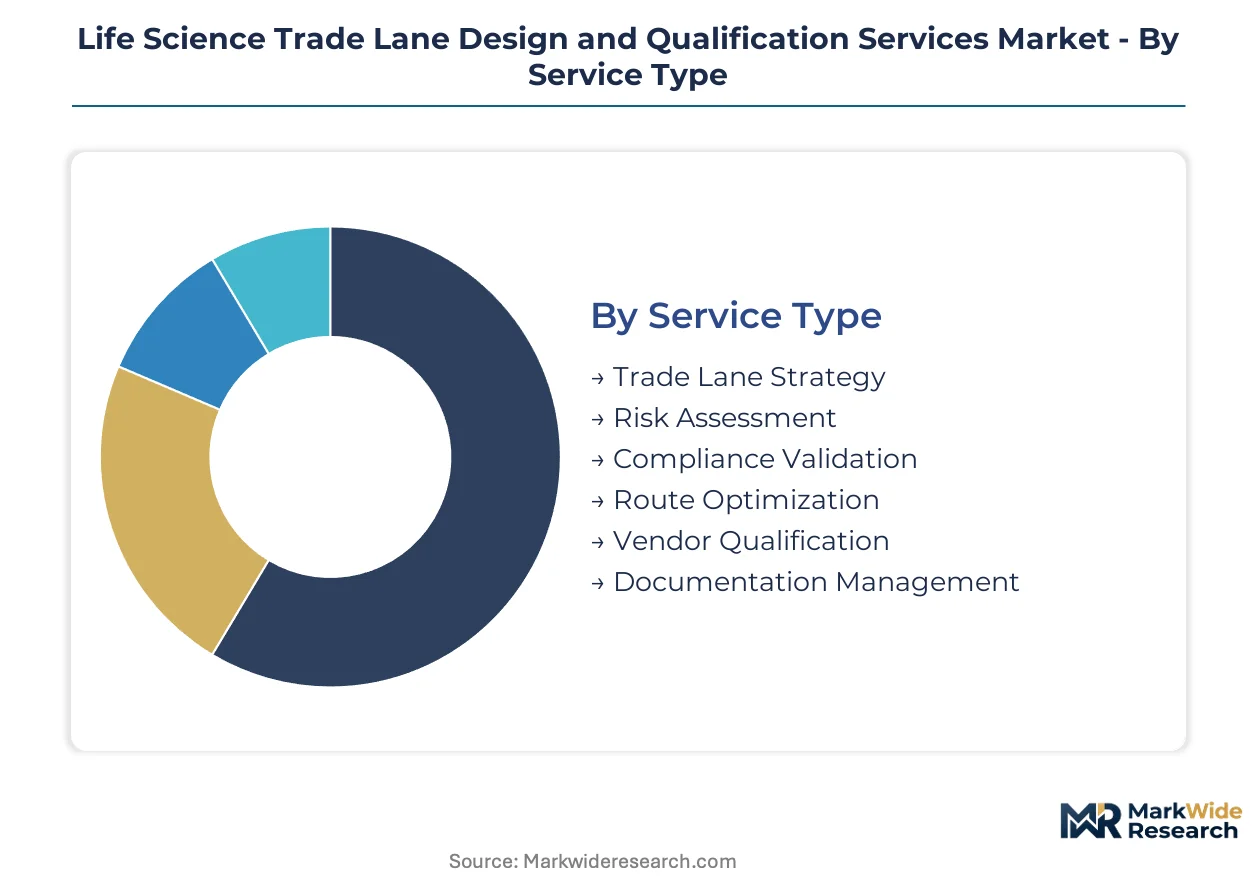
Segmentation in life science trade lane services reveals how procurement patterns split between integrated logistics bundles and specialized unbundled offerings. Biotech sponsors now select vendors based on therapeutic modality complexity rather than geography alone.
Service Type:
Pharmaceutical procurement teams weight vendor selection toward documentation rigor and thermal validation depth.
- Trade Lane Strategy:Encompasses network topology design, hub placement optimization, and multi-modal corridor selection for temperature-sensitive biologics. Demand concentrates among cell therapy developers in Germany and Switzerland requiring patient-specific distribution architectures.
- Compliance Validation:Covers FDA DSCSA documentation, EMA GDP verification, and WHO prequalification pathway preparation. Contract research organizations in the Boston-Cambridge corridor now mandate this as a standalone procurement category separate from logistics execution.
- Risk Assessment:Thermal mapping, stability data review, and excursion probability modeling for candidate distribution routes.
- Route Optimization:Algorithm-driven lane selection balancing transit time against temperature excursion risk profiles.
- Vendor Qualification:Systematic audit and certification of packaging converters, cold storage operators, and customs brokers.
- Documentation Management:Chain-of-custody record maintenance, deviation investigation, and regulatory submission support.
Volume sits with Compliance Validation; growth tilts toward Trade Lane Strategy.
Application:
Service margins diverge sharply based on temperature stringency and regulatory inspection frequency.
- Cold Chain Logistics:End-to-end qualification of 2-8°C and cryogenic distribution pathways incorporating thermal packaging validation and real-time monitoring integration. European biologics manufacturers absorb premium pricing for lanes serving EMA F-Gas Regulation-compliant infrastructure.
- Clinical Supply Chain:Direct-to-patient and depot-to-site validation for decentralized trial models. Sponsors running parallel US-EU-Asia-Pacific studies drive fastest expansion as protocol fragmentation multiplies route qualification requirements per investigational program.
- Commercial Distribution:Post-approval supply chain qualification for marketed pharmaceutical products.
- Regulatory Adherence:GDP compliance verification and pharmacopeial standard alignment services.
- Quality Assurance:Temperature excursion investigation and corrective action documentation.
- Product Release Coordination:Batch certification and customs clearance facilitation for cross-border movements.
Cold Chain Logistics commands the revenue base; Clinical Supply Chain is climbing the fastest.
End User:
Organizational scale and therapeutic portfolio complexity determine whether buyers procure bundled or unbundled services.
- Pharmaceutical Manufacturers:Large-cap sponsors with established distribution networks.
- Biotech Firms:Mid-size developers of monoclonal antibodies and gene therapies. Procurement concentrates in South San Francisco and Cambridge, Massachusetts, where sponsors now separate route validation from packaging and monitoring into distinct vendor relationships.
- Contract Research Organizations:Full-service clinical trial operators requiring integrated lane qualification across multiple investigator sites. IQVIA and Parexel demand bundled thermal packaging certification with real-time monitoring capabilities.
- Medical Device Producers:EU MDR compliance is extending qualification scope to device distribution corridors previously exempt from cold chain protocols.
- Clinical Trial Sponsors:Academic institutions and government research programs.
- Distribution Specialists:Third-party logistics providers seeking subcontracted qualification expertise.
Contract Research Organizations anchor current volume; Biotech Firms are gaining share fastest.
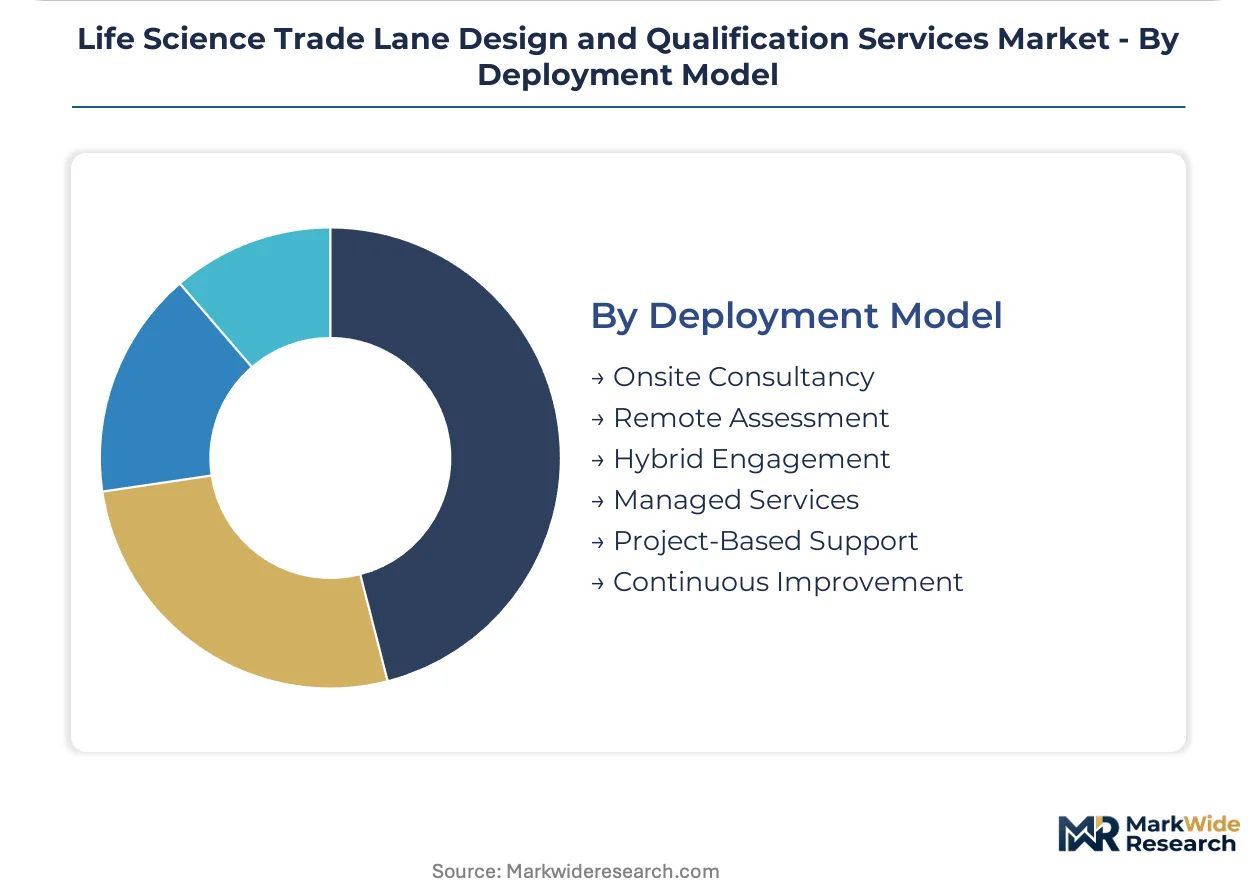
Deployment Model:
Engagement structure selection tracks sponsor geographic dispersion and internal thermal engineering capabilities.
- Onsite Consultancy:Physical presence at manufacturing sites and distribution hubs for thermal mapping and packaging qualification.
- Remote Assessment:Digital twin simulation and virtual audit protocols reducing lane qualification timelines from physical trial shipments. Adoption accelerates among sponsors with limited internal cold chain engineering resources.
- Hybrid Engagement:Blended onsite and remote delivery optimizing cost and speed.
- Managed Services:Multi-year outsourcing of entire qualification portfolios.
- Project-Based Support:Single-study or single-lane validation engagements.
- Continuous Improvement:Ongoing lane performance monitoring and re-qualification services.
Hybrid Engagement carries the installed base; Remote Assessment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical manufacturing clusters anchor European cold chain infrastructure investment. Qualified logistics corridors radiate from central European hubs toward North American and Asia-Pacific destinations.
United States
Cell therapy developers in the Boston-Cambridge corridor fragment procurement into separate route validation, packaging, and monitoring contracts. FDA Drug Supply Chain Security Act enforcement compresses vendor qualification timelines for cross-border biologics movements. South San Francisco biotech sponsors now mandate standalone compliance validation as a distinct procurement category.
Germany
Central European pharmaceutical manufacturing concentration drives premium pricing for EMA F-Gas Regulation-compliant cold chain infrastructure. Deutsche Post DHL Group leverages temperature-controlled warehousing footprints across the continent. Frankfurt and Munich logistics hubs absorb re-qualification costs for legacy lane portfolios as REACH chemical safety registrations restrict refrigerant chemistries.
Switzerland
Gene therapy shipment volumes from Basel and Zurich manufacturing sites mandate blockchain-enabled temperature logging integration. Swissmedic inspection frameworks accelerate service standardization pressures for high-value biologics corridors. Large pharmaceutical sponsors now require immutable chain-of-custody records for cross-border movements into EU distribution networks.
India
CDSCO manufacturing site approvals in Mumbai and Hyderabad accelerate demand for lane qualification services connecting to European hubs. Carbon dioxide capture rate fluctuations at ammonia plants create dry ice supply volatility for cryogenic shipments. Contract research organizations operating multi-regional studies drive fastest growth in decentralized clinical trial distribution validation.
United Kingdom
Post-Brexit customs complexity increases documentation management service demand for biologics entering EU distribution networks. London-based clinical trial sponsors fragment shipment endpoints through direct-to-patient distribution models. UK logistics providers invest in digital twin simulation capabilities to compress lane qualification timelines from physical trial shipments.
Life Science Trade Lane Design and Qualification Services Market Competitive Landscape
Global majors compete with regional champions across integrated service bundling versus specialized unbundling vectors. The vendor base splits between logistics conglomerates offering end-to-end qualification portfolios and boutique consultancies selling discrete route validation or thermal packaging certification. Three archetypes dominate: integrated logistics giants with pan-continental cold chain footprints, specialized pharmaceutical logistics certifiers, and technology-enabled lane qualification boutiques. Competitive moves concentrate on digital twin capability acquisition and strategic partnerships with IoT sensor providers.
Among integrated logistics conglomerates, Deutsche Post DHL Group, FedEx, and Kuehne+Nagel occupy positions exemplifying scale-driven service bundling. Deutsche Post DHL Group anchors European infrastructure dominance through temperature-controlled warehousing concentration. FedEx represents North American integration of customs brokerage with real-time monitoring capabilities. Kuehne+Nagel sits within the specialized certification tier, anchoring competitive positioning through pharmaceutical logistics credentials rather than asset scale alone.
| Leading Market Players |
|---|
| DB Schenker |
| Deutsche Post DHL Group |
| United Parcel Service |
| FedEx |
| Kuehne+Nagel |
| DSV |
| CEVA Logistics |
| Expeditors International |
| C.H. Robinson |
| Others |
Pricing and Supply Chain Analysis
Contract research organizations operating multi-regional clinical trials concentrate procurement power and drive unbundled service pricing. Their demand for standalone compliance validation separates route optimization from thermal packaging and monitoring contracts.
Pricing Analysis
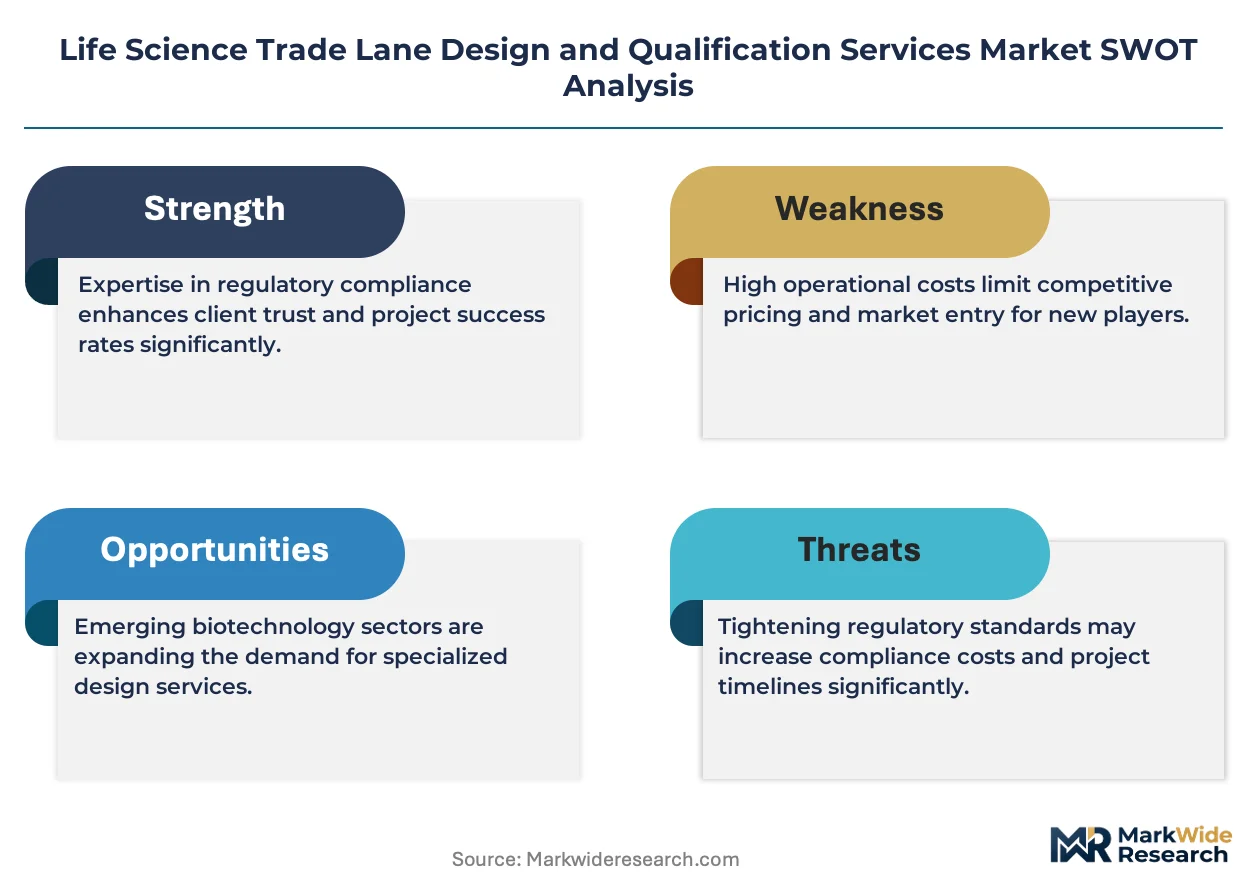
Service bundling versus unbundling defines the dominant pricing structure. Three-tier pricing separates premium GDP-certified lanes from standard temperature-controlled corridors and economy non-validated routes. Price differentiation rests on EMA certification depth and real-time IoT integration. Cost compression in standard-tier lanes intensifies because dry ice supply volatility forces packaging material hedging. Small biotech firms show highest price sensitivity; gene therapy developers absorb premium pricing for patient-specific distribution.
Supply Chain Analysis
Domestic-content mandates in the EU F-Gas Regulation reshape refrigerant sourcing toward bio-based phase-change materials. Manufacturing of vacuum-insulated panels and specialized thermal packaging concentrates in Germany, Switzerland, and the Netherlands. Raw material supply draws from ammonia plant carbon dioxide capture, bio-derived paraffin formulations, and recycled aluminum cores. Single-source vulnerability runs through three European converters controlling qualified packaging substrate supply. Distribution feeds from central European hubs through qualified cold storage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around documentation capability and thermal engineering talent scarcity. FDA enforcement of Drug Supply Chain Security Act provisions pressures boutique consultancies lacking integrated digital infrastructure.
For Market Incumbents: Anticipate sponsor unbundling by acquiring digital twin simulation capabilities before route validation commoditizes. Deutsche Post DHL Group and Kuehne+Nagel should deepen backward integration into IoT sensor networks to control monitoring data streams. Thermal engineer talent concentration among incumbents remains the primary defensive moat against technology-enabled boutiques.
For New Entrants and Emerging Players: Digital twin platforms offer the clearest technology-first wedge for compressing lane qualification timelines. White-space targets include decentralized clinical trial distribution validation and reusable thermal packaging subscription models. India pharmaceutical export corridors connecting Mumbai and Hyderabad to European hubs represent the most penetrable geography. A compliance-validation-first go-to-market angle bypasses incumbent logistics asset advantages.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized lane qualification boutiques in Germany and Switzerland facing re-qualification cost absorption from REACH refrigerant restrictions. Long-term viability centers on regulatory documentation depth rather than physical warehousing scale. Watch CDSCO manufacturing site approval velocity as the signal indicating India corridor service demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Capability Acquisition | Compresses physical trial shipments to simulated thermal validation for biologics corridors. |
| IoT Sensor Network Integration | Creates unified vendor scorecards merging quality assurance with logistics procurement functions. |
| REACH-Compliant Refrigerant Reformulation | Enables continued European lane operation under tightened EMA chemical safety registrations. |
| India-Europe Corridor Qualification | Captures CDSCO-accelerated pharmaceutical export growth connecting Mumbai to Frankfurt hubs. |
| Blockchain Temperature Logging Deployment | Satisfies Swissmandate for immutable chain-of-custody records on gene therapy shipments. |
Research Methodology
Regulatory filings, pharmaceutical logistics trade associations, and cold chain engineering publications formed the secondary backbone. Primary interviews with thermal packaging engineers, GDP compliance officers, clinical supply chain directors, and biotech procurement managers validated segment assumptions. Bottom-up and top-down triangulation cross-checked service provider capacity data against sponsor procurement survey responses. SEC filings from Deutsche Post DHL Group, FedEx, and Kuehne+Nagel provided integrated logistics revenue benchmarks.
Bottom-up modeling built from individual trade lane qualification engagements across service type, application, and deployment model segments. Top-down validation referenced EMA inspection frequency data and FDA DSCSA enforcement patterns. Modeled dimensions included therapeutic modality complexity, temperature stringency tier, and regional regulatory cluster. CAGRs derived from sponsor pipeline analysis and cold chain infrastructure investment tracking. Forecast inputs incorporated biologics manufacturing capacity expansion and decentralized clinical trial protocol fragmentation rates.
Several conditions sit outside the modeled scope, including pandemic-era emergency use authorization distribution pathways and military pharmaceutical logistics corridors. Forecasts reflect assumptions about regulatory convergence between FDA and EMA inspection frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Medical Second Opinion Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Medical Waste Disposal Services Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Global Offsite Medical Case Management Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
Specialty Pharma Home Delivery and Patient Support Logistics Market
Healthcare Services
Healthcare Third-Party Logistics Market