
 Ignition Systems for Range-Extended Hybrid Powertrains Market | 2026-2036
Ignition Systems for Range-Extended Hybrid Powertrains Market Size, Share, and Industry Trends Forecast 2026-2036
Ignition Systems for Range-Extended Hybrid Powertrains Market Insights
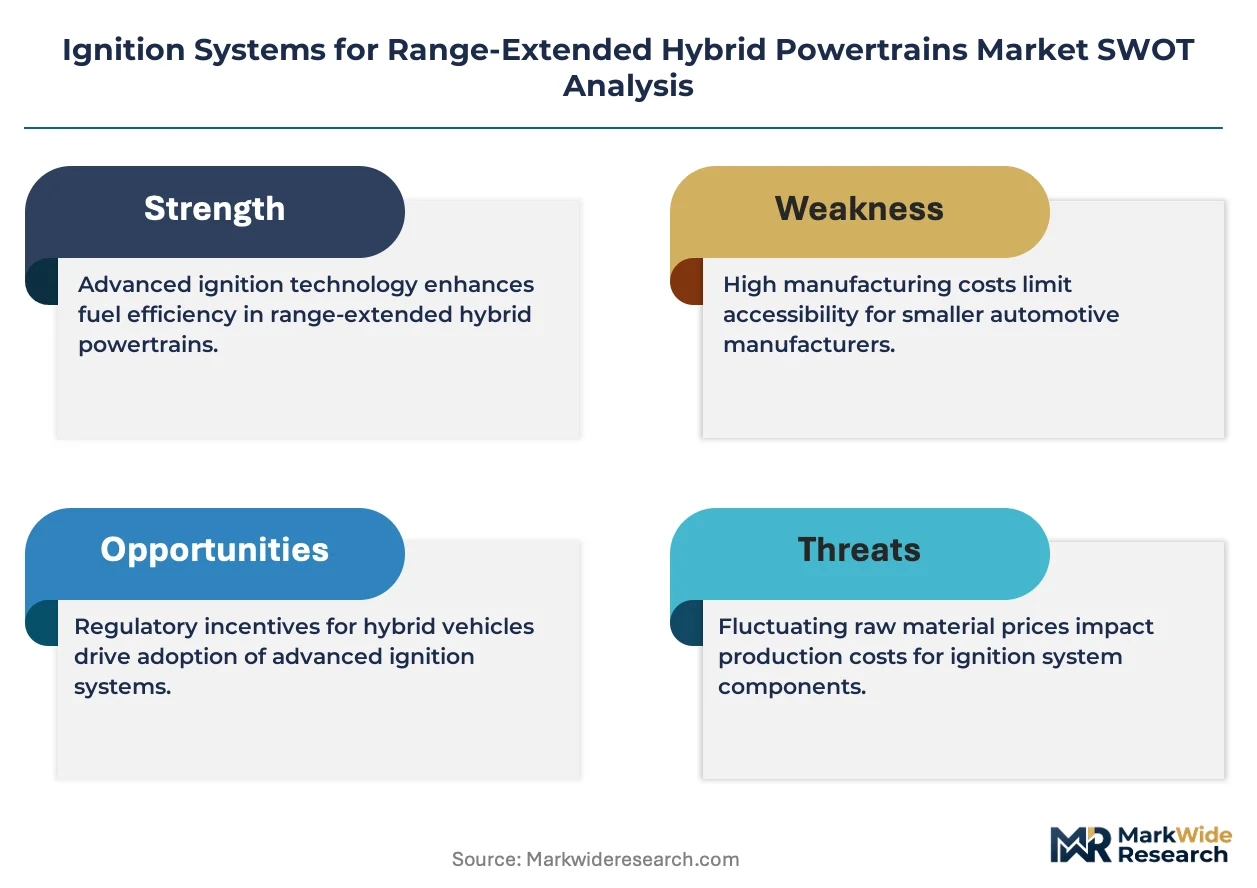
Asset-light leasing structures for powertrain testing equipment is narrowing the capital barrier for mid-tier suppliers entering range-extended hybrid ignition development. BorgWarner leverages its integrated mechatronics portfolio to bundle ignition modules with thermal management systems for OEM customers. Mahle anchors its position through deep R&D into plasma-assisted combustion for lean-burn range-extended engines. ZF Friedrichshafen competes by extending its chassis-electronics expertise into engine-management integration.
Ignition systems for range-extended hybrid powertrains comprise high-voltage coil assemblies, precise timing controllers, and durable spark interfaces engineered to fire reliably across intermittent combustion cycles where engines cycle on and off frequently. Coil-on-plug ignition dominates current production due to packaging efficiency and reduced electromagnetic interference in densely integrated engine bays. Electronic ignition technology leads value creation, while plasma ignition represents the fastest-advancing segment as manufacturers pursue ultra-lean combustion for emission compliance. Passenger vehicles anchor application volume, though commercial vehicles command higher per-unit ignition system content.
The EPA tailpipe standards and NHTSA corporate average fuel economy rules in the United States compel range-extended hybrid designs to minimize cold-start emissions through advanced ignition timing strategies. EMA and REACH in Europe enforce material restrictions and end-of-life accountability that shape supplier material selections for ignition coil housings and connector systems. Stakeholders must monitor how evolving multi-country emission test protocols redefine the performance thresholds that ignition systems must certify against.
Market Dynamics
Intermittent combustion cycles in range-extended architectures are forcing ignition system architectures toward rapid-fire readiness and thermal cycling durability. The tension between cold-start emission compliance and component longevity is compressing supplier development timelines.
Growth Catalysts
- MIIT Dual Carbon Goals:China's updated fuel-consumption standards compel domestic automakers to optimize combustion-cycle efficiency, expanding procurement of precision ignition controllers.
- Plasma-Assisted Combustion:This emerging ignition modality enables ultra-lean burn regimes that satisfy tightening NOx thresholds without aftertreatment complexity.
- Fleet TCO Advantages:North American commercial fleet operators are crystallizing total-cost-of-ownership calculations that favor range-extended hybrid powertrains over pure electric for long-haul duty cycles.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings destabilize high-voltage ignition coil cost structures, squeezing mid-tier supplier margins.
- German Supplier Concentration:Bosch, Continental, and ZF Friedrichshafen anchor development around Stuttgart and Munich, creating geographic single-point vulnerability for European OEM programs.
- REACH Material Restrictions:ECHA enforcement of end-of-life accountability limits housing and connector material selections, constraining design flexibility.
Strategic Opportunities
- Asset-Light Testing Infrastructure:Leasing structures for powertrain validation equipment lower capital barriers for mid-tier suppliers entering range-extended hybrid ignition development.
- Commercial Vehicle Penetration:Higher per-unit ignition system content in heavy-duty applications offers margin expansion versus passenger vehicle commoditization.
- Integration Bundling:Convergence of ignition modules with thermal management systems creates value-add positioning for mechatronics-capable suppliers.
Industry Challenges
- Electromagnetic Interference Mitigation:Densely integrated engine bays in hybrid architectures demand coil-on-plug designs that suppress cross-talk without shielding mass penalties.
- Multi-Protocol Certification Burden:Evolving EPA tailpipe standards, NHTSA CAFE rules, and EU test cycles force redundant validation cycles across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ignition Systems for Range-Extended Hybrid Powertrains Market |
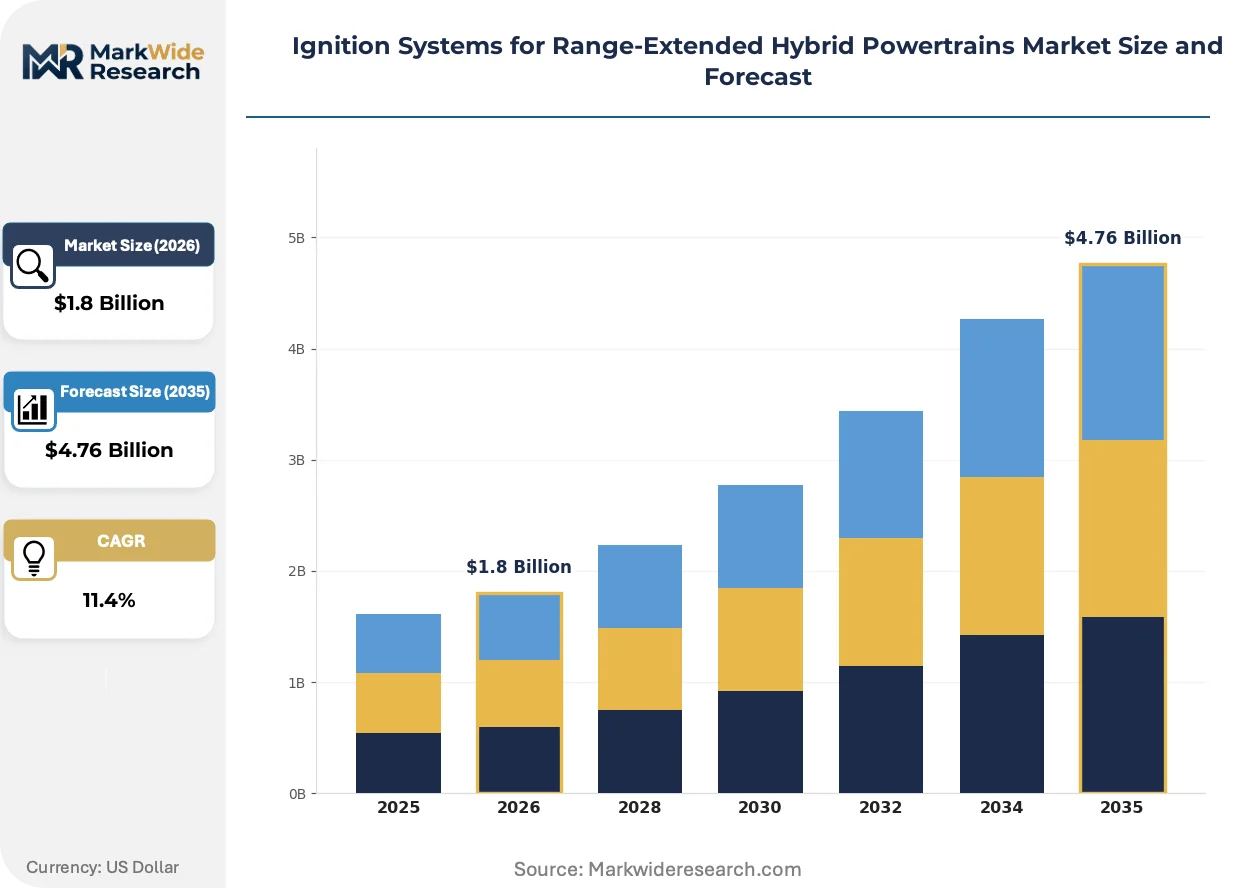
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coil-on-Plug Ignition, Distributorless Ignition, Capacitor Discharge Ignition, Transistorized Ignition Technology: Electronic Ignition, Magnetic Pickup, Optical Sensor, Plasma Ignition, Laser Ignition Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Machinery, Marine Engines, Agricultural Equipment End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Providers, Engine Rebuilders |
| Companies Covered | BorgWarner, Mahle, ZF Friedrichshafen, Valeo, Schaeffler, Magna International, Horse Powertrain, Hyundai Mobis, Rheinmetall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ignition Systems for Range-Extended Hybrid Powertrains Market Trends and Innovations
Electronic ignition architectures are displacing mechanical distributors across all vehicle classes, while plasma ignition advances from laboratory to pilot production. Three convergent developments are compressing supplier competitive windows.
Plasma ignition systems are collapsing the trade-off between lean-burn efficiency and combustion stability. These high-energy discharge devices ionize air-fuel mixtures at temperatures exceeding conventional spark capabilities. European OEMs are piloting plasma-assisted regimes in range-extended prototypes to meet Euro 7 NOx limits without lean-NOx trap hardware. The structural consequence is collapsing the addressable market for traditional high-energy inductive coils in premium powertrain programs.
EPA tailpipe standards and NHTSA corporate average fuel economy rules are compressing cold-start emission allowances to near-zero thresholds. This regulatory pressure forces ignition timing strategies that fire reliably at sub-optimal coolant temperatures. Passenger vehicle programs targeting California Air Resources Board compliance are absorbing the highest engineering overhead, retarding spark advance and compensating with secondary injection.
Fleet procurement departments are consolidating supplier relationships around integrated powertrain subsystem providers. Single-source accountability for ignition, thermal management, and engine control is displacing discrete component bidding. This concentration is most visible in North American commercial vehicle segments, where leasing companies and large fleet operators negotiate enterprise-level supply agreements spanning multiple vehicle platforms.
Ignition Systems for Range-Extended Hybrid Powertrains Market Segmentation
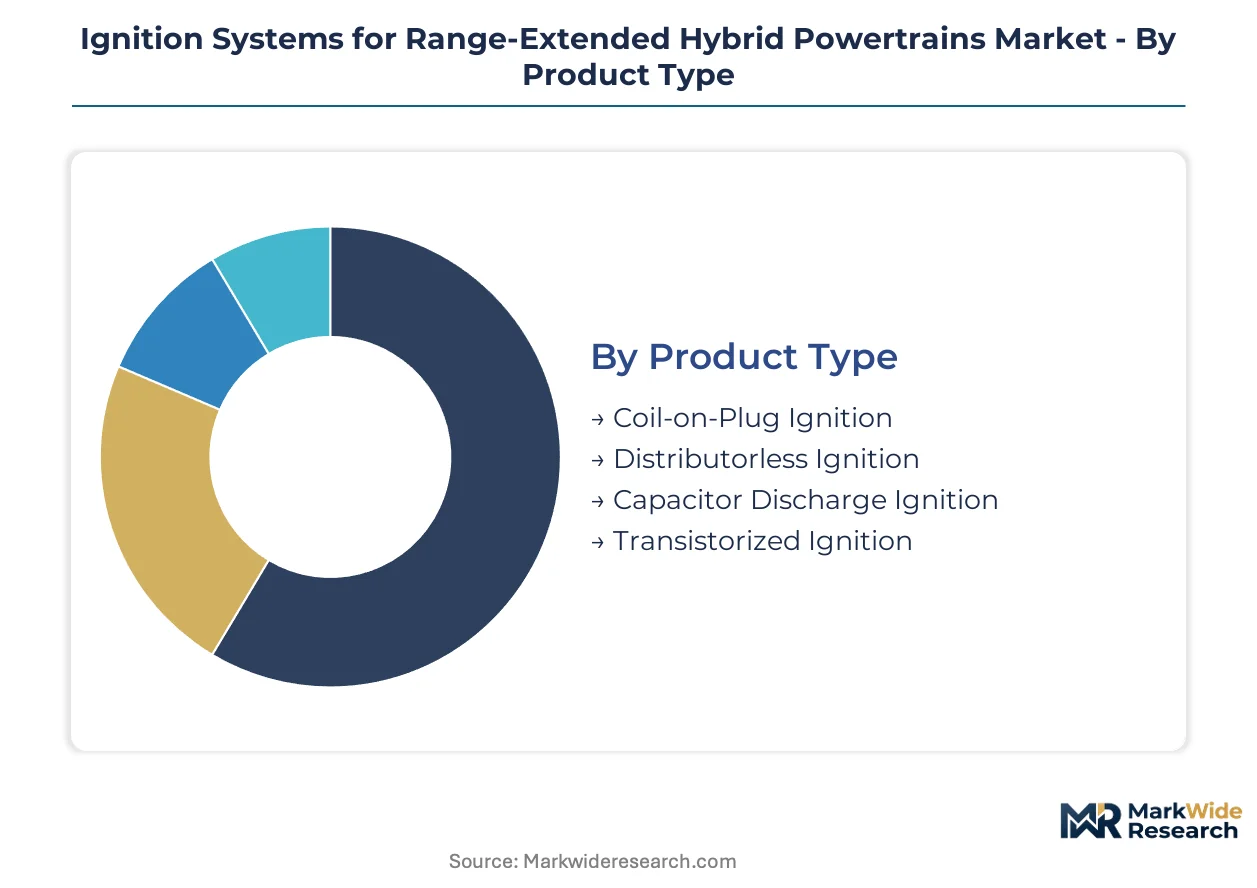
Ignition system architectures for range-extended hybrids fragment across multiple technical and commercial dimensions. Product refresh cycles vary dramatically—from mature coil-on-plug designs with decade-long production runs to experimental plasma ignition platforms still validating durability.
Product Type:
Replacement frequency diverges sharply across this category, with some architectures engineered for 150,000-mile service intervals while others face thermal cycling degradation from intermittent combustion duty.
- Coil-on-Plug Ignition:Individual coil-per-cylinder packaging eliminates distributor wear and reduces electromagnetic interference in densely packed hybrid engine bays. Passenger vehicle OEMs in Germany and Japan specify this architecture for new range-extended platforms, prioritizing packaging efficiency over service accessibility.
- Distributorless Ignition:Wasted-spark and coil-pack configurations persist in cost-optimized commercial vehicle programs where cylinder count and duty cycles favor simplified servicing. Chinese domestic automakers leverage this mature technology to meet MIIT fuel consumption targets without premium component costs.
- Capacitor Discharge Ignition:High-voltage rapid-discharge systems suit small-displacement range-extended engines requiring precise timing control across variable load profiles.
- Transistorized Ignition:Solid-state switching architectures dominate aftermarket replacement demand where backward compatibility with legacy engine management systems governs procurement.
Coil-on-Plug Ignition anchors the volume base while Plasma Ignition (within Technology) gains share at the steepest rate.
Technology:
Development investment intensity separates proven electronic architectures from emerging energy-dense modalities still climbing the manufacturing learning curve.
- Electronic Ignition:Microprocessor-controlled timing with closed-loop feedback from crankshaft position sensors enables real-time adaptation to EGR rates and fuel quality variation. This architecture commands the largest installed base across US EPA-compliant passenger vehicles, where cold-start emission protocols demand precise spark advance modulation.
- Plasma Ignition:High-energy corona discharge ionizes lean air-fuel mixtures beyond conventional spark breakdown limits, enabling 25:1+ equivalence ratios that collapse NOx formation without aftertreatment hardware. European OEM pilot programs around Stuttgart and Munich are validating thermal durability for Euro 7 compliance timelines.
- Magnetic Pickup:Variable reluctance sensors provide robust crankshaft position data in high-vibration commercial vehicle environments.
- Optical Sensor:Photoelectric timing references resist electromagnetic interference from hybrid power electronics, finding niche application in premium passenger segments.
- Laser Ignition:Focused optical breakdown ignition remains laboratory-stage for range-extended applications, constrained by window fouling and packaging volume.
Electronic Ignition captures the revenue base while Plasma Ignition expands most quickly as emission thresholds tighten.
Application:
Per-unit ignition system content scales with engine displacement and duty cycle severity, creating margin dispersion across vehicle classes.
- Passenger Vehicles:Compact transverse engine packaging favors integrated coil-on-plug modules with reduced wiring harness complexity. California Air Resources Board compliance programs drive the highest engineering overhead in this segment, requiring ignition strategies that stabilize combustion during catalyst light-off.
- Commercial Vehicles:Heavy-duty range-extended trucks and buses demand redundant ignition channels and extended service intervals that multiply component count per powertrain. Fleet operators across the United States are consolidating procurement around integrated subsystem suppliers who warranty ignition performance across million-mile duty cycles.
- Heavy-Duty Machinery:Construction and mining equipment with range-extended electric architectures requires sealed ignition systems resistant to particulate contamination.
- Marine Engines:Salt-air corrosion resistance governs housing material selection for ignition components in maritime hybrid propulsion.
- Agricultural Equipment:Dust-ingress protection and vibration isolation dominate specification requirements for farm machinery ignition systems.
Passenger Vehicles anchor the volume base while Commercial Vehicles gains share at the steepest rate as fleet TCO advantages crystallize.
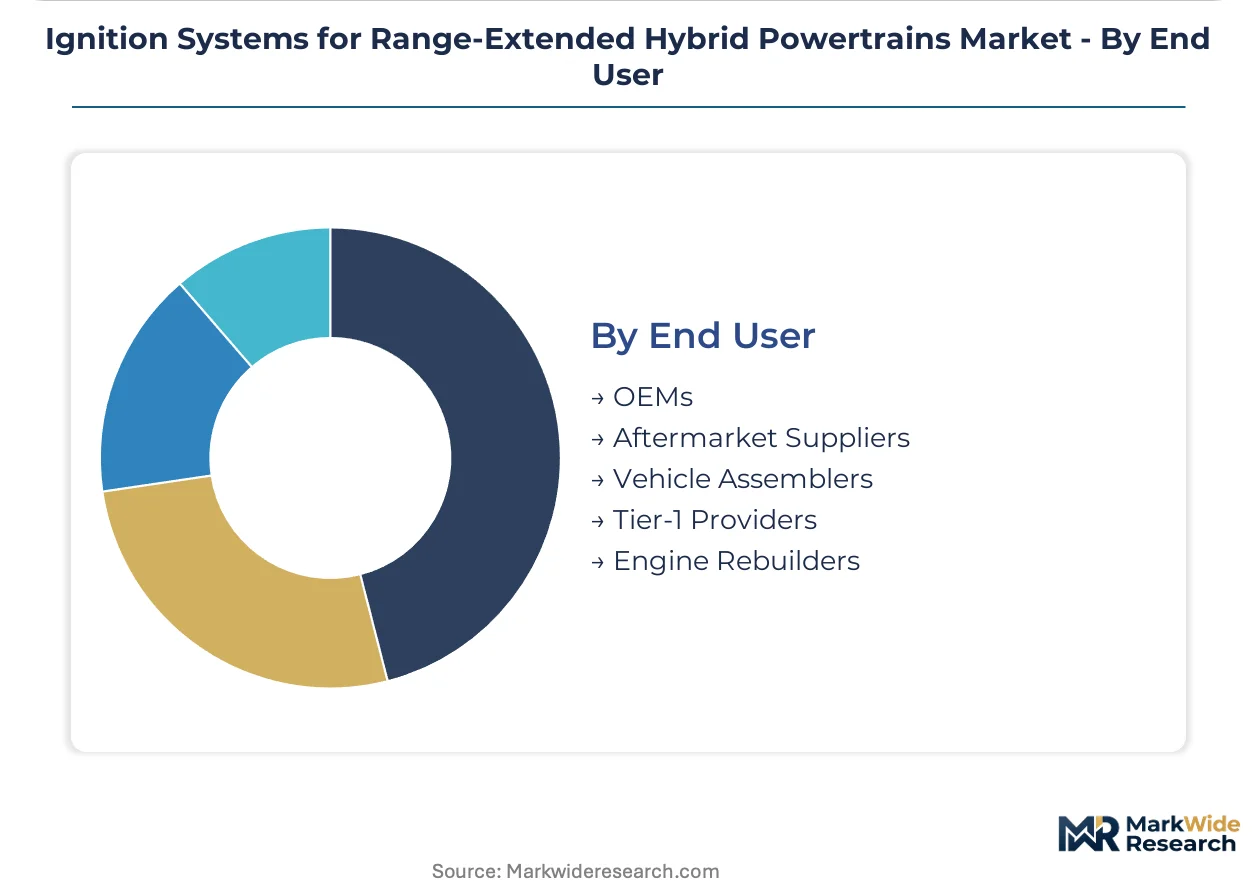
End User:
Procurement authority concentrates differently across direct OEM supply relationships versus fragmented aftermarket channels with diverging technical support expectations.
- OEMs:Original equipment manufacturers specify ignition systems at platform conception, locking in multi-year supply agreements that span vehicle generations. German automotive OEMs around Stuttgart and Munich exercise particular influence over European supplier development roadmaps.
- Tier-1 Providers:Integrated powertrain subsystem suppliers bundle ignition modules with thermal management and engine control units, displacing discrete component sourcing. BorgWarner and ZF Friedrichshafen leverage this position to capture margin through single-source accountability.
- Aftermarket Suppliers:Independent distributors serve replacement demand with reverse-engineered or licensed components, competing on price and availability rather than technical integration.
- Vehicle Assemblers:Contract manufacturers without captive engineering rely on Tier-1 specification packages for ignition system selection.
- Engine Rebuilders:Remanufacturing specialists source ignition components for overhaul programs, prioritizing interchangeability over latest-technology performance.
OEMs anchor the volume base while Tier-1 Providers gains share at the steepest rate as subsystem integration concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for ignition systems tilt toward net-import positions in markets lacking precision coil manufacturing infrastructure, while production-surplus economies ship coil-on-plug modules and plasma ignition prototypes to assembly plants in demand centers.
United States
Fleet operators across long-haul corridors are crystallizing total-cost-of-ownership advantages for range-extended hybrid commercial vehicles. NHTSA corporate average fuel economy rules compress cold-start emission allowances, forcing ignition timing strategies that fire reliably at sub-optimal coolant temperatures. Detroit's automotive supplier ecosystem anchors development programs targeting EPA tailpipe compliance.
Germany
Precision ignition controller procurement expands as domestic automakers optimize combustion-cycle efficiency for range-extended architectures. ECHA enforcement of REACH material restrictions limits housing and connector material selections, constraining design flexibility. The supplier corridor around Stuttgart and Munich concentrates development activity for European OEM programs.
China
Domestic automakers face MIIT dual carbon goals and updated fuel-consumption standards that compel combustion-cycle optimization in range-extended designs. The country's national automotive regulator enforces test protocols that redefine performance thresholds for ignition system certification. Yangtze River Delta manufacturing clusters scale coil-on-plug production for both domestic consumption and export.
Japan
Compact transverse engine packaging for passenger vehicles favors integrated coil-on-plug modules with reduced wiring harness complexity. METI energy efficiency directives shape supplier development roadmaps for hybrid powertrain components. Kanto region engineering centers validate ignition strategies for catalyst light-off stabilization.
South Korea
Integrated powertrain subsystem suppliers bundle ignition modules with thermal management systems for OEM customers. The national automotive technology regulator oversees certification against evolving emission test cycles. Seoul Capital Area R&D facilities pilot plasma-assisted combustion regimes for ultra-lean burn applications.
Ignition Systems for Range-Extended Hybrid Powertrains Market Competitive Landscape
On the supply side, the industry is consolidating around integrated mechatronics providers capable of bundling ignition modules with adjacent thermal management and engine control systems. Three strategic archetypes dominate: diversified automotive Tier-1 conglomerates with chassis-electronics expertise, precision combustion specialists pursuing plasma ignition breakthroughs, and regional component fabricators serving cost-optimized commercial vehicle programs. Competitive moves center on subsystem integration partnerships and asset-light testing infrastructure leasing to lower capital barriers for technology validation.
Among diversified automotive Tier-1 conglomerates, BorgWarner and ZF Friedrichshafen exemplify the integration-bundling archetype, occupying positions that leverage chassis-electronics expertise into engine-management convergence. Mahle represents the precision combustion specialist tier, anchoring development activity around advanced ignition modalities. These three entities collectively illustrate how supplier competitive windows are compressing toward single-source accountability for multi-technology powertrain subsystems.
| Leading Market Players |
|---|
| BorgWarner |
| Mahle |
| ZF Friedrichshafen |
| Valeo |
| Schaeffler |
| Magna International |
| Horse Powertrain |
| Hyundai Mobis |
| Rheinmetall |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's precision coil manufacturing corridor concentrates high-voltage ignition coil capacity for European OEM programs, translating geographic supply dominance into pricing power for Tier-1 suppliers serving range-extended hybrid platforms. This clustering dynamic compresses margins for mid-tier competitors while reinforcing contract-based long-term offtake structures for anchor suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in multi-year supply agreements across vehicle generations. Price differentiation separates plasma ignition systems certified for Euro 7 compliance from standard coil-on-plug modules serving cost-optimized commercial programs. Cost compression in mid-tier supplier tiers is intensifying because rare earth magnet volatility destabilizes high-voltage coil cost structures. Fleet procurement departments demonstrate highest price sensitivity, while German automotive OEMs prioritize technical integration over unit cost.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese rare earth processing facilities, Japanese magnet alloy refiners, and German precision coil winding operations. Raw material dependencies center on rare earth magnets, copper windings, and high-temperature polymer housings. Single-source vulnerability concentrates in Chinese rare earth supply channels. Distribution runs through Tier-1 integrated subsystem suppliers bundling ignition modules with thermal management systems for OEM direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment protects incumbent positions. Multi-protocol certification burdens across EPA, NHTSA, and EU test cycles create switching costs that deter new supplier entry.
For Market Incumbents: Harden certification investments around plasma ignition durability validation to defend against emerging combustion-technology substitutes. Deepen backward integration into rare earth magnet supply channels to mitigate price volatility exposure. Capacity expansion in Yangtze River Delta manufacturing clusters captures Chinese domestic automaker procurement growth. For New Entrants and Emerging Players: Establish a beachhead in North American commercial vehicle aftermarket channels where fleet operators prioritize availability over OEM integration. Target distributorless ignition architectures serving Chinese domestic automakers meeting MIIT fuel consumption targets without premium component costs. Pursue asset-light testing infrastructure leasing to lower capital barriers for technology validation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision combustion specialists with plasma ignition pilot programs advancing toward production scale. Long-term viability hinges on Euro 7 compliance timelines and subsequent regulatory adoption cycles. Acquisition targets should demonstrate thermal cycling durability validation and subsystem integration capabilities. Watch plasma ignition pilot-to-production conversion rates as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Ignition Pilot-to-Production Scale-Up | Euro 7 NOx compliance without lean-NOx trap hardware validates premium positioning for European OEM programs. |
| Backward Integration into Rare Earth Magnet Supply | Neodymium price volatility hedging secures cost structures for high-voltage coil manufacturing operations. |
| Subsystem Integration Partnership | Bundling ignition modules with thermal management creates single-source accountability valued by fleet operators. |
| Asset-Light Testing Infrastructure Leasing | Powertrain validation equipment leasing lowers capital barriers for mid-tier supplier technology entry. |
| Multi-Protocol Certification Investment | EPA tailpipe and NHTSA CAFE compliance expands addressable market across North American OEM platforms. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement patterns anchors the qualitative findings. Primary interviews with powertrain development executives, ignition system R&D directors, fleet procurement managers, and aftermarket distribution specialists combine with secondary validation from EPA certification databases, NHTSA fuel economy filings, MIIT fuel consumption bulletins, and vehicle production registration data. Bottom-up segment sizing and top-down market triangulation reconcile volume estimates across the analysis window.
Calibration against historical production volumes and disclosed supplier contract values shapes the analytical framework. Segmentation dimensions span product type, technology modality, vehicle application, and regional production cluster. CAGRs derive from regression analysis of disclosed OEM platform launch timelines and supplier capacity expansion announcements. Forecast inputs incorporate MIIT dual carbon policy enforcement intensity and Euro 7 regulatory finalization trajectories.
Macroeconomic conditions sit as an overlay; deviation in rare earth commodity prices, automotive production volumes, or regulatory enforcement timelines would shift the trajectory. Forecasts reflect documented assumptions about technology adoption curves and certification protocol harmonization. Cross-checking against IHS Markit vehicle production forecasts and disclosed Tier-1 supplier backlog data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
North America Micro Hybrid Vehicles Market