
 Canada Hybrid Electric Vehicle Battery Market | 2026-2036
Canada Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Hybrid Electric Vehicle Battery Market Insights
Canada's Clean Fuel Regulations is pivoting the cost-of-entry calculus for battery suppliers serving the hybrid electric vehicle segment. LG Energy Solution leverages its established North American manufacturing footprint to sustain cathode supply commitments for Canadian OEM programs. Panasonic Holdings Corporation anchors its position through high-nickel cell chemistry leadership aligned with cold-climate performance requirements. Electrovaya Inc. competes as a domestic specialist with lithium-ion pouch configurations optimized for regional duty cycles.
Canada Hybrid Electric Vehicle Battery refers to electrochemical energy storage systems combining internal combustion engines with electric propulsion, typically employing nickel-metal hydride or lithium-ion cell architectures with nominal voltages between 200 and 350 volts and operating temperatures engineered for sub-zero performance. These systems buffer regenerative braking energy and deliver torque-fill during transient power demands, reducing fuel consumption in passenger and commercial platforms. Li-ion chemistry leads new platform introductions due to superior gravimetric energy density and declining cell costs, while NiMH retains share in cost-sensitive hybrid variants where thermal stability outweighs weight penalties. The below 50 kWh capacity band dominates current hybrid architectures, though 50-100 kWh configurations are gaining traction in plug-in hybrid commercial vehicles where extended electric range supports fleet electrification targets.
Health Canada and Environment and Climate Change Canada shape product standards through emissions compliance frameworks and battery recycling mandates, while Transport Canada administers vehicle safety certification for high-voltage systems. The federal zero-emission vehicle sales target creates phased demand pull, with provincial rebate programs in Quebec and British Columbia accelerating consumer uptake. Stakeholders must monitor regulatory alignment between federal ZEV mandates and provincial grid infrastructure timelines, as charging capacity constraints could redirect investment toward conventional hybrid platforms rather than plug-in variants.
Market Dynamics
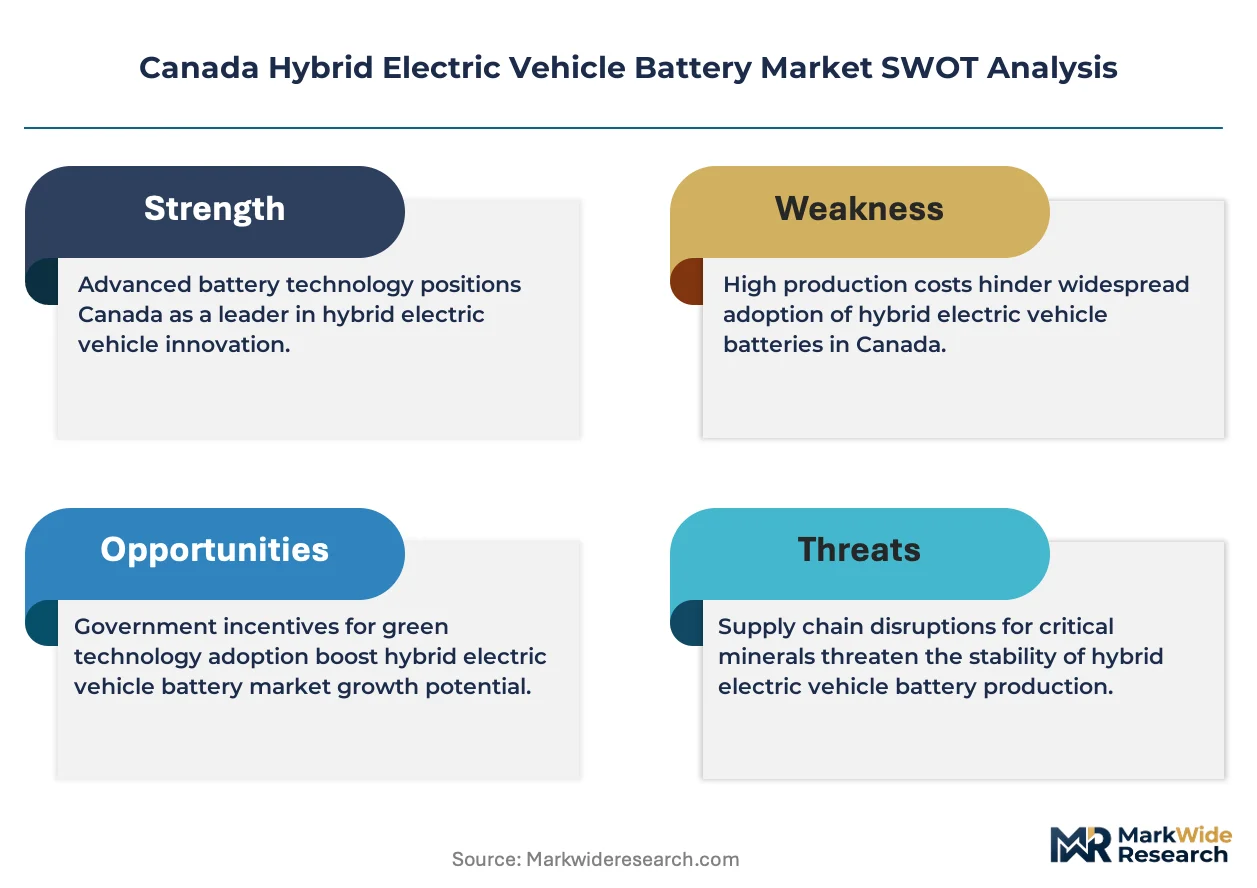
Federal zero-emission vehicle mandates are compressing compliance timelines for fleet operators across Ontario and British Columbia, redirecting procurement budgets toward hybrid platforms while cathode supply concentration in East Asia creates procurement bottlenecks for domestic battery assemblers.
Growth Catalysts
- Clean Fuel Regulations:The federal framework is recalibrating total-cost-of-ownership calculations for commercial fleets operating medium-duty delivery corridors through Toronto and Vancouver.
- Quebec and British Columbia provincial rebate programs:Consumer-facing incentives are accelerating household adoption of plug-in hybrid architectures in urban centers.
- Li-ion gravimetric energy density improvements:Cell-level advances are enabling extended electric range in commercial van platforms without payload penalties.
Market Restraints
- Nickel and cobalt price volatility:Cathode raw material cost swings are compressing margin visibility for domestic pack assemblers serving cost-sensitive hybrid variants.
- East Asian cathode supply concentration:Over-reliance on concentrated overseas precursor processing creates geopolitical exposure for Canadian OEM programs.
- Sub-zero thermal management complexity:Cold-climate performance requirements impose additional engineering overhead that NiMH alternatives avoid.
Strategic Opportunities
- Prairie province fleet electrification:Alberta and Saskatchewan commercial operators remain underpenetrated relative to coastal corridors, presenting first-mover positioning for regional service networks.
- Regenerative braking integration with autonomous logistics:Predictive route optimization converging with brake-energy recovery systems is opening efficiency gains in last-mile delivery.
- Battery recycling mandates under Environment and Climate Change Canada:End-of-life regulations are creating circular-economy revenue streams for domestic recyclers.
Industry Challenges
- High-voltage systems certification timelines:Transport Canada safety validation protocols for new pack architectures are extending product launch cycles.
- Electrochemical engineering talent scarcity:Cell characterization and thermal modeling expertise shortages are constraining domestic R&D expansion.
- Legacy fleet integration complexity:Retrofit compatibility with existing maintenance infrastructure is fragmenting procurement decisions among municipal operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Hybrid Electric Vehicle Battery Market |
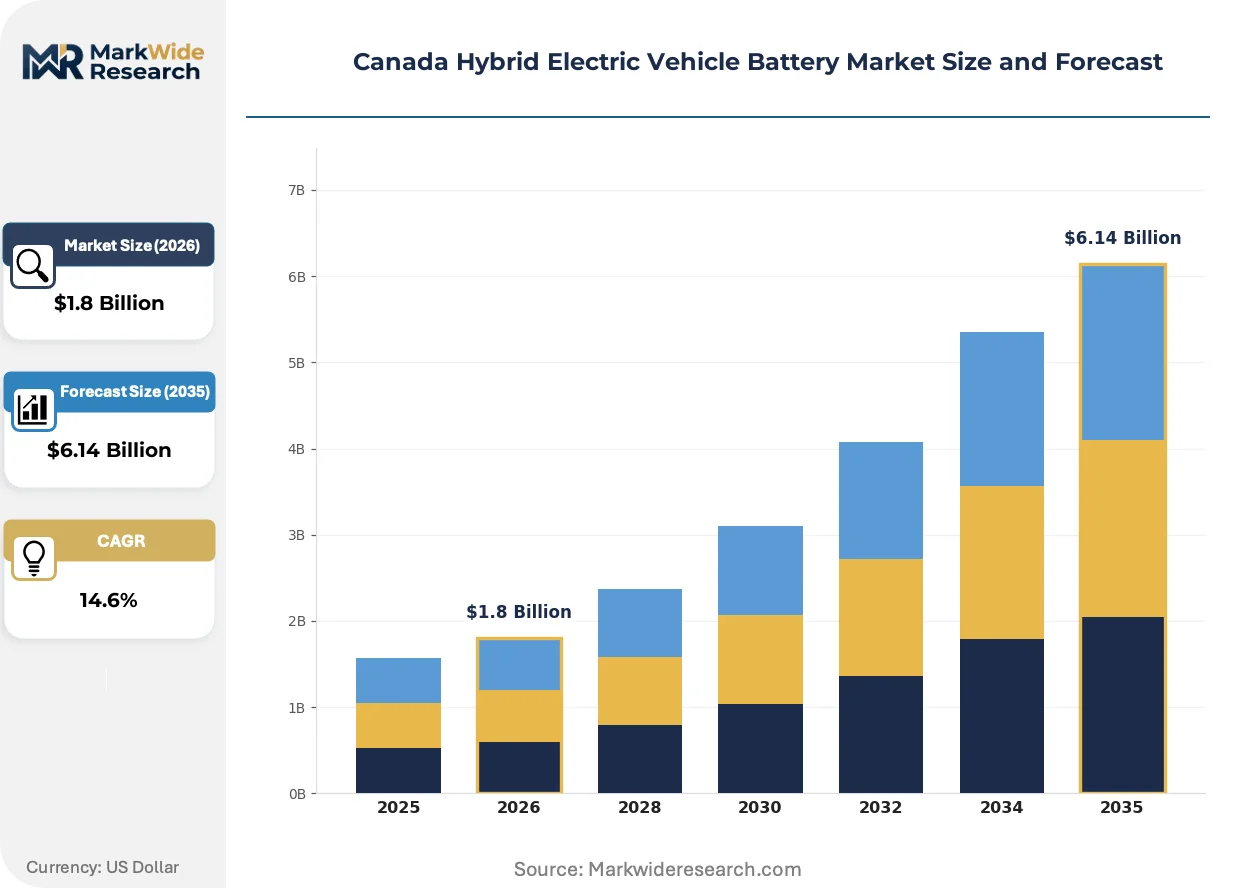
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: NiMH, Li-ion, Li-Po, Lead Acid Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, SUVs Capacity: Below 50 kWh, 50-100 kWh, Above 100 kWh, Ultra High Capacity Application: Urban Commuting, Long-Distance Travel, Delivery Services, Fleet Operations |
| Companies Covered | LG Energy Solution, Panasonic Holdings Corporation, Electrovaya Inc., EnerSys, Exide Industries Ltd, Stellantis, Volkswagen, Northvolt, Li-Cycle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Hybrid Electric Vehicle Battery Market Trends and Innovations
Silicon-anode chemistries and solid-state prototyping are compressing performance gaps between hybrid and full-electric platforms, while regulatory pressure on supply chain provenance is forcing cathode sourcing transparency.
Lithium iron phosphate (LFP) cell architectures are electrifying medium-duty commercial platforms through superior thermal stability and reduced cobalt dependency. Fleet operators in Vancouver's port logistics corridor are adopting LFP configurations for daily charge-cycling intensity. This chemistry is electrifying procurement specifications away from high-nickel alternatives in cost-sensitive commercial segments.
Health Canada and Environment and Climate Change Canada are tightening battery recycling mandates through extended producer responsibility frameworks. The industrial consequence is forcing pack assemblers to design for disassembly and materials recovery from initial concept stages. Commercial vehicle platforms serving Ontario's Golden Horseshoe are responding with modular pack architectures that simplify end-of-life processing.
Fleet procurement departments are consolidating vendor relationships around full-service battery lifecycle contracts rather than transactional cell purchases. The direct-OEM channel is displacing independent distributor networks for large commercial accounts. This concentration is most visible among Toronto-area logistics operators managing thousand-plus vehicle deployments.
Canada Hybrid Electric Vehicle Battery Market Segmentation
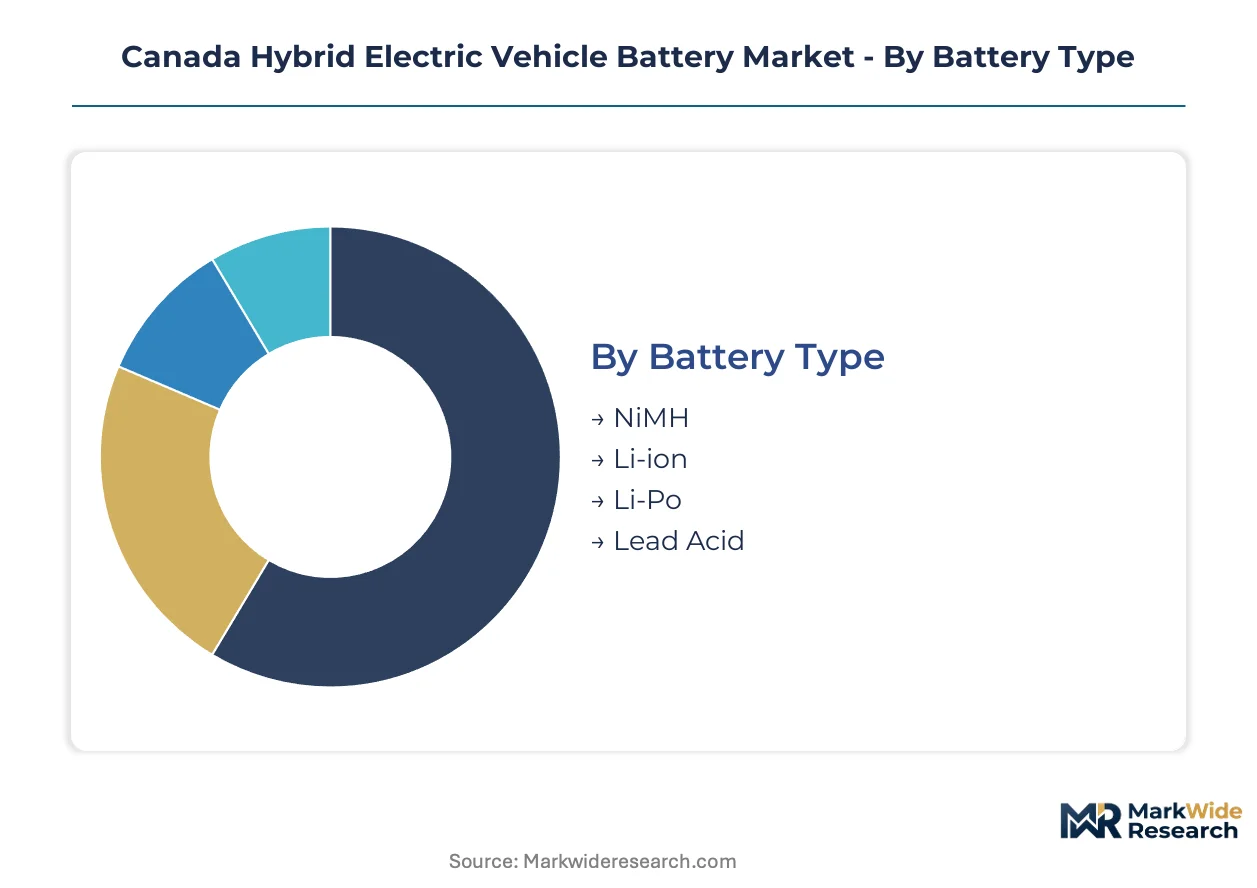
Segmentation in the Canada Hybrid Electric Vehicle Battery Market reveals how Transport Canada certification requirements and Health Canada safety protocols map differently across battery chemistries and vehicle platforms. Procurement patterns diverge sharply between commercial fleet operators facing zero-emission compliance deadlines and consumer segments responding to provincial rebate structures.
Battery Type:
Transport Canada's high-voltage system certification protocols impose differentiated compliance burdens across electrochemical architectures, with thermal runaway testing requirements varying by cell chemistry and energy density.
- NiMH:Nickel-metal hydride cells deliver proven thermal stability in sub-zero operating conditions without complex battery management systems. Fleet operators in Alberta and Saskatchewan favor this chemistry for cost-sensitive hybrid retrofits where cold-start reliability outweighs gravimetric efficiency concerns.
- Li-ion:Lithium-ion architectures dominate new platform development through superior energy density and declining cell costs. Medium-duty delivery vans serving Toronto and Vancouver logistics corridors specify Li-ion packs to maximize electric range without payload penalties under Clean Fuel Regulations compliance timelines.
- Li-Po:Lithium-polymer pouch configurations from domestic specialists like Electrovaya optimize packaging efficiency for regional duty cycles.
- Lead Acid:Flooded and AGM variants retain niche presence in micro-hybrid stop-start systems where cost minimization dominates engineering specifications.
Li-ion sits at the top of the volume ranking, with LFP sub-variants climbing the fastest as fleet procurement shifts toward cobalt-reduced chemistries.
Vehicle Type:
Vehicle classification determines which provincial incentive programs apply and whether federal zero-emission vehicle mandates trigger compliance obligations for fleet operators.
- Passenger Cars:Consumer hybrid architectures in Quebec and British Columbia benefit from provincial rebate programs accelerating household electrification. These platforms typically deploy below 50 kWh configurations optimized for urban charge-cycling rather than extended electric range.
- Commercial Vehicles:Medium-duty vans and trucks face the most aggressive federal compliance timeline compression. Fleet procurement departments across Ontario's Golden Horseshoe are consolidating vendor relationships around full-service battery lifecycle contracts for thousand-plus vehicle deployments.
- Two-Wheelers:Electric-assist bicycles and scooters fall outside federal ZEV mandate scope but attract municipal electrification subsidies in Vancouver and Montreal.
- SUVs:Larger platform footprints accommodate higher-capacity pack architectures, though weight penalties constrain hybrid efficiency gains relative to sedan counterparts.
Commercial Vehicles command the dominant revenue share, with SUVs expanding most quickly as manufacturers respond to consumer preference shifts toward larger platform electrification.
Capacity:
Energy storage sizing directly correlates with application duty cycle intensity and determines whether platforms qualify as conventional hybrids or plug-in variants under federal classification frameworks.
- Below 50 kWh:This band dominates current hybrid architectures where battery systems buffer regenerative braking energy and provide torque-fill during transient power demands. Passenger cars and light commercial platforms across Toronto and Vancouver urban corridors standardize on these configurations for cost-optimized electrification.
- 50-100 kWh:Extended-range plug-in hybrid commercial vehicles specify these capacities to support fleet electrification targets without full BEV infrastructure dependency. Port logistics operators in Vancouver's container corridor are adopting 50-100 kWh LFP configurations for daily charge-cycling intensity.
- Above 100 kWh:Heavy-duty hybrid prototypes and range-extended commercial platforms explore these capacities for regional haul applications.
- Ultra High Capacity:Experimental architectures for specialized mining and resource extraction equipment in Alberta's oil sands regions test boundary conditions for hybrid electrification.
Below 50 kWh maintains volume leadership, with 50-100 kWh gaining share fastest as fleet operators balance electric range requirements against charging infrastructure constraints.
Application:
End-use context shapes thermal management requirements, cycle life specifications, and whether regenerative braking integration delivers sufficient efficiency gains to justify platform cost premiums.
- Urban Commuting:Stop-start traffic patterns maximize regenerative braking recovery potential. Montreal and Toronto metropolitan area drivers benefit most from hybrid architectures where frequent deceleration events recharge battery systems.
- Long-Distance Travel:Highway-dominated duty cycles reduce regenerative braking opportunity, making conventional hybrid efficiency gains harder to capture relative to urban applications.
- Delivery Services:Last-mile operators in Vancouver's dense urban core combine predictive route optimization with brake-energy recovery systems. Autonomous logistics integration is opening efficiency gains for commercial fleets managing fixed delivery schedules.
- Fleet Operations:Large-scale deployments across Ontario and British Columbia face compressed compliance timelines under federal ZEV mandates. Procurement standardization around modular pack architectures simplifies maintenance infrastructure and end-of-life processing under Environment and Climate Change Canada recycling mandates.
Fleet Operations represents the largest addressable segment, with Delivery Services showing the steepest expansion trajectory as e-commerce logistics electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's automotive corridor established Canada's hybrid battery scaling foundation through decades of powertrain manufacturing heritage concentrated around the Golden Horseshoe.
Ontario
Toronto-area logistics operators and Windsor-Toronto automotive suppliers drive procurement concentration for medium-duty commercial platforms. Transport Canada administers vehicle safety certification protocols from its Ottawa headquarters, compressing product launch timelines for new pack architectures. The Golden Horseshoe manufacturing belt anchors cathode processing partnerships and pack assembly operations serving Great Lakes cross-border supply chains.
Quebec
Montreal metropolitan commuters and provincial fleet operators generate sustained demand for urban-optimized hybrid configurations. The province's zero-emission vehicle rebate programs accelerate household adoption of plug-in architectures. Quebec-based mining operations supply battery-grade lithium to regional processing facilities, creating upstream integration opportunities for domestic assemblers.
British Columbia
Vancouver port logistics corridors and municipal electrification subsidies concentrate commercial vehicle deployment along the Pacific gateway. Environment and Climate Change Canada recycling mandates shape end-of-life processing requirements for regional operators. The Lower Mainland serves as the primary entry point for East Asian cell imports, with customs facilitation supporting just-in-time cathode supply.
Alberta
Calgary and Edmonton fleet operators remain underpenetrated relative to coastal corridors, presenting expansion opportunities for cold-climate battery configurations. The province's oil sands equipment electrification pilots test boundary conditions for heavy-duty hybrid architectures. Regional service network gaps create first-mover positioning for pack assemblers establishing prairie maintenance infrastructure.
Atlantic Canada
Halifax port logistics and provincial government fleet procurement generate modest but growing demand for hybrid commercial platforms. Federal zero-emission vehicle mandates apply uniformly across all provinces, creating compliance obligations for municipal operators. The region's renewable energy integration targets align with battery storage co-location opportunities at wind and tidal generation sites.
Canada Hybrid Electric Vehicle Battery Market Competitive Landscape
The competitive structure tilts toward multinational cell manufacturers with established North American manufacturing footprints. Domestic specialists occupy niche positions serving regional duty cycles with customized pouch configurations. Three archetypes dominate: Korean and Japanese conglomerates with integrated cathode supply chains, Canadian specialists optimizing for cold-climate performance requirements, and European entrants pursuing circular-economy recycling integration. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure cathode precursor commitments.
Among Korean and Japanese conglomerates, LG Energy Solution and Panasonic Holdings Corporation anchor the multinational tier with established cathode supply commitments for Canadian OEM programs. Electrovaya Inc. occupies the domestic specialist position, representing Canadian lithium-ion pouch configuration expertise optimized for regional duty cycles. These three exemplify the competitive spectrum spanning integrated global supply chains versus localized engineering adaptation.
| Leading Market Players |
|---|
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Electrovaya Inc. |
| EnerSys |
| Exide Industries Ltd |
| Stellantis |
| Volkswagen |
| Northvolt |
| Li-Cycle |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement departments at Ontario and British Columbia logistics operators concentrate buying power around full-service battery lifecycle contracts, anchoring a contract-based long-term offtake pricing model that locks in cathode supply commitments against nickel and cobalt price volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high-nickel cell chemistries with cold-climate certification from LFP configurations and NiMH alternatives for cost-sensitive retrofits. Price differentiation rests on cathode material grade and Transport Canada safety validation tier. Cost compression in the economy tier is intensifying because East Asian precursor supply bottlenecks compress margin visibility for domestic pack assemblers. Municipal fleet operators exhibit highest price sensitivity, while autonomous logistics platforms with predictive route optimization show lowest sensitivity due to efficiency capture potential.
Supply Chain Analysis
Reverse-logistics flows for end-of-life battery recovery are creating circular-economy revenue streams under Environment and Climate Change Canada extended producer responsibility frameworks, with modular pack architectures designed for disassembly from initial concept stages. Geographic supply concentration centers on China, South Korea, and Japan for cathode precursor processing and cell manufacturing. Raw material dependencies draw from Chilean lithium, Indonesian nickel, and Congolese cobalt. Single-source vulnerability in East Asian cathode supply creates geopolitical exposure for Canadian OEM programs. Distribution runs through direct-OEM channels displacing independent distributor networks for large commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada Hybrid Electric Vehicle Battery Market operates as a regulatory compounder where federal zero-emission vehicle sales targets create phased demand pull with compliance deadlines compressing fleet procurement timelines through 2035.
For Market Incumbents: Deploy cathode supply chain diversification to mitigate East Asian concentration risk. Secure precursor processing partnerships in Chile and Australia to reduce single-source vulnerability. Invest in Transport Canada high-voltage systems certification capabilities to compress product launch cycles against emerging domestic specialists.
For New Entrants and Emerging Players: Launch via regional service network partnerships targeting Alberta and Saskatchewan fleet operators where prairie province commercial penetration remains underdeveloped relative to coastal corridors. Focus on cold-climate thermal management specialization for sub-zero operating conditions. Pursue full-service lifecycle contracts rather than transactional cell sales to match incumbent positioning.
For Investors and Strategic Acquirers: Korean and Japanese battery conglomerates are the most active acquirer in this space, seeking cathode supply security and North American manufacturing footprint expansion. Long-term viability hinges on circular-economy recycling integration under tightening federal mandates. Monitor Environment and Climate Change Canada recycling mandate enforcement intensity as inflection indicator for domestic recycler valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Supply Agreement | Locks in precursor commitments from Chilean and Australian mining operations for Canadian OEM programs. |
| Transport Canada Certification Investment | Compresses high-voltage systems safety validation timelines for new Li-ion pack architectures. |
| Prairie Service Network Expansion | Captures first-mover positioning in Alberta and Saskatchewan fleet electrification corridors. |
| Battery Recycling Infrastructure Buildout | Creates circular-economy revenue streams under federal extended producer responsibility frameworks. |
| LFP Chemistry Transition | Reduces cobalt dependency while matching thermal stability requirements for Vancouver port logistics intensity. |
Research Methodology
Multiple input streams — primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, and fleet operations directors; secondary validation through Transport Canada safety certification databases, Environment and Climate Change Canada regulatory filings, and vehicle production registries; plus bottom-up and top-down triangulation — were reconciled to construct market estimates.
Historical shipment data cross-referenced against panel input from cathode suppliers and pack assemblers anchored the analytical framework across the analysis window. Segmentation dimensions modeled include battery chemistry architecture, vehicle platform classification, energy capacity banding, and regional fleet electrification corridor. CAGRs were derived from slope analysis of interpolated annual values. Industry-specific forecast inputs incorporated Clean Fuel Regulations compliance timeline phasing and provincial rebate program uptake curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel-cobalt price volatility spikes and Transport Canada certification backlog scenarios. Practitioners should monitor federal ZEV mandate alignment with provincial grid infrastructure timelines for early signals of hybrid versus plug-in hybrid investment redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
North America Micro Hybrid Vehicles Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Hybrid Truck Market