
 India Hybrid Vehicles Market | 2026-2036
India Hybrid Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
India Hybrid Vehicles Market Foresight
Multi-source procurement for battery management systems is pivoting toward domestic vendors as import costs fluctuate. Toyota Kirloskar Motor Private Limited anchors its hybrid strategy through deep supplier relationships in Karnataka. Maruti Suzuki India Limited leverages its nationwide service density to sustain aftermarket loyalty for mild-hybrid variants. Tata Motors Limited specializes in integrating indigenous power electronics with its electric-petrol hybrid architecture.
India hybrid vehicles combine an internal combustion engine with one or more electric motors, typically employing a 48V to 400V battery pack and regenerative braking to recapture kinetic energy; these systems reduce fuel consumption by enabling electric-only propulsion at low speeds and supplementing engine torque during acceleration. Their primary purpose is to lower tailpipe emissions without requiring external charging infrastructure, bridging the gap between conventional ICE vehicles and full battery-electric platforms. Powertrain technology segmentation shows parallel hybrid configurations dominating current production volumes due to lower retrofit complexity, while plug-in hybrid architectures capture expanding margin pools among premium SUV buyers seeking extended electric-only range. Vehicle type segmentation reveals SUVs absorbing disproportionate engineering investment as manufacturers respond to fleet operator preferences for higher ground clearance and cargo capacity in urban delivery routes.
BIS certification requirements for automotive electrical systems and CEA guidelines for grid-interactive charging infrastructure shape product development timelines and component sourcing decisions for OEMs. The PLI scheme administered by DPIIT redirects capital toward localized motor and inverter manufacturing, tightening eligibility criteria annually to deepen domestic value addition. Stakeholders must monitor how state-level EV policies in Delhi, Maharashtra, and Gujarat treat hybrid eligibility for road-tax waivers relative to full-electric alternatives, as these classifications determine effective consumer pricing and fleet procurement economics.
Market Dynamics
The PLI scheme's tightening localization mandates are forcing powertrain suppliers to relocate motor and inverter production to Karnataka and Tamil Nadu, compressing import-dependent margins while accelerating domestic value addition.
Growth Catalysts
- Fleet electrification mandates:Urban freight operators in Delhi and Mumbai face diesel curbs that push adoption of 48V mild-hybrid systems for last-mile logistics without charging infrastructure dependency.
- CEA grid-interactive guidelines:Standards for vehicle-to-building power flow enable commercial fleets to monetize stationary battery assets, expanding total cost of ownership advantages for plug-in hybrid procurement.
- Indigenous power electronics:Localized silicon carbide inverter manufacturing under revised PLI criteria reduces bill-of-material exposure to yen and euro volatility.
Market Restraints
- Lithium-ion cell import concentration:Over 90 percent of battery cell supply originates from East Asian contract manufacturers, exposing OEMs to shipping rate spikes and customs processing delays at Nhava Sheva and Chennai ports.
- BIS certification timelines:Automotive electrical system testing protocols extend product validation cycles by four to six months versus conventional ICE platforms.
- Full-electric substitution threat:Falling battery pack costs and expanding fast-charging corridors in Maharashtra and Gujarat redirect premium buyer budgets away from plug-in hybrid architectures.
Strategic Opportunities
- Semi-urban penetration gaps:Tier-3 and Tier-4 cities across Uttar Pradesh and Madhya Pradesh lack reliable grid infrastructure, creating addressable space for self-charging hybrid systems that require no external power source.
- State-level road-tax waivers:Gujarat and Maharashtra classification rules that extend tax exemptions to strong hybrids reduce effective consumer pricing versus conventional ICE equivalents.
- Powertrain convergence:Integration of 48V belt-driven starter-generators with compressed natural gas combustion systems opens fleet segments facing dual fuel-cost and emissions pressures.
Industry Challenges
- Embedded software talent scarcity:Battery management system firmware development requires automotive-grade functional safety expertise that concentrates in Bengaluru and Pune, constraining supplier scaling.
- Dual-homologation complexity:Parallel certification under BIS automotive electrical standards and CMVR safety regulations extends engineering validation for hybrid-specific components.
- Service network retraining costs:High-voltage safety protocols demand technician certification programs that strain Maruti Suzuki and Tata Motors dealership economics in rural markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Hybrid Vehicles Market |
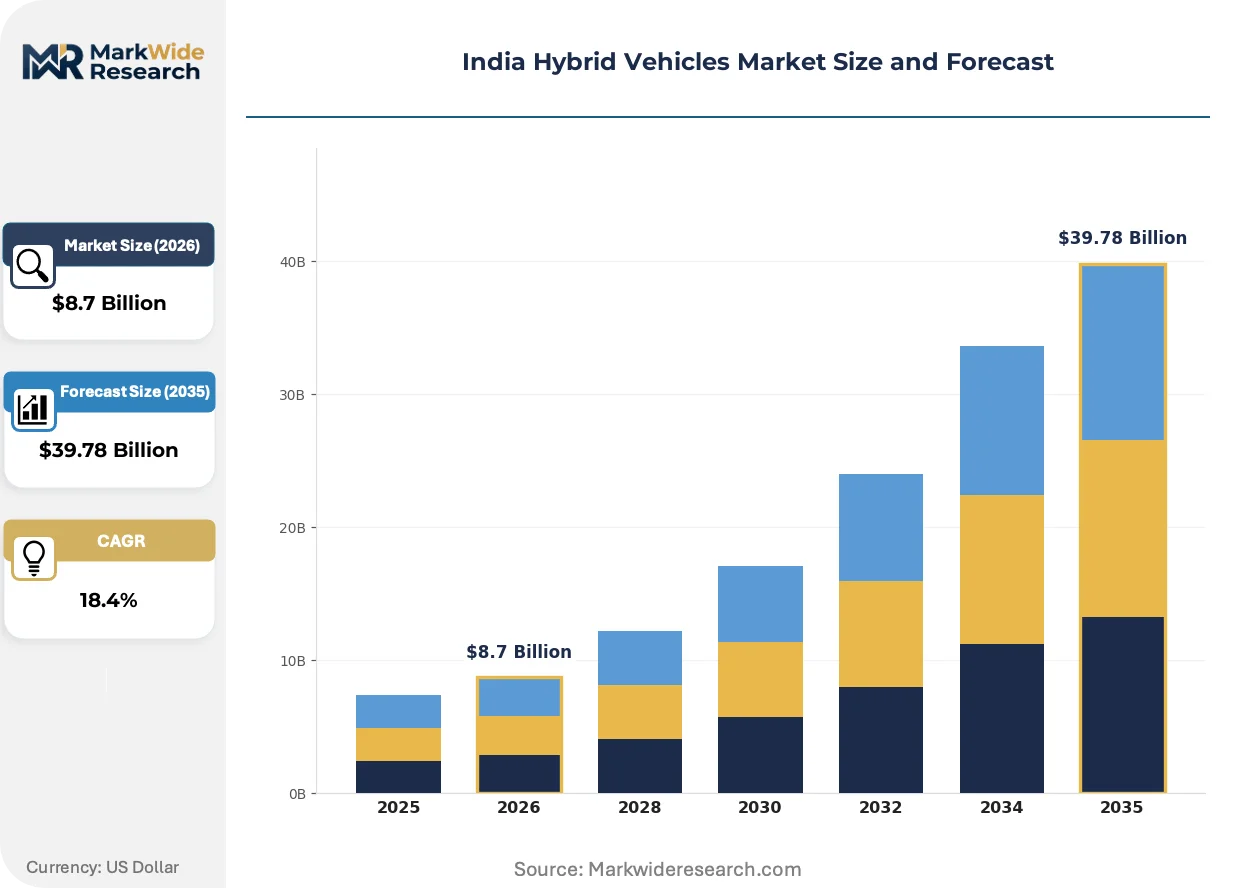
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Coupe Powertrain Technology: Parallel Hybrid, Series Hybrid, Plug-in Hybrid, Mild Hybrid Fuel Type: Petrol, Diesel, Electric, Ethanol Customer Segment: Personal Use, Fleet Operators, Government, Ride-sharing |
| Companies Covered | Honda Motor Company Limited, Kia Motors India Private Limited, Maruti Suzuki India Limited, Nissan Motor India Private Limited, Renault India Private Limited, Toyota Kirloskar Motor Private Limited, Hyundai Motor India Limited, Tata Motors Limited, Mahindra & Mahindra Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Hybrid Vehicles Market Shifts & Advancements
Powertrain architecture decisions are pivoting around battery voltage thresholds and thermal management integration, with supplier R&D budgets reallocating toward localized inverter production and regenerative braking optimization.
Silicon carbide-based inverters are overtaking conventional insulated-gate bipolar transistor modules in 400V hybrid architectures. Fleet operators purchasing premium SUVs for executive transport specify SiC-equipped power electronics to maximize energy recuperation during urban stop-start cycles. This transition is compressing price premiums for wide-bandgap semiconductors toward parity with silicon-based alternatives by 2027.
PLI scheme eligibility revisions administered by DPIIT now require 50 percent domestic value addition for motor and inverter assemblies. Automotive component suppliers in Pune and Chennai are reconfiguring procurement to source magnet wire and laminated steel cores from local mills. OEM product planning teams are accelerating platform launches to capture incentive windows before annual tightening thresholds take effect.
Fleet procurement committees now weight total cost of ownership over sticker price, unbundling after-sales service contracts from vehicle acquisition. Logistics operators in Tamil Nadu negotiate separate agreements for battery health monitoring and powertrain refurbishment, transferring residual value risk to third-party asset managers. This shift is most visible among e-commerce delivery fleets with standardized 100,000-kilometer annual utilization targets.
India Hybrid Vehicles Market Segmentation
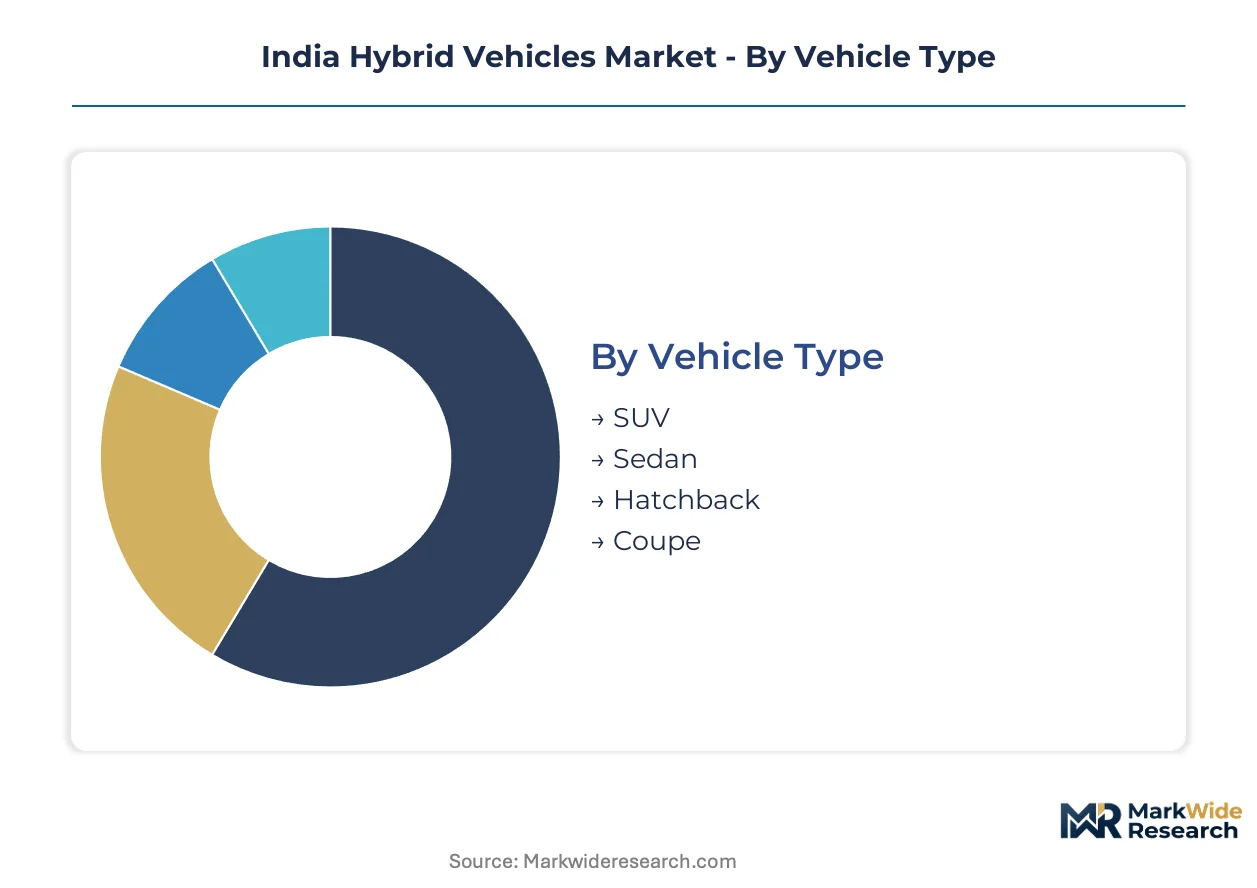
Segmentation in the India hybrid vehicles market reveals how buyer priorities diverge across powertrain architectures and duty cycles. Fleet operators prioritize total cost of ownership and charging infrastructure independence, while personal buyers respond to state-level road-tax waivers and fuel-cost volatility. Understanding these splits enables OEMs to align platform development with procurement economics.
Vehicle Type:
Fleet procurement committees weight ground clearance and cargo capacity heavily in their acquisition criteria, driving disproportionate engineering investment toward specific body styles.
- SUV:Higher ride height and expanded cargo volume accommodate urban delivery routes and executive transport contracts. Demand concentrates in Maharashtra and Tamil Nadu, where fleet operators serving e-commerce and corporate clients specify all-wheel-drive variants for monsoon-season reliability.
- Sedan:Lower center of gravity and aerodynamic profiles optimize fuel efficiency for highway-dominant usage patterns. Personal buyers in Gujarat and Delhi favor mid-size sedans for daily commuting, attracted by strong-hybrid eligibility for state road-tax exemptions.
- Hatchback:Compact dimensions suit congested urban centers with limited parking infrastructure.
- Coupe:Premium positioning targets enthusiast segments with performance-oriented hybrid powertrains.
Volume sits with SUV configurations; growth tilts toward Sedan variants as state tax policies sharpen price competitiveness.
Powertrain Technology:
Retrofit complexity and localization feasibility determine which architectures dominate production planning at OEM assembly plants.
- Parallel Hybrid:Internal combustion engine and electric motor connect mechanically to the drivetrain, enabling independent or combined propulsion. Maruti Suzuki and Toyota Kirloskar leverage this configuration for mild-hybrid variants, sourcing belt-driven starter-generators from supplier parks near Pune and Bangalore.
- Plug-in Hybrid:Larger battery packs enable 40-60 kilometers of electric-only range, appealing to premium buyers with residential charging access. Fleet operators in Delhi and Mumbai specify plug-in architectures to qualify for congestion-zone exemptions while retaining range security for inter-city routes.
- Series Hybrid:Electric motor exclusively drives wheels while engine functions as generator, simplifying transmission design.
- Mild Hybrid:48V systems provide torque assist and regenerative braking without electric-only propulsion capability.
Production volume concentrates on Parallel Hybrid architectures; steepest expansion trajectory belongs to Plug-in Hybrid as charging infrastructure spreads through Gujarat and Maharashtra.
Fuel Type:
Refining infrastructure distribution and import dependency shape fuel availability across India's state-level markets.
- Petrol:Widest retail network coverage supports hybrid deployment in semi-urban and rural markets lacking CNG or ethanol blending facilities. OEMs in Tamil Nadu optimize engine calibration for 20% ethanol blends, aligning with national biofuel policy directives.
- Electric:Grid-interactive charging under CEA guidelines enables vehicle-to-building power flow for commercial fleets. Logistics operators in Karnataka negotiate time-of-use tariffs with state discoms to minimize charging costs for depot-based plug-in hybrid fleets.
- Diesel:Facing urban entry restrictions that accelerate displacement by hybrid alternatives.
- Ethanol:Flex-fuel hybrid development targets sugar-belt states with established molasses-to-ethanol supply chains.
Petrol dominates current registrations; electric-capable architectures gain share fastest as grid reliability improves in Tier-2 cities.
Customer Segment:
Utilization intensity and financing structures create distinct service and warranty requirements across buyer categories.
- Fleet Operators:Standardized 100,000-kilometer annual utilization drives demand for unbundled service contracts and battery health monitoring. E-commerce delivery fleets in Tamil Nadu and Maharashtra negotiate separate agreements for powertrain refurbishment, transferring residual value risk to third-party asset managers.
- Personal Use:Lower mileage profiles and longer ownership horizons prioritize upfront purchase incentives and manufacturer warranty coverage. Buyers in Delhi and Gujarat respond to state-level road-tax waivers that reduce effective pricing for strong-hybrid variants versus conventional ICE equivalents.
- Government:Central and state procurement policies mandate domestic value addition thresholds under PLI scheme eligibility.
- Ride-sharing:High daily utilization and driver ownership models create demand for financing packages with embedded maintenance provisions.
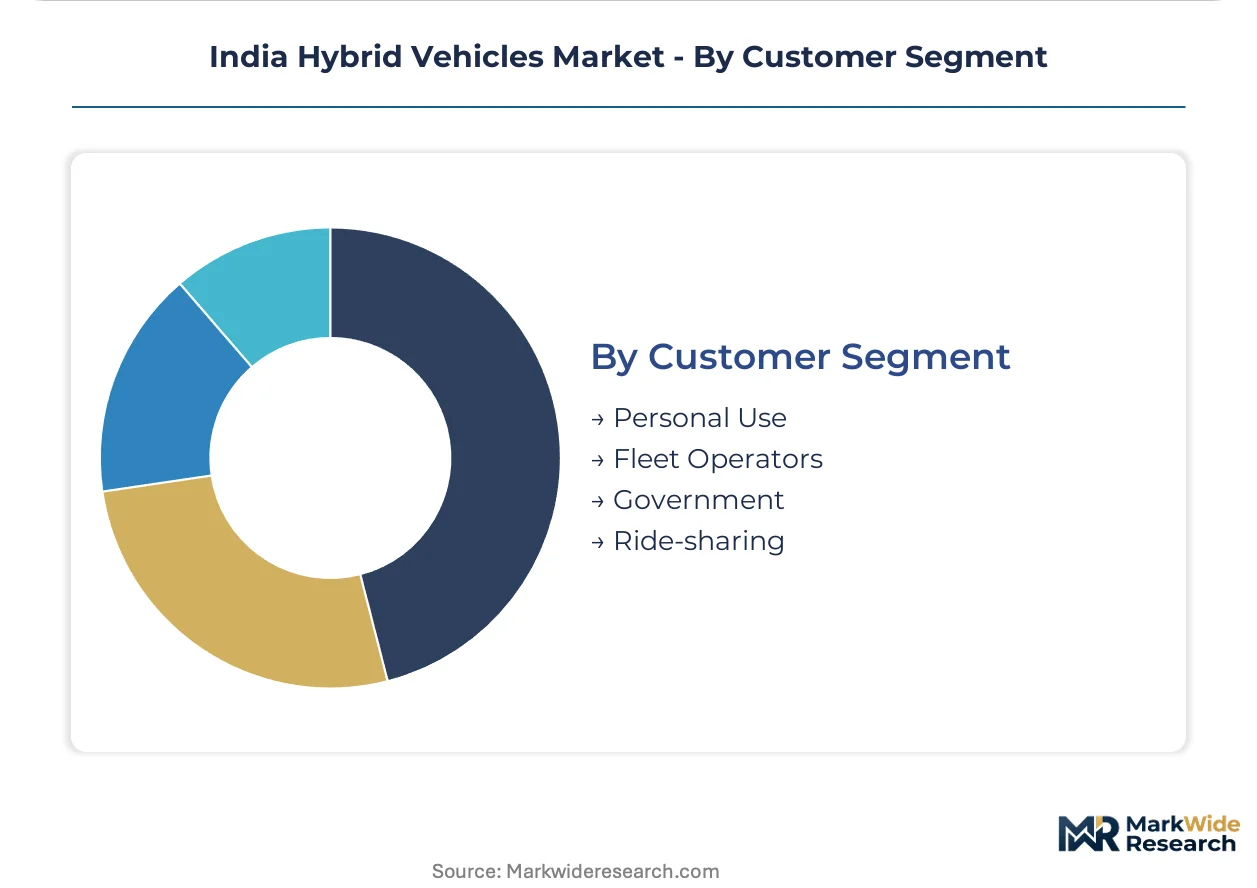
Registration volume clusters with Personal Use buyers; fleet procurement is climbing the fastest as diesel curbs tighten in Delhi and Mumbai.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium reserves in Karnataka's Mandya district and Tamil Nadu's coastal belt anchor India's hybrid battery supply chain localization efforts. State-level policy divergence creates procurement arbitrage opportunities for fleet operators navigating road-tax waivers and diesel curbs.
Maharashtra
Fleet operators in Mumbai and Pune drive demand for SUV-based mild-hybrid systems serving e-commerce last-mile logistics. The state extends road-tax waivers to strong-hybrid variants under its EV policy, reducing effective ownership costs versus conventional ICE vehicles. Supplier parks around Chakan and Talegaon concentrate belt-driven starter-generator manufacturing for Maruti Suzuki and Tata Motors assembly lines.
Tamil Nadu
Automotive export corridors through Chennai Port accelerate hybrid platform launches targeting Southeast Asian markets. CEA grid-interactive guidelines enable commercial fleets to negotiate vehicle-to-building power tariffs with state discoms. The Sriperumbudur-Oragadam belt hosts inverter and motor assembly operations supplying Toyota Kirloskar's localized powertrain programs.
Gujarat
Premium buyers in Ahmedabad and Surat respond to strong-hybrid eligibility for registration-tax exemptions that narrow pricing gaps with full-electric alternatives. The state's petroleum refining infrastructure supports ethanol-blended fuel distribution for flex-fuel hybrid development. GIFT City and Sanand industrial zones attract power electronics suppliers seeking PLI scheme benefits.
Karnataka
Bengaluru's embedded software talent pool concentrates battery management system firmware development for functional safety certification. The state EV policy treats plug-in hybrids equivalently to full-electric vehicles for congestion-zone exemptions in the capital region. Hosur and Bidadi supplier clusters manufacture silicon carbide inverters under revised domestic value addition thresholds.
Delhi-NCR
Diesel vehicle curbs in the National Capital Territory push logistics operators toward 48V mild-hybrid systems requiring no charging infrastructure. Delhi's EV policy excludes mild-hybrids from purchase incentives but grants road-tax waivers to strong-hybrid variants. Gurugram and Manesar assembly plants serve as export hubs for right-hand-drive hybrid platforms bound for South Asian markets.
India Hybrid Vehicles Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs retool assembly lines for hybrid platform localization under tightening PLI criteria. The vendor base stratifies across three tiers: multinational joint ventures with deep supplier integration, domestic conglomerates with captive component manufacturing, and emerging specialists in power electronics firmware. Strategic archetypes include full-line manufacturers balancing ICE and electrified portfolios, and technology licensors importing hybrid system architectures. Competitive intensity centers on backward integration into motor and inverter production, and geographic expansion of service networks into Tier-3 cities.
Within the multinational joint venture tier, Toyota Kirloskar Motor Private Limited and Maruti Suzuki India Limited exemplify divergent localization strategies. Toyota Kirloskar anchors its position through Karnataka-based supplier relationships and technology transfer programs. Maruti Suzuki leverages nationwide service density to sustain aftermarket loyalty. Among domestic conglomerates, Tata Motors Limited occupies a position integrating indigenous power electronics with multi-fuel hybrid architectures. Mahindra & Mahindra Limited sits within the utility-vehicle specialist archetype, targeting fleet procurement committees with ground clearance and cargo capacity specifications.
| Leading Market Players |
|---|
| Honda Motor Company Limited |
| Kia Motors India Private Limited |
| Maruti Suzuki India Limited |
| Nissan Motor India Private Limited |
| Renault India Private Limited |
| Toyota Kirloskar Motor Private Limited |
| Hyundai Motor India Limited |
| Tata Motors Limited |
| Mahindra & Mahindra Limited |
| Others |
Supply & Pricing Matrix
Silicon carbide inverter adoption simultaneously compresses power electronics costs and concentrates procurement leverage among Karnataka-based suppliers qualifying under PLI localization thresholds. Fleet operators unbundling after-sales contracts from vehicle acquisition are transferring residual value risk to third-party asset managers, reshaping how OEMs structure upfront pricing versus lifecycle revenue.
Pricing Analysis
Warranty and service bundling now separates premium from standard tiers, with fleet procurement committees negotiating standalone powertrain refurbishment agreements that strip traditional manufacturer coverage from sticker prices. Price differentiation hinges on PLI qualification status and after-sales contract inclusion, with unbundled architectures commanding lower upfront outlays. Cost compression in mild-hybrid segments is intensifying as Maruti Suzuki and Tata Motors localize belt-driven starter-generator production around Pune and Chennai. Fleet operators exhibit highest price sensitivity due to standardized 100,000-kilometer annual utilization targets, while personal buyers in Gujarat and Maharashtra respond to state road-tax waivers that reduce effective ownership costs.
Supply Chain Analysis
Lithium-ion cell supply rests on contract manufacturers concentrated in China, South Korea, and Japan, exposing OEMs to shipping rate volatility and customs processing delays at Nhava Sheva and Chennai ports. Magnet wire, laminated steel cores, and silicon carbide wafers constitute critical input dependencies for motor and inverter assemblies. Single-source vulnerability in battery management system firmware development concentrates in Bengaluru and Pune, constraining supplier scaling. Distribution runs through OEM assembly plants in Maharashtra, Tamil Nadu, and Gujarat, with supplier parks clustering around Chakan, Sriperumbudur, and Sanand industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's hybrid vehicle market operates as a supply-constrained environment where lithium-ion cell import bottlenecks prop pricing power for localized powertrain assemblers qualifying under tightening PLI criteria.
For Market Incumbents: Anticipate full-electric substitution pressure in premium SUV segments as fast-charging corridors expand through Gujarat and Maharashtra. Defensive consolidation should prioritize backward integration into silicon carbide inverter production at Hosur and Bidadi supplier clusters. Certification investment in BIS automotive electrical standards ahead of annual PLI threshold tightening will secure incentive eligibility windows.
For New Entrants and Emerging Players: Begin with Tier-3 and Tier-4 city penetration across Uttar Pradesh and Madhya Pradesh, where grid infrastructure gaps favor self-charging hybrid architectures requiring no external power source. The most penetrable segment sits with fleet operators facing diesel curbs in Delhi and Mumbai. A direct fleet sales model with unbundled battery health monitoring contracts bypasses established dealership networks.
For Investors and Strategic Acquirers: Re-rating potential sits with power electronics specialists possessing silicon carbide inverter capabilities given CEA grid-interactive guideline expansion enabling vehicle-to-building monetization. Long-term viability over the next decade hinges on domestic value addition depth rather than assembly-scale metrics. The signal to monitor is state-level EV policy reclassification of hybrid eligibility for road-tax waivers relative to full-electric alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering validation cycles for parallel hybrid architectures across Maruti Suzuki and Toyota Kirloskar lineups. |
| Battery Supply Agreement | Secures lithium-ion cell offtake from East Asian contract manufacturers amid shipping rate volatility at Indian ports. |
| Software-Defined Vehicle Investment | Addresses embedded firmware talent scarcity concentrated in Bengaluru for battery management system development. |
| Geographic Manufacturing Footprint | Expands motor and inverter assembly to Tamil Nadu supplier parks serving Toyota Kirloskar's localized programs. |
| Charging Infrastructure Partnership | Enables plug-in hybrid fleet monetization under CEA vehicle-to-building guidelines in Karnataka and Maharashtra. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator acquisition committees, and dealership operations heads. BIS certification databases, CEA grid-interactive guidelines, DPIIT PLI scheme disclosures, and state EV policy documents provided secondary validation. Bottom-up vehicle registration analysis and top-down automotive production estimates were triangulated to establish market sizing.
Data-stream reconciliation across the projection horizon employed vehicle class, propulsion architecture, and regional production cluster segmentation. CAGRs were derived from installed base growth modeling and replacement cycle analysis. Silicon carbide inverter adoption curves and PLI localization threshold compliance timelines served as industry-specific forecast inputs throughout the modeling period.
Underlying measurement precision varies by segment; fleet operator procurement data carries tighter precision than personal buyer sentiment indicators. Forecasts reflect assumptions regarding PLI scheme continuity, lithium-ion cell import availability, and state-level tax policy stability. Regulatory reclassification of hybrid eligibility, battery cost trajectories, and charging infrastructure buildout pace constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Hydrogen Fuel Automotive Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market